
 Cartoning Machines for Pharmaceutical Industry Market | 2026-2036
Cartoning Machines for Pharmaceutical Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Cartoning Machines for Pharmaceutical Industry Market Insights
Integration of servo motor systems with vision inspection technology is reshaping pharmaceutical cartoning from mechanical indexing to continuous-motion, zero-reject processing. IMA Group leverages its vertical integration into blister-cartoning combination systems to capture high-value biologics contracts. Marchesini Group anchors its competitive position through deep specialization in vial and syringe cartoning for injectable therapies. Syntegon Technology GmbH differentiates via modular platform architectures that allow pharmaceutical manufacturers to reconfigure lines for multiple package formats without full replacement.
Cartoning machines for pharmaceutical applications are automated packaging systems designed to erect, load, and seal paperboard cartons at speeds typically ranging from 50 to 600 units per minute, with primary functions including product insertion, leaflet insertion, and tamper-evident closure for regulated drug delivery. These systems serve the essential commercial purpose of ensuring dose integrity, child resistance, and full traceability compliance across solid oral, parenteral, and topical dosage forms. Horizontal cartoners dominate current installed capacity due to their compatibility with standard blister card dimensions and established changeover protocols, though rotary cartoners are gaining share in high-throughput vaccine operations where gentle handling of temperature-sensitive vials is paramount. Servo motor systems are displacing legacy pneumatic architectures as the preferred technology layer because they reduce changeover downtime by enabling electronic recipe management and real-time torque feedback.
FDA's Drug Supply Chain Security Act and the EU Falsified Medicines Directive mandate unit-level serialization, driving pharmaceutical manufacturers to replace standalone cartoning equipment with integrated lines featuring electronic control systems and vision inspection modules. Germany's KBA and France's ANSM enforce packaging integrity standards that effectively block non-compliant machinery from their national markets, creating regulatory moats for established European suppliers. Stakeholders must monitor whether emerging cell and gene therapy packaging formats will outpace the adaptability of current cartoning platform designs.
Market Dynamics
Pharmaceutical cartoning equipment is migrating from mechanical indexing to continuous-motion servo architectures as serialization mandates force line-wide electronic integration rather than standalone machine upgrades.
Growth Catalysts
- EU Falsified Medicines Directive:Unit-level track-and-trace requirements are compelling pharmaceutical manufacturers to retrofit cartoning lines with vision inspection and aggregation software, creating mandatory replacement cycles across European production facilities.
- Biologics packaging formats:Rising output of temperature-sensitive injectable therapies is accelerating demand for gentle-handling rotary cartoners with integrated cold-chain monitoring capabilities.
- German supplier cluster density:Concentrated engineering expertise around Stuttgart and Karlsruhe enables rapid prototyping of modular cartoning platforms, shortening delivery timelines for contract packaging organizations scaling automated capacity.
Market Restraints
- Stainless steel and electronic component costs:Input price volatility for pharmaceutical-grade construction materials and servo drive systems compresses margin structures for mid-tier equipment suppliers.
- Validation timeline compression:FDA 21 CFR Part 11 and EU GMP Annex 15 documentation requirements extend factory acceptance testing periods, delaying revenue recognition for capital equipment vendors.
- Pre-owned equipment channel:Secondary market availability of refurbished Bosch and Uhlmann lines creates price anchoring that constrains pricing power for new machine sales in cost-sensitive emerging markets.
Strategic Opportunities
- Cell and gene therapy packaging:Autologous therapy manufacturing requires small-batch, high-changeover cartoning solutions that existing high-speed platforms cannot address, opening white space for flexible modular systems.
- India's PLI scheme for pharmaceuticals:Production-linked incentives for domestic drug manufacturing are driving greenfield facility construction, creating first-mover advantage for cartoning suppliers establishing local service networks.
- Servo-vision convergence:Integration of torque-feedback motors with deep-learning inspection algorithms enables zero-reject processing that mechanical systems cannot replicate, commanding premium positioning.
Industry Challenges
- Mechatronics engineering scarcity:Cross-disciplinary expertise combining pharmaceutical validation protocols with servo control programming is concentrated among aging workforces in Southern Germany and Northern Italy.
- Legacy line integration:Brownfield pharmaceutical facilities require cartoning equipment to communicate with 1990s-era SCADA architectures through protocol translation gateways, complicating commissioning.
- Serialization data integrity:Ensuring seamless handshakes between cartoning-level aggregation and warehouse management systems demands specialized integration expertise that general automation contractors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cartoning Machines for Pharmaceutical Industry Market |
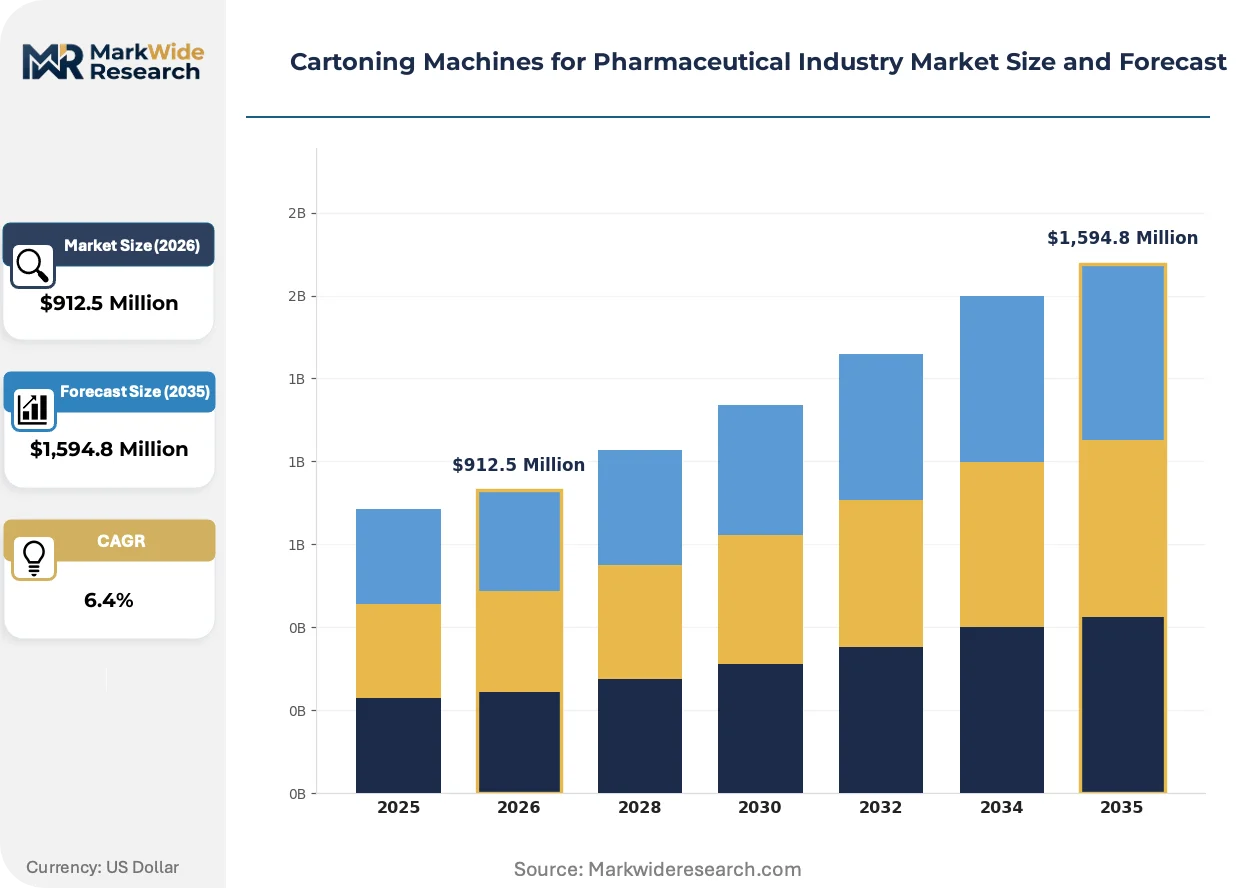
| Market Size in 2026 | $912.5 Million |
| Market Size in 2035 | $1,594.8 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Cartoners, Vertical Cartoners, Rotary Cartoners, Automatic Cartoners, Semi-Automatic Cartoners Technology: Servo Motor Systems, Pneumatic Systems, Electronic Control Systems, Vision Inspection Systems, Touch Screen Interface Application: Blister Packaging, Bottles Packaging, Sachet Packaging, Tube Packaging, Vial Packaging End User: Pharmaceutical Manufacturers, Biotech Companies, Nutraceutical Firms, Contract Packaging Organizations, Research Laboratories |
| Companies Covered | IMA Group, Marchesini Group, Uhlmann Pac-Systeme GmbH & Co. KG, Syntegon Technology GmbH, Bosch Packaging Technology, Romaco GmbH, Coesia S.p.A., Harro Höfliger, Körber Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cartoning Machines for Pharmaceutical Industry Market Trends and Innovations
Cartoning technology is converging with adjacent inspection and serialization systems, collapsing what were discrete capital purchases into unified line architectures with embedded compliance functionality.
Servo motor systems are migrating from niche high-speed applications to standard pharmaceutical configurations. These architectures eliminate mechanical cams and enable electronic recipe management that cuts changeover downtime. Contract packaging organizations are adopting these platforms to serve multiple biologics clients from shared lines, compressing the payback period for automation investments through higher utilization rates.
EU MDR and FDA DSCSA aggregation requirements are forcing cartoning equipment to incorporate camera-based verification and serial number printing as standard rather than optional modules. Pharmaceutical manufacturers must now validate entire line sequences rather than individual machines, shifting supplier relationships toward turnkey integration partners. Vaccine producers face the tightest compliance windows, driving earliest adoption of fully integrated cartoning-inspection-serialization sequences.
After-sales service contracts are unbundling from equipment sales as pharmaceutical manufacturers seek operational expenditure treatment for compliance-related upgrades. Third-party service providers are capturing maintenance and validation work that OEMs previously controlled, particularly in North American markets where multi-site operators prefer standardized service agreements across vendor portfolios. This disintermediation is most advanced among large contract packaging organizations managing heterogeneous equipment fleets.
Cartoning Machines for Pharmaceutical Industry Market Segmentation
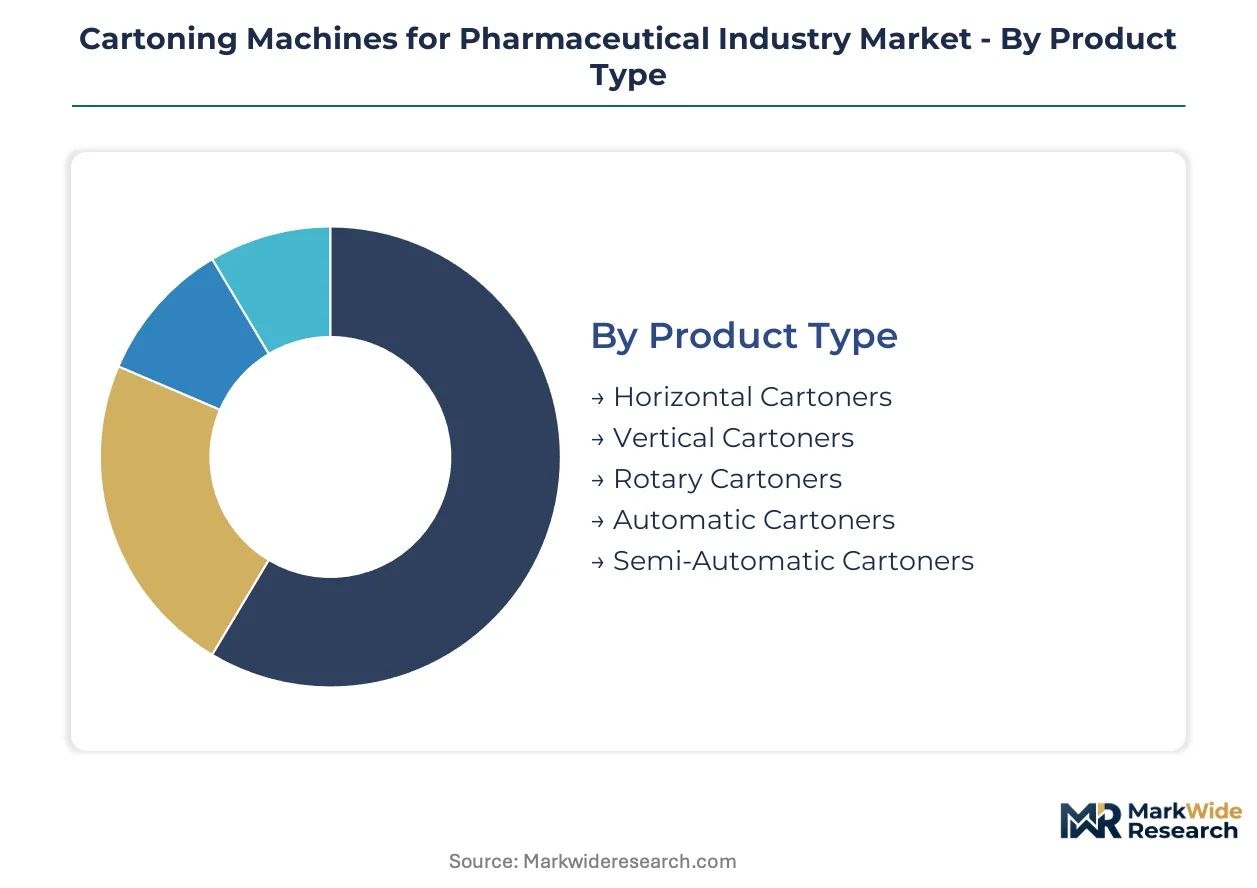
Cartoning machine segmentation reveals how after-sales service intensity varies sharply across configuration types and automation levels. Pharmaceutical manufacturers prioritize segments where validation support and spare parts availability determine total cost of ownership more than initial capital expenditure.
Product Type:
After-sales service contracts concentrate most heavily on high-speed continuous-motion platforms where downtime costs escalate exponentially.
- Horizontal Cartoners:These side-loading configurations dominate installed capacity through compatibility with standard blister card dimensions and established changeover protocols. Demand clusters among large solid-dosage manufacturers in Germany and Switzerland, where FDA and EMA serialization mandates drive retrofit programs for legacy mechanical indexing lines.
- Rotary Cartoners:Gentle-handling rotary architectures with star-wheel infeed systems protect temperature-sensitive vials during high-speed processing. Vaccine producers in Belgium and the Netherlands specify these systems for COVID-19 and influenza fill-finish operations, prioritizing integrated cold-chain monitoring over maximum throughput.
- Vertical Cartoners:Top-loading formats suit bottle and jar applications where gravity-assisted product flow reduces handling complexity.
- Automatic Cartoners:Fully integrated lines with electronic recipe management compress changeover downtime for contract packaging organizations serving multiple biologics clients.
- Semi-Automatic Cartoners:Operator-assisted systems persist in research laboratories and clinical trial packaging where batch sizes resist full automation economics.
Horizontal cartoners hold the largest share; momentum sits with rotary cartoners as biologics output expands.
Technology:
Technology choices increasingly determine margin structures through embedded software licensing and predictive maintenance subscriptions.
- Servo Motor Systems:Torque-feedback motors with electronic cam replacement enable real-time parameter adjustment without mechanical changeover. Pharmaceutical manufacturers in Italy and Spain adopt these architectures to validate multiple products on shared lines, amortizing compliance costs across higher utilization rates.
- Vision Inspection Systems:Camera-based verification modules with deep-learning algorithms perform carton integrity, leaflet presence, and serialization code grading in a single pass. EU FMD and FDA DSCSA aggregation requirements make these standard rather than optional, particularly for export-oriented facilities in Ireland and Denmark.
- Pneumatic Systems:Legacy compressed-air architectures persist in cost-sensitive emerging markets where electricity reliability concerns favor mechanical simplicity.
- Electronic Control Systems:PLC-based architectures with Ethernet/IP connectivity enable line-wide data handshakes for serialization aggregation.
- Touch Screen Interface:HMI panels with recipe-driven operation reduce operator training burden and error rates in high-changeover environments.
Servo motor systems command the dominant installed base; vision inspection systems are climbing the fastest as regulatory deadlines harden.
Application:
Application segmentation tracks directly to dosage form growth trajectories and packaging material innovation cycles.
- Blister Packaging:Solid oral dosage forms in push-through foil-and-film configurations represent the highest-volume application, with demand concentrated among generic manufacturers scaling output for regulated export markets.
- Vial Packaging:Injectable therapies require gentle-handling cartoners with integrated nest-and-tray loading for glass and polymer vials. Biotech companies in Massachusetts and California drive specification of rotary architectures with minimal G-force exposure during high-speed transfer.
- Bottles Packaging:Tablet and capsule containers in HDPE and PET formats utilize vertical cartoners with desiccant insertion capabilities.
- Sachet Packaging:Unit-dose powder and liquid formats for pediatric and geriatric compliance employ specialized collating and stacking modules.
- Tube Packaging:Semi-solid topical formulations require cartoners with leaflet folding and glue-seal verification for compliance with child-resistance standards.
Blister packaging maintains volume leadership; vial packaging shows the steepest expansion trajectory as biologics manufacturing scales.
End User:
End user categories diverge sharply in procurement authority, with contract packaging organizations consolidating purchasing power across multi-site networks.
- Contract Packaging Organizations:These outsourced service providers operate heterogeneous equipment fleets across dedicated and shared-resource facilities. CMOs in Germany and the Netherlands prioritize modular cartoning platforms with rapid format changeover to serve biologics manufacturers without dedicated packaging infrastructure.
- Pharmaceutical Manufacturers:Integrated drug companies with captive packaging operations specify turnkey lines with embedded compliance functionality, accepting longer validation timelines for single-source accountability.
- Biotech Companies:Emerging therapeutic developers favor flexible systems accommodating small-batch autologous therapies with high changeover frequency.
- Nutraceutical Firms:Dietary supplement producers apply pharmaceutical-grade cartoning equipment to differentiate through packaging quality signaling.
- Research Laboratories:Clinical packaging operations require GMP-compliant systems with batch record integration for investigational medicinal products.
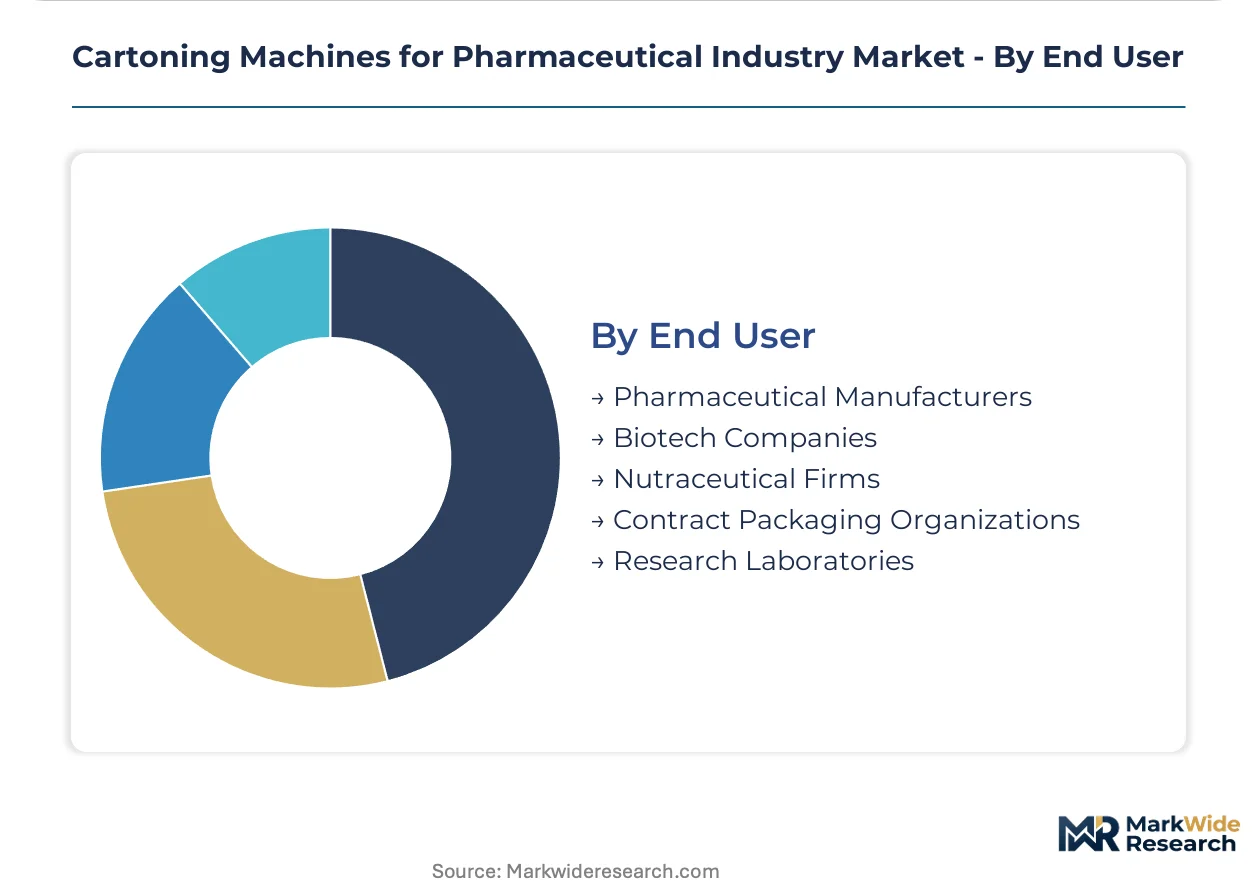
Pharmaceutical manufacturers represent the largest installed base; contract packaging organizations are gaining share fastest as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract packaging organizations in Germany and biotech manufacturers in the United States concentrate the highest procurement volumes for pharmaceutical cartoning equipment, with regulatory serialization mandates driving synchronized upgrade cycles across both markets.
Germany
Stuttgart and Karlsruhe host dense engineering clusters where Bosch Packaging Technology and Uhlmann Pac-Systeme prototype modular cartoning platforms. The KBA enforces packaging integrity standards that block non-compliant machinery from national markets. Contract packaging organizations in Baden-Württemberg scale automated capacity to serve biologics manufacturers facing EU Falsified Medicines Directive deadlines.
United States
Biotech companies in Massachusetts and California drive specification of rotary cartoners with minimal G-force exposure for temperature-sensitive vials. The FDA's Drug Supply Chain Security Act mandates unit-level serialization, compelling replacement of standalone cartoning equipment with integrated lines. Third-party service providers in the Northeast capture maintenance contracts previously controlled by OEMs.
India
Production-linked incentives for domestic drug manufacturing are accelerating greenfield facility construction across Maharashtra and Gujarat. The CDSCO aligns with international serialization standards, forcing contract manufacturers to adopt vision inspection modules. Domestic packaging specialists in Mumbai and Ahmedabad establish local service networks to capture first-mover advantage.
Switzerland
Large solid-dosage manufacturers around Basel retrofit legacy mechanical indexing lines to meet EMA serialization mandates. Swissmedic enforces documentation requirements that extend factory acceptance testing periods. Engineering expertise in the Zurich-Zug corridor concentrates on servo-vision convergence for zero-reject processing.
Netherlands
Vaccine producers in Belgium and the Netherlands specify rotary architectures with integrated cold-chain monitoring for COVID-19 and influenza operations. The ANSM and national regulators enforce aggregation requirements that demand seamless handshakes between cartoning systems and warehouse management platforms. Contract packaging organizations in Rotterdam prioritize rapid format changeover to serve multiple biologics clients.
Cartoning Machines for Pharmaceutical Industry Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Premium-tier vendors supply turnkey integration with embedded compliance functionality, while mid-tier fabricators compete on modular reconfigurability. Two strategic archetypes dominate: engineering-intensive specialists concentrated in Southern Germany and Northern Italy, and diversified packaging conglomerates leveraging cross-divisional technology transfer. Competitive moves center on backward integration into vision inspection components and geographic expansion through localized service networks.
Among Germany-based precision engineering specialists, Uhlmann Pac-Systeme GmbH & Co. KG and Syntegon Technology GmbH exemplify the servo-vision convergence archetype, while IMA Group represents diversified packaging conglomerates with vertical reach into blister-cartoning combination systems. These three anchors occupy positions where regulatory compliance depth and after-sales service intensity determine competitive viability more than initial equipment pricing.
| Leading Market Players |
|---|
| IMA Group |
| Marchesini Group |
| Uhlmann Pac-Systeme GmbH & Co. KG |
| Syntegon Technology GmbH |
| Bosch Packaging Technology |
| Romaco GmbH |
| Coesia S.p.A. |
| Harro Höfliger |
| Körber Pharma |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Southern Germany's engineering cluster is compressing quotation timelines for modular cartoning platforms while simultaneously eroding margin buffers for mid-tier fabricators competing against refurbished equipment channels. Pharmaceutical manufacturers exploit this utilization slack to negotiate extended payment terms and bundled validation support, shifting supplier risk profiles toward after-sales service intensity.
Pricing Analysis
Cost-plus contracts with stainless steel indexation dominate capital equipment procurement, though servo motor and electronic control components increasingly carry separate semiconductor-linked escalation clauses. Three-tier pricing structure across premium, standard, and economy levels separates turnkey integration providers from modular platform specialists and refurbished equipment brokers. Pricing pressure stems from secondary market availability of Bosch and Uhlmann lines in India and Southeast Asia. Contract packaging organizations exhibit highest price sensitivity due to heterogeneous fleet management economics, while integrated pharmaceutical manufacturers prioritize single-source accountability over capital expenditure minimization.
Supply Chain Analysis
Export control regimes limiting servo drive and machine vision technology flows from Germany and Japan constrain supply elasticity for pharmaceutical-grade cartoning equipment. Manufacturing concentration in Germany, Italy, and Switzerland draws from specialized stainless steel foundries in Austria and precision bearing suppliers in Denmark. Single-source vulnerability sits with torque-feedback motor controllers sourced from a narrow supplier base in Southern Germany. Distribution runs through OEM direct sales for premium-tier installations and specialized pharmaceutical equipment distributors for mid-market configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as cell and gene therapy packaging formats proliferate beyond the adaptability of incumbent high-speed platforms, creating niche entry points for flexible modular specialists. Autologous therapy manufacturing demands small-batch, high-changeover solutions that established players have not prioritized.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance subscriptions into servo-vision platforms before third-party providers capture validation and spare parts contracts. Backward integration into machine vision components reduces exposure to semiconductor supply constraints. Capacity expansion in India's Maharashtra and Gujarat production corridors captures first-mover advantage as PLI scheme incentives accelerate greenfield pharmaceutical facility construction.
For New Entrants and Emerging Players: Pursue white-space positioning in cell and gene therapy packaging where autologous batch sizes resist standard high-speed platform economics. India's contract manufacturing sector offers the most penetrable geography given serialization mandate compliance deadlines and limited local service infrastructure. Go-to-market execution should emphasize rapid format changeover capabilities and localized validation support rather than throughput maximization.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across servo-vision convergence platforms as software licensing and predictive maintenance subscriptions reshape revenue composition toward recurring streams. Long-term viability over the next decade favors acquisition targets with captive control over inspection algorithm development and established pharmaceutical validation protocols. The signal to watch is consolidation velocity among third-party service providers capturing maintenance contracts previously controlled by OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Vision Platform Convergence | Integration of torque-feedback motors with deep-learning inspection algorithms enables zero-reject processing that commands premium positioning. |
| Modular Architecture Development | Reconfigurable platforms allow pharmaceutical manufacturers to adapt lines for multiple package formats without full capital replacement. |
| Localized Service Network Expansion | Establishing validation and spare parts infrastructure in India captures first-mover advantage as PLI scheme accelerates facility construction. |
| Predictive Maintenance Subscription Unbundling | Recurring revenue streams from operational expenditure treatment of compliance-related upgrades improve margin stability versus equipment sales cycles. |
| Cell and Gene Therapy Packaging Specialization | Small-batch, high-changeover solutions address autologous therapy manufacturing requirements that incumbent high-speed platforms cannot serve. |
Research Methodology
A spread of perspectives from pharmaceutical packaging engineers, contract manufacturing executives, regulatory affairs specialists, and aftermarket service managers converged on the working assumptions governing market size and growth trajectory. Primary fieldwork combined structured interviews with equipment procurement decision-makers at integrated drug companies and CMOs across Germany, the United States, India, and Switzerland. Secondary validation drew from FDA 510(k) filings, EMA notified body documentation, CDSCO facility inspection records, and trade data tracking pharmaceutical machinery imports. Bottom-up triangulation across installed base estimates and top-down cross-checks against capital expenditure disclosures anchored volume and value outputs.
Demand-supply balance framing shaped the analytical architecture across the projection horizon, with segmentation modeling across product type, technology layer, application format, and end-user category. Dosage form growth trajectories and regional regulatory cluster stringency provided industry-specific forecast inputs. CAGRs were derived from elasticity estimates linking serialization mandate compliance deadlines to replacement cycle timing, cross-referenced against biologics manufacturing capacity expansion plans.
Sensitivities concentrate around EU MDR implementation pacing, FDA DSCSA enforcement intensity, and semiconductor supply availability for servo control systems. Forecasts reflect documented assumptions regarding contract packaging organization outsourcing acceleration and cell therapy commercialization scale. Material shifts in pharmaceutical serialization deadline extensions or export control regime tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
Nutraceutical Packaging Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Plastic Pharma Tray Market