
 Active and Intelligent Packaging in Pharmaceutical Market | 2026-2036
Active and Intelligent Packaging in Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Active and Intelligent Packaging in Pharmaceutical Market Outlook
Platform licensing revenue is narrowing as pharmaceutical manufacturers seek direct control over serialization data and patient engagement platforms. Amcor plc leverages its integrated film-to-device manufacturing footprint to sustain pricing power in RFID-enabled blister packs. Avery Dennison Corporation specializes in adhesive-integrated sensor architectures that dominate North American smart label deployments.
Active and intelligent packaging in pharmaceutical applications encompasses systems that monitor, record, or actively modify the internal environment of drug containers through embedded sensors, time-temperature indicators, or oxygen-scavenging films, typically operating within calibrated ranges of 2°C to 8°C for biologics and incorporating printed electronics with conductivity thresholds below 0.1 ohm/square. These systems primarily assure product integrity, authenticate supply chain provenance, and drive patient adherence through visual or digital feedback mechanisms. Temperature Monitoring solutions lead product-type revenue as mRNA and cell-therapy pipelines expand cold-chain requirements, while Sensor Technology anchors the fastest technology trajectory due to miniaturization of printed electrochemical detectors. Smart Labels capture concentrated margin pools where pharmaceutical manufacturers bundle compliance and marketing functions into a single substrate.
The FDA's Drug Supply Chain Security Act mandates unit-level traceability, while the EU Falsified Medicines Directive enforces anti-tamper verification across European distribution channels, and ISO 15378 governs primary packaging materials for medicinal products to ensure cGMP alignment. These frameworks compel pharmaceutical manufacturers to embed authentication features at the primary package level rather than relying solely on secondary cartons. Stakeholders must monitor convergence between sustainability mandates and electronic component miniaturization to anticipate which packaging formats will absorb next-generation compliance costs without compromising recyclability targets.
Market Dynamics
Serialization mandates from the FDA and EMA are compressing adoption timelines for track-and-trace infrastructure, forcing pharmaceutical manufacturers to integrate authentication layers at the primary package level rather than secondary cartons. This regulatory compression is hybridizing traditional packaging economics with electronics manufacturing cost curves.
Growth Catalysts
- FDA DSCSA unit-level traceability:The Drug Supply Chain Security Act mandates pharmaceutical manufacturers to deploy serializable packaging by 2024, accelerating smart label procurement across the United States.
- mRNA cold-chain expansion:Cell therapy and gene therapy pipelines require calibrated 2°C to 8°C monitoring, pulling temperature-indicating films into standard packaging specifications.
- Printed electrochemical miniaturization:Conductivity thresholds below 0.1 ohm/square now enable oxygen-scavenging sensors to embed directly into blister lidding without secondary attachment.
Market Restraints
- Silver and copper conductor volatility:Printed electronics rely on precious metal inks subject to commodity price swings, compressing margin stability for sensor-integrated substrates.
- German equipment supplier concentration:Precision coating and laser-etching systems for RFID antenna production cluster with Bavarian and Baden-Württemberg machinery vendors, creating single-source vulnerability.
- Recyclability incompatibility:Multi-layer films combining polyethylene with aluminum oxide barrier layers face sorting rejection at European material recovery facilities under EU Packaging and Packaging Waste Regulation targets.
Strategic Opportunities
- Indian cold-chain underpenetration:CDSCO's expanding biologics approval pipeline outpaces temperature-controlled distribution infrastructure, creating first-mover advantage for low-cost indicator technologies.
- Japan METI carbon-neutral packaging roadmap:The 2030 sustainable packaging targets incentivize bio-based substrate development for intelligent labels, opening subsidy-aligned procurement channels.
- Blockchain-IoT convergence:Distributed ledger verification of sensor data streams enables patient-facing adherence apps to authenticate medication provenance without proprietary platform licensing.
Industry Challenges
- Printed electronics integration timelines:Pharmaceutical packaging lines engineered for 600 units per minute require retooling for pick-and-place sensor embedding, extending validation cycles by 12-18 months.
- Cross-functional talent scarcity:Packaging engineers with cGMP fluency and RF engineering capability command premium compensation, constraining mid-tier manufacturer hiring pipelines.
- ISO 15378 alignment complexity:Primary packaging materials for medicinal products must demonstrate contamination control across electrochemical sensor migration testing, adding certification burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active and Intelligent Packaging in Pharmaceutical Market |
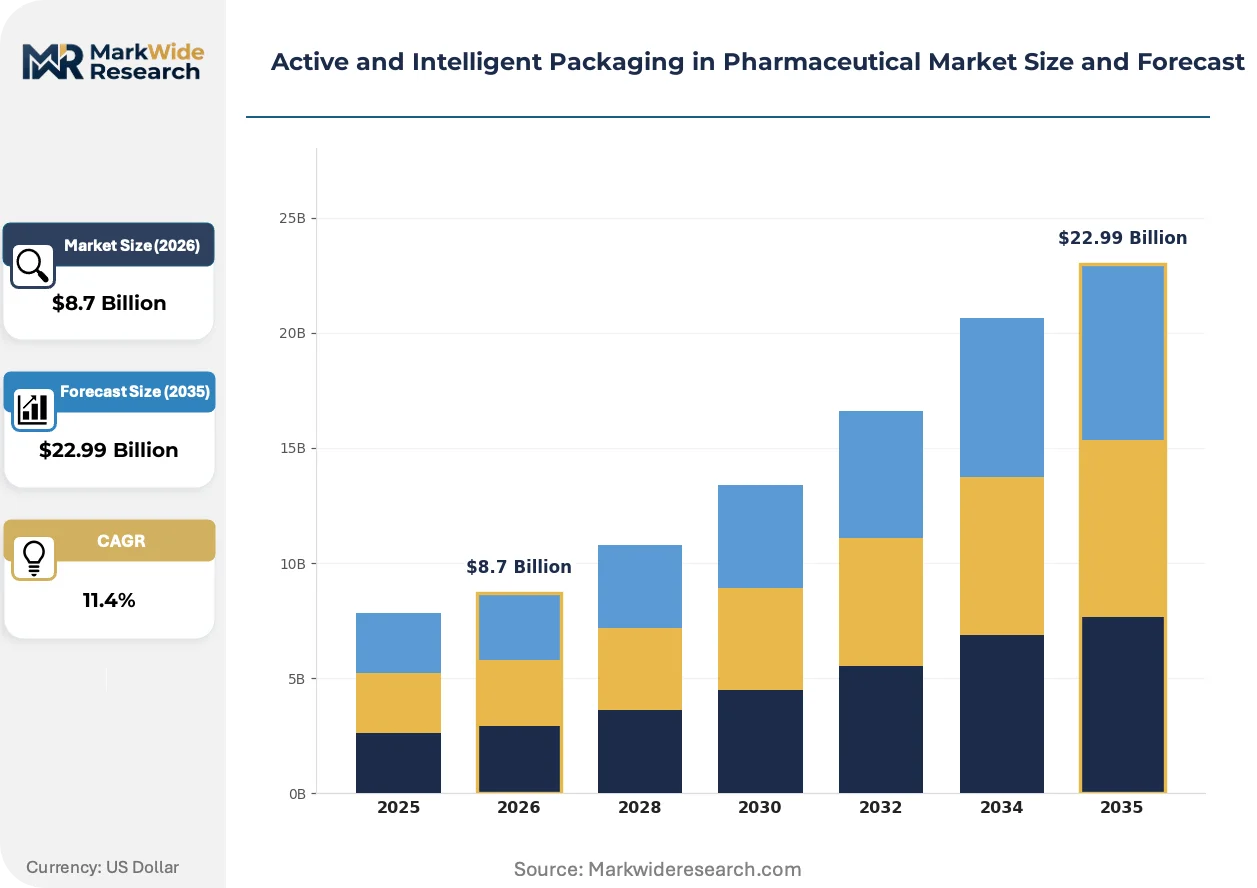
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Packaging, Smart Labels, Temperature Monitoring, RFID Tags Application: Drug Delivery, Inventory Management, Patient Compliance, Safety Monitoring Technology: Nanotechnology, Microencapsulation, Sensor Technology, Biodegradable Materials End User: Pharmaceutical Manufacturers, Distributors, Hospitals, Retail Pharmacies |
| Companies Covered | Avery Dennison Corporation, Sealed Air Corporation, Amcor plc, DS Smith, Berry Global Inc., Mondi Group, Gerresheimer AG, Huhtamäki Oyj, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active and Intelligent Packaging in Pharmaceutical Market Strategic Shifts
Active and intelligent packaging is hybridizing physical containment with digital identity layers, compressing the traditional separation between manufacturing execution systems and patient-facing interfaces. Three developments are restructuring competitive positioning and procurement criteria.
Printed electrochemical sensors is hybridizing oxygen detection with humidity monitoring through single-substrate multi-analyte architectures. Biologics manufacturers in Germany and Switzerland are specifying these for high-value injectables, eliminating separate desiccant canisters. The technology is hybridizing secondary packaging functions into primary containers, reducing bill-of-materials complexity and dimensional cube for cold-chain shipment.
EU Falsified Medicines Directive enforcement through 2025 requires anti-tamper verification across all European distribution channels. Pharmaceutical manufacturers must redesign folding cartons with overt and covert authentication features, redirecting packaging development resources from sustainability initiatives toward security compliance. Small-molecule generics in Southern Europe face disproportionate cost impact as lower-margin products absorb serialized label premiums without corresponding price recovery.
Hospital and pharmacy buying groups are consolidating procurement of compliance-enabled packaging under single-source agreements with integrated film-to-device manufacturers. Direct contracting for serialization data ownership is displacing third-party platform licensing, particularly among top-20 pharmaceutical manufacturers seeking patient engagement analytics control. This concentration is most visible in United States group purchasing organization negotiations, where multi-year contracts now bundle smart label volumes with traditional blister and bottle formats.
Active and Intelligent Packaging in Pharmaceutical Market Segmentation
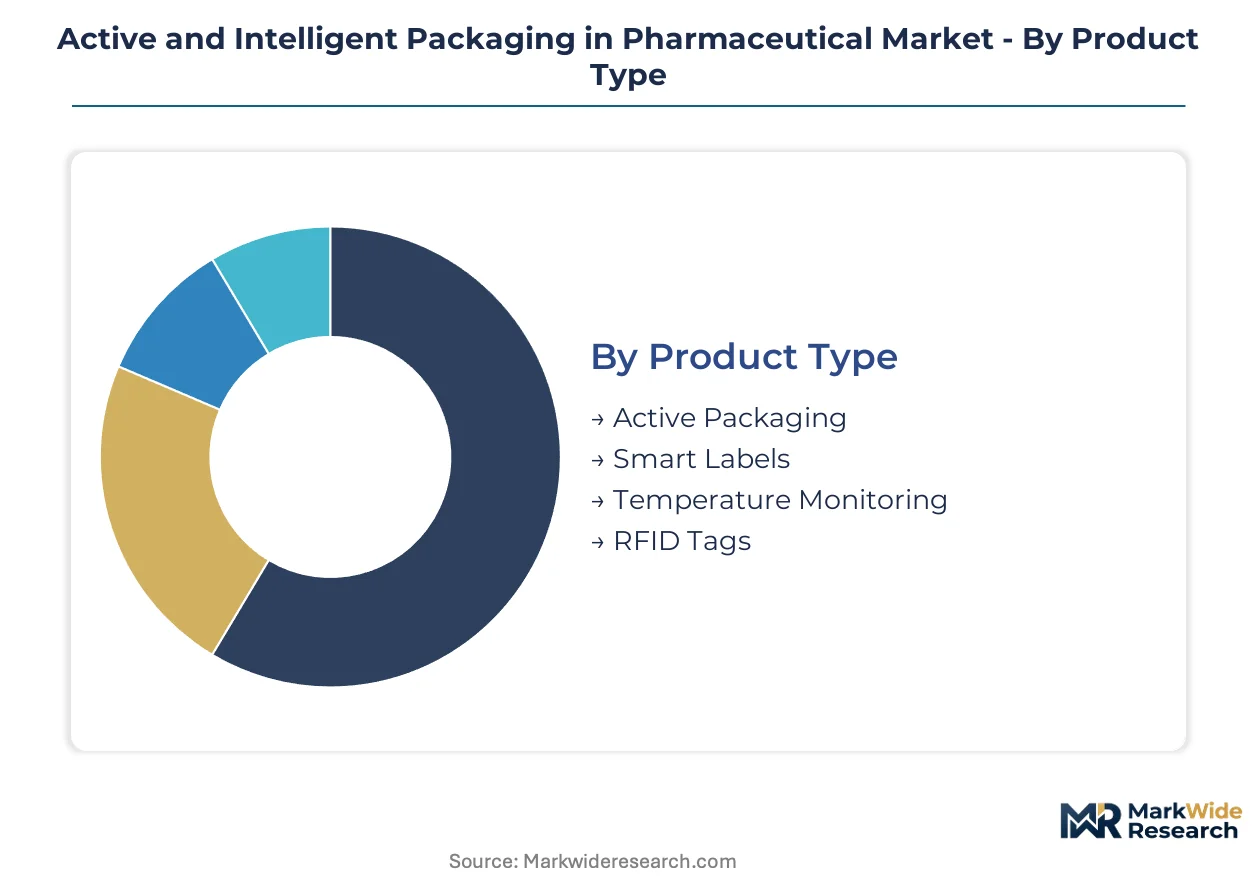
Active and intelligent packaging in pharmaceuticals spans functional systems with divergent replacement cycles, from disposable temperature indicators to multi-year RFID infrastructure. Segmentation reveals where procurement budgets concentrate versus where technology roadmaps are disrupting incumbent specifications.
Product Type:
Temperature Monitoring solutions turn over fastest as single-use indicators accompany every cold-chain shipment, while RFID Tags persist for years within reusable logistics containers.
- Temperature Monitoring:Single-use time-temperature indicators and electronic data loggers record cumulative thermal exposure through calibrated 2°C to 8°C ranges. Demand concentrates with mRNA and cell-therapy manufacturers in the United States and Germany where cold-chain validation is mandatory for biologics licensing.
- Smart Labels:Adhesive-integrated substrates combine printed electronics with serialization codes for unit-level traceability. Pharmaceutical manufacturers in the United States bundle these with patient engagement features to satisfy FDA DSCSA mandates while capturing adherence analytics.
- Active Packaging:Oxygen-scavenging films and desiccant-embedded blisters modify internal container atmospheres to extend shelf life.
- RFID Tags:UHF and NFC-enabled tags enable automated inventory tracking across distribution networks.
Temperature Monitoring dominates installed base. Smart Labels is where expansion concentrates.
Application:
Patient Compliance applications command premium pricing per unit through direct-to-consumer digital interfaces, while Inventory Management scales through high-volume logistics contracts.
- Patient Compliance:Packaging with visual or connected reminders for dosing schedules, opening detection, and refill prompts. Hospital systems in Japan specify these for chronic disease management programs where medication adherence directly impacts reimbursement metrics.
- Safety Monitoring:Anti-tamper features and authentication layers verify product integrity through distribution. European pharmaceutical manufacturers redesign folding cartons for EU Falsified Medicines Directive enforcement, embedding overt and covert verification elements.
- Drug Delivery:Active modification of local environments within inhalers, injectors, or transdermal patches.
- Inventory Management:Automated tracking and expiry monitoring across warehouse and pharmacy systems.
Inventory Management dominates installed base. Patient Compliance is climbing the fastest.
Technology:
Sensor Technology carries the steepest miniaturization cost curve as printed electrochemical detectors shrink, while Biodegradable Materials face extended validation timelines for pharmaceutical acceptance.
- Sensor Technology:Printed electrochemical and semiconductor detectors measuring oxygen, humidity, or temperature through conductivity thresholds below 0.1 ohm/square. Biologics manufacturers in Switzerland specify multi-analyte architectures for high-value injectables, eliminating separate desiccant canisters.
- Microencapsulation:Encapsulated active agents release scavenging compounds or antimicrobial agents in response to environmental triggers. Generic drug manufacturers in India adopt these for cost-sensitive stability extension without cold-chain infrastructure.
- Nanotechnology:Nanoscale barrier coatings and antimicrobial surfaces integrated into primary packaging films.
- Biodegradable Materials:Bio-based substrates for intelligent labels aligned with sustainability mandates.
Sensor Technology dominates installed base. Microencapsulation is gaining share fastest.
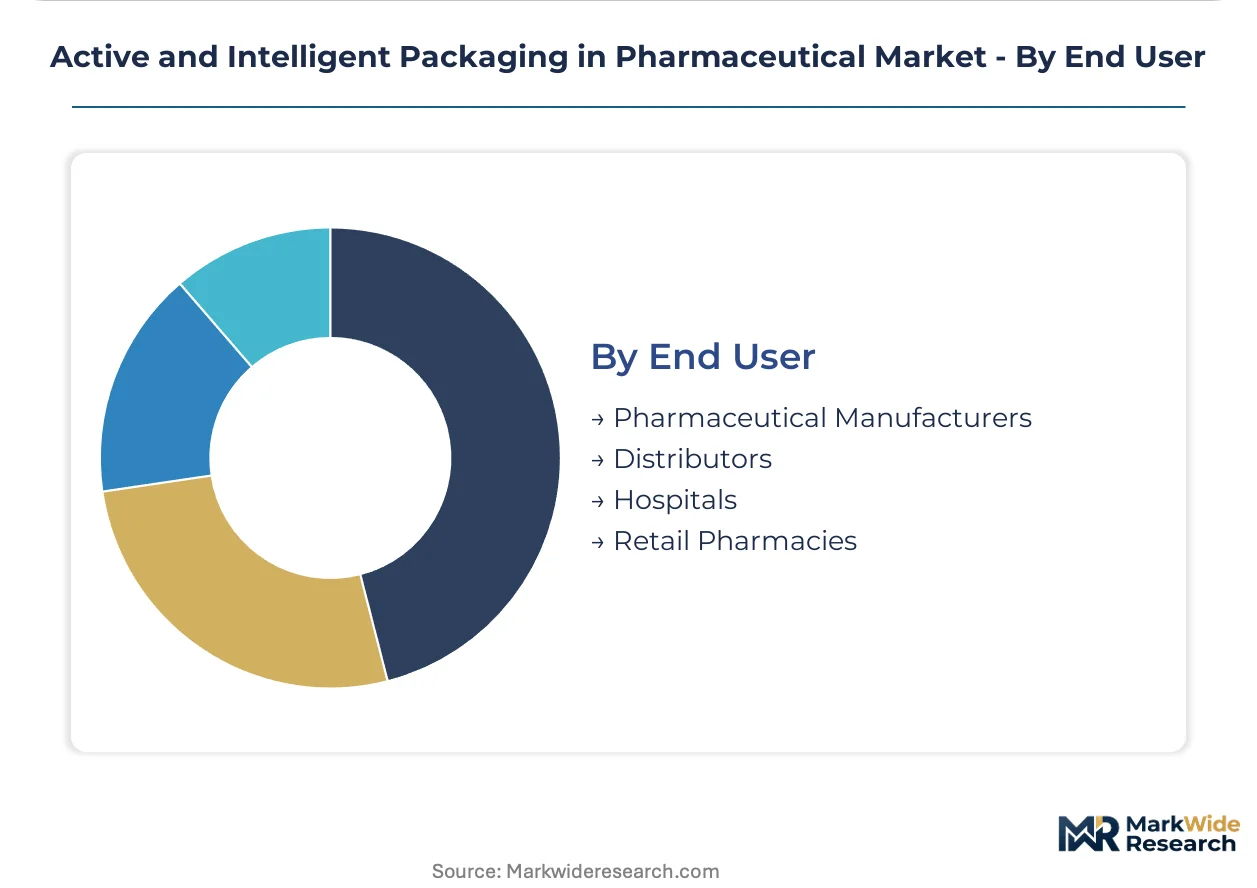
End User:
Pharmaceutical Manufacturers absorb the longest validation cycles for primary packaging changes, while Retail Pharmacies turn over technology fastest through competitive refresh of dispensing systems.
- Pharmaceutical Manufacturers:Primary packaging specification owners integrating compliance, stability, and patient engagement into blister, bottle, and vial formats. Top-20 manufacturers in the United States direct-contract for serialization data ownership, displacing third-party platform licensing.
- Hospitals:Integrated delivery networks consolidating procurement through group purchasing organizations. United States hospital buying groups bundle smart label volumes with traditional formats under multi-year agreements with film-to-device manufacturers.
- Distributors:Third-party logistics providers managing temperature-controlled storage and transport verification.
- Retail Pharmacies:Chain and independent pharmacies deploying adherence-focused packaging for chronic medication programs.
Pharmaceutical Manufacturers dominate installed base. Hospitals is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature cold-chain economies and emerging biologics markets. The United States and Germany deploy sensor-integrated primary packaging for patient adherence analytics, while India and China prioritize low-cost temperature indicators for distribution integrity.
United States
FDA DSCSA serialization deadlines compress procurement timelines for smart labels across top-20 pharmaceutical manufacturers. Hospital buying groups consolidate multi-year contracts bundling RFID-enabled blister packs with traditional formats. New Jersey and Massachusetts biotech clusters specify printed electrochemical sensors for cell-therapy cold-chain validation.
Germany
Bavarian and Baden-Württemberg machinery vendors supply precision coating systems for RFID antenna production, creating equipment supplier concentration. EMA serialization requirements align with FDA mandates, driving dual-compliant label specifications. Frankfurt-Rhine-Main logistics hubs deploy reusable RFID infrastructure for temperature-controlled distribution.
Japan
METI's 2030 carbon-neutral packaging roadmap subsidizes bio-based substrate development for intelligent labels. Chronic disease management programs in Tokyo and Osaka specify adherence-monitoring packaging for reimbursement-linked outcomes. PMDA biologics approvals expand cold-chain monitoring requirements beyond traditional small-molecule portfolios.
India
CDSCO's accelerating biologics approval pipeline outpaces temperature-controlled distribution infrastructure across Maharashtra and Gujarat. Generic manufacturers adopt microencapsulation for cost-sensitive stability extension without capital-intensive cold-chain investment. Hyderabad and Bangalore formulation clusters pilot low-cost printed indicators for export compliance.
Switzerland
Swissmedic's stringent primary packaging standards elevate contamination control requirements for electrochemical sensor migration testing. Basel and Zurich biologics manufacturers specify multi-analyte sensor architectures for high-value injectables. Precision pharmaceutical packaging suppliers cluster around Lake Geneva industrial corridors.
Active and Intelligent Packaging in Pharmaceutical Market Competitive Environment
Capability concentration sits with integrated film-to-device manufacturers; scale advantage sits with diversified packaging conglomerates. The vendor base separates into three tiers: multi-material specialists with captive electronics integration, adhesive-integrated sensor architects, and regional converters licensing third-party platforms. Dominant competitive moves include backward integration into printed electronics manufacturing and direct contracting for serialization data ownership displacing platform intermediaries.
Within the integrated manufacturing tier, Amcor plc and Avery Dennison Corporation occupy positions spanning substrate production to device assembly. Sealed Air Corporation exemplifies the logistics-focused archetype emphasizing reusable cold-chain infrastructure over disposable indicators. These three entities represent divergent strategic vectors: film-to-device integration, adhesive-embedded sensor specialization, and temperature-assurance systems for distribution networks.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Sealed Air Corporation |
| Amcor plc |
| DS Smith |
| Berry Global Inc. |
| Mondi Group |
| Gerresheimer AG |
| Huhtamäki Oyj |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European printed electronics substrate manufacturing is compressing margin structures for RFID-enabled blister pack suppliers while simultaneously accelerating price competition for temperature-monitoring film contracts. This utilization imbalance forces German and Swiss machinery vendors to extend payment terms for precision coating systems, indirectly subsidizing pharmaceutical manufacturers' smart label procurement timelines.
Pricing Analysis
Long-term offtake agreements dominate smart label procurement as top-20 pharmaceutical manufacturers direct-contract for serialization data ownership, displacing spot-market platform licensing. Pricing stratifies across premium, standard, and economy tiers based on FDA DSCSA compliance certification and patient engagement analytics bundling. Cost compression in standard-tier temperature indicators is intensifying because Indian generic manufacturers are scaling microencapsulation alternatives. Hospital buying groups exhibit lowest price sensitivity due to bundled GPO contracts, while independent retail pharmacies face acute margin pressure from adherence-monitoring packaging premiums.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for printed electrochemical sensor substrates. Manufacturing concentration in Germany, Japan, and South Korea feeds from silver and copper conductor inks, polyethylene barrier films, and semiconductor detector components. Single-source vulnerability clusters with Bavarian precision coating equipment vendors. Distribution runs through integrated film-to-device manufacturers holding captive electronics assembly capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital group purchasing organization consolidation in the United States and integrated delivery network procurement centralization in Japan, fragmenting vendor negotiation leverage across mid-tier packaging suppliers.
For Market Incumbents: Pre-empt platform disintermediation by backward integration into printed electrochemical sensor manufacturing rather than licensing third-party architectures. Capture patient engagement analytics control through direct serialization data ownership, neutralizing the threat from SaaS-based adherence platform entrants. Anchor capacity expansion in Switzerland and Germany to exploit proximity to biologics manufacturing clusters requiring ISO 15378-aligned contamination control.
For New Entrants and Emerging Players: Build out low-cost temperature indicator production for Indian CDSCO biologics approvals where cold-chain infrastructure lags behind regulatory expansion. Target Maharashtra and Gujarat generic manufacturers with microencapsulation-based stability extension as the most penetrable segment. Pursue METI subsidy-aligned bio-based substrate development for Japanese intelligent label procurement channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-integrated primary packaging as pharmaceutical manufacturers demand in-house electronics assembly rather than outsourced component attachment. Long-term viability favors integrated film-to-device manufacturers with captive RF engineering capabilities over pure-play adhesive converters. Watch for FDA DSCSA enforcement intensity as the signal indicating whether serialization data ownership premiums sustain or compress.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Printed Electronics | Captures margin pools from silver conductor inks and eliminates third-party sensor licensing dependencies. |
| Direct Serialization Data Ownership | Displaces platform intermediaries and enables patient adherence analytics control for FDA DSCSA compliance. |
| Bio-Based Substrate Development | Aligns with METI carbon-neutral packaging subsidies and opens Japanese procurement channels. |
| Multi-Analyte Sensor Architecture | Eliminates separate desiccant canisters for Swiss biologics manufacturers and reduces bill-of-materials complexity. |
| Low-Cost Indicator Localization | Addresses Indian CDSCO biologics pipeline expansion where temperature-controlled distribution infrastructure remains underdeveloped. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA DSCSA guidance documents, EMA falsified medicines enforcement records, and ISO 15378 certification databases. Primary interviews engaged packaging development executives at top-20 pharmaceutical manufacturers, regulatory affairs leads navigating serialization mandates, hospital GPO procurement managers, and RF engineering specialists at printed electronics substrate suppliers. Secondary validation drew from SEC 10-K disclosures of integrated packaging conglomerates, customs trade data for silver and copper conductor imports, and clinical trial cold-chain requirement filings. Bottom-up unit economics for temperature-monitoring film production were triangulated against top-down pharmaceutical packaging procurement budget allocations.
Forecast inputs span product type segmentation across temperature monitoring, smart labels, active packaging, and RFID tags; application segmentation across patient compliance, safety monitoring, drug delivery, and inventory management; technology segmentation across sensor technology, microencapsulation, nanotechnology, and biodegradable materials; and end-user segmentation across pharmaceutical manufacturers, hospitals, distributors, and retail pharmacies. Treatment line positioning, dosage form complexity, and regional regulatory cluster stringency were modeled as cross-cutting dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating mRNA pipeline expansion rates and DSCSA compliance deadline proximity. Industry-specific inputs include CDSCO biologics approval velocity and METI sustainable packaging subsidy allocation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by adhesive-integrated sensor specialists would shift outcomes beyond modeled ranges. Material shifts in FDA DSCSA enforcement intensity or EMA serialization timeline acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Vaccine Shippers Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market