
 Saudi Arabia Pharmaceutical Packaging Market | 2026-2036
Saudi Arabia Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Pharmaceutical Packaging Market Analytics
SFDA serialization mandates for pharmaceutical traceability is repositioning demand toward smart labels and integrated coding systems. Rexam PLC leverages its aluminum and glass expertise to supply primary containers for domestic injectable production. Salman Group anchors local carton manufacturing through Noor Carton & Packaging Industry's expanded Riyadh operations. Aptar Group specializes in dosing and dispensing closures that meet SFDA child-resistance standards.
Pharmaceutical packaging encompasses primary and secondary containment systems engineered with barrier films, desiccant integration, and tamper-evident seals to ensure drug stability, patient safety, and regulatory compliance throughout distribution. Blister packaging dominates unit-dose dispensing for Saudi Arabia's expanding generics sector, while cold-chain formats for biologics command premium margins due to specialized insulation and temperature-monitoring requirements. Plastic bottles lead volume in over-the-counter distribution, though glass vials sustain higher per-unit value in hospital-administered therapies.
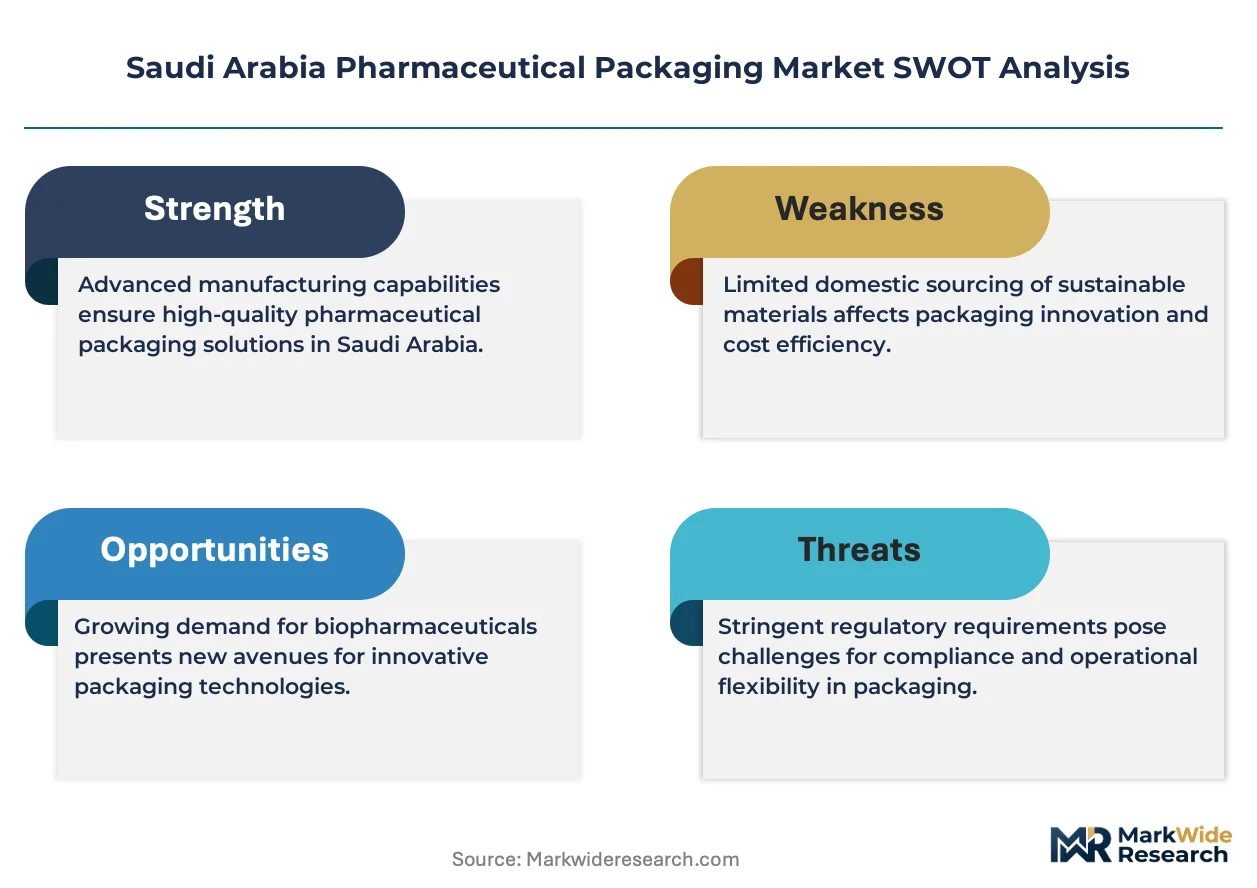
SFDA enforcement of Gulf Central Committee for Drug Registration harmonized standards, alongside SASO technical regulations for packaging materials, shapes material selection and supplier qualification protocols across the Kingdom. The Saudi Food and Drug Authority's alignment with WHO prequalification criteria further filters import sourcing toward certified international vendors. Stakeholders must monitor domestic API manufacturing expansion under Vision 2030 localization targets, as backward integration into pharmaceutical production will reshape packaging procurement from import-dependent to captive-supply models.
Market Dynamics
SFDA serialization mandates and biologics cold-chain requirements are compressing supplier qualification timelines while elevating technical barriers to market entry across Saudi Arabia's pharmaceutical packaging sector.
Growth Catalysts
- Biologics manufacturing expansion:Contract manufacturers in Riyadh's industrial cluster are commissioning temperature-controlled packaging for monoclonal antibodies and vaccines, creating specialized demand for validated cold-chain formats.
- SFDA track-and-trace mandates:The Saudi Food and Drug Authority's serialization requirements are forcing label upgrades to integrated coding systems with unique identifiers at the unit level.
- Vision 2030 localization targets:Domestic API manufacturing investments are pulling packaging procurement from import-dependent models toward captive supply arrangements with local converters.
Market Restraints
- Aluminum and polymer feedstock volatility:Primary container costs fluctuate with global commodity indices, compressing margins for blister and bottle converters serving the generics sector.
- European and Asian supplier concentration:Specialized barrier films and desiccant technologies remain concentrated among a limited set of certified international vendors, creating qualification bottlenecks.
- SFDA harmonization friction:Gulf Central Committee for Drug Registration alignment delays are extending approval timelines for novel packaging materials and formats.
Strategic Opportunities
- Eastern Province biologics corridor:King Abdullah Economic City's emerging life sciences zone offers greenfield packaging facility placement adjacent to planned fill-finish operations.
- Smart label convergence:Temperature-logging RFID and NFC integration with secondary packaging is creating premium service tiers for high-value biologics distribution.
- Reverse logistics integration:Returnable and reusable cold-chain shipper models are opening service-based revenue streams beyond single-use packaging sales.
Industry Challenges
- Cold-chain validation expertise scarcity:Thermal mapping and ISTA 7E testing capabilities are concentrated among a limited pool of qualified engineers, extending project timelines.
- Serialization line retrofit capex:Existing carton and label production equipment requires substantial modification to accommodate aggregation and verification hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Pharmaceutical Packaging Market |
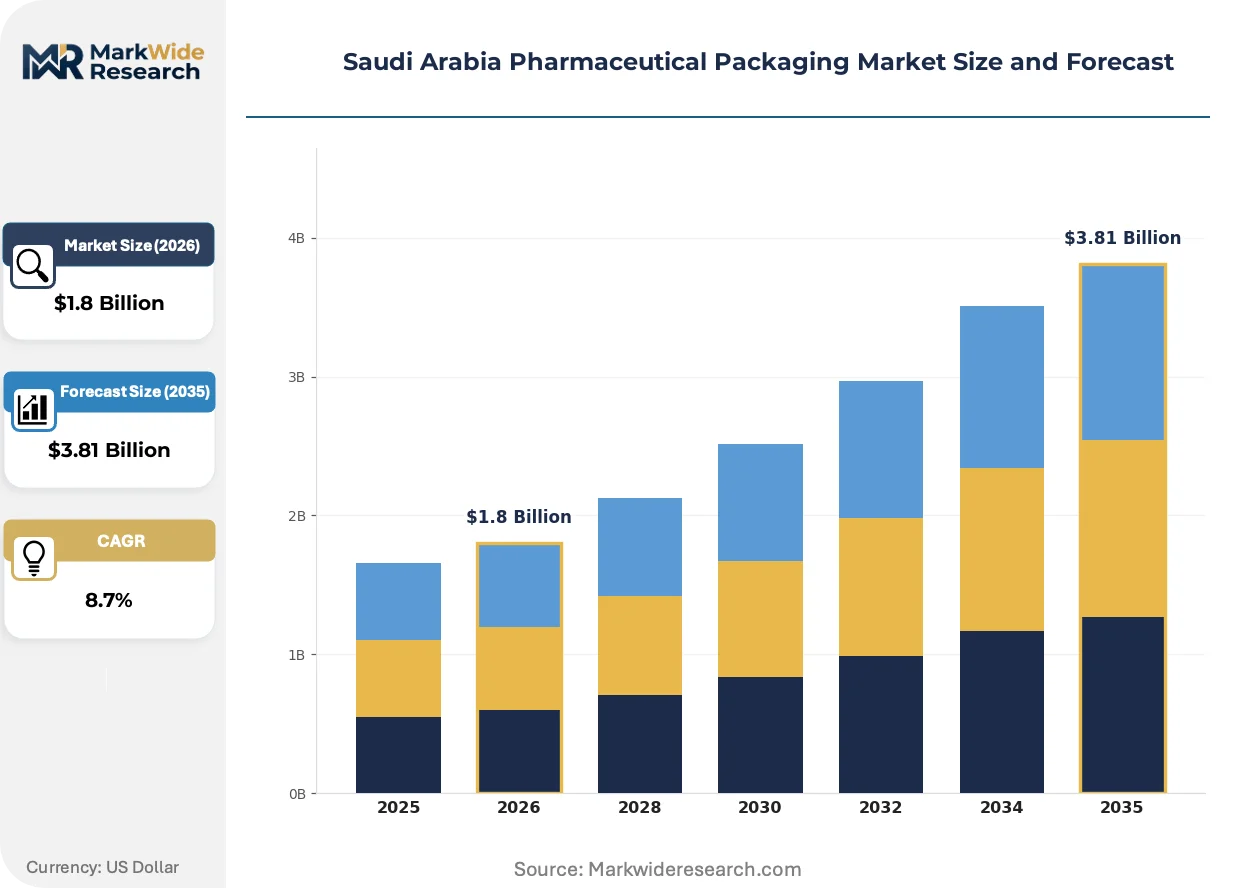
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Blisters, Cartons, Labels Material: Plastic, Glass, Paper, Aluminum End User: Pharmacies, Hospitals, Clinics, Contract Manufacturers Product Type: Prescription Drugs, Over-the-Counter, Biologics, Generics |
| Companies Covered | Rexam PLC (Ball Corporation), Salman Group (Noor Carton & Packaging Industry), CCL Industries, Aptar Group, Jabil Inc., Napco Group, Sealed Air Saudi Arabia, Amber Packaging Industries LLC, Becton, Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Pharmaceutical Packaging Market Evolving Landscape
Active and intelligent packaging formats are penetrating Saudi pharmaceutical supply chains, driven by regulatory mandates for traceability and the thermal sensitivity of expanding biologics portfolios.
Multi-layer barrier films with embedded desiccant functionality are absorbing moisture protection requirements previously handled by separate sachet inserts. Domestic injectable manufacturers are adopting these integrated formats to streamline line speeds and reduce foreign object risk. The technology is absorbing market share from conventional blister-lidding combinations in high-humidity climate applications.
SFDA alignment with WHO prequalification criteria is filtering import sourcing toward packaging suppliers with established international certification. This regulatory convergence is compressing the qualified vendor pool while elevating documentation and audit requirements. Secondary packaging converters serving export-oriented pharmaceutical manufacturers are investing in upgraded quality management systems to maintain access.
Hospital and pharmacy procurement consolidation is concentrating purchasing power among integrated health systems and national distributor networks. Long-term framework agreements with technical specifications are displacing spot-market transactions for primary containers. This pattern is most visible in Riyadh and Jeddah, where Ministry of Health central procurement is standardizing packaging requirements across affiliated facilities.
Saudi Arabia Pharmaceutical Packaging Market Segmentation
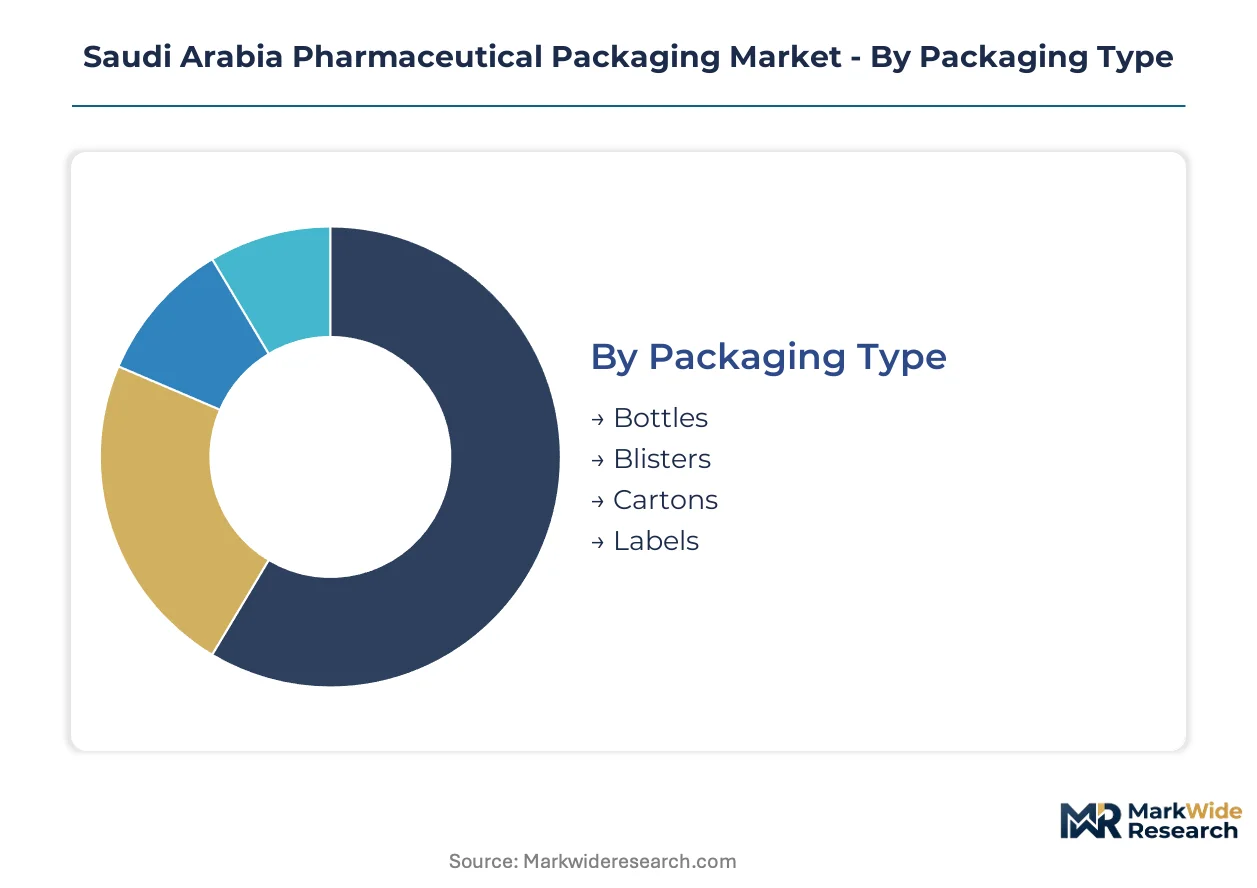
Pharmaceutical packaging segmentation in Saudi Arabia reflects divergent capital requirements across primary containment, secondary branding, and cold-chain logistics. Material selection and regulatory compliance tiers create distinct investment profiles that shape supplier positioning across Riyadh's industrial cluster.
Packaging Type:
Capital intensity peaks in formats requiring specialized barrier engineering and serialization-ready infrastructure.
- Bottles:High-density polyethylene and polyethylene terephthalate containers dominate oral solid dosing for chronic therapies. Demand concentrates in Jeddah's distribution corridor, where Ministry of Health central procurement standardizes HDPE specifications for hypertension and diabetes medications.
- Blisters:Thermoformed PVC and aluminum cold-form laminates provide unit-dose protection with tamper-evident sealing. Riyadh's generics manufacturers are the primary volume sink, though SFDA serialization mandates are forcing line upgrades to accommodate integrated coding systems at unit level.
- Cartons:Folding cartonboard with embedded track-and-trace layers serves secondary branding and regulatory information display.
- Labels:Pressure-sensitive and booklet formats carry serialization codes, dosing instructions, and multilingual warnings.
Most installed capacity flows through Bottles. Expansion is steepest in Blisters.
Material:
Raw material sourcing geography and conversion complexity determine working capital intensity and supplier qualification timelines.
- Plastic:Injection-molded and blow-molded polymers offer design flexibility and child-resistance compliance at scale. Eastern Province resin converters supply Riyadh pharmaceutical clusters, though polymer feedstock volatility compresses margins for generic drug packaging.
- Glass:Borosilicate and soda-lime vials sustain premium positioning for parenteral and biologic applications. Domestic injectable fill-finish operations in King Abdullah Economic City are pulling demand toward Type I borosilicate formats with validated container closure integrity.
- Paper:SBS and CUK board grades provide printable surfaces for secondary cartons and patient information leaflets.
- Aluminum:Cold-form foils and lidding materials deliver moisture and light barriers for sensitive formulations.
Glass commands the highest per-unit value. Plastic carries the largest tonnage throughput.
End User:
Procurement consolidation patterns and technical specification rigor vary sharply across institutional versus commercial channels.
- Pharmacies:Retail dispensaries drive volume for OTC bottles and blister packs with consumer-readable labeling. Urban pharmacy chains in Riyadh and Jeddah are consolidating purchasing through national distributor networks, displacing fragmented spot buying.
- Hospitals:Ministry of Health facilities impose stringent lot traceability and unit-dose requirements. Centralized tendering across affiliated hospitals in the Central Region standardizes primary container specifications for oncology and critical care therapies.
- Clinics:Outpatient facilities generate mixed demand for sample-sized and full-course packaging formats.
- Contract Manufacturers:CDMO operations in Riyadh's industrial cluster are the fastest-expanding demand source, commissioning validated cold-chain formats for biologics export.
Contract Manufacturers absorb the most specialized technical investment. Pharmacies represent the broadest volume base.
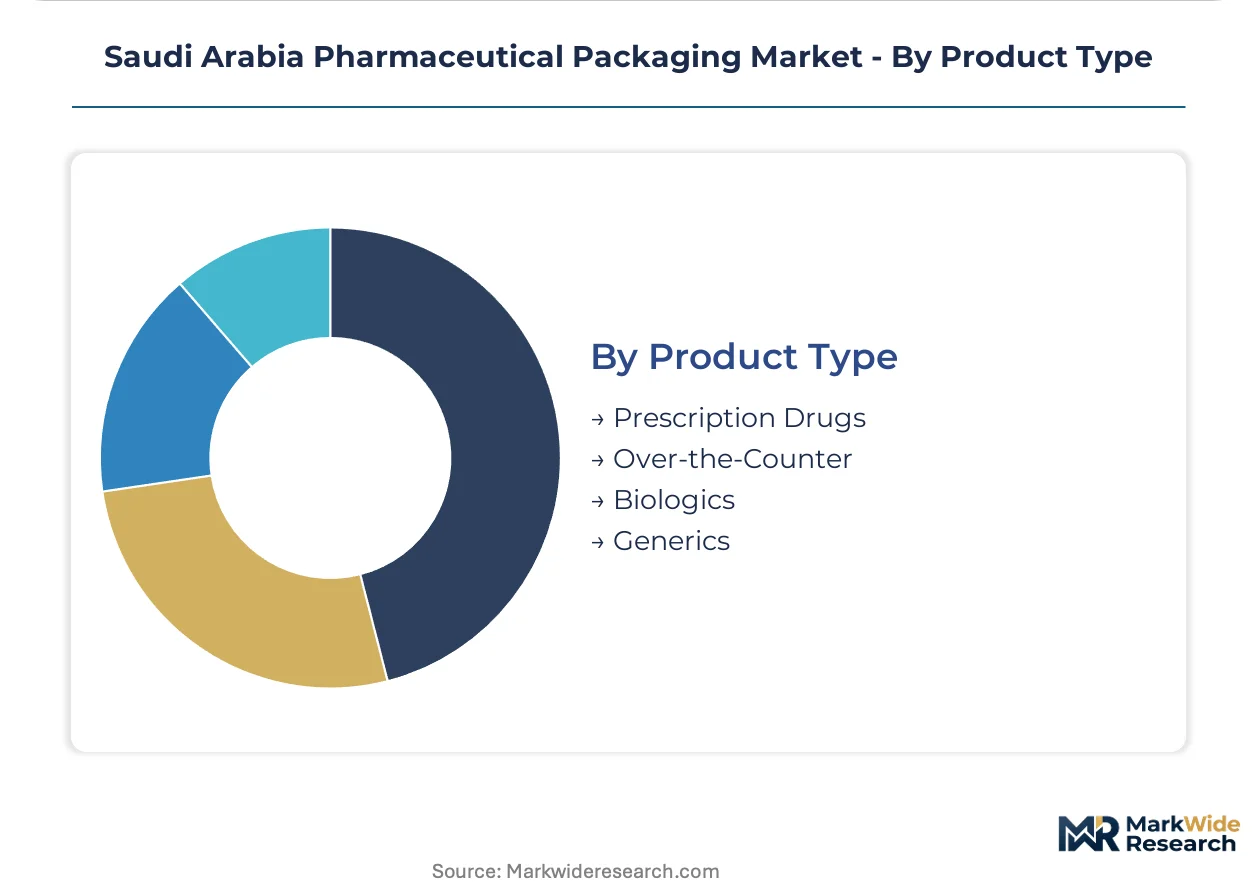
Product Type:
Regulatory pathway complexity and thermal sensitivity create tiered packaging performance requirements across therapeutic categories.
- Prescription Drugs:Physician-directed therapies require child-resistant closures, adherence packaging, and detailed patient counseling inserts. Cardiovascular and metabolic prescriptions dominate hospital discharge volumes in the Central Region.
- Over-the-Counter:Self-medication categories prioritize shelf appeal, tamper evidence, and consumer-friendly opening features. Analgesic and gastrointestinal OTC segments drive bottle demand through retail pharmacy networks.
- Biologics:Monoclonal antibodies and vaccines demand validated cold-chain packaging with temperature-logging capabilities. Riyadh contract manufacturers are commissioning thermal shippers with phase-change materials for GCC export.
- Generics:Cost-optimized blister and bottle formats serve price-sensitive substitution markets. Domestic production capacity expansion under Vision 2030 is pulling packaging procurement toward local converter relationships.
Generics command the largest unit volume. Biologics carry the steepest packaging value premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cold-chain engineers and thermal validation specialists concentrate in Riyadh's industrial corridor, anchoring Saudi Arabia's pharmaceutical packaging workforce density. Eastern Province resin converters and Western Region distribution hubs complete the Kingdom's tripartite supply geography.
Riyadh
Contract manufacturers commissioning monoclonal antibody packaging drive specialized demand for validated cold-chain formats. SFDA serialization mandates force label upgrades across the Second Industrial City cluster. King Salman Park life sciences zone is attracting fill-finish operations that pull primary container procurement toward captive supply arrangements.
Eastern Province
Petrochemical feedstock integration supports high-density polyethylene bottle production for chronic therapy distribution. SASO technical regulations for packaging materials shape resin grade specifications at Jubail industrial complexes. King Abdullah Economic City's emerging biologics corridor offers greenfield packaging placement adjacent to planned vaccine manufacturing.
Western Region
Jeddah's Ministry of Health central procurement standardizes container specifications across affiliated hospital networks. Red Sea port logistics concentrate import sourcing for European barrier films and Asian desiccant technologies. King Abdullah Medical City oncology procurement is consolidating unit-dose requirements for hospital-administered therapies.
NEOM Northwest
Regulatory sandbox provisions for advanced manufacturing are testing autonomous packaging line deployments. Vision 2030 localization targets prioritize domestic API-to-packaging integration in the linear city development zone. Oxagon industrial city planning includes dedicated pharmaceutical logistics infrastructure with temperature-controlled warehousing.
Saudi Arabia Pharmaceutical Packaging Market Competitive Landscape
Capital-heavy converters with integrated resin and metallization capabilities compete with asset-light specialists sourcing barrier films from certified international vendors. The supplier base stratifies across three tiers: multinational material science conglomerates with aluminum and polymer expertise, regional carton and label converters with SFDA serialization line investments, and niche cold-chain engineering firms with ISTA 7E validation capabilities. Dominant competitive moves include strategic partnerships with domestic API manufacturers under Vision 2030 localization mandates and portfolio diversification into temperature-logging smart label formats.
Within the multinational material science tier, Rexam PLC and Aptar Group exemplify archetypes with aluminum, glass, and dosing closure expertise. Salman Group anchors regional carton manufacturing through Noor Carton & Packaging Industry's Riyadh operations, representing the domestic converter segment's scale position. These three occupy distinct competitive spaces: metallized barrier and primary containment, precision dispensing systems, and secondary packaging with integrated track-and-trace layers.
| Leading Market Players |
|---|
| Rexam PLC (Ball Corporation) |
| Salman Group (Noor Carton & Packaging Industry) |
| CCL Industries |
| Aptar Group |
| Jabil Inc. |
| Napco Group |
| Sealed Air Saudi Arabia |
| Amber Packaging Industries LLC |
| Becton, Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Captive supply arrangements between Riyadh's expanding contract manufacturers and domestic packaging converters anchor both cost predictability and margin defense for primary container procurement. SFDA serialization mandates and cold-chain validation requirements compress supplier choice, elevating pricing power for certified vendors while squeezing spot-market alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated cold-chain formats from conventional blister packs and commodity bottles. Price differentiation hinges on ISO 15378 certification grade and thermal validation documentation depth. Cost compression in the generics bottle segment is intensifying because polymer feedstock volatility transfers directly to converter margins. Hospital procurement through Ministry of Health central tenders exhibits lowest price sensitivity; retail pharmacy chains show highest elasticity.
Supply Chain Analysis
Direct-to-CDMO channels handle hyperscale demand from Riyadh's biologics manufacturers, while distributor networks aggregate fragmented pharmacy procurement. Geographic supply concentration rests on Germany for barrier film metallization, China for desiccant technologies, and India for secondary cartonboard grades. Raw material dependencies draw from Saudi petrochemical feedstocks for HDPE resin, imported aluminum coil for cold-form foils, and European specialty polymers for multilayer structures. Single-source vulnerability in ISTA 7E thermal validation engineering creates qualification bottlenecks for cold-chain packaging deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's pharmaceutical packaging market functions as a regulatory compounder where SFDA serialization mandates and Gulf Central Committee harmonization create sustained demand for upgraded label and track-and-trace infrastructure.
For Market Incumbents: Hedge against margin compression in generic blister formats by securing backward integration into aluminum lidding supply through Jubail metallization partnerships. SFDA enforcement of WHO prequalification criteria threatens import-dependent converters; prioritize captive resin supply from Eastern Province petrochemical complexes to defend cost position in high-volume bottle segments. For New Entrants and Emerging Players: Contract manufacturer technical service partnerships offer the most penetrable entry vector, particularly for temperature-logging RFID integration with secondary cartons. Target King Abdullah Economic City's emerging biologics corridor where greenfield fill-finish operations lack validated cold-chain packaging relationships. Lead with thermal shipper rental models rather than single-use sales to differentiate service architecture. For Investors and Strategic Acquirers: Roll-up economics work for regional carton converters with SFDA serialization line investments because qualification timelines for new entrants extend 18-24 months. Long-term viability centers on platforms with integrated primary-to-secondary packaging capabilities and established CDMO relationships. Monitor King Salman Park life sciences zone occupancy rates as inflection indicator for captive supply model adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Validation Partnership | ISTA 7E certification with Riyadh CDMOs secures biologics packaging exclusivity. |
| Serialization Line Retrofit | Aggregation hardware integration meets SFDA track-and-trace mandate deadlines. |
| Reverse Logistics Platform | Returnable thermal shipper pools generate recurring revenue beyond unit sales. |
| Backward Integration into Metallization | Jubail aluminum coil processing reduces cold-form foil import dependency. |
| Smart Label Convergence | NFC temperature logging with secondary packaging creates premium service tiers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with packaging procurement managers at Ministry of Health facilities, regulatory affairs leads at SFDA, supply chain directors at Riyadh contract manufacturers, and technical directors at domestic carton converters. Secondary validation drew from SFDA serialization guidance documents, SASO technical regulations for packaging materials, Gulf Central Committee harmonization standards, and customs import data for barrier films and desiccant technologies. Bottom-up demand modeling across dosage formats and therapeutic categories was triangulated against top-down pharmaceutical production capacity estimates.
Historical reference periods spanning pre- and post-SFDA mandate implementation anchored the forecast window, with growth trajectory calibration against Vision 2030 localization investment schedules. Segmentation dimensions modeled include packaging type, material grade, end-user channel, and product thermal sensitivity tier. CAGRs were derived from supply-side capacity buildout timelines and demand-pull from domestic API manufacturing expansion. Industry-specific inputs incorporated cold-chain validation project backlogs and serialization line retrofit capex cycles.
Revisions become necessary when SFDA enforcement intensity shifts, Gulf Central Committee alignment timelines extend, or biologics manufacturing investment pauses materialize. Forecasts reflect documented assumptions regarding petrochemical feedstock cost stability and qualified engineering labor availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market