
 Pharmaceutical Caps and Closures Market | 2026-2036
Pharmaceutical Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
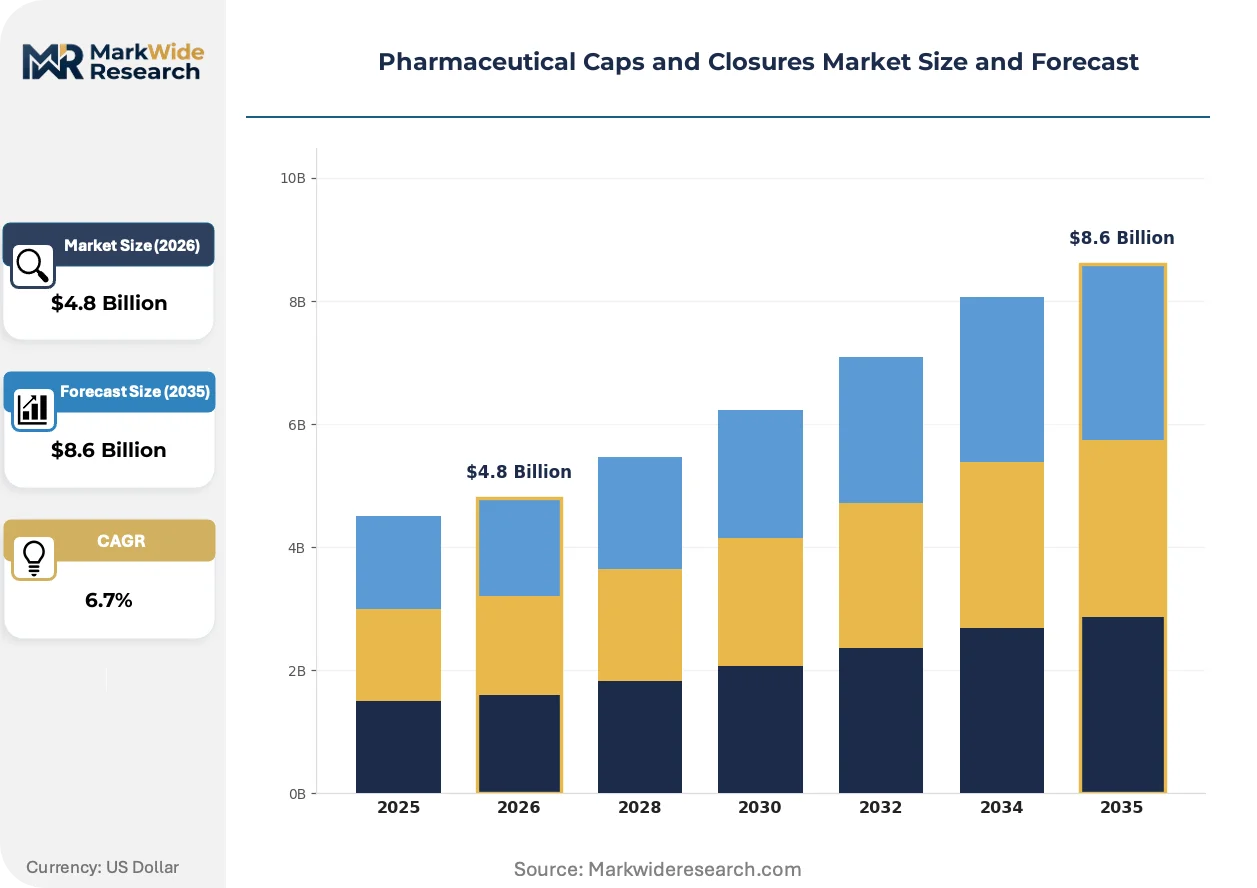
Pharmaceutical Caps and Closures Market Outlook
ISO 15378 certification for primary packaging materials is reorganizing competitive access in pharmaceutical closures. Berry Global Group Inc. leverages its multi-material platform across plastic and aluminum closure formats. West Pharmaceutical Services, Inc. anchors its position through integrated elastomer and closure systems for biologic containment. AptarGroup, Inc. differentiates via precision-dosing closure technologies for specialized drug delivery.
Pharmaceutical caps and closures are engineered sealing and dispensing interfaces, typically manufactured from polypropylene, high-density polyethylene, or aluminum with elastomeric liners, designed to ensure container integrity, prevent contamination, and enable controlled substance access. Screw caps dominate volume demand across oral solid dosage bottles, while tamper-evident closures command premium positioning due to regulatory mandates for over-the-counter and prescription drug security. Plastic closures sustain the largest material share driven by cost scalability, though aluminum alternatives retain niche strength in parenteral and high-barrier applications.
FDA cGMP requirements and EU MDR standards enforce extractables and leachables testing protocols that elevate R&D barriers for new closure entrants. The EPA and ECHA jointly constrain plasticizer and additive chemistries through evolving substance restrictions, redirecting formulation investments toward compliant polymer systems. Stakeholders must monitor how dual regulatory pressures on material safety and traceability reshape supplier qualification timelines and contract manufacturing relationships.
Market Dynamics
Biologic drug containment requirements are forcing pharmaceutical manufacturers to requalify their entire closure supply chains, elevating elastomeric liner specifications and extractables testing protocols as the decisive competitive filter.
Growth Catalysts
- EU MDR and FDA cGMP alignment:Harmonized extractables and leachables testing standards are compelling drug sponsors to upgrade closure specifications, expanding the addressable market for certified primary packaging materials.
- Biologics manufacturing expansion:Monoclonal antibody and cell therapy producers in Germany, the United States, and India are procuring specialized elastomeric closure systems with validated container-closure integrity.
- Child-resistant mandate proliferation:Poison Prevention Packaging Act enforcement and comparable EU safety directives are converting standard screw caps to tamper-evident and child-resistant formats across over-the-counter portfolios.
Market Restraints
- Raw material concentration:Medical-grade polypropylene and halobutyl elastomer supply concentrates among petrochemical complexes in the US Gulf Coast and Middle East, exposing converters to feedstock volatility.
- ISO 15378 certification barriers:The quality management standard for primary packaging materials imposes 12-18 month qualification timelines that freeze out uncertified regional suppliers.
- Aluminum substitution ceiling:High-barrier parenteral applications retain metal closure preference despite plastic advances, limiting polymer penetration in lyophilized and oxygen-sensitive drug segments.
Strategic Opportunities
- Indian pharmaceutical packaging hub expansion:CDSCO manufacturing license reforms and export-linked incentive schemes are attracting multinationals to establish regional closure sourcing and finishing operations.
- Precision-dosing convergence:Metered-dose and micro-dispensing closure technologies for ophthalmic and nasal biologics represent uncaptured value pools beyond conventional screw-cap commoditization.
- EU Green Deal chemistry restrictions:ECHA substance of very high concern designations for certain plasticizers are creating first-mover advantage for compliant polymer reformulation specialists.
Industry Challenges
- Container-closure integrity validation:Biologic drug sponsors demand probabilistic leak-test data and accelerated aging studies that extend new product introduction cycles by 8-14 months.
- Cross-functional talent scarcity:The intersection of polymer science, pharmaceutical regulatory affairs, and high-speed automation engineering remains undersupplied across closure manufacturers and their drug-company customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Caps and Closures Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Bottles, Syringes, Ampoules Material: Plastic, Glass, Rubber, Aluminum Closure Type: Screw Caps, Snap Caps, Corks, Tamper-Evident Caps End User: Pharmaceutical Companies, Contract Manufacturers, Research Labs, Hospitals |
| Companies Covered | Berry Global Group Inc., West Pharmaceutical Services, Inc., AptarGroup, Inc., Amcor Plc, Gerresheimer AG, WestRock Company, Datwyler Sealing Solutions, Stevanato Group, Closure Systems International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Caps and Closures Market Strategic Shifts
Digital traceability integration and advanced barrier material science are restructuring how pharmaceutical closures demonstrate provenance, performance, and patient safety across the value chain.
Multilayer co-injection molding with ethylene vinyl alcohol interlayers is bifurcating the high-barrier closure segment. Parenteral and inhalation drug manufacturers in Switzerland and Japan are specifying these structures for moisture-sensitive formulations. The technology is compressing aluminum's historical dominance in premium barrier applications while commanding 40-60% price premiums over standard polypropylene.
REACH substance restriction amendments and FDA guidance on nitrosamine impurities are tightening elastomeric compound formulations. Closure manufacturers must reformulate curing agents and accelerate extractables profiling to retain drug-master-file compatibility. The regulatory friction falls most heavily on generic oral solid dosage producers with legacy compound portfolios.
Consolidated buying by contract development and manufacturing organizations is compressing supplier negotiation cycles and unbundling technical service from unit pricing. Large CDMOs in North Carolina and Bavaria now demand dedicated quality agreements and inventory consignment. The shift is most pronounced in sterile injectable segments where supply assurance outweighs transactional cost optimization.
Pharmaceutical Caps and Closures Market Segmentation
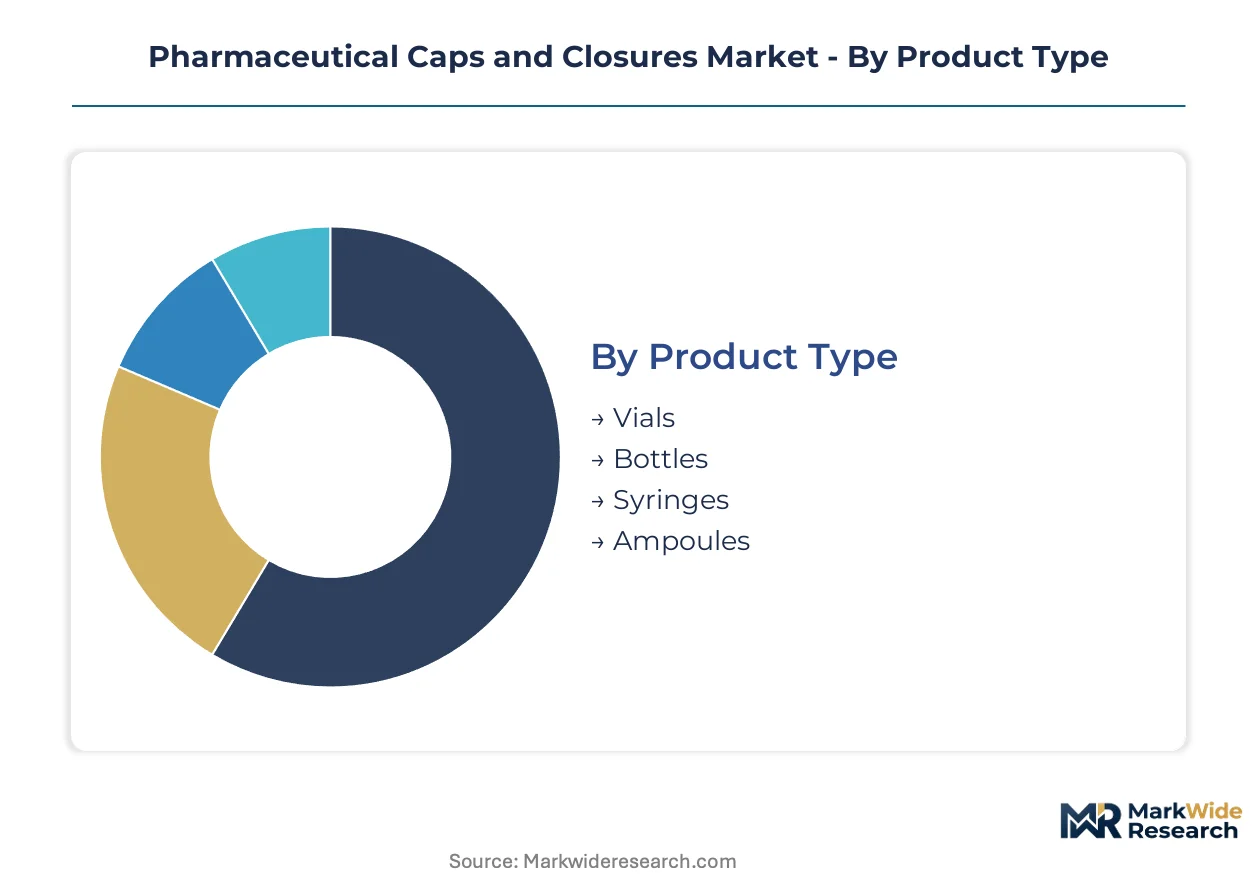
Pharmaceutical caps and closures segment along functional, material, and regulatory dimensions that directly determine container-closure integrity validation requirements. Each segmentation axis carries distinct certification burdens and supply chain qualification protocols that reshape competitive access.
Product Type:
FDA cGMP and EU MDR impose divergent extractables testing protocols across primary container formats, forcing closure manufacturers to maintain parallel validation dossiers.
- Vials:Borosilicate or tubular glass containers with elastomeric septum closures dominate parenteral biologics. German and Swiss monoclonal antibody producers specify halobutyl rubber formulations with validated container-closure integrity for freeze-dried and liquid formulations.
- Bottles:High-density polyethylene and polyethylene terephthalate containers with screw or child-resistant closures command oral solid dosage volume. Indian pharmaceutical exporters in Hyderabad and Ahmedabad drive procurement of tamper-evident formats meeting Poison Prevention Packaging Act requirements for US-bound generics.
- Syringes:Prefilled glass or polymer barrels with integrated plunger-stopper systems require elastomeric formulations compatible with protein therapeutics. The format demands accelerated aging studies that extend supplier qualification timelines.
- Ampoules:Single-use glass containers with flame-sealed necks bypass conventional closure systems entirely, eliminating elastomeric extractables concerns but requiring specialized scoring and break-ring designs for safe opening.
Established volume favors bottles; emerging adoption favors vials as biologics manufacturing expands.
Material:
Raw material selection locks in regulatory compliance pathways and determines barrier performance against moisture, oxygen, and extractables migration.
- Plastic:Medical-grade polypropylene and cyclic olefin polymer dominate oral and topical applications. ECHA substance of very high concern designations for certain plasticizers are redirecting formulation investments toward compliant polymer systems certified under ISO 15378.
- Glass:Type I borosilicate and treated soda-lime compositions serve parenteral and high-barrier needs. The material retains preference for oxygen-sensitive and lyophilized drugs despite weight and fragility penalties.
- Rubber:Halobutyl, bromobutyl, and silicone elastomer formulations function as septum, liner, and plunger components. FDA guidance on nitrosamine impurities is forcing reformulation of curing agents across legacy compound portfolios.
- Aluminum:Rolled and deep-drawn metal closures with lacquered interiors retain niche strength in parenteral vial seals and high-barrier applications where plastic oxygen transmission rates remain insufficient.
Plastic captures standard-volume share; aluminum defends premium-barrier positioning.
Closure Type:
Mechanism design determines patient safety compliance, dispensing functionality, and manufacturing automation compatibility.
- Screw Caps:Threaded polypropylene or polyethylene closures with induction-sealed liners dominate oral solid dosage bottles. The format sustains cost scalability but requires conversion to child-resistant designs for regulatory compliance.
- Snap Caps:Press-fit closures with audible engagement feedback serve unit-dose and compliance packaging. CDMOs in Bavaria specify these for blister-lid integration in elderly-accessible formats.
- Corks:Agglomerated and natural cork closures retain residual demand for traditional wine-based pharmaceutical tinctures and ceremonial products, though synthetic alternatives displace volume.
- Tamper-Evident Caps:Break-ring, shrink-band, and induction-seal technologies command premium positioning. EU MDR and FDA mandates for over-the-counter security are converting standard screw caps to these formats across portfolios.
Screw caps anchor commodity volume; tamper-evident formats climb the fastest on regulatory mandate proliferation.
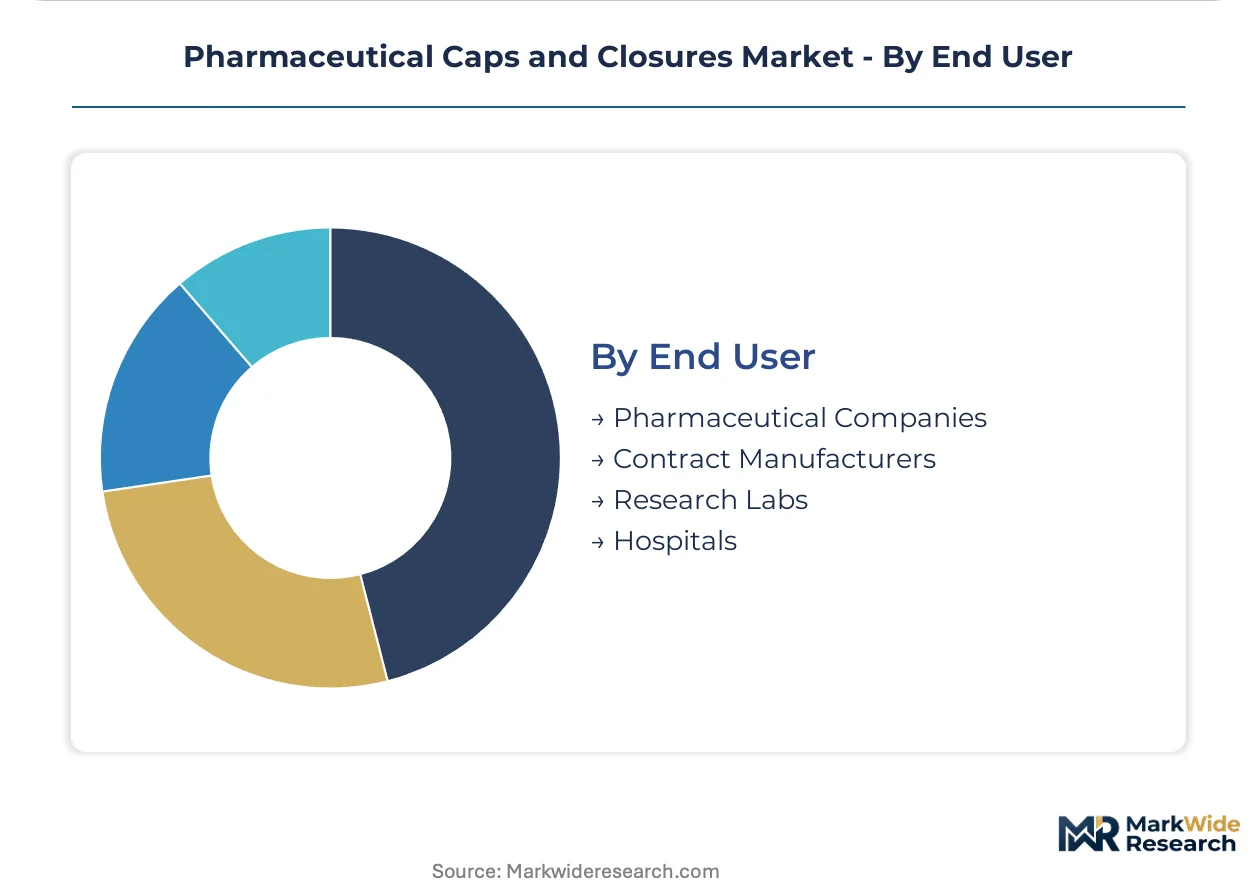
End User:
Customer scale and technical sophistication determine service bundling, inventory models, and quality agreement structures.
- Pharmaceutical Companies:Multinational drug sponsors with internal packaging operations demand dedicated quality agreements and long-term supply contracts. These buyers validate entire closure supply chains for biologic containment.
- Contract Manufacturers:CDMOs in North Carolina and Bavaria consolidate procurement across multiple drug sponsors, compressing negotiation cycles and demanding inventory consignment for sterile injectable segments.
- Research Labs:Academic and clinical trial material producers purchase lower volumes with higher specification variability, requiring flexible minimum order quantities and rapid qualification support.
- Hospitals:Compounding pharmacies and centralized sterile preparation facilities source closures for patient-specific admixtures, prioritizing single-use formats and aseptic presentation.
Pharmaceutical companies retain direct procurement dominance; contract manufacturers gain share through outsourcing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-linked incentive schemes and domestic manufacturing license reforms are redirecting pharmaceutical packaging investments toward specialized closure production hubs in Germany, the United States, India, Switzerland, and Japan.
United States
Monoclonal antibody producers in North Carolina and Massachusetts are procuring validated elastomeric closure systems for biologic containment. FDA cGMP extractables and leachables testing protocols enforce 12-18 month supplier qualification timelines. The Research Triangle Park cluster anchors sterile injectable packaging operations serving both domestic drug sponsors and export markets.
Germany
Freeze-dried biologic manufacturers in Bavaria and Baden-Württemberg specify halobutyl rubber formulations with demonstrated container-closure integrity. EU MDR quality system regulations tighten child-resistant and tamper-evident standards for over-the-counter portfolios. The Upper Franconia region concentrates precision-dosing closure finishing operations for ophthalmic and nasal drug delivery.
India
Generic pharmaceutical exporters in Hyderabad and Ahmedabad drive procurement of Poison Prevention Packaging Act-compliant closures for US-bound oral solid dosages. CDSCO manufacturing license reforms and production-linked incentive schemes attract multinationals to establish regional sourcing operations. The Gujarat pharmaceutical belt specializes in high-volume screw cap and tamper-evident format production.
Switzerland
Parenteral and inhalation drug manufacturers specify multilayer co-injection molded closures with ethylene vinyl alcohol interlayers for moisture-sensitive formulations. Swissmedic pharmaceutical regulations align with EU MDR standards for primary packaging material certification. The Basel-Land canton hosts integrated elastomer and closure system operations serving biologic drug sponsors.
Japan
Prefilled syringe producers in Kanto and Kansai regions demand elastomeric formulations compatible with protein therapeutics and accelerated aging validation protocols. PMDA quality guidelines enforce nitrosamine impurity controls across rubber compound portfolios. The Osaka pharmaceutical corridor concentrates plunger-stopper system manufacturing for cell therapy applications.
Pharmaceutical Caps and Closures Market Competitive Environment
Player mix skews toward diversified packaging conglomerates with multi-material platforms, integrated elastomer specialists, and precision-dosing technology developers. The market structure concentrates among tier-one suppliers capable of ISO 15378 certification and parallel FDA-EU validation dossiers. Three archetypes dominate: petrochemical-anchored converters with backward polymer integration, pharmaceutical-dedicated component manufacturers with captive elastomer compounding, and drug delivery specialists with metering mechanism intellectual property. Competitive dynamics center on M&A-driven portfolio diversification into biologic-compatible materials and strategic partnerships with CDMOs for dedicated quality agreements.
Among North American packaging conglomerates, Berry Global Group Inc. and WestRock Company occupy positions anchored in multi-material conversion capabilities across plastic and aluminum formats. West Pharmaceutical Services, Inc. exemplifies the integrated elastomer specialist archetype with validated container-closure systems for biologic containment. AptarGroup, Inc. represents the precision-dosing technology vector through specialized closure mechanisms for ophthalmic and nasal drug delivery applications.
| Leading Market Players |
|---|
| Berry Global Group Inc. |
| West Pharmaceutical Services, Inc. |
| AptarGroup, Inc. |
| Amcor Plc |
| Gerresheimer AG |
| WestRock Company |
| Datwyler Sealing Solutions |
| Stevanato Group |
| Closure Systems International |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Gulf Coast petrochemical complexes shapes both feedstock availability and price floors for medical-grade polypropylene and halobutyl elastomer inputs. Scale concentration among converters with ISO 15378 certification creates tiered procurement access, locking uncertified regional suppliers out of biologic drug containment contracts.
Pricing Analysis
Certification level creates the primary spread across closure procurement tiers. Three-tier pricing structure across premium, standard, and economy levels separates validated elastomeric systems for biologics from oral solid dosage commodity caps. Pricing pressure stems from consolidated CDMO procurement compressing technical service margins into unit pricing. Generic oral solid dosage producers exhibit highest price sensitivity; monoclonal antibody sponsors prioritize supply assurance over cost optimization.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes disrupt just-in-time delivery of specialized elastomer formulations to Swiss and German biologic manufacturers. Medical-grade polypropylene supply concentrates in the US Gulf Coast, Germany, and Saudi Arabia; halobutyl rubber production centers on Russia, Singapore, and the United States. Feedstock volatility at naphtha crackers poses the dominant structural risk. Distribution runs through direct quality agreements with multinational drug sponsors and inventory consignment arrangements with large CDMOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of polymer science, pharmaceutical regulatory affairs, and high-speed automation engineering remains critically undersupplied, constraining expansion timelines for closure manufacturers and their drug-company customers alike.
For Market Incumbents: Consolidate elastomer compounding capabilities through backward integration into halobutyl rubber formulation to defend against emerging integrated specialists. Expand finishing capacity in Gujarat and Bavaria to capture CDMO consolidation-driven demand for sterile injectable supply assurance. Prioritize ISO 15378 certification maintenance as the competitive moat against uncertified regional converters. For New Entrants and Emerging Players: Anchor in precision-dosing closure technologies for ophthalmic and nasal biologics, the segment least penetrated by commodity screw-cap specialists. Target Indian pharmaceutical exporters in Hyderabad seeking Poison Prevention Packaging Act-compliant tamper-evident formats for US-bound generics. Lead with rapid qualification support and flexible minimum order quantities to outmaneuver tier-one incumbents on service velocity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated elastomer specialists with validated container-closure systems and long-term quality agreements with biologic drug sponsors. Acquisition candidates with captive compounding operations and parallel FDA-EU validation dossiers offer superior long-term viability. Monitor ECHA substance of very high concern designations for plasticizer restrictions as the inflection signal for compliant polymer reformulation specialists.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | Unlocks biologic drug containment contracts with 12-18 month qualification timelines under FDA and EU MDR standards. |
| Backward Integration into Elastomer Compounding | Captures margin from halobutyl rubber formulations and accelerates extractables testing protocol compliance. |
| Precision-Dosing Technology Development | Opens uncaptured value pools in ophthalmic and nasal biologics beyond commoditized screw-cap segments. |
| Indian Manufacturing License Expansion | Positions for CDSCO reforms and export-linked incentives attracting multinational regional sourcing operations. |
| Multilayer Co-Injection Molding Adoption | Compresses aluminum's barrier dominance with EVOH-interlayer structures for moisture-sensitive parenteral formulations. |
Study Parameters
Operator-level perspectives from regulatory affairs directors, pharmaceutical procurement managers, elastomer compounding specialists, and CDMO supply chain heads anchored the qualitative base. Primary interviews combined with secondary validation across FDA drug master file submissions, EMA packaging material registrations, ISO 15378 certification databases, and customs trade records. Bottom-up segment sizing and top-down market triangulation cross-verified volume and value estimates.
Sensitivity analysis tested forecast robustness across raw material price scenarios, regulatory timeline variations, and biologic drug approval trajectories. Segmentation modeling incorporated product type, material composition, closure mechanism, and end-user archetype dimensions across the projection horizon. CAGRs derived from weighted average growth contributions by segment, with inputs including pharmaceutical production indices, biologics pipeline data, and packaging material trade flows.
Underlying assumptions cover sustained FDA-EU regulatory alignment on extractables testing, with deviation risk concentrated in ECHA substance restriction amendments and nitrosamine impurity guidance enforcement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Dispensing Caps Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Canada Plastic Caps and Closures Market
Caps and Closures
Overcaps Market
Caps and Closures
Flapper Caps Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Foam End Caps Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Handheld Induction Cap Sealers Market