
 Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market | 2026-2036
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market Analytics
The EU Green Deal is repositioning capital allocation across pharmaceutical packaging supply chains as carbon accounting rules tighten for cleanroom operations and sterilization energy use. Gerresheimer AG leverages its integrated glass-forming and pharmaceutical tubing operations to control upstream material quality for prefilled syringe converters. Schott AG sustains technology leadership through proprietary borosilicate glass compositions engineered for hydrolytic resistance in biologic drug storage. Stevanato Group anchors southern European supply capacity with specialized capabilities in high-speed filling-line integration.
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment encompasses automated machinery systems designed to handle, sterilize, fill, seal, and label borosilicate glass primary containers for sterile injectable drugs, with equipment typically operating under ISO 5 cleanroom conditions and achieving fill accuracy within plus or minus one percent for high-value biologics. The primary commercial purpose centers on enabling aseptic processing of ready-to-use glass containment systems that eliminate terminal sterilization requirements for heat-sensitive drug products. Prefilled syringes command the dominant product position as chronic disease biologics and vaccine portfolios shift toward self-administration formats. Filling technology captures concentrated margin pools due to precision dosing requirements and validation complexity for high-potency compounds. Sealing systems face accelerating replacement demand as elastomer closure integrity standards tighten under revised EU GMP Annex 1 guidelines.
EMA pharmacovigilance requirements, REACH chemical registration mandates, and the EU MDR device traceability framework collectively shape equipment specifications by demanding serialized container tracking, extractables testing documentation, and validated cleaning protocols. The F-Gas Regulation further constrains sterilization technology choices by phasing down hydrofluorocarbon-based sterilants used in ethylene oxide alternatives. Stakeholders must monitor how the CSRD corporate sustainability reporting rules will extend carbon disclosure obligations to pharmaceutical packaging equipment procurement decisions.
Market Dynamics
The EU Green Deal is compressing capital cycles across pharmaceutical packaging as carbon accounting rules force cleanroom operators to revalidate sterilization energy profiles and equipment procurement criteria.
Growth Catalysts
- Biologics self-administration formats:Chronic disease therapies and vaccine portfolios are migrating toward prefilled syringe formats that eliminate multi-step reconstitution. Contract manufacturing organizations in Germany and Switzerland are scaling dedicated filling lines to capture this demand.
- F-Gas Regulation phase-down:The mandated reduction in hydrofluorocarbon-based sterilants is accelerating equipment replacement cycles as converters seek validated ethylene oxide alternatives. This regulatory pressure is pulling forward capital expenditure timelines.
- EMA pharmacovigilance serialization:Container-level track-and-trace mandates are requiring integrated vision inspection and labeling systems that link primary packaging to patient safety databases.
Market Restraints
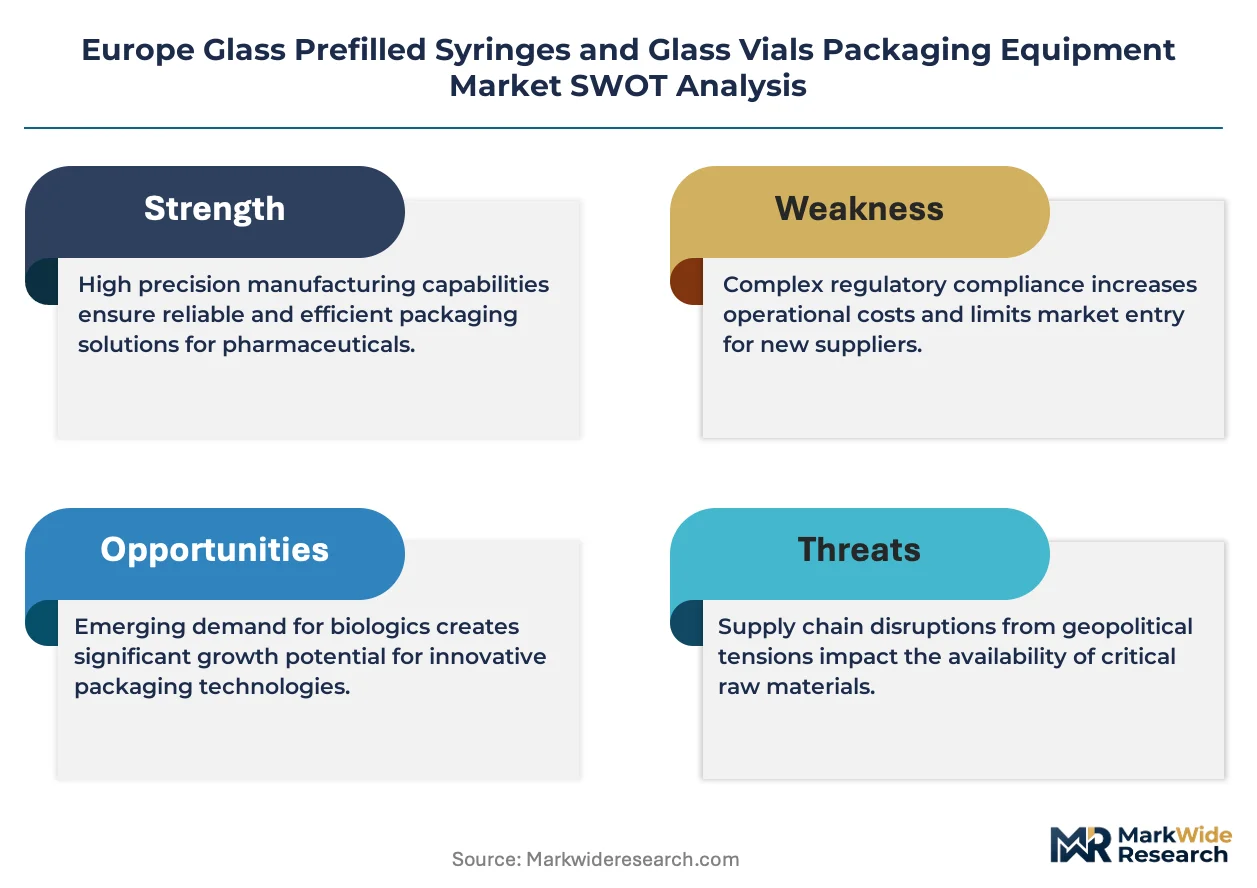
- Borosilicate glass supply concentration:Tubing supply for Type I pharmaceutical glass remains concentrated among a limited set of European suppliers, creating input vulnerability for equipment converters dependent on consistent dimensional specifications.
- REACH extractables documentation:Chemical registration mandates for elastomer closures and lubricants are extending qualification timelines and raising compliance costs for multi-component packaging systems.
- Terminal sterilization elimination:The shift toward aseptic processing for heat-sensitive biologics removes fallback sterilization options, tightening validation requirements and limiting equipment flexibility.
Strategic Opportunities
- High-speed filling-line integration:Southern European contract manufacturers are investing in turnkey systems that combine depyrogenation, filling, and sealing under single-source accountability to reduce validation complexity.
- CSRD carbon disclosure alignment:The Corporate Sustainability Reporting Directive is creating procurement preference for equipment suppliers with documented lifecycle emissions data, rewarding early movers in cleanroom energy optimization.
- Ready-to-use container formats:Pre-sterilized, pre-assembled syringe systems are displacing bulk component processing, opening margin pools for equipment capable of handling nested, siliconized containers without manual intervention.
Industry Challenges
- ISO 5 cleanroom engineering scarcity:Qualified technicians capable of validating laminar airflow patterns and particle monitoring systems are concentrated in established pharmaceutical clusters, constraining expansion timelines.
- EU MDR device traceability integration:Packaging equipment must now feed serialization data into medical device regulatory databases, requiring software architecture redesigns and extended qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market |
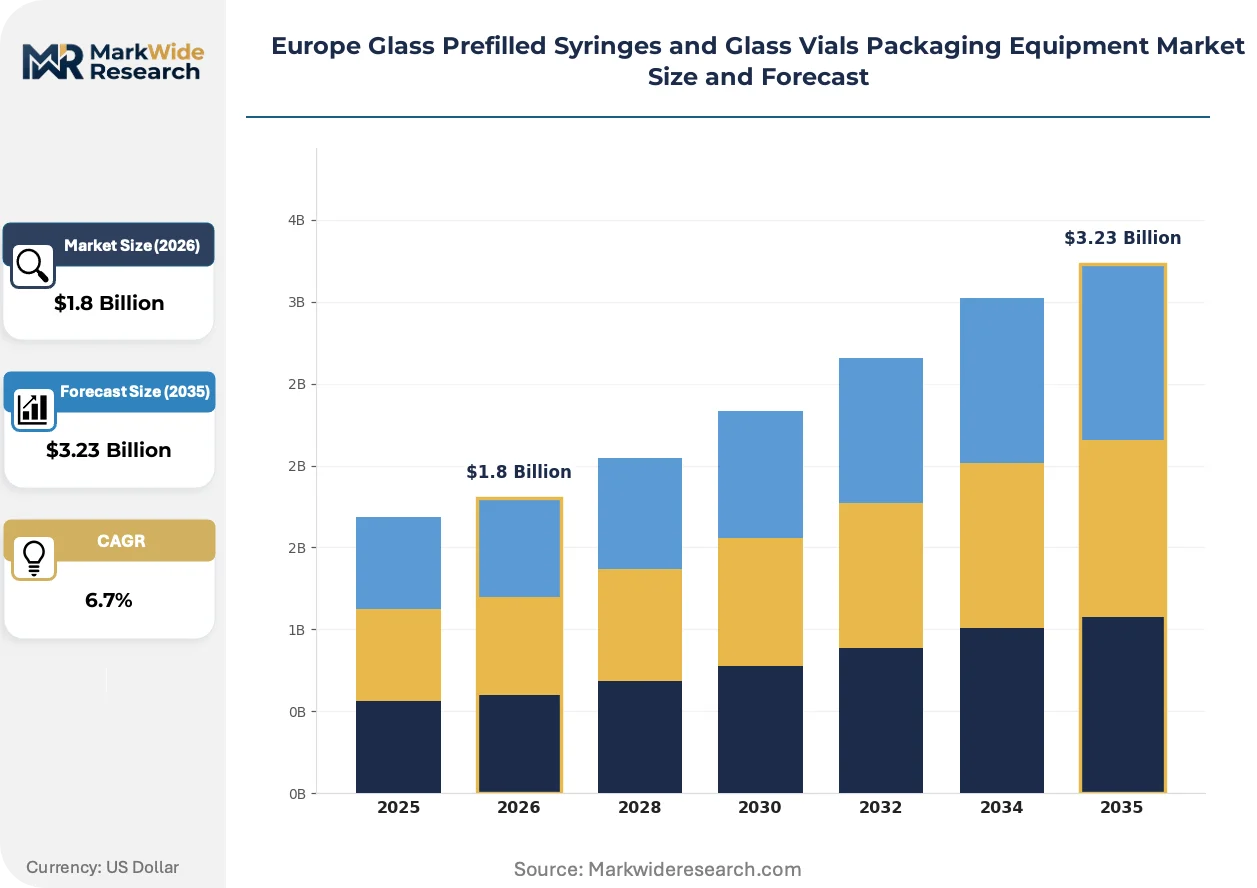
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefilled Syringes, Glass Vials, Cartridges, Ampoules Technology: Sterilization, Filling, Sealing, Labeling End User: Pharmaceuticals, Biotechnology, Research Labs, Healthcare Packaging Type: Single-dose, Multi-dose, Customized Packs, Others |
| Companies Covered | Gerresheimer AG, Schott AG, Becton Dickinson, Stevanato Group, West Pharmaceutical Services, SGD Pharma, DWK Life Sciences, Nipro Corporation, AptarGroup, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market Evolving Landscape
Automation architectures are converging with sustainability mandates as equipment buyers prioritize energy recovery systems and predictive maintenance platforms that reduce cleanroom downtime.
Single-use product contact surfaces are rewriting aseptic processing economics by eliminating steam-in-place validation cycles. Biopharmaceutical manufacturers in the Netherlands and Belgium are piloting these systems for multi-product facilities. The technology is compressing changeover timelines from days to hours while reducing water and energy consumption per batch.
The revised EU GMP Annex 1 is mandating continuous viable and non-viable particle monitoring with alarm-triggered line stoppage capabilities. Sterile injectable manufacturers are retrofitting filling isolators with real-time environmental monitoring systems. High-potency cytotoxic drug filling operations face the most stringent compliance timelines.
Contract development and manufacturing organizations are consolidating vendor relationships around equipment suppliers offering integrated qualification documentation. Buyers in Germany now require pre-validated software and mechanical interfaces that compress site acceptance testing. This concentration is visible in the Rhine-Main corridor where multi-national biopharma firms are standardizing on single-platform architectures.
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market Segmentation
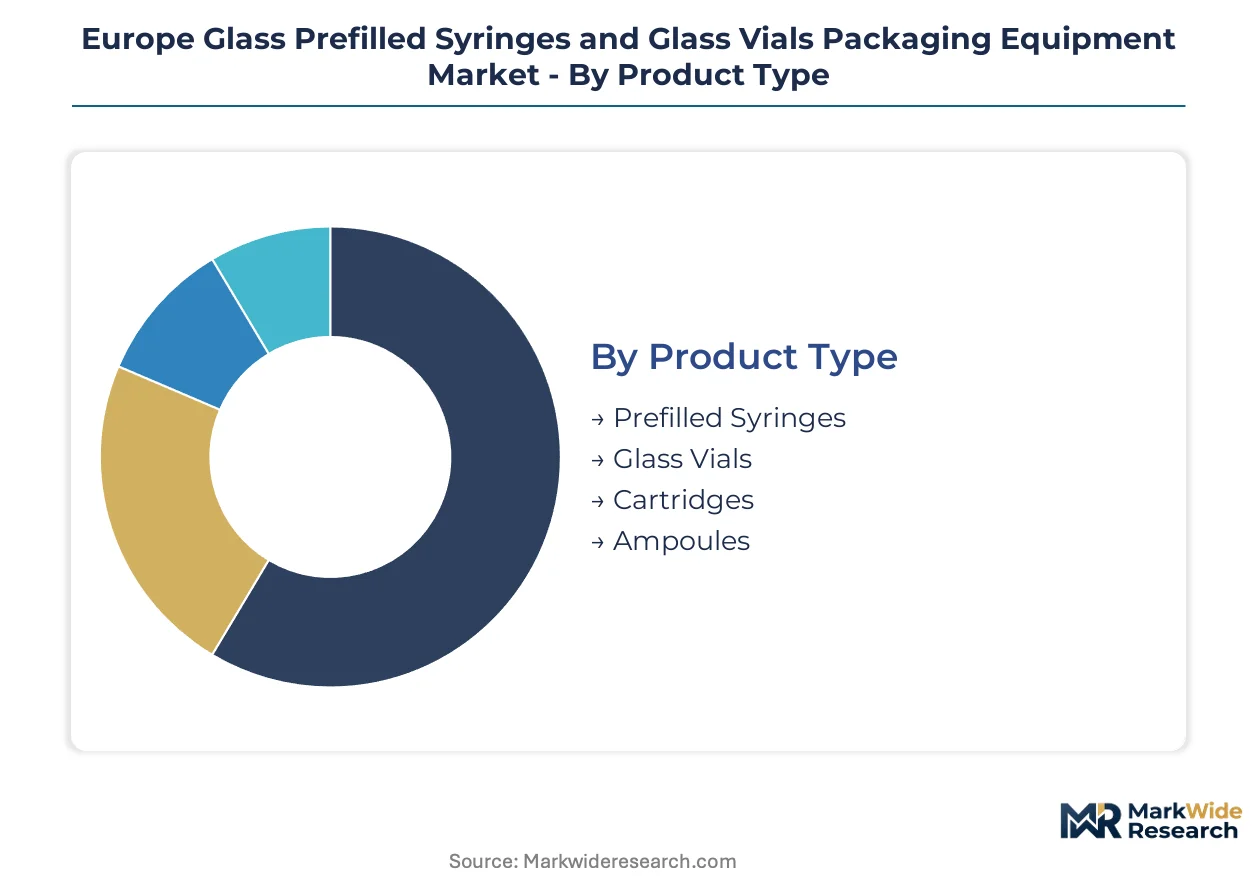
Segmentation in this market tracks how equipment specifications diverge across container formats, processing technologies, and end-use compliance requirements. Each dimension carries distinct validation protocols and capital intensity profiles that shape procurement decisions.
Product Type:
Standalone filling lines dominate high-volume biologics manufacturing, while integrated systems serve multi-format contract packaging operations.
- Prefilled Syringes:Borosilicate glass barrels with bonded needles or luer-lock fittings, engineered for hydrolytic resistance and silicone oil lubrication consistency. Demand clusters in Germany and Switzerland where self-administration biologics for diabetes and autoimmune conditions require ready-to-use formats. Stevanato Group and Schott AG supply the upstream tubing that constrains equipment converter flexibility.
- Glass Vials:Type I molded or tubular containers ranging from 2R to 50R volumes, processed through depyrogenation tunnels before aseptic filling. Vaccine and oncology injectable portfolios in Belgium and the Netherlands drive capacity expansion for nested, pre-sterilized vial formats.
- Cartridges:Cylindrical containers for pen-injector systems, requiring specialized plunger insertion and seal crimping modules.
- Ampoules:Single-use containers for emergency and anesthetic drugs, processed through flame-sealing equipment with lower automation integration.
Volume placements concentrate in Prefilled Syringes; the faster expansion belongs to Glass Vials as vaccine portfolios diversify.
Technology:
Cost tiering separates capital-intensive sterilization infrastructure from modular filling and labeling units that permit incremental capacity expansion.
- Sterilization:Dry-heat depyrogenation tunnels and ethylene oxide alternatives replacing hydrofluorocarbon systems under F-Gas Regulation mandates. High capital requirements and extended validation timelines create entry barriers for new equipment suppliers.
- Filling:Peristaltic and time-pressure dosing systems achieving plus or minus one percent accuracy for high-potency biologics. Swiss and German contract manufacturers prioritize turnkey isolator-integrated lines to compress site acceptance testing.
- Sealing:Elastomer stopper insertion and aluminum crimping systems facing replacement demand from revised EU GMP Annex 1 closure integrity standards.
- Labeling:Vision-inspection-integrated print-and-apply systems feeding EMA pharmacovigilance serialization databases.
Capital allocation concentrates in Filling technology; the steepest expansion trajectory belongs to Sterilization as F-Gas phase-down accelerates equipment replacement.
End User:
Customer type determines validation depth, with commercial pharmaceutical manufacturing requiring exhaustive qualification documentation versus research-scale flexibility.
- Pharmaceuticals:Multinational drug manufacturers and contract development organizations operating under EMA marketing authorization requirements. Rhine-Main corridor facilities standardize on single-platform architectures to reduce multi-site qualification burden.
- Biotechnology:Emerging and mid-cap biologics developers prioritizing single-use product contact surfaces and rapid changeover capabilities. Netherlands and Belgium pilot facilities lead adoption of disposable flow paths.
- Research Labs:Clinical trial material production requiring small-batch flexibility and abbreviated validation protocols.
- Healthcare:Hospital pharmacy compounding and regional fill-finish operations with limited automation integration.
Procurement volume concentrates in Pharmaceuticals; Biotechnology is gaining share fastest as pipeline biologics migrate toward dedicated manufacturing partnerships.
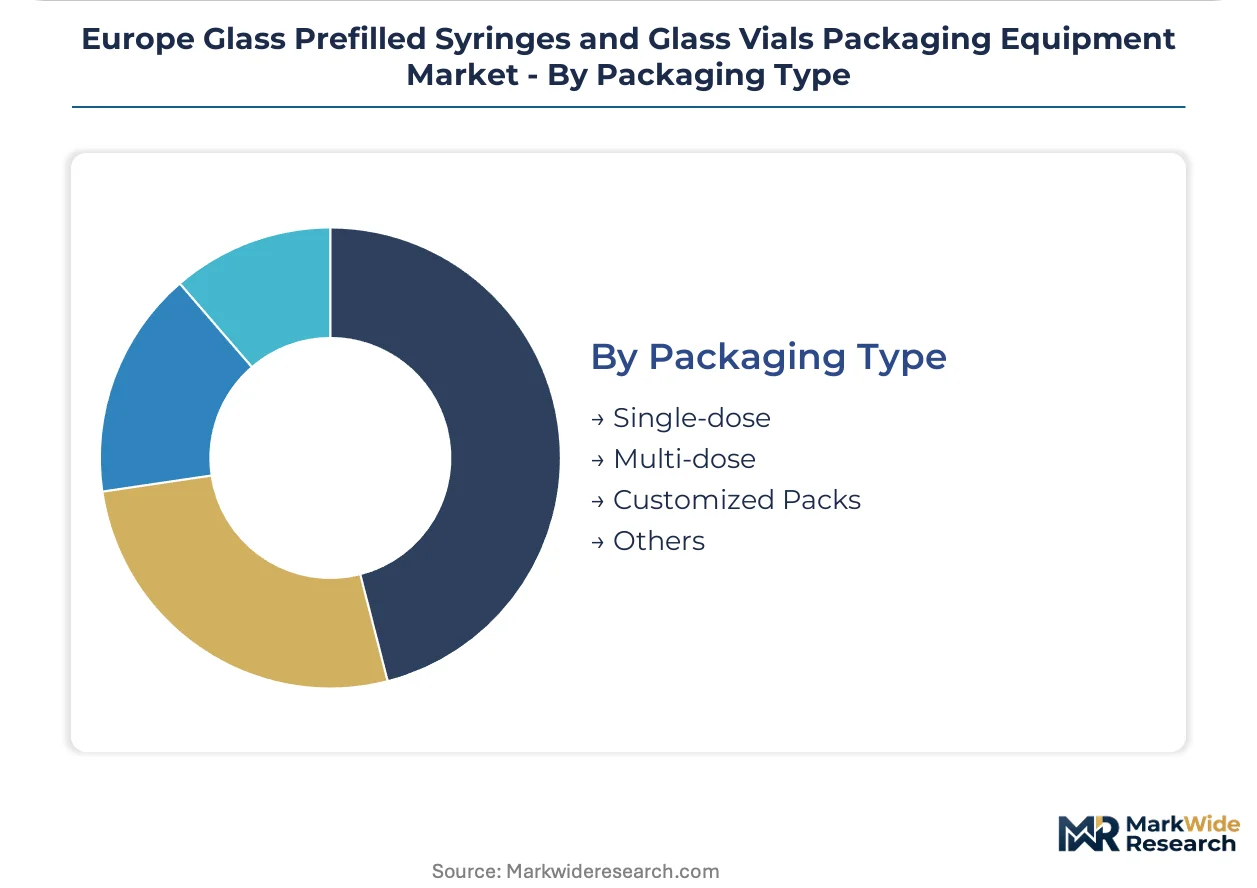
Packaging Type:
Application context drives format selection, with chronic disease therapies favoring patient-ready single-dose units versus institutional multi-dose configurations.
- Single-dose:Pre-filled, pre-assembled units eliminating reconstitution steps for self-administration. Demand from rheumatoid arthritis and multiple sclerosis biologics portfolios in Germany and France.
- Multi-dose:Vial configurations with preservative compatibility for hospital and clinic settings, requiring validated withdrawal techniques.
- Customized Packs:Patient-specific kits combining primary containers with ancillaries, processed through flexible line configurations.
- Others:Specialty formats including dual-chamber systems for lyophilized drug reconstitution.
Equipment deployments concentrate in Single-dose formats; Customized Packs are climbing the fastest as personalized medicine protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Switzerland concentrate equipment manufacturing capacity while demand spreads across Western European biopharma clusters. The Rhine-Main corridor anchors precision engineering supply chains for sterile injectable packaging systems.
Germany
Rheumatoid arthritis and diabetes biologics portfolios drive prefilled syringe line investments from contract manufacturers. EMA pharmacovigilance serialization mandates require integrated vision inspection systems feeding patient safety databases. The Rhine-Main corridor hosts multi-national biopharma firms standardizing on single-platform filling architectures to compress multi-site qualification burdens.
Switzerland
High-potency cytotoxic drug filling operations demand turnkey isolator-integrated lines with validated containment performance. Swissmedic device traceability requirements extend serialization obligations to primary packaging equipment interfaces. Basel and Zurich precision engineering clusters supply peristaltic dosing systems achieving sub-one-percent fill accuracy for biologics manufacturing.
Netherlands
Vaccine fill-finish capacity expansion accelerates adoption of nested, pre-sterilized vial formats for diversified immunization portfolios. REACH extractables documentation mandates extend qualification timelines for elastomer closure systems. Rotterdam and Utrecht biopharma pilot facilities lead single-use product contact surface adoption, compressing changeover timelines from days to hours.
Belgium
Oncology injectable manufacturing drives demand for high-speed depyrogenation tunnel integration with aseptic filling isolators. EU Green Deal carbon accounting rules force cleanroom operators to revalidate sterilization energy profiles and equipment procurement criteria. The Flanders biopharma corridor concentrates contract manufacturing capacity serving global vaccine and antibody-drug conjugate portfolios.
France
Multiple sclerosis and autoimmune biologics self-administration formats expand prefilled syringe equipment deployments. F-Gas Regulation phase-down mandates accelerate replacement of hydrofluorocarbon-based sterilants with validated ethylene oxide alternatives. The Paris-Saclay cluster anchors sterile injectable research-scale manufacturing requiring flexible line configurations for clinical trial material production.
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market Competitive Landscape
The competitive structure tilts toward integrated glass-forming and equipment specialists with captive upstream material control. Three archetypes dominate: precision engineering conglomerates with pharmaceutical tubing operations, specialized filling-line integrators with isolator expertise, and diversified packaging component suppliers extending into equipment services. Consolidation pressure intensifies as multi-national biopharma buyers reduce vendor counts to compress qualification overhead. Strategic partnerships between glass tubing producers and filling-line specialists are displacing arm's-length procurement relationships.
Among German-based precision engineering groups, Gerresheimer AG and Schott AG occupy positions anchored by proprietary borosilicate glass compositions and integrated forming operations. Stevanato Group represents the southern European specialist archetype with concentrated capability in high-speed filling-line integration. These three exemplify how upstream material control and downstream equipment integration are converging under single-source accountability models that reduce validation complexity for contract manufacturers.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| Becton Dickinson |
| Stevanato Group |
| West Pharmaceutical Services |
| SGD Pharma |
| DWK Life Sciences |
| Nipro Corporation |
| AptarGroup |
| Others |
Value Network & Pricing Analysis
Performance-tier divergence between isolator-integrated turnkey systems and standalone filling modules manifests in both capital expenditure spreads and supply chain sourcing patterns. Buyers in Germany and Switzerland absorb premium pricing for validated single-source accountability, while contract manufacturers in southern Europe optimize equipment procurement through modular component sourcing.
Pricing Analysis
Margin tightening in standard filling equipment reflects REACH extractables documentation burdens and extended qualification timelines. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 5 cleanroom certification grade and after-sales service bundling. Cost-down pressure on mid-tier configurations accelerates because biotechnology buyers prioritize rapid changeover capabilities over precision specifications. Pharmaceutical multinationals exhibit lowest price sensitivity; research-scale clinical trial material producers face acute budget constraints.
Supply Chain Analysis
Borosilicate glass tubing supply rests on German and Swiss specialty forming operations, with Italian component integrators feeding secondary equipment modules. Critical inputs include proprietary pharmaceutical-grade tubing, peristaltic pump dosing mechanisms, and vision inspection sensors. Single-source vulnerability concentrates in Type I glass formulations where Schott AG and Gerresheimer AG control dimensional specifications. Distribution runs through direct OEM relationships with multi-site qualification support, bypassing distributor markups for high-value isolator systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as single-use product contact surfaces displace stainless steel flow paths requiring steam-in-place validation cycles.
For Market Incumbents: Extend captive tubing supply advantages into turnkey isolator-integrated offerings that compress site acceptance testing timelines. Deepen backward integration into pre-sterilized nested container formats to capture ready-to-use demand from biologics contract manufacturers. Counter emerging single-use technology specialists by embedding predictive maintenance platforms that reduce cleanroom downtime below competing disposable system economics. For New Entrants and Emerging Players: Capture unmet demand in Netherlands and Belgium pilot facilities where biotechnology developers prioritize rapid changeover over legacy validation depth. Penetrate the mid-cap biologics segment through disposable flow path systems that eliminate steam-in-place cycles. Position through equipment-as-a-service models that transfer qualification burden from capital-constrained buyers. For Investors and Strategic Acquirers: Re-rating potential sits with precision engineering specialists possessing isolator containment expertise given EU GMP Annex 1 alarm-triggered line stoppage mandates. Long-term viability favors archetypes with documented lifecycle emissions data aligning with CSRD procurement preferences. Monitor F-Gas Regulation enforcement intensity as the inflection signal for sterilization equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Integrated Turnkey Systems | Compresses multi-site qualification burdens for Rhine-Main corridor biopharma firms. |
| Single-Use Product Contact Surfaces | Eliminates steam-in-place validation cycles for Netherlands and Belgium pilot facilities. |
| Predictive Maintenance Platforms | Reduces cleanroom downtime through real-time equipment performance monitoring. |
| Pre-Sterilized Nested Container Handling | Captures ready-to-use demand from self-administration biologics portfolios. |
| CSRD-Aligned Lifecycle Emissions Documentation | Creates procurement preference among carbon-accounting pharmaceutical buyers. |
Research Methodology
EMA regulatory filings, EU trade customs databases, and pharmaceutical equipment procurement records formed the secondary backbone for demand quantification. Primary interviews with sterile injectable manufacturing directors, cleanroom validation engineers, GMP compliance officers, and contract manufacturing procurement leads informed equipment specification trends. Bottom-up triangulation across country-level biopharma capacity expansion announcements and top-down reconciliation with EMA marketing authorization data established volume estimates.
Bottom-up modeling tracked prefilled syringe and glass vial line deployments by technology tier, end-user category, and national regulatory cluster across the projection horizon. Segmentation dimensions included container format, processing technology, and compliance requirement intensity. CAGRs derived from equipment replacement cycle analysis under F-Gas Regulation phase-down mandates and biologics self-administration format migration patterns. Industry-specific inputs incorporated REACH extractables documentation timeline extensions and EU MDR device traceability integration costs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal carbon accounting enforcement and borosilicate glass supply concentration disruptions. Forecasts reflect documented assumptions regarding regulatory implementation pace and cleanroom energy cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Injectable Drug Packaging Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market