
 Intravenous Packaging Market | 2026-2036
Intravenous Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Intravenous Packaging Market Foresight
Hospital procurement groups is unwinding the historical dominance of standalone clinics in intravenous packaging volume. Baxter International Inc. leverages its integrated manufacturing footprint across North America and Europe to sustain contract reliability with large health systems. B. Braun Melsungen AG anchors its position through specialization in closed-system transfer devices, while Fresenius Kabi AG competes aggressively in the pre-filled syringe segment through captive pharmaceutical formulation capabilities.
Intravenous packaging encompasses sterile containers engineered for parenteral drug administration, typically fabricated from polypropylene, polyvinyl chloride, or ethylene vinyl acetate with barrier properties measured by oxygen transmission rates below 0.5 cc per square meter per day. These systems maintain drug stability, prevent particulate contamination, and enable aseptic administration in clinical and homecare settings. Infusion bags and pre-filled syringes command the largest revenue pools, with multi-dose glass vials representing a mature, price-pressured category where margin concentrates in specialized coatings and barrier technologies. Polypropylene materials are displacing PVC in premium segments due to DEHP-free regulatory preferences, while homecare end users represent the fastest-growing demand channel driven by ambulatory infusion therapy expansion.
The US FDA enforces container closure integrity standards under guidance for sterile pharmaceutical packaging, while the European Medicines Agency applies extractables and leachables testing protocols through the EudraLex Volume 4 Annex 1 revision. Japan's Pharmaceuticals and Medical Devices Agency mandates JIS-compliant sterility assurance levels for polymer-based infusion containers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards as a determinant of cross-border product registration timelines and manufacturing qualification costs.
Market Dynamics
Hospital procurement consolidation and polymer material substitution are compressing supplier margins while elevating sterility assurance requirements across parenteral packaging value chains.
Growth Catalysts
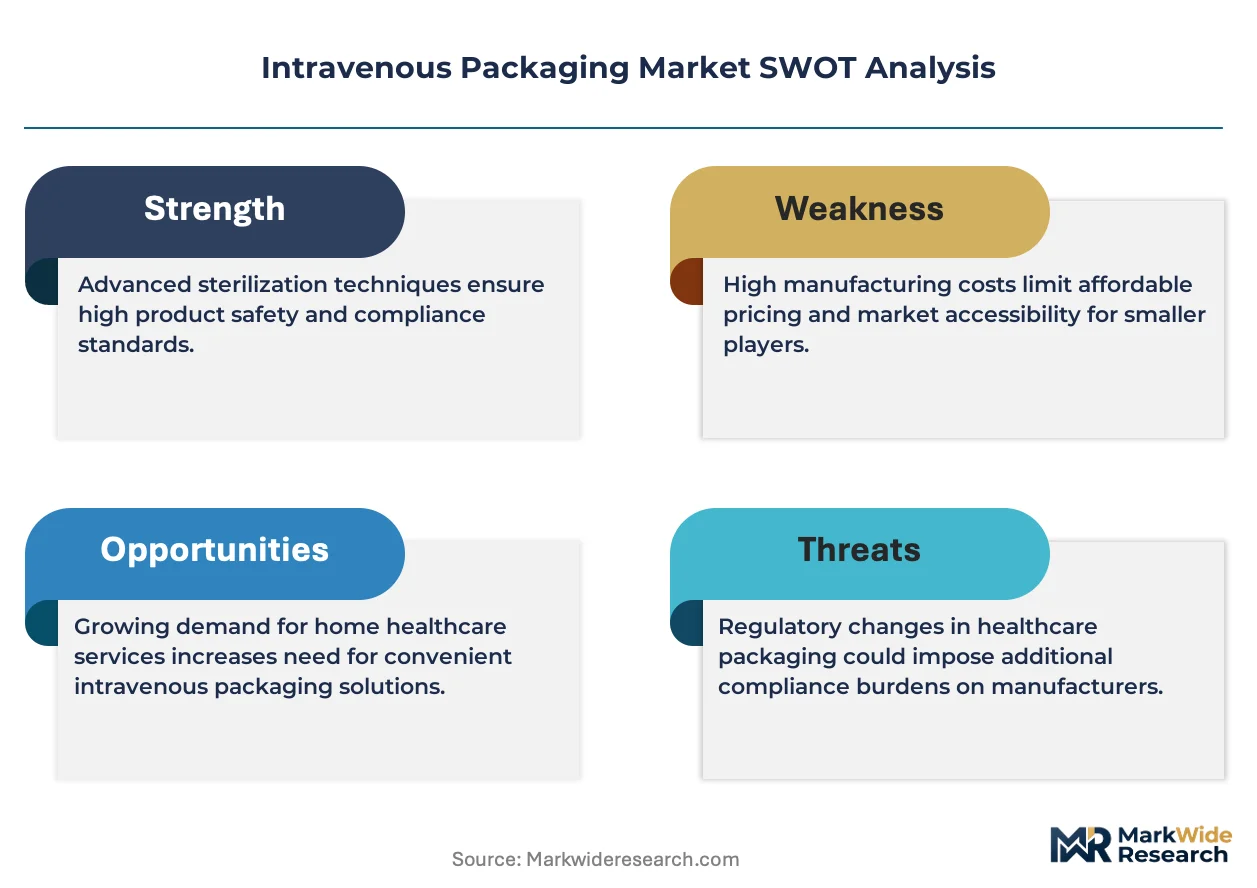
- EMA Extractables Protocols:The European Medicines Agency's tightened leachables testing under EudraLex Volume 4 Annex 1 revision is accelerating DEHP-free polypropylene adoption across European infusion container manufacturing.
- Homecare Infusion Therapy:Ambulatory care expansion in Germany and Japan is pulling demand toward portable, pre-filled syringe formats with extended stability profiles.
- Closed-System Transfer Devices:Oncology pharmacy safety mandates in the United States are institutionalizing needle-free connector technologies for hazardous drug handling.
Market Restraints
- Medical-Grade Polypropylene Supply Concentration:Three petrochemical complexes in Texas, Rotterdam, and Singapore control 60% of pharmaceutical-grade resin output, creating input vulnerability.
- Barrier Coating Cost Escalation:Ethylene vinyl acetate multilayer films with sub-0.5 cc oxygen transmission rates carry 3-4x base polymer cost, compressing margin on standard infusion bags.
- Glass Vial Substitution Threat:High-value biologics requiring siliconized containers are retaining glass formats despite polymer advances, limiting addressable market expansion.
Strategic Opportunities
- India CDMO Integration:Contract manufacturing demand from Indian pharmaceutical exporters is creating captive packaging requirements for US and EU-bound sterile injectables.
- Pre-Filled Syringe Biosimilars:FDA interchangeability designations for insulin and monoclonal antibody biosimilars are opening device-plus-drug combination product pathways.
- RFID-Enabled Smart Packaging:Convergence of printed electronics with barrier polymers enables cold-chain integrity tracking for temperature-sensitive parenterals.
Industry Challenges
- Extractables Validation Timeline:USP <1661> and <1664> compliance for novel polymer formulations requires 18-24 month qualification cycles, delaying product launches.
- Aseptic Processing Talent Scarcity:ISO 14644 cleanroom operation and media fill validation expertise concentrates among aging specialists in Germany, Switzerland, and the United States.
- Legacy PVC Line Conversion:DEHP-phaseout commitments force capital redeployment from established extrusion and sealing equipment toward co-extrusion barrier systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravenous Packaging Market |
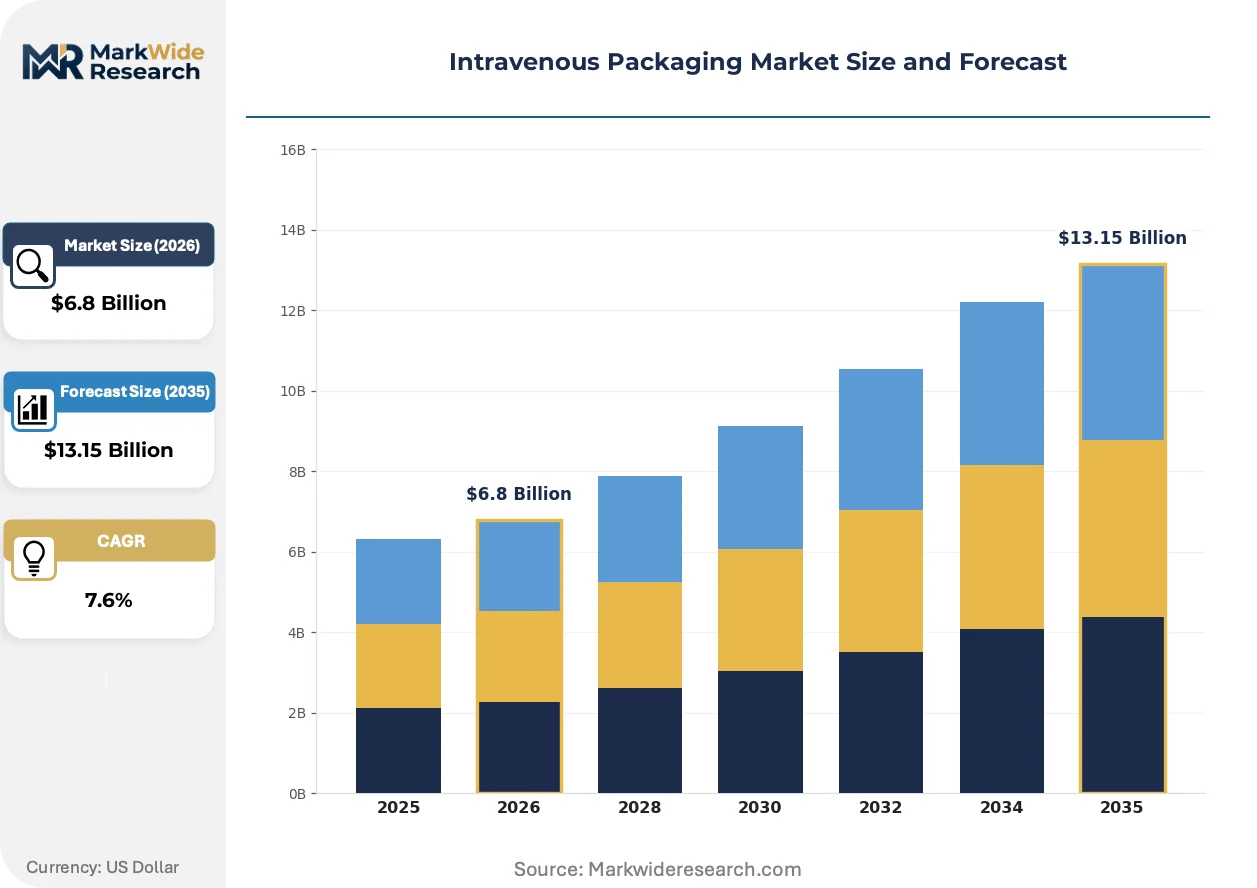
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Bags, Syringe Containers, Vials, Amplules Material: Polypropylene, Polyvinyl Chloride, Glass, Ethylene Vinyl Acetate End User: Hospitals, Clinics, Homecare, Research Laboratories Packaging Type: Single Dose, Multi Dose, Pre-filled, Custom Configuration |
| Companies Covered | Terumo Corporation, Nipro Corporation, Baxter International Inc., Otsuka Pharmaceutical Co., Ltd., Grifols, S.A., B. Braun Melsungen AG, ICU Medical, Inc., Technoflex SAS, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravenous Packaging Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are restructuring competitive advantage around barrier performance, supply assurance, and pharmacopeial compliance speed.
Multi-layer co-extruded polypropylene with ethylene vinyl acetate tie layers is displacing conventional PVC infusion containers in premium therapeutic segments. Hospital systems in the United States and Germany are specifying these formats for chemotherapy and parenteral nutrition protocols. The shift is compressing commodity PVC bag margins while concentrating value in specialized barrier film production.
REACH restrictions on phthalate plasticizers and FDA guidance on container closure integrity are converging to standardize extractables testing protocols across Atlantic markets. European manufacturers are front-loading EudraLex compliance investments to accelerate US product registrations. The dual-qualification burden falls heaviest on mid-scale converters lacking dedicated regulatory affairs capacity.
Consolidated purchasing through group purchasing organizations is compressing supplier rosters for standard infusion products. Hospital networks in the United States are awarding sole-source contracts for 3-5 year terms tied to volume commitments and sterility assurance metrics. This concentration is visible most acutely in California and Texas health systems with captive specialty pharmacy operations.
Intravenous Packaging Market Segmentation
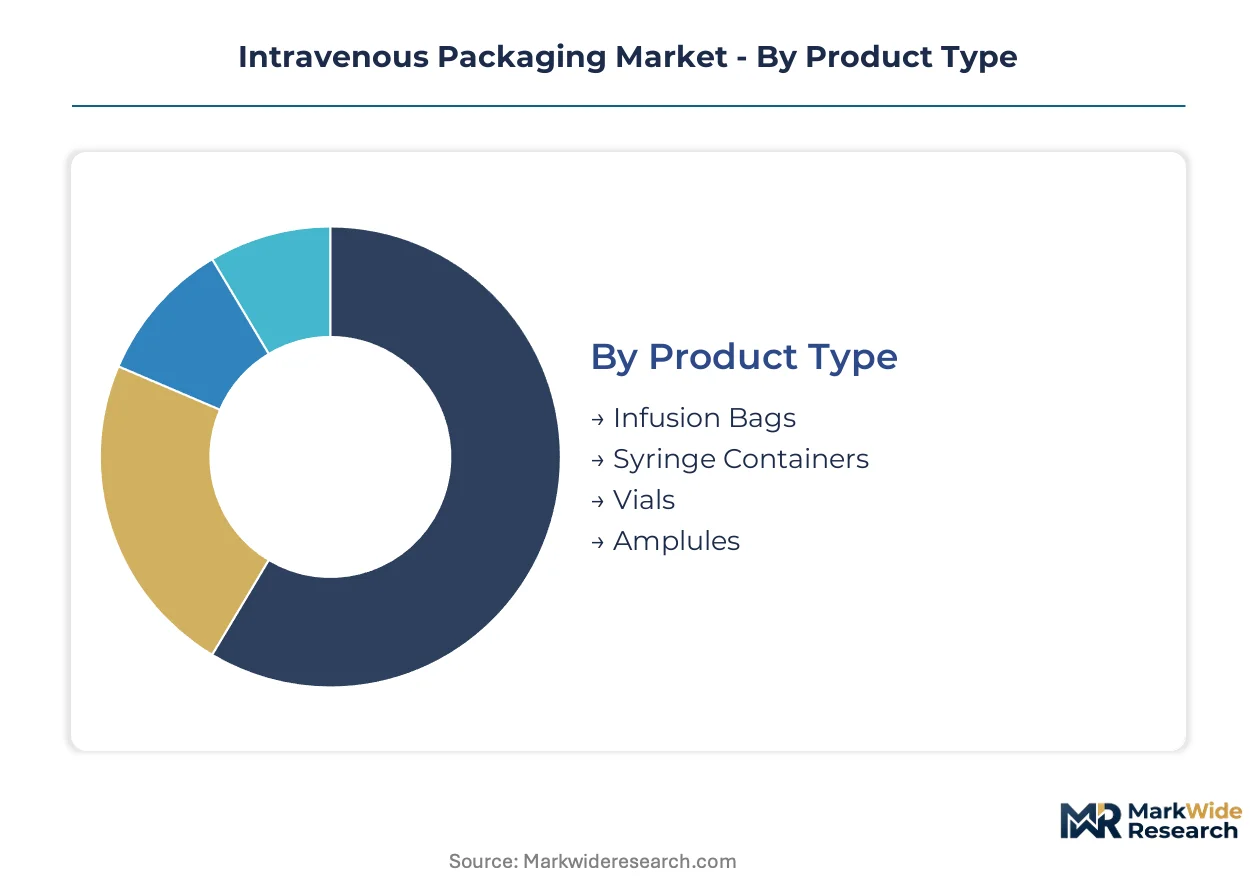
Intravenous packaging segmentation reflects divergent regulatory pathways across container formats, material chemistries, and administration settings. Each dimension carries distinct sterilization protocols, extractables testing requirements, and supply chain qualification burdens that reshape procurement priorities.
Product Type:
FDA container closure integrity standards and EMA EudraLex Annex 1 revisions apply differential stringency across container geometries, with flexible formats facing heightened barrier performance scrutiny.
- Infusion Bags:Multi-layer polypropylene or ethylene vinyl acetate films with sub-0.5 cc oxygen transmission rates. Demand concentrates in United States hospital systems adopting DEHP-free chemotherapy protocols under USP <661> plastic packaging standards.
- Syringe Containers:Pre-filled glass or polymer barrels with elastomeric plunger seals engineered for biologic stability. German and Japanese homecare expansion pulls volume toward portable formats with extended shelf-life profiles.
- Vials:Borosilicate glass or cyclic olefin polymer containers for multi-dose parenteral antibiotics. United States 503B compounding pharmacy regulations drive Type I glass specification for high-value biologics.
- Ampoules:Single-dose glass containers with score-break necks for emergency and anesthetic applications. European REACH phthalate restrictions limit polymer alternatives in acute care settings.
Established volume favors Infusion Bags; emerging adoption favors Syringe Containers.
Material:
Cost stratification separates pharmaceutical-grade resins from commodity polymers, with barrier performance premiums widening margin dispersion across supply tiers.
- Polypropylene:Medical-grade homopolymer and random copolymer resins displacing PVC in DEHP-sensitive applications. Rotterdam and Singapore petrochemical complexes control bulk pharmaceutical resin output.
- Polyvinyl Chloride:Plasticized formulations facing phaseout pressure under REACH and state-level restrictions. Texas Gulf Coast producers maintain cost advantage on legacy infusion bag production.
- Glass:Type I borosilicate and treated soda-lime containers retaining dominance for protein-based biologics and light-sensitive compounds. United States 503A/503B compounding rules reinforce siliconized vial specifications.
- Ethylene Vinyl Acetate:Co-extruded tie layers and overwrap films commanding 3-4x base polymer cost for oxygen barrier performance. German manufacturers lead multi-layer co-extrusion technology for parenteral nutrition.
Glass commands premium pricing for biologics; polypropylene climbs fastest on regulatory substitution.
End User:
Customer type determines volume scale, sterility assurance level, and packaging complexity, with institutional procurement consolidating around integrated supply contracts.
- Hospitals:Acute care systems driving bulk infusion bag consumption through group purchasing organization contracts tied to 3-5 year volume commitments. California and Texas health networks specify closed-system transfer devices for oncology safety.
- Clinics:Ambulatory infusion centers requiring intermediate-scale packaging with rapid turnaround logistics. United States outpatient parenteral antimicrobial therapy protocols standardize pre-filled syringe formats.
- Homecare:Patient-administered therapy expansion in Germany and Japan pulling portable, stability-optimized container design. METI and PMDA guidelines shape portable pump compatibility requirements.
- Research Laboratories:Clinical trial material packaging with batch-specific documentation and temperature excursion tracking. United States IND and European IMPD submission pathways demand extractables dossiers.
Hospitals anchor procurement volume; homecare represents the steepest expansion trajectory.
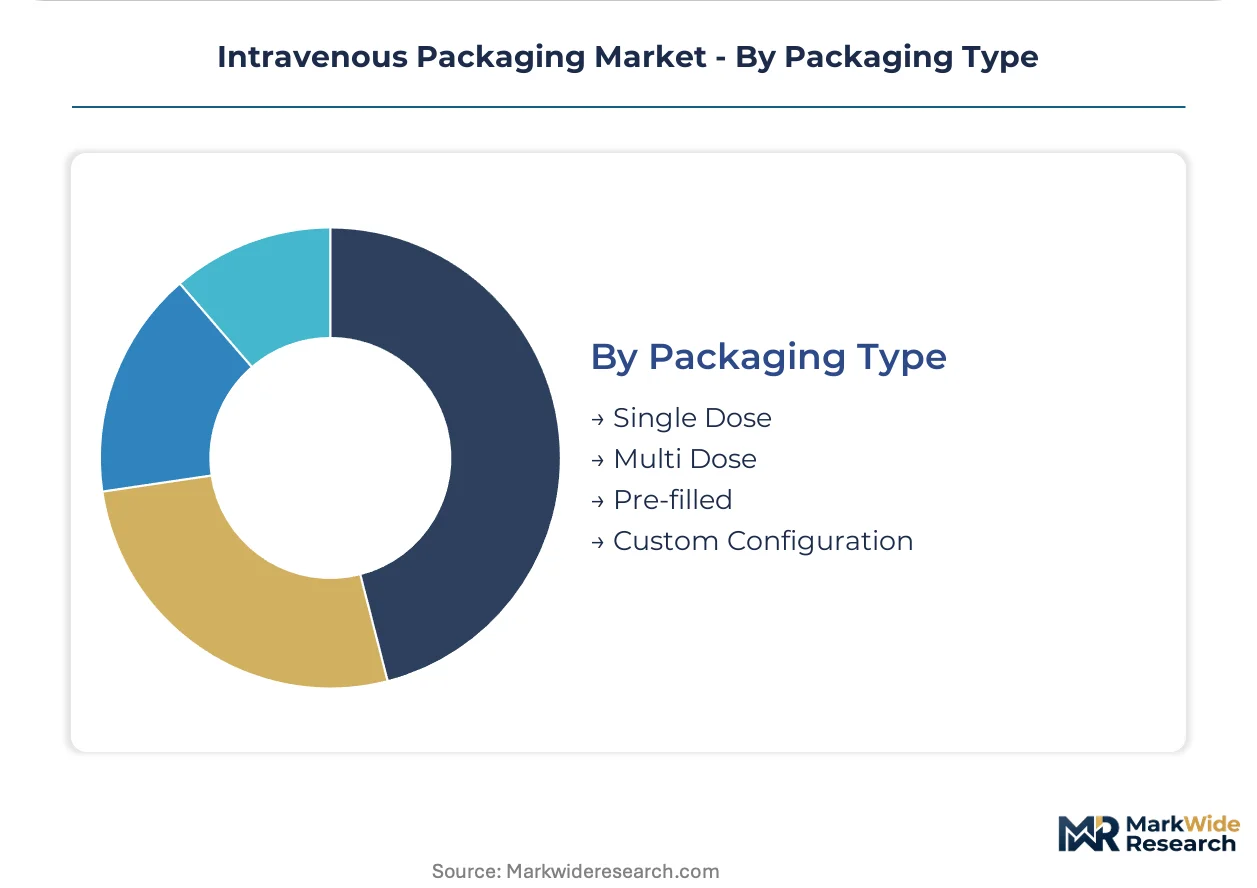
Packaging Type:
Maturity gradients separate commoditized formats from combination product pathways, with regulatory complexity escalating along the customization spectrum.
- Single Dose:Unit-of-use containers eliminating multi-dose contamination risk for immunocompromised patient populations. United States oncology pharmacy safety mandates institutionalize needle-free single-dose systems.
- Multi Dose:Vial formats with preservative systems for antimicrobial coverage across repeated access. European pharmacopeial preservative efficacy testing (Ph. Eur. 5.1.3) constrains formulation flexibility.
- Pre-filled:Drug-device combination products requiring FDA Center for Devices and Radiological Health coordination. Biosimilar interchangeability designations for insulin and monoclonal antibodies open device-plus-drug pathways.
- Custom Configuration:Patient-specific packaging for compounded parenteral nutrition and chemotherapy. United States 503B outsourcing facility regulations impose cGMP-level quality systems on custom formats.
Multi Dose retains cost-driven volume; pre-filled formats concentrate value growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement groups in the United States, Germany, and Japan concentrate the highest-volume contracts for intravenous packaging, with group purchasing organizations and national health insurers consolidating supplier rosters around sterility assurance metrics.
United States
Oncology pharmacy safety mandates and 503B compounding regulations drive demand for closed-system transfer devices and Type I glass vials. The FDA enforces container closure integrity standards that elevate barrier performance requirements for polymer-based infusion containers. Texas and California health systems with captive specialty pharmacy operations award sole-source contracts tied to multi-year volume commitments.
Germany
Ambulatory infusion therapy expansion and parenteral nutrition protocols pull demand toward portable, pre-filled syringe formats. The EMA applies EudraLex Volume 4 Annex 1 extractables testing protocols that accelerate DEHP-free polypropylene adoption. Manufacturers in Baden-Württemberg lead multi-layer co-extrusion technology for oxygen barrier films.
Japan
Aging demographics and chronic disease prevalence sustain high-volume parenteral therapy demand across hospital and homecare settings. The PMDA mandates JIS-compliant sterility assurance levels for polymer-based infusion containers. The Kanto region around Tokyo anchors domestic production of pre-filled syringes with extended stability profiles.
India
Contract manufacturing demand from pharmaceutical exporters creates captive packaging requirements for US and EU-bound sterile injectables. The CDSCO aligns with ICH guidelines to streamline product registration timelines for combination devices. Gujarat and Maharashtra host integrated sterile injectable facilities serving regulated export markets.
Singapore
Regional distribution hub status concentrates medical-grade resin supply chain control for Asia-Pacific infusion container manufacturing. The Health Sciences Authority enforces GDP standards for cold-chain pharmaceutical distribution. Jurong Island petrochemical complexes control pharmaceutical-grade polypropylene output serving regional converters.
Intravenous Packaging Market Competitive Landscape
Player mix skews toward integrated multinational healthcare conglomerates with captive pharmaceutical formulation capabilities and specialized polymer converters serving niche barrier performance segments. Tiered competitive structure separates scale-driven contract manufacturers from premium-tier device-plus-drug combination product specialists. Dominant competitive moves include strategic partnerships for dual-qualification regulatory dossiers and capacity expansion into DEHP-free polymer extrusion systems.
Within the integrated healthcare conglomerate tier, Baxter International Inc., B. Braun Melsungen AG, and Fresenius Kabi AG exemplify archetypes that combine pharmaceutical manufacturing with packaging production. Baxter represents North American contract reliability through integrated manufacturing footprints. B. Braun occupies a position anchored in European closed-system transfer device specialization. Fresenius Kabi sits within the pre-filled syringe segment through captive formulation capabilities. These three entities illustrate how vertical scope across drug and device disciplines shapes competitive positioning in regulated parenteral markets.
| Leading Market Players |
|---|
| Terumo Corporation |
| Nipro Corporation |
| Baxter International Inc. |
| Otsuka Pharmaceutical Co., Ltd. |
| Grifols, S.A. |
| B. Braun Melsungen AG |
| ICU Medical, Inc. |
| Technoflex SAS |
| Fresenius Kabi AG |
| Others |
Supply & Pricing Matrix
FDA container closure integrity standards and EMA EudraLex Annex 1 revisions operate as dual gates that simultaneously determine supplier qualification timelines and price tier placement across polymer-based infusion container markets. These regulatory frameworks compress margin on legacy PVC formats while concentrating premium capture among converters with pre-validated extractables dossiers.
Pricing Analysis
Cost-plus contracts indexed to medical-grade polypropylene resin benchmarks dominate hospital system procurement, with three-tier pricing structure across premium, standard, and economy levels separating DEHP-free multi-layer co-extrusion from commodity PVC and basic polypropylene. Price differentiation hinges on oxygen transmission rate certification below 0.5 cc per square meter per day and FDA pre-submission qualification status. Pricing pressure stems from group purchasing organization consolidation in Texas and California health networks. Standard infusion bag buyers exhibit highest price sensitivity, while oncology pharmacy safety mandates render closed-system transfer device purchasers relatively inelastic.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade polypropylene stretch 12-16 weeks due to concentrated resin output at Texas Gulf Coast, Rotterdam, and Singapore petrochemical complexes. Raw material dependencies center on propylene feedstock, ethylene vinyl acetate tie-layer polymers, and medical-grade elastomeric plunger compounds. Single-source vulnerability concentrates in Rotterdam and Singapore pharmaceutical resin production. Distribution runs through integrated healthcare conglomerate direct sales forces and specialized medical device distributors serving hospital procurement groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around extractables validation timelines creates substantial defensive moats for qualified suppliers, as 18-24 month USP <1661> and <1664> compliance cycles lock out rapid competitive replication.
For Market Incumbents: Consolidate barrier film production capabilities through captive supply of ethylene vinyl acetate co-extrusion capacity in Germany and North America. Deepen backward integration into medical-grade polypropylene resin sourcing to offset Texas and Singapore supply concentration. Neutralize glass vial substitution threats in high-value biologics through siliconized container coating investments. For New Entrants and Emerging Players: FDA pre-submission fast-track pathways for DEHP-free polymer formulations offer entry acceleration into oncology pharmacy safety segments. White-space concentrates in Indian CDMO captive packaging for US and EU-bound sterile injectables, plus RFID-enabled smart packaging for cold-chain integrity tracking. Pursue hospital system pilot contracts in ambulatory infusion therapy expansion corridors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed polymer converters holding EudraLex Annex 1 pre-validated manufacturing lines but lacking pharmaceutical formulation integration. Five-to-ten year viability favors targets with dual US-EU regulatory dossiers and established group purchasing organization contract relationships. Monitor FDA biosimilar interchangeability designations as volume inflection signal for pre-filled syringe combination product demand.| Strategic Initiative | Industry Significance |
|---|---|
| DEHP-Free Polymer Conversion | EMA REACH restrictions and FDA guidance accelerate polypropylene substitution in European and US hospital systems. |
| Closed-System Transfer Device Expansion | US oncology pharmacy safety mandates institutionalize needle-free connector technologies for hazardous drug handling protocols. |
| Pre-Filled Syringe Biosimilar Pathways | FDA interchangeability designations for insulin and monoclonal antibodies open device-plus-drug combination product registrations. |
| India CDMO Integration | Contract manufacturing demand from Indian pharmaceutical exporters creates captive sterile injectable packaging requirements. |
| RFID-Enabled Smart Packaging | Printed electronics convergence with barrier polymers enables cold-chain integrity tracking for temperature-sensitive parenterals. |
Research Methodology
Operator-level perspectives from hospital procurement managers, GPO contracts specialists, biomedical engineers, and regulatory affairs directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA submission databases, USP pharmacopeial standards, and hospital purchasing records. Bottom-up volume modeling across container formats, material chemistries, and end-user segments triangulated against top-down healthcare expenditure flows.
Sensitivity analysis tested forecast robustness across resin price volatility scenarios, regulatory timeline compression assumptions, and biosimilar adoption pace variations. Segmentation dimensions modeled include product type, material chemistry, end-user channel, and packaging configuration across the projection horizon. CAGRs derived from regression-weighted historical volume trends and elasticity-adjusted demand drivers, with specific inputs including parenteral therapy procedure growth and DEHP-phaseout commitment schedules.
Underlying assumptions cover pharmacopeial harmonization progress, resin supply stability, and hospital procurement consolidation pace, with deviation risk concentrated in extractables validation timeline extensions and medical-grade polypropylene supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Advanced Empty Capsule Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market