
 Polyp Biopsy Market | 2026-2036
Polyp Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Polyp Biopsy Market Outlook
Software-enabled pathology analytics is rebalancing how biopsy services are contracted and monetized across health systems. Olympus Corporation leverages its endoscopy-installation base to bundle digital pathology subscriptions with hardware refreshes. Boston Scientific Corporation anchors its position through R&D intensity in single-use forceps design, while Medtronic competes via backward integration into specimen-handling logistics.
Polyp biopsy involves the extraction of mucosal tissue specimens from colorectal or gastrointestinal polyps using flexible endoscopic instruments, typically cold or hot forceps ranging from 1.8 mm to 2.4 mm jaw diameter, with samples preserved in formalin for histopathological grading of dysplasia. The procedure serves primary industrial purpose in early-stage colorectal cancer detection and surveillance protocol compliance. Endoscopic forceps command the largest product-type margin pool due to disposable-unit economics and infection-control mandates, while screening procedures represent the fastest-growing application segment as population-health programs expand. Hospitals absorb the majority of end-user volume through centralized procurement of capital equipment and consumable contracts.
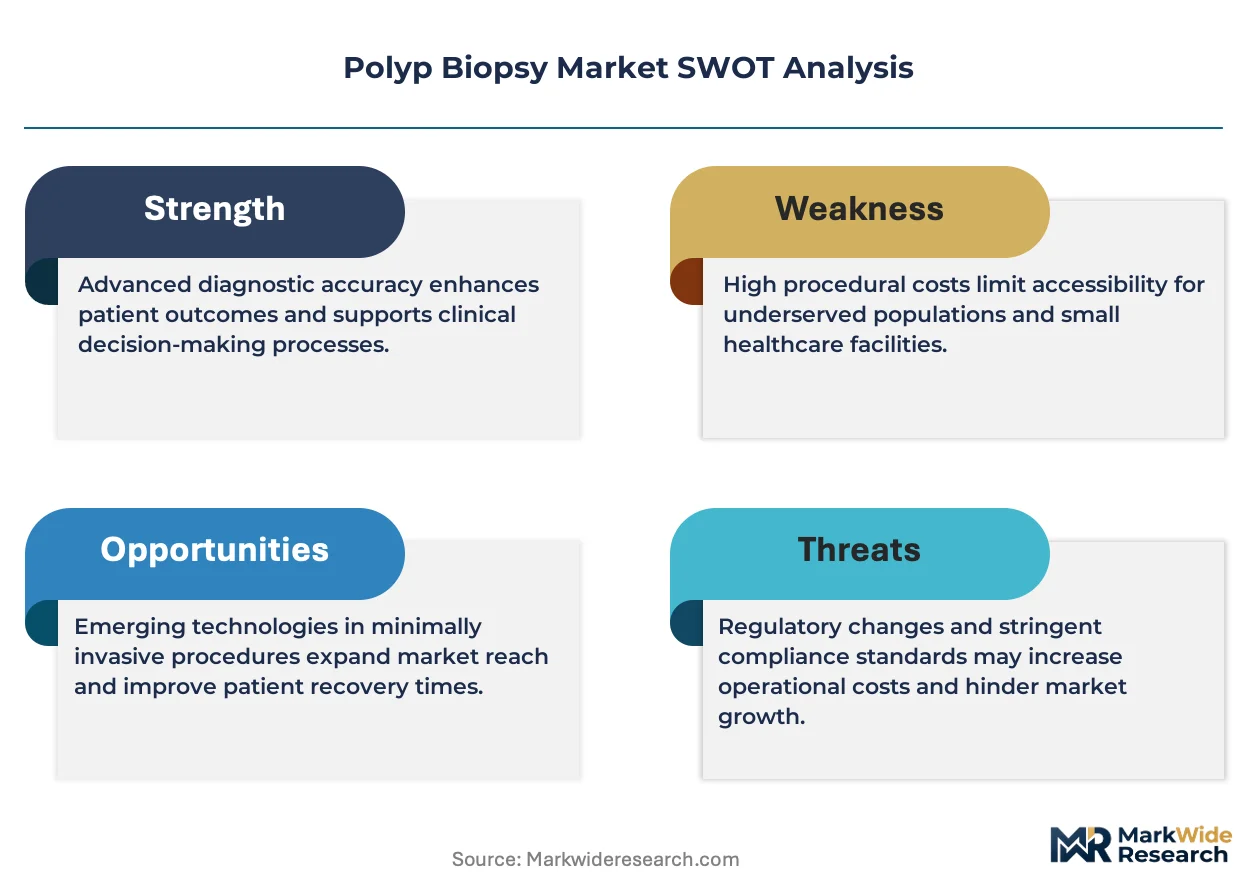
FDA premarket notification requirements under 510(k) govern forceps and needle designations, while HIPAA frameworks shape digital pathology data transmission standards and cloud-storage vendor qualifications. The EU MDR and CE marking requirements impose additional clinical-evidence burdens on manufacturers seeking European market access. Stakeholders must monitor evolving CMS coverage determinations for AI-assisted polyp characterization to anticipate reimbursement shifts that could restructure competitive economics.
Market Dynamics
Medicare reimbursement protocols are compressing procedure economics while FDA guidance on colorectal cancer risk stratification forces health systems to upgrade diagnostic workflows. This dual pressure is reshaping vendor contracting structures and capital allocation priorities across hospital procurement departments.
Growth Catalysts
- CMS Coverage Expansion:Medicare reimbursement for minimally invasive diagnostic protocols incentivizes hospital adoption of disposable forceps systems over reusable alternatives. United States health systems accelerate screening program expansion.
- Population Health Mandates:Colorectal cancer surveillance protocols in employer-sponsored wellness programs drive demand for compliant biopsy services. Large self-insured employers contract directly with diagnostic networks.
- AI-Assisted Characterization:Machine learning algorithms for polyp classification reduce pathologist review time. Hospital laboratories integrate these tools to meet throughput targets without proportional staffing increases.
Market Restraints
- Nitinol Supply Concentration:Forceps jaw manufacturing depends on nitinol wire sourced from a limited supplier base in Japan and Germany. Input cost volatility constrains margin flexibility for disposable instrument producers.
- EU MDR Clinical Evidence Burden:European market access now requires expanded clinical trials for Class IIa forceps designations. Smaller manufacturers delay CE marking submissions due to documentation costs.
- Capsule Endoscopy Substitution:Non-invasive colorectal screening alternatives reduce biopsy referral volumes in asymptomatic populations. Diagnostic chains report modest procedure volume erosion in preventive care segments.
Strategic Opportunities
- Rural Hospital Penetration:Critical access hospitals in the United States remain undersupplied with advanced endoscopy suites. Mobile diagnostic service providers contract with these facilities on per-procedure terms.
- Cloud Pathology Integration:Convergence of digital slide scanning with telepathology platforms enables centralized diagnostic networks. Regional health systems consolidate histopathology review across dispersed sites.
- IRA Preventive Care Incentives:Inflation Reduction Act provisions expand zero-cost screening coverage for Medicare beneficiaries. Federally qualified health centers upgrade endoscopic capacity to capture this volume.
Industry Challenges
- Gastroenterologist Training Pipeline:Fellowship program output trails demand for advanced endoscopists capable of complex polyp resection. Health systems compete for limited specialist placement through recruitment incentives.
- Legacy PACS Integration:Digital pathology platforms face interoperability friction with existing hospital imaging archives. IT departments allocate substantial integration resources to achieve seamless workflow connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyp Biopsy Market |
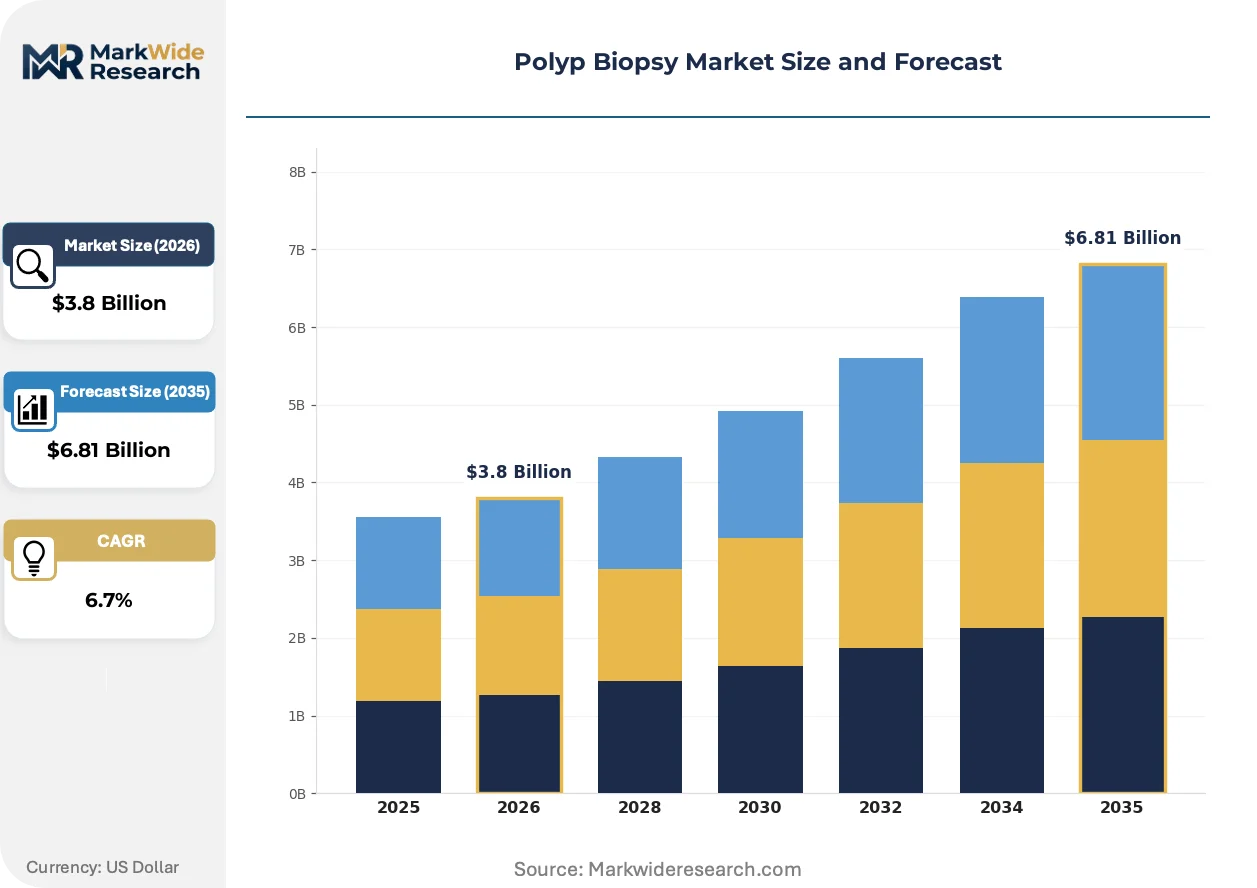
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopic Forceps, Biopsy Needles, Devices, Accessories Application: Colon Cancer Detection, Gastrointestinal Disorders, Screening Procedures, Diagnostic Tests End User: Hospitals, Diagnostic Laboratories, Outpatient Clinics, Research Institutions Distribution Channel: Online Sales, Direct Sales, Retail Pharmacies, Medical Equipment Distributors |
| Companies Covered | Cardinal Health, Inc., Olympus Corporation, Boston Scientific Corporation, Medtronic, Cook Medical, Fujifilm Holdings Corporation, Hologic, Inc., C.R. Bard, Inc., INRAD Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyp Biopsy Market Strategic Shifts
Software-enabled analytics and single-use instrument design are converging to transform how biopsy services are delivered and monetized. Three developments dominate competitive positioning.
Disposable electrocautery forceps is modularizing procedure workflows by separating tissue acquisition from energy delivery functions. Ambulatory surgery centers adopt these instruments to eliminate reprocessing bottlenecks and reduce infection control liability. The technology is modularizing capital-light service models that bypass traditional hospital-based diagnostic pathways.
FDA premarket notification pathways for AI-assisted polyp characterization are tightening evidentiary requirements for 510(k) clearance. Manufacturers must now submit larger validation datasets demonstrating diagnostic equivalence to pathologist review. Gastroenterology device segments with software components face extended regulatory timelines and elevated clinical trial costs.
Health system procurement departments are consolidating vendor relationships through enterprise-wide consumable contracts rather than department-level purchasing. Group purchasing organizations negotiate multi-year agreements bundling forceps, retrieval devices, and pathology services. This concentration is most visible in integrated delivery networks across the southeastern United States, where centralized sourcing reduces unit costs through volume commitments.
Polyp Biopsy Market Segmentation
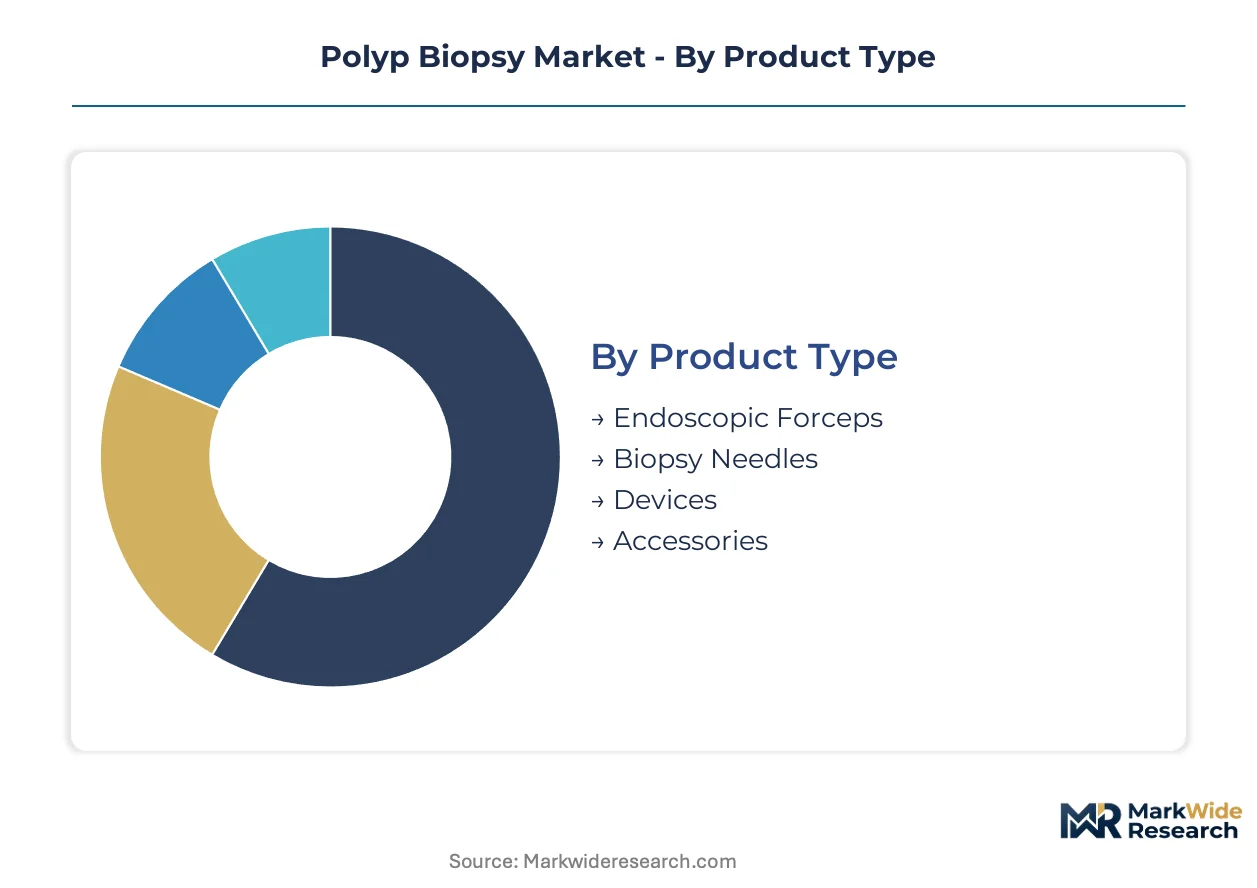
Polyp biopsy market segmentation reveals how procurement economics, clinical workflow requirements, and regulatory compliance reshape purchasing decisions across health systems. Each dimension exposes distinct margin structures and vendor contracting leverage points that determine competitive positioning.
Product Type:
Customization intensity spans from commodity accessories to precision-engineered forceps with proprietary jaw geometries and nitinol actuation mechanisms.
- Endoscopic Forceps:Disposable instruments with 1.8 mm to 2.4 mm jaw diameters dominate procurement volume through infection-control mandates and Medicare reimbursement favoring single-use protocols. Cold and hot variants segment further by electrocautery integration, with United States hospitals driving specification standards through group purchasing organization consolidation.
- Biopsy Needles:Fine-needle aspiration and core biopsy designs serve lesion sampling where forceps access proves anatomically constrained. EU MDR clinical evidence requirements now delay CE marking for new needle geometries, compressing European launch windows relative to FDA 510(k) pathways.
- Devices:Integrated retrieval systems and specimen collection containers standardize handling logistics across laboratory networks.
- Accessories:Irrigation tubing, bite blocks, and mouth guards complete procedure kits without commanding independent procurement decisions.
Leading the category by volume: Endoscopic Forceps. Growing fastest: Biopsy Needles.
Application:
Reimbursement intensity and clinical urgency create four distinct demand tiers with diverging price elasticity and vendor stickiness.
- Colon Cancer Detection:Diagnostic confirmation of malignancy drives highest-value pathology workflows with mandatory histopathological grading. United States screening guidelines from the US Preventive Services Task Force mandate surveillance intervals that sustain recurring biopsy volume.
- Screening Procedures:Asymptomatic population surveillance expands fastest through employer wellness programs and IRA zero-cost coverage provisions. Federally qualified health centers capture this volume through capacity upgrades.
- Gastrointestinal Disorders:Inflammatory bowel disease monitoring and celiac diagnosis sustain steady procedural demand without screening-program volatility.
- Diagnostic Tests:Follow-up of abnormal imaging findings completes the clinical pathway with lower per-procedure reimbursement.
Screening Procedures command the steepest expansion trajectory as preventive care mandates broaden eligible populations.
End User:
Capital deployment capacity and procurement sophistication stratify customers from centralized hospital systems to dispersed research operations.
- Hospitals:Integrated delivery networks leverage enterprise-wide consumable contracts bundling forceps, retrieval devices, and pathology services. Southeastern United States health systems demonstrate this concentration through multi-year vendor commitments.
- Diagnostic Laboratories:Regional networks consolidate histopathology review across dispersed sites using cloud-enabled digital slide scanning and telepathology platforms.
- Outpatient Clinics:Ambulatory surgery centers adopt modular capital-light models with disposable electrocautery forceps eliminating reprocessing infrastructure.
- Research Institutions:Academic medical centers drive protocol innovation with lower volume but higher specification influence over commercial product roadmaps.
Hospitals absorb majority volume through centralized procurement. Diagnostic Laboratories expand most quickly via network consolidation.
Distribution Channel:
Channel economics reflect inventory carrying costs, technical support requirements, and contract negotiation leverage across customer segments.
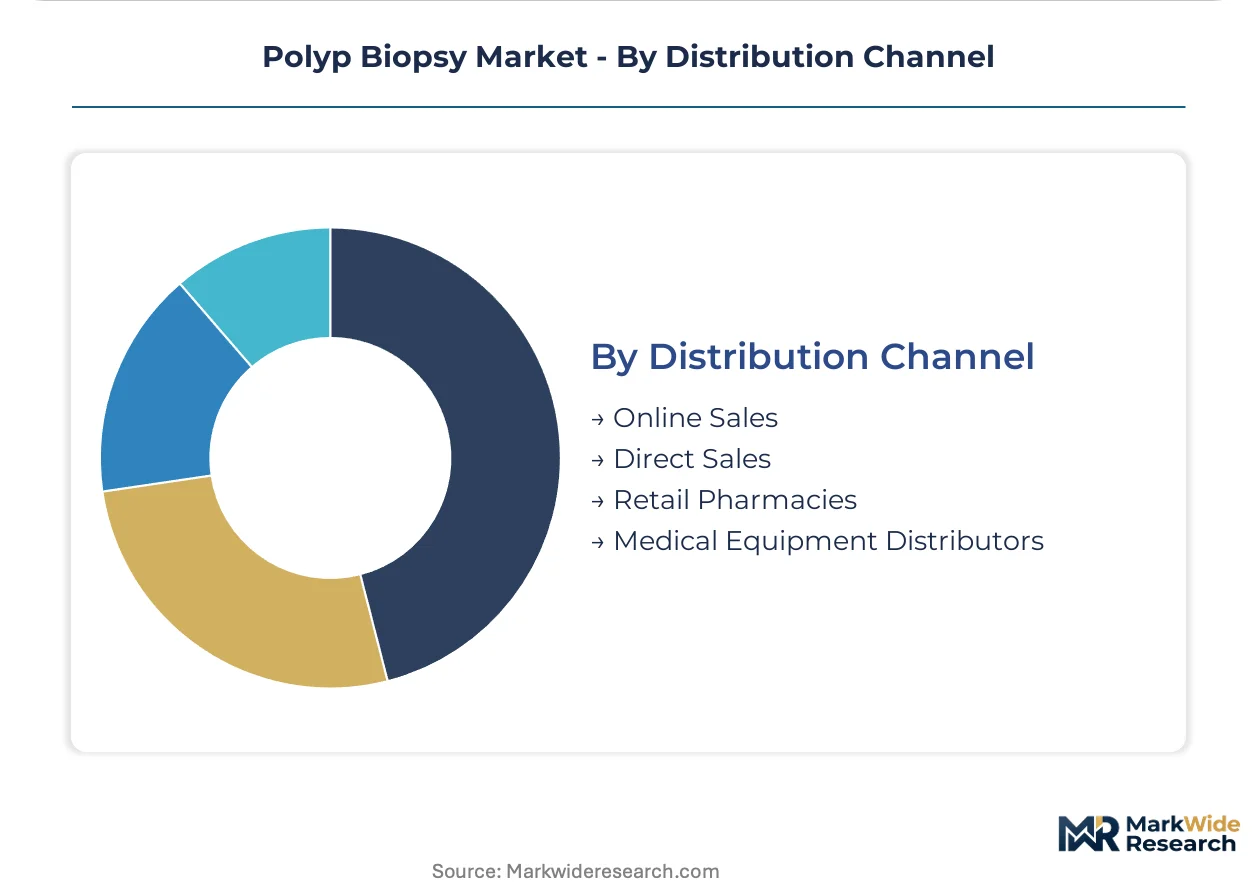
- Direct Sales:Manufacturer field forces manage enterprise accounts with capital equipment attachments and service bundling. Olympus Corporation leverages endoscopy-installation bases to embed digital pathology subscriptions within hardware refresh cycles.
- Medical Equipment Distributors:Regional intermediaries serve mid-tier hospitals with inventory financing and localized technical support where manufacturer presence remains thin.
- Online Sales:E-procurement platforms capture standard consumable replenishment with transparent pricing and reduced transaction friction for routine orders.
- Retail Pharmacies:Minimal penetration limited to patient-directed accessory purchases outside institutional procurement workflows.
Direct Sales dominates value concentration. Online Sales gains share fastest as procurement departments digitize routine replenishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American polyp biopsy device manufacturing through Medtronic's operational footprint and the Mayo Clinic's clinical validation protocols.
United States
Medicare reimbursement protocols and FDA 510(k) premarket notification requirements shape procurement decisions across integrated delivery networks. The Inflation Reduction Act's zero-cost screening provisions expand eligible populations for colorectal cancer surveillance. Hospital systems in the Southeast consolidate vendor contracts through group purchasing organizations.
Germany
EU MDR clinical evidence burdens delay CE marking for new forceps designs while nitinol supply relationships concentrate in Baden-Württemberg's precision metalworking corridor. Heidelberg University Hospital drives digital pathology integration standards. Manufacturers navigate expanded documentation requirements for Class IIa device classifications.
Japan
PMDA regulatory frameworks govern endoscopic instrument approvals alongside METI industrial policy supporting domestic medical device production. Tokyo's diagnostic networks adopt AI-assisted polyp characterization tools. Olympus Corporation leverages its domestic installation base to bundle hardware refreshes with software subscriptions.
United Kingdom
NHS England's bowel cancer screening programme mandates surveillance intervals that sustain recurring biopsy volume through regional diagnostic hubs. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR timelines. London's academic medical centers influence commercial product roadmaps through protocol innovation.
India
CDSCO medical device regulations and Ayushman Bharat health coverage expansion drive demand for cost-optimized disposable instruments. Maharashtra's diagnostic laboratory networks consolidate histopathology review through cloud-enabled platforms. Mumbai's private hospital chains upgrade endoscopic capacity to capture preventive care volume.
Polyp Biopsy Market Competitive Environment
Capital-heavy producers compete with asset-light designers across distinct value chain positions in the polyp biopsy market. The vendor base separates between integrated endoscopy system manufacturers owning installation footprints and specialized instrument producers focused on single-use consumable economics. Three archetypes dominate: diversified medical technology conglomerates with backward integration into specimen logistics, precision instrument specialists concentrated in nitinol forceps engineering, and diagnostic workflow integrators bundling hardware with digital pathology subscriptions. Competitive moves concentrate on enterprise consumable contract consolidation and cloud-based telepathology platform development.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific Corporation exemplify scale-driven positioning through integrated supply chain control over disposable instrument production. Olympus Corporation anchors the endoscopy-system tier, leveraging hardware-installation bases to embed recurring software revenue streams. Cardinal Health, Inc. occupies the distribution-centric archetype, consolidating procurement relationships across hospital networks through inventory financing and logistics integration.
| Leading Market Players |
|---|
| Cardinal Health, Inc. |
| Olympus Corporation |
| Boston Scientific Corporation |
| Medtronic |
| Cook Medical |
| Fujifilm Holdings Corporation |
| Hologic, Inc. |
| C.R. Bard, Inc. |
| INRAD Inc. |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the southeastern United States concentrate procurement leverage through multi-year enterprise consumable contracts that bundle forceps, retrieval devices, and pathology services into subscription-like pricing models. This buyer consolidation forces manufacturers toward outcome-tied pricing structures where reimbursement rates hinge on diagnostic throughput guarantees rather than per-unit markups.
Pricing Analysis
Throughput-based pricing anchors vendor contracting as hospital laboratories negotiate per-procedure fees tied to histopathological review volumes. Price differentiation rests on FDA 510(k) clearance tier and electrocautery integration level, with premium hot-forceps variants commanding substantial uplifts over cold-forceps baselines. Pricing pressure stems from Medicare reimbursement compression for minimally invasive diagnostic protocols, squeezing margin pools across disposable instrument tiers. Ambulatory surgery centers exhibit acute price sensitivity due to capital-light operating models, while academic medical centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from major group purchasing organizations force manufacturers to qualify nitinol wire suppliers across both Japan and Germany, diluting single-source dependency despite geographic concentration. Component supply draws from Baden-Württemberg's precision metalworking corridor for forceps jaw fabrication, with formalin preservation media sourced from United States chemical producers. Single-source vulnerability in nitinol supply creates exposure to input cost volatility when Japanese or German output disruptions occur. Distribution runs through manufacturer field forces for enterprise accounts, with regional medical equipment distributors serving mid-tier hospitals requiring localized technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race where control over specimen-handling logistics and cloud pathology platforms determines long-term margin capture. Players are pursuing backward integration into nitinol supply chains and digital workflow software to escape commodity forceps pricing.
For Market Incumbents: Lock in enterprise consumable contract renewals by embedding AI-assisted polyp characterization subscriptions within hardware refresh cycles. Defend against capsule endoscopy substitution by expanding mobile diagnostic service partnerships with critical access hospitals. Prioritize backward integration into nitinol supply to insulate margin pools from Baden-Württemberg and Japanese supplier volatility.
For New Entrants and Emerging Players: Group purchasing organizations represent the most accessible channel for bypassing entrenched manufacturer relationships. Target rural hospital networks in the United States that remain undersupplied with advanced endoscopy suites and lack procurement sophistication for enterprise contracting. Lead with modular disposable electrocautery forceps that eliminate reprocessing infrastructure requirements.
For Investors and Strategic Acquirers: The window for entry favors diagnostic workflow integrators bundling hardware with telepathology platforms over pure-play instrument manufacturers. Long-term viability centers on cloud-enabled pathology networks capable of consolidating histopathology review across dispersed sites. Watch for CMS coverage determinations on AI-assisted polyp characterization as the inflection signal for reimbursement-driven vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Olympus leverages endoscopy-installation base to embed digital pathology subscriptions with hardware refreshes. |
| CE Marking Pathway | EU MDR clinical evidence burdens delay European launch windows for new forceps and needle geometries. |
| Backward Integration | Medtronic controls specimen-handling logistics to differentiate beyond commodity forceps manufacturing. |
| Software Companion Development | Machine learning algorithms for polyp classification reduce pathologist review time and meet laboratory throughput targets. |
| Reimbursement Strategy | IRA zero-cost screening provisions expand Medicare beneficiary eligibility for colorectal cancer surveillance protocols. |
Study Parameters
FDA 510(k) premarket notification databases, CMS Medicare coverage determinations, and EU MDR CE marking registries formed the secondary backbone for regulatory pathway mapping. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and gastroenterology department heads validated procurement behavior and technology adoption patterns. Bottom-up modeling of disposable forceps unit economics and top-down reconciliation against health system capital expenditure disclosures ensured cross-verification of market sizing.
Historical trendline analysis of screening procedure volumes and reimbursement rate trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, application, end user, and distribution channel, with additional granularity on electrocautery integration levels and digital pathology adoption patterns. CAGRs were derived from procedure volume elasticity to population-health mandates and vendor contract renewal cycles, incorporating nitinol supply constraints and AI-assisted characterization regulatory timelines as scenario modifiers.
Caveats apply where FDA guidance shifts on colorectal cancer risk stratification or CMS reimbursement protocols for AI-assisted diagnosis could materially shift the outlook. Forecasts reflect assumptions about Medicare coverage stability and EU MDR documentation burden persistence. A model refresh is warranted upon material change in nitinol supply availability or IRA preventive care incentive funding levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Bronchoscopy Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
US Colonic Stents Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Global Endoscopy Ultrasound Market