
 Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market | 2026-2036
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market Outlook
Japanese biopharma manufacturing capacity is shifting toward precision oncology compounds as regional governments expand reimbursement for biomarker-directed care. Bristol-Myers Squibb leverages its immuno-oncology infrastructure to anchor clinical trial networks across East Asia. Eli Lilly and Company sustains insulin-related oncology research pipelines that intersect with pancreatic disease biology. AstraZeneca competes through targeted therapy development programs aligned with regional genetic profiling adoption.
Asia-Pacific pancreatic cancer therapeutics and diagnostics encompass systemic treatment modalities and detection technologies for exocrine and endocrine pancreatic malignancies, including CA 19-9 serum assays, CT/MRI imaging protocols, and KRAS mutation analysis via next-generation sequencing platforms. The primary purpose centers on improving five-year survival outcomes through earlier stage detection and genotype-matched intervention selection. Chemotherapy retains the largest current revenue footprint among product types, though molecular diagnostics and biomarker testing represent the fastest-expanding technology segments as pathology laboratories upgrade sequencing infrastructure. Diagnostic imaging maintains stable procedural volumes while margin pools increasingly migrate toward genetic profiling services.
Japan's PMDA, Australia's TGA, and South Korea's MFDS each maintain distinct biomarker validation requirements that fragment approval pathways for companion diagnostic kits. China's NMPA implements domestic clinical trial mandates that extend registration timelines for foreign assay manufacturers. Stakeholders must monitor evolving multi-country harmonization initiatives versus persistent national testing requirements.
Market Dynamics
Biomarker validation requirements across Japan's PMDA, Australia's TGA, and South Korea's MFDS are fragmenting approval pathways and forcing manufacturers to maintain parallel regulatory track systems for companion diagnostic kits.
Growth Catalysts
- Centralized cancer center expansion:China's tier-one hospital networks are consolidating pancreatic care into high-volume diagnostic hubs that standardize molecular testing protocols and drive procedure volumes.
- PMDA accelerated review pathways:Japan's streamlined biomarker-driven therapy approvals are compressing development-to-commercialization timelines for precision oncology compounds.
- Sequencing infrastructure upgrades:Regional pathology laboratories are deploying next-generation sequencing platforms that expand KRAS mutation analysis capacity and shift margin pools toward genetic profiling services.
Market Restraints
- NMPA domestic trial mandates:China's requirement for local clinical data extends registration timelines for foreign assay manufacturers and raises capital requirements for market entry.
- Biomarker kit supply concentration:Companion diagnostic reagent production clusters in select East Asian contract manufacturing zones, creating single-source vulnerability for regional distributors.
- Five-year survival ceiling:Pancreatic cancer biology imposes inherent efficacy limits on systemic therapies that constrain pricing power and reimbursement negotiations.
Strategic Opportunities
- Australia's TGA harmonization initiatives:Emerging multi-country validation frameworks could reduce redundant testing requirements and streamline kit registrations across developed Asia-Pacific markets.
- Liquid biopsy integration:Circulating tumor DNA platforms are converging with tissue-based sequencing to enable non-invasive monitoring and expand testing frequency in oncology clinics.
- South Korea's MFDS orphan drug incentives:Rare disease designation pathways for pancreatic subtypes offer tax credits and expedited reviews that attract development investment.
Industry Challenges
- Molecular pathologist scarcity:Interpretation of complex genomic reports requires specialized training that outpaces current fellowship program output across the region.
- Multi-platform integration complexity:CA 19-9 serum assays, imaging protocols, and sequencing results must reconcile within electronic health record systems that lack standardized data architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market |
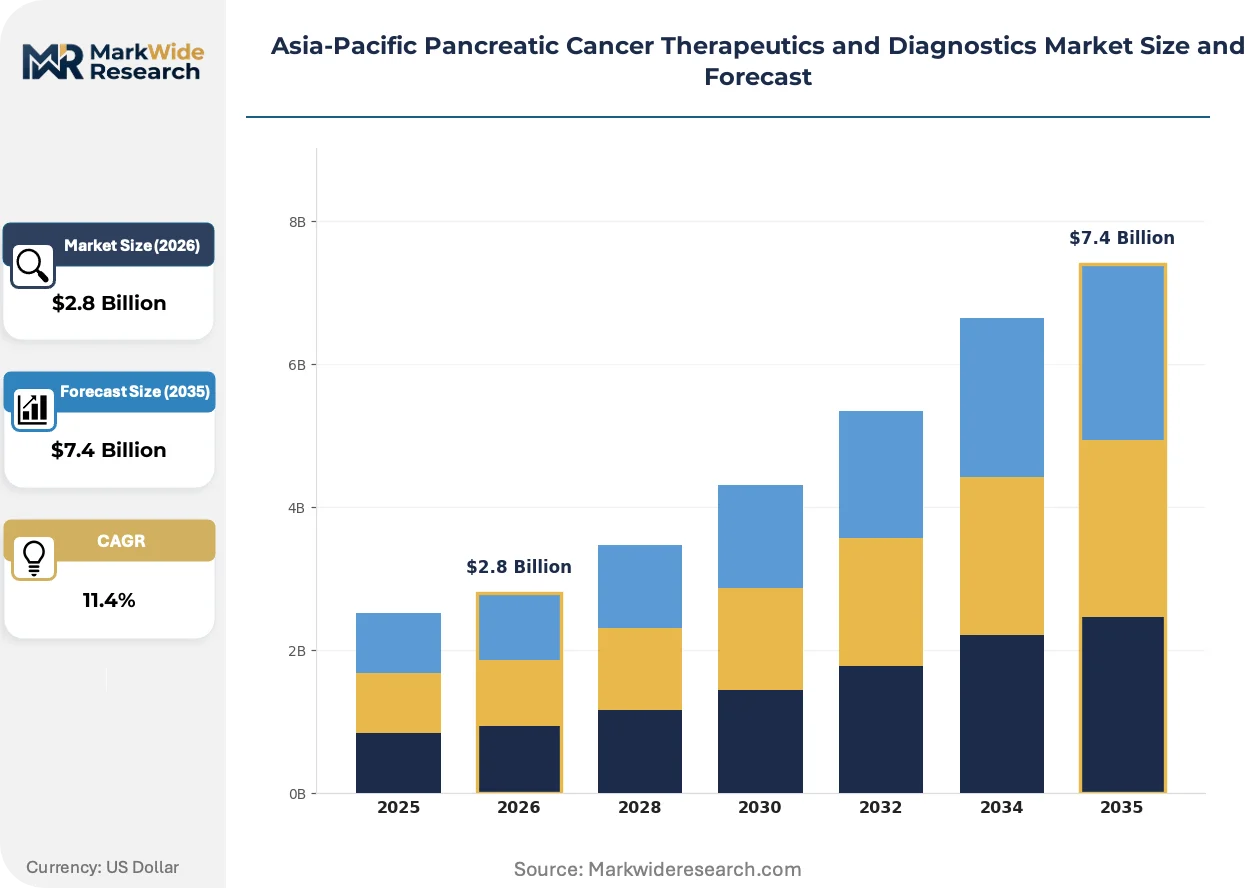
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Diagnostic Imaging Technology: Molecular Diagnostics, Biomarker Testing, Genetic Profiling, Imaging Techniques End User: Oncology Clinics, Hospitals, Diagnostic Laboratories, Research Institutions Delivery Mode: Intravenous, Oral, Injectable, Diagnostic Procedures |
| Companies Covered | Bristol-Myers Squibb, Novartis AG, F. Hoffmann-La Roche AG, Pfizer Inc, Eli Lilly and Company, AstraZeneca PLC, Amgen Inc, Merck KGaA, Sysmex Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market Strategic Shifts
Digital pathology workflows are compressing diagnostic turnaround times while artificial intelligence applications reshape how molecular data informs treatment selection in pancreatic oncology.
Next-generation sequencing platforms are automating variant interpretation pipelines that previously required manual pathologist review. Major cancer centers in Tokyo, Seoul, and Shanghai are deploying these systems to handle rising test volumes. This compression of analytical labor is reallocating specialist time toward complex case consultation rather than routine mutation calling.
Australia's TGA is aligning companion diagnostic validation requirements with emerging ICH guidelines to reduce redundant submission packages. This regulatory convergence is lowering compliance costs for multinational manufacturers. The policy shift most directly benefits mid-sized assay developers seeking simultaneous entry across Australia, Japan, and South Korea.
Hospital procurement committees are consolidating molecular testing contracts under single-vendor agreements that bundle sequencing, bioinformatics, and clinical decision support. This vendor consolidation is displacing the previous fragmented purchasing model where pathology departments selected platforms independently. The pattern is most visible in China's provincial hospital networks where centralized bidding processes favor integrated service providers.
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market Segmentation
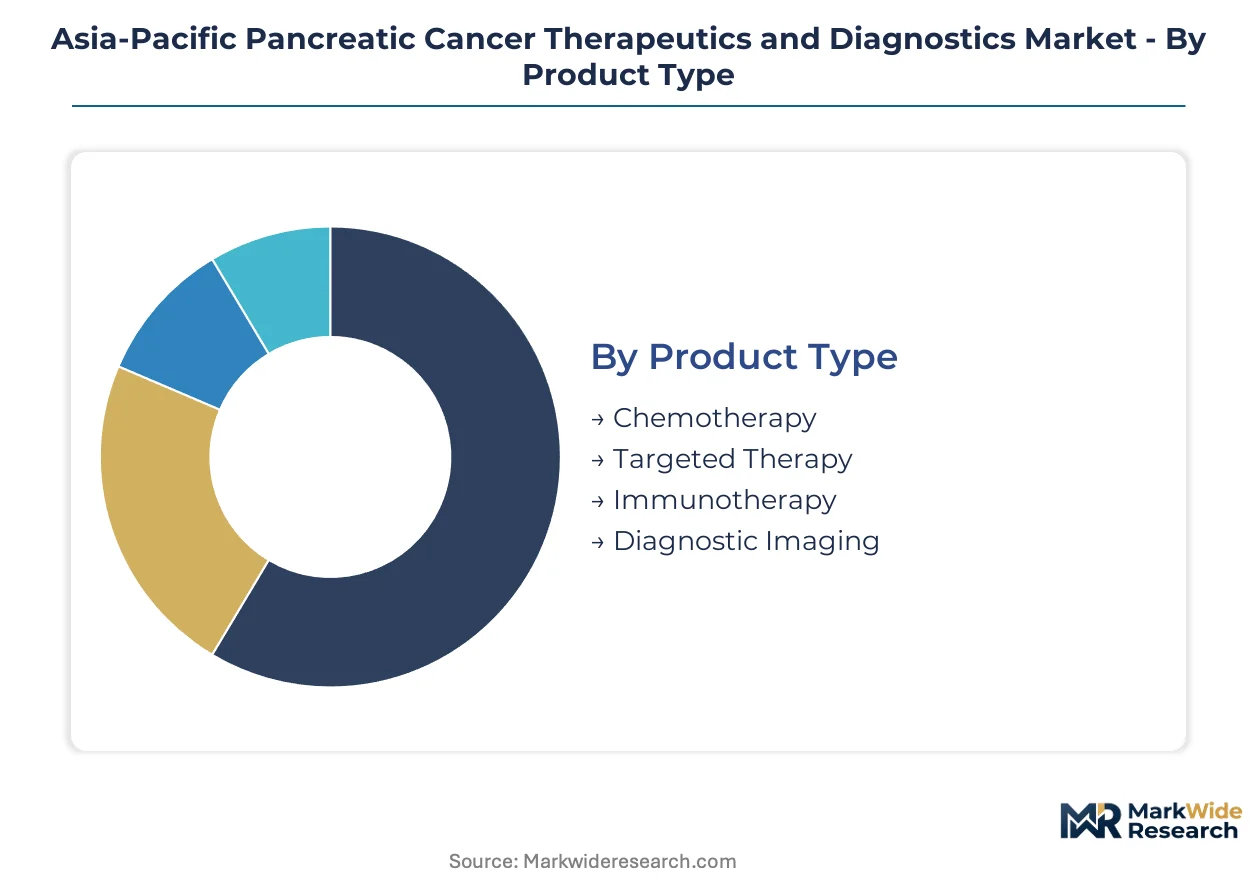
Pancreatic cancer care in Asia-Pacific fragments across therapeutic modalities, detection technologies, and care settings. Treatment selection and diagnostic sequencing depend on tumor biology, institutional capabilities, and reimbursement pathways that vary by country.
Product Type:
Physicians weigh efficacy data against toxicity profiles and reimbursement status when selecting systemic therapy.
- Chemotherapy:Gemcitabine-based and FOLFIRINOX protocols remain first-line standards for metastatic disease. Oncology clinics in Japan and South Korea administer these regimens at high volumes, though margin compression from biosimilar competition constrains pricing power.
- Targeted Therapy:PARP inhibitors and EGFR-directed agents address specific molecular subtypes identified through companion diagnostic testing. China's tier-one hospitals are expanding access to these genotype-matched interventions as NMPA accelerates biomarker-driven approvals.
- Immunotherapy:Checkpoint inhibitors show limited efficacy in unselected pancreatic populations but retain development interest for microsatellite-instability-high subtypes.
- Diagnostic Imaging:CT and MRI protocols stage disease and monitor treatment response across the region.
Chemotherapy leads on scale; targeted therapy leads on momentum.
Technology:
Capital deployment and technical expertise determine which detection platforms dominate within each national health system.
- Molecular Diagnostics:Next-generation sequencing platforms automate KRAS mutation detection and variant interpretation. Pathology laboratories in Tokyo, Seoul, and Shanghai are upgrading infrastructure to handle rising test volumes and reduce turnaround times.
- Biomarker Testing:CA 19-9 serum assays and emerging circulating tumor DNA platforms enable non-invasive monitoring. Australia's TGA harmonization initiatives are streamlining validation requirements for multi-analyte panels.
- Genetic Profiling:Germline and somatic testing identifies hereditary syndromes and actionable alterations. South Korea's MFDS orphan drug incentives accelerate development of subtype-directed interventions.
- Imaging Techniques:Contrast-enhanced CT, MRI with diffusion-weighted sequences, and endoscopic ultrasound guide biopsy and staging decisions.
Molecular diagnostics commands the steepest expansion trajectory; imaging techniques anchor procedural volume.
End User:
Procurement authority and clinical workflow integration shape vendor selection across care settings.
- Oncology Clinics:Specialized centers concentrate pancreatic cancer expertise and molecular testing capabilities. Japan's PMDA accelerated review pathways compress the interval between biomarker identification and therapy initiation at these sites.
- Hospitals:China's provincial hospital networks are consolidating molecular testing contracts under single-vendor agreements that bundle sequencing, bioinformatics, and clinical decision support.
- Diagnostic Laboratories:Reference labs process complex genomic assays for institutions lacking in-house platforms.
- Research Institutions:Academic medical centers conduct early-phase trials and generate real-world evidence on novel combinations.
Hospitals lead on scale; oncology clinics lead on momentum.
Delivery Mode:
Patient compliance, administration infrastructure, and pharmacokinetic requirements determine route selection.
- Intravenous:Cytotoxic agents and monoclonal antibodies require infusion center capacity. Australia's TGA and Japan's PMDA maintain distinct manufacturing and handling standards that fragment supply chain configurations.
- Oral:Tyrosine kinase inhibitors and maintenance regimens offer outpatient convenience. China's NMPA domestic trial mandates extend registration timelines for foreign oral oncology manufacturers.
- Injectable:Subcutaneous formulations reduce infusion center burden for select supportive care agents.
- Diagnostic Procedures:Tissue acquisition for molecular testing requires interventional radiology and pathology coordination.
Intravenous leads on scale; oral leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's oncology infrastructure outpaces Australia's in biomarker testing density, while China's hospital consolidation creates divergent procurement dynamics across the region.
Japan
Oncology clinics in Tokyo and Osaka are deploying next-generation sequencing platforms at scale. PMDA accelerated review pathways compress approval timelines for companion diagnostic kits. The Kanto region concentrates precision oncology manufacturing as biopharma capacity shifts toward genotype-matched compounds.
China
Tier-one hospital networks in Beijing and Shanghai are consolidating pancreatic care into centralized diagnostic hubs. NMPA domestic clinical trial mandates extend registration timelines for foreign assay manufacturers. The Yangtze River Delta anchors contract manufacturing clusters for companion diagnostic reagents.
South Korea
Seoul's cancer centers are expanding molecular diagnostic adoption for KRAS mutation analysis. MFDS orphan drug incentives attract development investment for pancreatic cancer subtypes. The Seoul Capital Area drives regional sequencing infrastructure upgrades through academic medical center procurement.
Australia
TGA harmonization initiatives are streamlining validation requirements for multi-analyte biomarker panels. Sydney and Melbourne oncology clinics are integrating liquid biopsy platforms with tissue-based sequencing. The TGA's alignment with emerging ICH guidelines reduces redundant submission packages for multinational manufacturers.
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market Competitive Environment
North American pharmaceutical conglomerates anchor the therapeutics tier; Japanese and European diagnostic specialists hold the testing infrastructure layer. Market structure concentrates around integrated oncology portfolios versus standalone diagnostic platforms. Three archetypes dominate: immuno-oncology heavyweights, precision therapy developers, and sequencing platform vendors. Competitive moves center on clinical trial network expansion and companion diagnostic co-development partnerships.
Within the immuno-oncology tier, Bristol-Myers Squibb and AstraZeneca PLC occupy positions shaped by regional trial infrastructure investments. Among precision therapy developers, Eli Lilly and Company exemplifies archetype players intersecting insulin-related research with pancreatic disease biology. Roche's diagnostic division and Sysmex Corporation represent the sequencing and biomarker testing infrastructure layer, anchoring pathology laboratory upgrade cycles across East Asian markets.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Novartis AG |
| F. Hoffmann-La Roche AG |
| Pfizer Inc |
| Eli Lilly and Company |
| AstraZeneca PLC |
| Amgen Inc |
| Merck KGaA |
| Sysmex Corporation |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient spot indices for gemcitabine and nab-paclitaxel feed directly into oncology procurement negotiations across East Asian hospital networks, compressing distributor margins when raw material costs spike while leaving branded companion diagnostic kits insulated from commodity volatility through locked long-term service contracts.
Pricing Analysis
Distributor margin compression runs through China's provincial hospital networks as centralized bidding processes force reagent suppliers to absorb logistics and cold-chain costs. Three-tier pricing structure across premium, standard, and economy levels separates fully automated NGS platforms from manual PCR workflows and basic CA 19-9 serum assays. Pricing pressure stems from biosimilar FOLFIRINOX competition in Japan and South Korea. Oncology clinics in tier-two Chinese cities exhibit highest price sensitivity; Tokyo's academic medical centers show lowest.
Supply Chain Analysis
Companion diagnostic reagent production rests on contract manufacturing clusters in China's Yangtze River Delta, South Korea's Seoul Capital Area, and Japan's Kanto region. Key inputs span synthetic oligonucleotides, fluorescent probe chemistries, and sequencing flow cells. Single-source vulnerability concentrates in East Asian specialty chemical producers for probe synthesis. Distribution runs through regional distributors holding cold-chain certifications for temperature-sensitive reagents, with direct-to-hospital contracts emerging for high-volume NGS service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PMDA accelerated review pathways for biomarker-driven therapies compound regulatory demand, creating procurement urgency as Japanese oncology clinics race to deploy genotype-matched interventions before reimbursement windows narrow.
For Market Incumbents: Deepen companion diagnostic co-development partnerships with immuno-oncology developers to lock in platform exclusivity as liquid biopsy technologies threaten tissue-based testing volumes. Expand sequencing service capacity in Shanghai and Seoul to capture hospital consolidation contracts before provincial bidding processes freeze vendor selection. Certification investment in Australia's TGA harmonization framework reduces redundant validation costs across developed Asia-Pacific markets.
For New Entrants and Emerging Players: Australia's regional oncology clinics represent an underserved buyer archetype as TGA streamlining lowers entry barriers for mid-sized assay developers. White-space targets include circulating tumor DNA monitoring platforms for post-surgical surveillance and KRAS G12C subtyping assays for South Korea's orphan drug incentive pathways. Go-to-market angle: bundle bioinformatics interpretation with assay provision to offset molecular pathologist scarcity.
For Investors and Strategic Acquirers: Asymmetric upside sits with sequencing platform vendors holding installed base density in Tokyo and Seoul cancer centers. Long-term viability hinges on recurring reagent revenue streams rather than capital equipment placement. Acquisition target archetype: liquid biopsy specialists with validated ctDNA panels for pancreatic cancer monitoring. Signal to watch: NMPA biomarker-driven approval velocity as indicator of Chinese market access premium.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Locks in platform exclusivity with Bristol-Myers Squibb and AstraZeneca precision oncology pipelines. |
| NGS Infrastructure Scale-Up | Captures consolidated procurement contracts across China's provincial hospital networks. |
| TGA Harmonization Alignment | Reduces redundant submission costs for simultaneous Australia-Japan-South Korea market entry. |
| Liquid Biopsy Platform Integration | Enables non-invasive monitoring frequency expansion as tissue acquisition constraints persist. |
| Orphan Drug Incentive Pathway | Leverages MFDS tax credits for pancreatic cancer subtype-directed assay development. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads at PMDA and MFDS, hospital procurement managers in tier-one Chinese networks, and payer access specialists with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up procedure volume estimates and top-down market sizing triangulated across data streams.
Historical reference periods anchored the forecast window to established therapy adoption curves and diagnostic infrastructure deployment cycles. Segmentation dimensions spanned treatment line, technology platform, end-user setting, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, pricing elasticity assumptions, and reimbursement pathway velocity. Industry-specific inputs included biomarker testing penetration rates and companion diagnostic co-approval timelines.
Inputs from regulatory filing databases and hospital procurement records were available through the study window; gaps in real-world liquid biopsy adoption data introduce uncertainty bands around non-invasive monitoring projections. Forecasts reflect documented assumptions on PMDA review pathway efficiency and NMPA domestic trial mandate enforcement. Regulatory approval delays, biomarker validation failures, and reimbursement renegotiations warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market