
 Asia-Pacific Colorectal Cancer Diagnostics Market | 2026-2036
Asia-Pacific Colorectal Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Colorectal Cancer Diagnostics Market Outlook
Modular test bundling is consolidating routine fecal immunochemical tests with follow-up colonoscopy referrals into single-contract service agreements. F. Hoffmann-La Roche Ltd leverages its centralized lab automation platforms to anchor high-throughput molecular workflows across Japanese hospital networks. Illumina Inc competes by extending next-generation sequencing panel accessibility into mid-tier diagnostic laboratories in South Korea and Australia. QIAGEN sustains sample-to-insight workflow dominance through integrated PCR and sample preparation systems deployed in Chinese reference labs.
Colorectal cancer diagnostics encompasses laboratory and imaging modalities designed to detect neoplastic lesions in the colon and rectum through histopathological examination, molecular biomarker analysis, and endoscopic visualization with optical or chromoendoscopic enhancement. These systems serve to identify precancerous polyps, stage invasive carcinomas, and guide targeted therapeutic selection through MSI-status and RAS-mutation profiling. Blood-based screening and molecular diagnostics represent the fastest-expanding segments as liquid biopsy sensitivity improves and multi-cancer early detection panels gain reimbursement traction. Endoscopy maintains the largest installed base and highest per-procedure revenue capture, though margin compression from commoditized colonoscope manufacturing is shifting profit pools toward disposable accessories and AI-assisted polyp detection software.
Japan's PMDA and China's NMPA enforce divergent molecular diagnostics registration frameworks, with PMDA requiring prospective clinical validation and NMPA accepting bridging studies from overseas trial data, creating asymmetric market entry timelines for foreign manufacturers. India's CDSCO has streamlined in-vitro diagnostics rules under the Medical Device Rules, though state-level laboratory licensing remains fragmented and delays commercial scale-up. Australia's TGA alignment with EU MDR transition timelines adds compliance complexity for multinational kit suppliers. Stakeholders must monitor evolving reimbursement codes for blood-based screening across Australia's Medicare Benefits Schedule and Japan's universal health insurance fee revisions to calibrate product-portfolio investment sequencing.
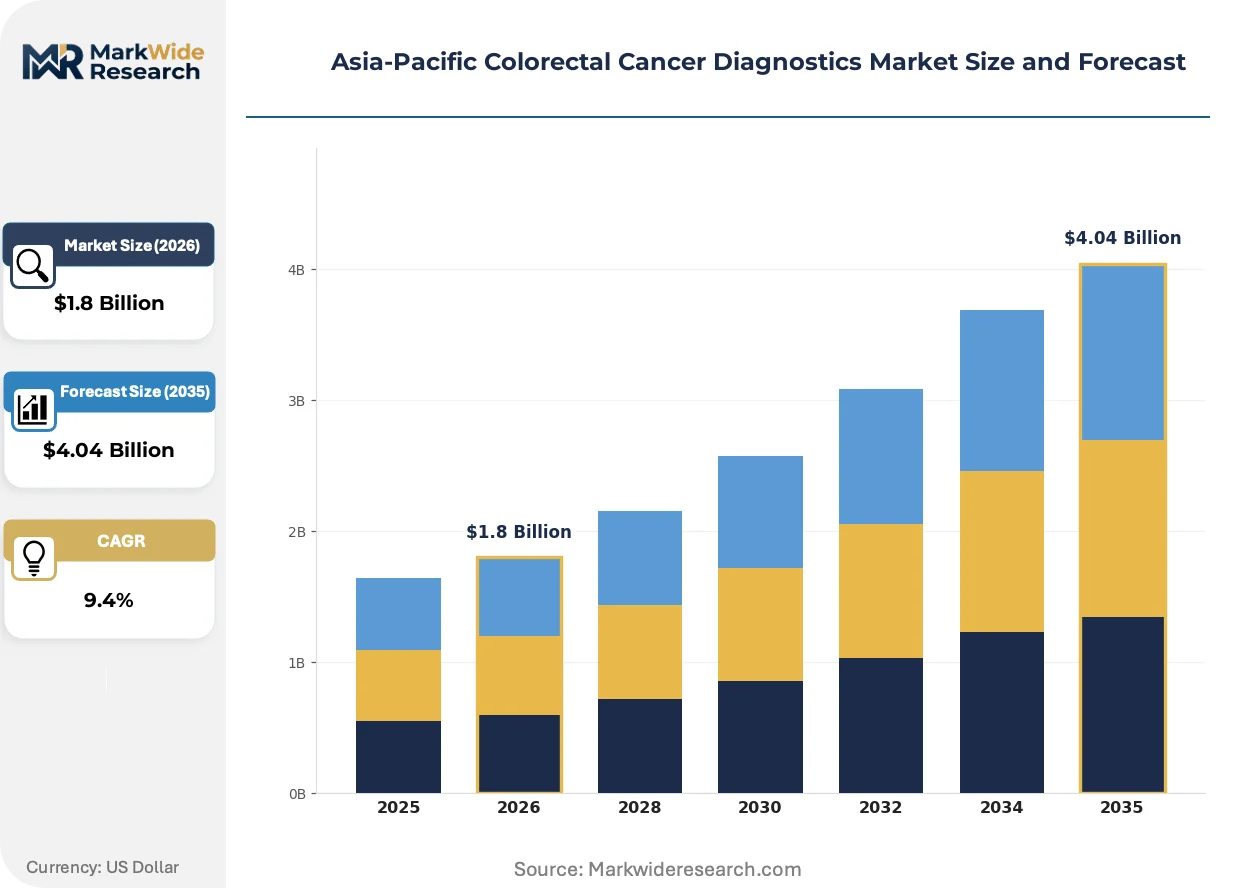
Market Dynamics
Modular test bundling is compressing procurement cycles across Asia-Pacific hospital networks, consolidating fecal immunochemical testing with colonoscopy referrals into single-contract service agreements that lock in multi-year vendor relationships and reduce switching flexibility.
Growth Catalysts
- CDSCO Streamlined IVD Rules:India's Medical Device Rules 2017 amendments have reduced registration timelines for stool-based screening kits, enabling faster commercial scale-up of non-invasive diagnostics in tier-2 and tier-3 cities.
- PMDA Molecular Pathway Acceleration:Japan's tightened but clarified biomarker validation framework is compressing approval timelines for RAS-mutation profiling assays, pulling companion diagnostics into earlier-stage treatment protocols.
- Liquid Biopsy Sensitivity Gains:Blood-based methylated DNA detection thresholds have crossed clinical utility thresholds, expanding reimbursement eligibility for colorectal cancer screening beyond fecal occult blood testing in Australian and South Korean health systems.
Market Restraints
- Colonoscope Manufacturing Commoditization:Margin compression in reusable endoscope hardware is shifting profit pools toward disposable accessories, constraining capital equipment vendors' pricing power across Chinese procurement consortia.
- NMPA Bridging Study Limitations:China's acceptance of overseas trial data for molecular diagnostics creates asymmetric validation requirements that delay product-market fit for novel biomarker panels against local patient populations.
- Reference Lab Concentration:High-throughput molecular workflows consolidate in Beijing, Shanghai, and Tokyo hospital networks, creating bottleneck risk for sample processing capacity during screening campaign surges.
Strategic Opportunities
- Vietnam and Indonesia Penetration:Underdeveloped screening infrastructure in Southeast Asian urban centers presents first-mover positioning for portable fecal immunochemical testing platforms distributed through pharmacy retail chains.
- AI-Assisted Polyp Detection:Computer vision integration with standard colonoscopy hardware is creating software-as-a-service revenue streams that displace per-procedure physician interpretation costs in Japanese and Australian endoscopy suites.
- Multi-Cancer Early Detection Panels:Liquid biopsy platforms combining colorectal signals with lung and pancreatic biomarkers are securing pilot reimbursement codes in Australia's Medicare Benefits Schedule, expanding addressable screening populations.
Industry Challenges
- MSI-Status Assay Standardization:Discordant immunohistochemistry and PCR-based microsatellite instability testing protocols across Chinese reference laboratories are generating false-negative rates that complicate immunotherapy eligibility decisions.
- Sample-to-Result Workflow Integration:Mid-tier diagnostic laboratories in South Korea and Australia face capital constraints when retrofitting legacy PCR infrastructure with automated nucleic acid extraction systems required for high-complexity molecular testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Colorectal Cancer Diagnostics Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsies, Imaging Tests, Endoscopy, Blood Tests Technology: Molecular Diagnostics, Immunohistochemistry, PCR, Next-Generation Sequencing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Outpatient Clinics Application: Screening, Early Detection, Genetic Testing, Treatment Monitoring |
| Companies Covered | F. Hoffmann-La Roche Ltd, Illumina Inc, QIAGEN, Thermo Fisher Scientific Inc, Abbott Laboratories, GE HealthCare Technologies Inc, Becton Dickinson & Co, Siemens Healthineers AG, Exact Sciences Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Colorectal Cancer Diagnostics Market Strategic Shifts
Artificial intelligence integration and blood-based screening modalities are actively redistributing diagnostic value across the Asia-Pacific colorectal cancer detection pathway, compressing traditional endoscopy-centric revenue models while opening software and liquid biopsy service opportunities.
Next-generation sequencing panels for RAS and BRAF mutation profiling are decentralizing molecular testing authority from centralized reference laboratories into mid-tier hospital pathology departments across South Korea and Australia. Regional health authorities in Seoul and Sydney are fast-tracking platform accreditation to reduce sample send-out delays. This geographic compression of testing capability is shortening turnaround times for targeted therapy selection while fragmenting kit vendor concentration.
PMDA's 2022 revised guidance on companion diagnostics approval is mandating prospective clinical validation for novel biomarker assays, eliminating previous bridging study pathways for certain mutation-detection platforms. Japanese pharmaceutical manufacturers are restructuring early-phase trial designs to generate Japan-specific efficacy data. Molecular diagnostics suppliers are responding by establishing captive clinical research organizations within Tokyo and Osaka to satisfy evidentiary requirements.
Hospital procurement consortia in China's tier-1 cities are consolidating fecal immunochemical test purchasing through three-year framework agreements that bundle reagent supply with analyzer placement and maintenance services. Traditional distributor networks are losing volume to direct manufacturer-contractor relationships. This channel restructuring is most visible in Beijing and Shanghai municipal health system tenders, where total-cost-of-ownership metrics now dominate unit-price evaluation.
Asia-Pacific Colorectal Cancer Diagnostics Market Segmentation
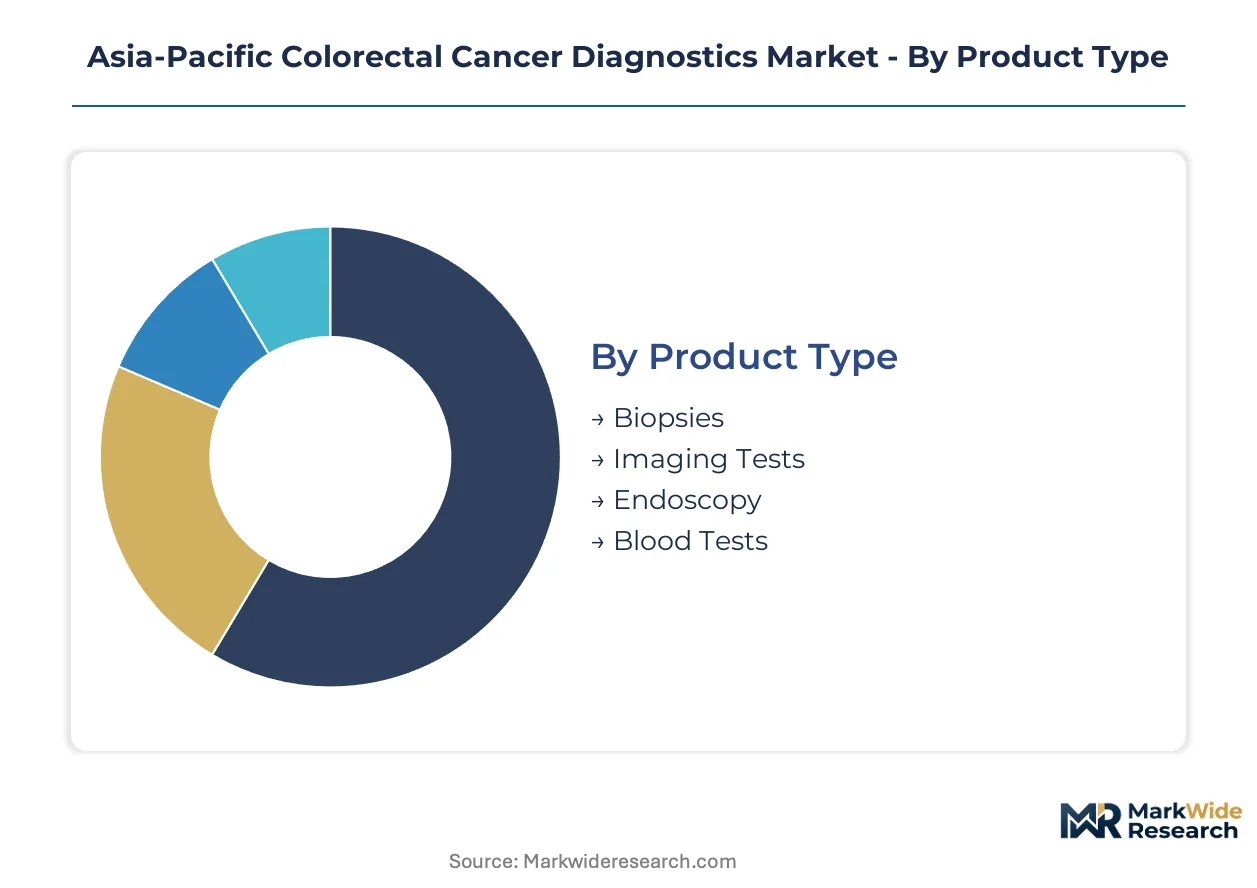
Segmentation in colorectal cancer diagnostics reveals how technology maturation, reimbursement pathways, and care delivery models fragment purchasing authority across Asia-Pacific health systems. Distinct procurement behaviors separate high-throughput hospital laboratories from distributed outpatient screening networks.
Product Type:
Endoscopy hardware and consumables anchor capital expenditure cycles, while blood-based modalities capture incremental screening volumes outside procedural settings.
- Endoscopy:Optical and chromoendoscopic visualization systems with disposable accessory channels dominate per-procedure revenue capture. Japanese hospital networks in Tokyo and Osaka maintain the densest installed bases of high-definition colonoscopes, though margin compression from Chinese manufacturing consortia is shifting profit pools toward single-use biopsy valves and irrigation pumps.
- Blood Tests:Liquid biopsy platforms detecting circulating tumor DNA and methylated biomarkers are expanding reimbursement eligibility beyond fecal occult blood testing in Australian and South Korean health systems. Sensitivity thresholds crossing clinical utility benchmarks are pulling these assays into population screening protocols previously reserved for stool-based methods.
- Biopsies:Tissue acquisition devices and histopathological processing services generate recurring revenue through standardized polyp resection workflows.
- Imaging Tests:CT colonography and MRI-based staging modalities serve contraindicated patient populations unable to tolerate endoscopic procedures.
Endoscopy leads on scale; blood tests lead on momentum.
Technology:
Workflow automation and multiplexing capability determine vendor selection in high-volume reference laboratories across Beijing, Shanghai, and Sydney.
- PCR:Polymerase chain reaction systems for KRAS, NRAS, and BRAF mutation detection remain the workhorse technology for companion diagnostic testing. QIAGEN's integrated sample-to-insight platforms dominate Chinese reference laboratories where throughput requirements exceed ten thousand samples monthly.
- Next-Generation Sequencing:Comprehensive genomic profiling panels are decentralizing from centralized Tokyo and Seoul reference laboratories into mid-tier hospital pathology departments. Regional health authorities in New South Wales and Gyeonggi Province are fast-tracking platform accreditation to reduce sample send-out delays for targeted therapy selection.
- Molecular Diagnostics:RNA and DNA-based assays for microsatellite instability status guide immunotherapy eligibility decisions.
- Immunohistochemistry:Antibody-based protein expression testing provides cost-effective screening for mismatch repair deficiency prior to confirmatory molecular testing.
PCR retains the largest installed base; next-generation sequencing shows the steepest expansion trajectory.
End User:
Procurement concentration varies sharply between capital-intensive hospital networks and distributed outpatient settings with constrained infrastructure budgets.
- Hospitals:Integrated diagnostic and therapeutic service lines in China's tier-1 cities and Japan's urban prefectures consolidate high-complexity molecular testing with oncology treatment planning. Three-year framework agreements bundling reagent supply with analyzer placement are displacing traditional distributor relationships in Beijing and Shanghai municipal tenders.
- Diagnostic Laboratories:Independent reference laboratories and hospital-affiliated central labs process screening volumes for multiple catchment areas. Australia's Sonic Healthcare and Japan's BML operate high-throughput workflows serving regional hospital networks with standardized turnaround time guarantees.
- Outpatient Clinics:Community-based screening sites in Vietnam and Indonesia present first-mover positioning for portable fecal immunochemical testing platforms distributed through pharmacy retail chains.
- Research Institutions:Academic medical centers in Melbourne and Singapore drive biomarker discovery and early-phase validation studies for novel detection modalities.
Hospitals command procurement volume; diagnostic laboratories are gaining share fastest through regional consolidation.
Application:
Reimbursement coding distinctions separate preventive screening from diagnostic confirmation and therapy guidance functions.
- Screening:Population-level detection programs for asymptomatic individuals concentrate demand in fecal immunochemical testing and emerging blood-based modalities. Australia's Medicare Benefits Schedule and Japan's universal health insurance system are revising fee structures to accommodate multi-cancer early detection panel pilots.
- Genetic Testing:Hereditary risk assessment through Lynch syndrome and familial adenomatous polyposis screening drives cascade testing demand in Australian and Japanese tertiary centers with established genetic counseling infrastructure.
- Early Detection:Diagnostic workup for symptomatic patients with positive screening results or clinical suspicion.
- Treatment Monitoring:Circulating tumor DNA surveillance for minimal residual disease and therapy response assessment.
Screening generates procedure volume; genetic testing commands premium pricing per assay.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered population-scale colorectal cancer screening through its 1992 national program, establishing the clinical validation frameworks that now govern molecular diagnostics approval across Asia-Pacific. This institutional heritage shapes regulatory convergence and technology diffusion patterns throughout the region.
China
Beijing and Shanghai municipal health systems drive procurement volume through three-year framework agreements bundling reagent supply with analyzer placement. NMPA acceptance of overseas bridging studies accelerates market entry for established platforms while creating validation gaps for novel biomarker panels. Yangtze River Delta hospital networks consolidate high-throughput molecular workflows, concentrating sample processing capacity in reference laboratories serving multiple provinces.
Japan
Tokyo and Osaka prefectures maintain the densest installed bases of high-definition colonoscopy systems and the most mature universal screening infrastructure. PMDA's 2022 revised companion diagnostics guidance mandates prospective clinical validation, eliminating previous bridging pathways for mutation-detection platforms. Kanto region pharmaceutical manufacturers restructure early-phase trials to generate Japan-specific efficacy data, pulling molecular diagnostics suppliers into captive CRO arrangements.
India
Tier-2 and tier-3 cities present expansion opportunities as CDSCO streamlines IVD registration under Medical Device Rules amendments. Maharashtra and Karnataka state laboratory licensing fragmentation delays commercial scale-up despite federal regulatory acceleration. Delhi-NCR tertiary centers anchor hereditary risk assessment demand through established genetic counseling infrastructure for Lynch syndrome cascade testing.
Australia
New South Wales and Victoria regional health authorities fast-track NGS platform accreditation to reduce sample send-out delays for targeted therapy selection. TGA alignment with EU MDR transition timelines adds compliance complexity for multinational kit suppliers. Medicare Benefits Schedule revisions for blood-based screening and multi-cancer early detection panel pilots expand reimbursement eligibility beyond traditional fecal occult blood testing protocols.
South Korea
Gyeonggi Province and Seoul Capital Area pathology departments decentralize comprehensive genomic profiling from centralized reference laboratories into mid-tier hospitals. MFDS regulatory frameworks support this geographic compression of testing capability. Busan-Ulsan manufacturing clusters supply automated nucleic acid extraction systems to laboratories retrofitting legacy PCR infrastructure for high-complexity molecular workflows.
Asia-Pacific Colorectal Cancer Diagnostics Market Competitive Environment
The competitive structure tilts toward integrated diagnostics conglomerates with centralized laboratory automation platforms. Swiss and German multinationals anchor high-throughput molecular workflows through sample-to-insight system integration, while American sequencing specialists compete on panel accessibility. Three archetypes dominate: full-workflow integrators bundling hardware, reagents, and analytics; platform-agnostic assay developers; and point-of-care screening specialists. Consolidation pressure manifests through multi-year service contracts displacing traditional distributor networks, and through software-as-a-service revenue models for AI-assisted detection algorithms.
Among Swiss-based full-workflow integrators, F. Hoffmann-La Roche Ltd occupies a position exemplifying centralized lab automation dominance across Japanese hospital networks. American sequencing platform developers Illumina Inc and Thermo Fisher Scientific Inc represent the accessibility-focused archetype, with the former extending NGS panel reach into mid-tier South Korean and Australian laboratories. German sample-to-insight specialists QIAGEN anchor PCR and sample preparation integration in Chinese reference laboratories processing ten-thousand-plus samples monthly.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Illumina Inc |
| QIAGEN |
| Thermo Fisher Scientific Inc |
| Abbott Laboratories |
| GE HealthCare Technologies Inc |
| Becton Dickinson & Co |
| Siemens Healthineers AG |
| Exact Sciences Corporation |
| Others |
Value Chain & Pricing Dynamics
Japan's carbon neutrality targets for healthcare facilities are tightening procurement standards for endoscopy hardware and molecular diagnostics platforms, restricting qualified supplier pools to manufacturers with verified lifecycle emissions data and compressing premium-tier pricing access for uncertified equipment vendors across Tokyo and Osaka hospital networks.
Pricing Analysis
Three-year framework agreements bundling reagent supply with analyzer placement dominate hospital procurement across Beijing and Shanghai municipal health systems. Price differentiation separates PMDA-validated companion diagnostics from NMPA-bridged molecular assays, with certification tier and after-sales service bundling driving premium positioning. Cost compression in reusable colonoscope hardware is intensifying because Chinese manufacturing consortia are commoditizing capital equipment, forcing Japanese and German vendors toward disposable accessory revenue streams. Tier-2 and tier-3 Indian laboratories exhibit highest price sensitivity, while Japan's urban prefecture hospitals prioritize throughput guarantees over unit cost.
Supply Chain Analysis
Direct manufacturer-contractor relationships with hospital procurement consortia are displacing traditional distributor networks across China's Yangtze River Delta. Supply concentrates in Germany, Switzerland, and Japan for high-throughput molecular workflow components, with South Korean and Chinese manufacturers supplying automated nucleic acid extraction systems. Raw material dependencies include optical sensors for colonoscopy systems, PCR reagents, and specialized plastics for disposable biopsy channels. Single-source vulnerability in fluorescence dye supply for immunohistochemistry creates bottleneck risk during screening campaign surges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
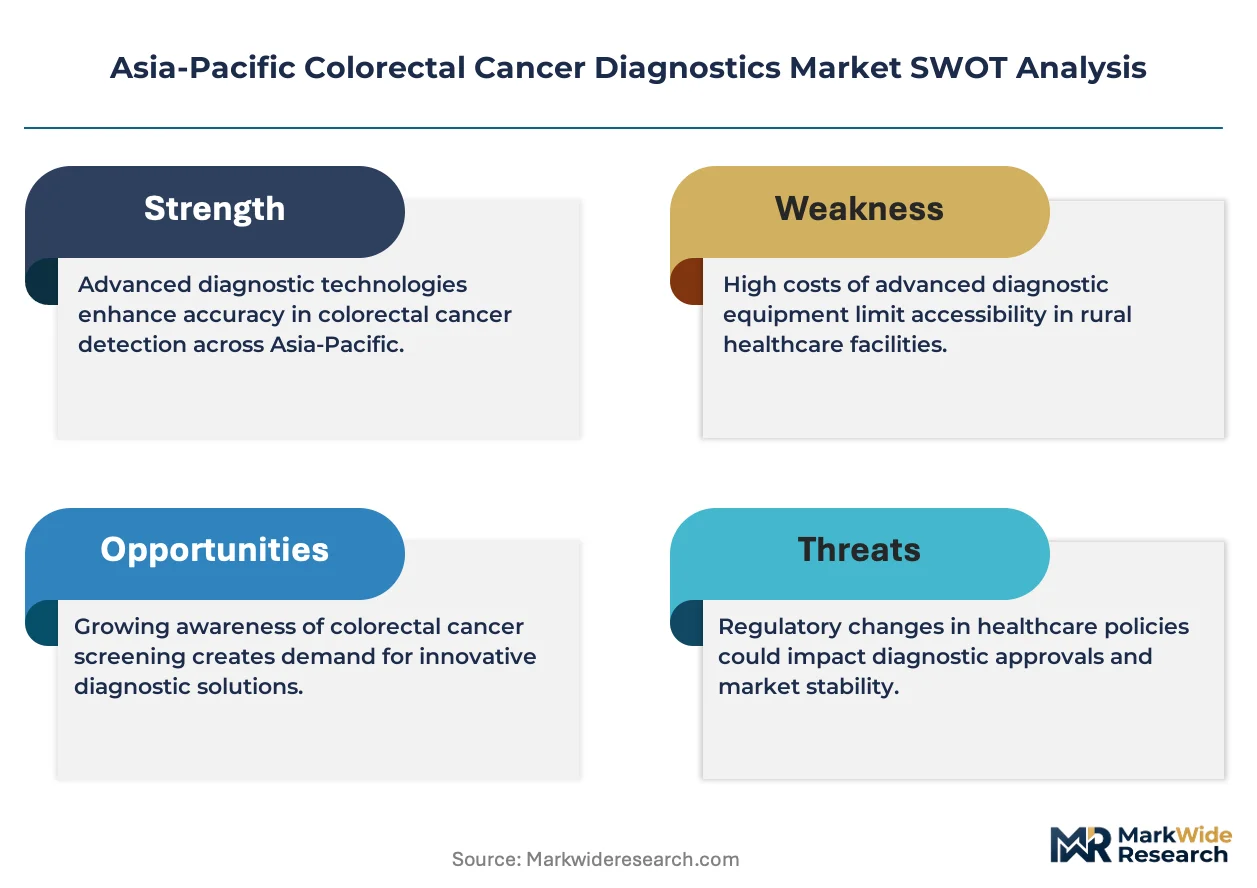
This market reads as a late-cycle quality story where reimbursement pathways for blood-based screening and multi-cancer early detection panels are pulling demand toward premium-sensitivity liquid biopsy platforms over commodity stool-based methods.
For Market Incumbents: Cement workflow integration advantages by deepening captive clinical research organization capacity in Tokyo and Osaka to satisfy PMDA's prospective validation mandates. Lock in multi-year reagent supply contracts with Beijing and Shanghai municipal health systems before NMPA tightens bridging study acceptance for novel biomarker panels, defending against mid-tier NGS entrants from South Korea.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium Swiss-German integrated systems and economy Chinese colonoscope manufacturers creates positioning room for portable fecal immunochemical testing platforms targeting Vietnam and Indonesia pharmacy retail chains. Penetrate Southeast Asian outpatient screening networks through distributor partnerships with local pharmaceutical wholesalers, avoiding direct competition with entrenched hospital procurement consortia in tier-1 Chinese cities.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier diagnostic laboratory networks because Australia's Sonic Healthcare and Japan's BML demonstrate scalable high-throughput workflow standardization across regional hospital catchments. Target platform-agnostic assay developers with NMPA bridging study capabilities and established Chinese reference lab relationships. Watch Australia's Medicare Benefits Schedule revisions for multi-cancer early detection panel reimbursement codes as inflection indicator for liquid biopsy platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Three-year framework agreements with Beijing municipal health systems lock in multi-year reagent revenue streams. |
| Software Companion Development | AI-assisted polyp detection algorithms create SaaS revenue displacing per-procedure physician costs in Japanese endoscopy suites. |
| Reimbursement Strategy | Medicare Benefits Schedule pilot codes for blood-based screening expand addressable populations beyond fecal occult blood testing. |
| CE Marking Pathway | TGA alignment with EU MDR transition timelines requires parallel regulatory investment for Australian market entry. |
| Regulatory Approval Pathway | PMDA's tightened companion diagnostics guidance demands Japan-specific clinical data generation through captive CRO arrangements. |
Study Parameters
Bottom-up hospital laboratory modeling reconciled against top-down molecular diagnostics platform shipment tracking forms the analytical core. Primary interviews with hospital procurement managers, pathology department heads, biomedical engineers, and GPO contracts managers were validated against secondary sources including PMDA approval databases, NMPA bridging study filings, Australia's Medicare Benefits Schedule revisions, and hospital tender documentation from Beijing and Shanghai municipal health systems.
Historical trendline analysis of screening volume growth and technology substitution patterns across the projection horizon informed segment-level CAGRs. Segmentation dimensions modeled include product type, technology platform, end-user facility tier, and application purpose. Industry-specific forecast inputs incorporated liquid biopsy sensitivity threshold improvements and evolving reimbursement eligibility for blood-based screening protocols.
Caveats apply where PMDA regulatory tightening, NMPA bridging study policy shifts, or Australia's Medicare Benefits Schedule revisions could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Global Clinical Oncology NGS Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market