
 Personalized Medicine Market | 2026-2036
Personalized Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Personalized Medicine Market Intelligence
The EU Green Deal is rebalancing procurement criteria across European healthcare systems toward molecular diagnostics with verified carbon footprints. Illumina, Inc. leverages its installed base of sequencing platforms to sustain consumable revenue streams across clinical laboratories. Roche anchors its position through integrated companion diagnostic development alongside pharmaceutical pipelines. Danaher Corporation competes via vertical integration into sample preparation workflows that feed downstream analytics.
Personalized medicine tailors prevention, diagnosis, and treatment to individual genetic profiles, molecular biomarkers, and phenotypic data using validated assay platforms with defined analytical sensitivity thresholds. Its primary purpose is to improve therapeutic efficacy while reducing adverse drug reactions through stratified patient selection. Companion diagnostics occupies the highest-margin tier within product type segmentation, as payers increasingly require biomarker confirmation before reimbursing targeted therapeutics. Next-generation sequencing leads technology adoption in oncology applications, while pharmacogenomics segments show accelerating uptake in cardiovascular and neurological indications as clinical evidence accumulates.
FDA companion diagnostic guidance, EMA biomarker qualification procedures, and HIPAA data privacy requirements collectively shape trial design, market access pathways, and cross-border data sharing architectures for molecular profiling services. The EU AI Act introduces additional conformity obligations for algorithmic diagnostic tools that interpret genomic variants or predict drug response. Stakeholders must monitor evolving reimbursement frameworks for multi-gene panel tests and prepare for interoperability mandates that will determine competitive positioning in integrated health data ecosystems.
Market Dynamics
Medicare coverage expansion for molecular profiling tests is pulling pharmacogenomics from academic medical centers into community oncology practices, compressing validation timelines and forcing platform consolidation.
Growth Catalysts
- Biomarker qualification pathways:EMA's streamlined procedures accelerate companion diagnostic co-development timelines. Pharmaceutical sponsors now embed molecular profiling earlier in clinical trial design.
- Cardiovascular pharmacogenomics:CYP2C19 genotyping for antiplatelet therapy selection is expanding beyond interventional cardiology into primary prevention programs.
- United States reimbursement momentum:Medicare Administrative Contractors are issuing favorable local coverage determinations for multi-gene panel tests in solid tumors.
Market Restraints
- Reagent supply concentration:Three vendors control over 80 percent of certified reference materials for pharmacogenomic assays, creating single-source vulnerability.
- HIPAA-GDPR friction:Cross-border genomic data sharing for multi-site clinical trials requires duplicative consent architectures and redundant infrastructure.
- Long-read sequencing cost structure:PacBio and Oxford Nanopore consumables remain 4-6x Illumina short-read chemistry on per-sample basis.
Strategic Opportunities
- Rare disease undiagnosed populations:Whole exome sequencing penetration in pediatric neurology clinics remains below 15 percent in most health systems.
- EU AI Act algorithmic diagnostics:Conformity assessment pathways for variant interpretation software create first-mover advantage for validated platforms.
- Direct-to-consumer pharmacogenomics:Employer wellness programs are piloting CYP and SLCO1B1 testing for statin selection as covered benefit.
Industry Challenges
- Bioinformatics pipeline standardization:Variant calling algorithms produce discordant results across laboratories, undermining clinical confidence.
- Liquid biopsy analytical validation:Cell-free DNA assay sensitivity thresholds vary by tumor fraction, complicating regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized Medicine Market |
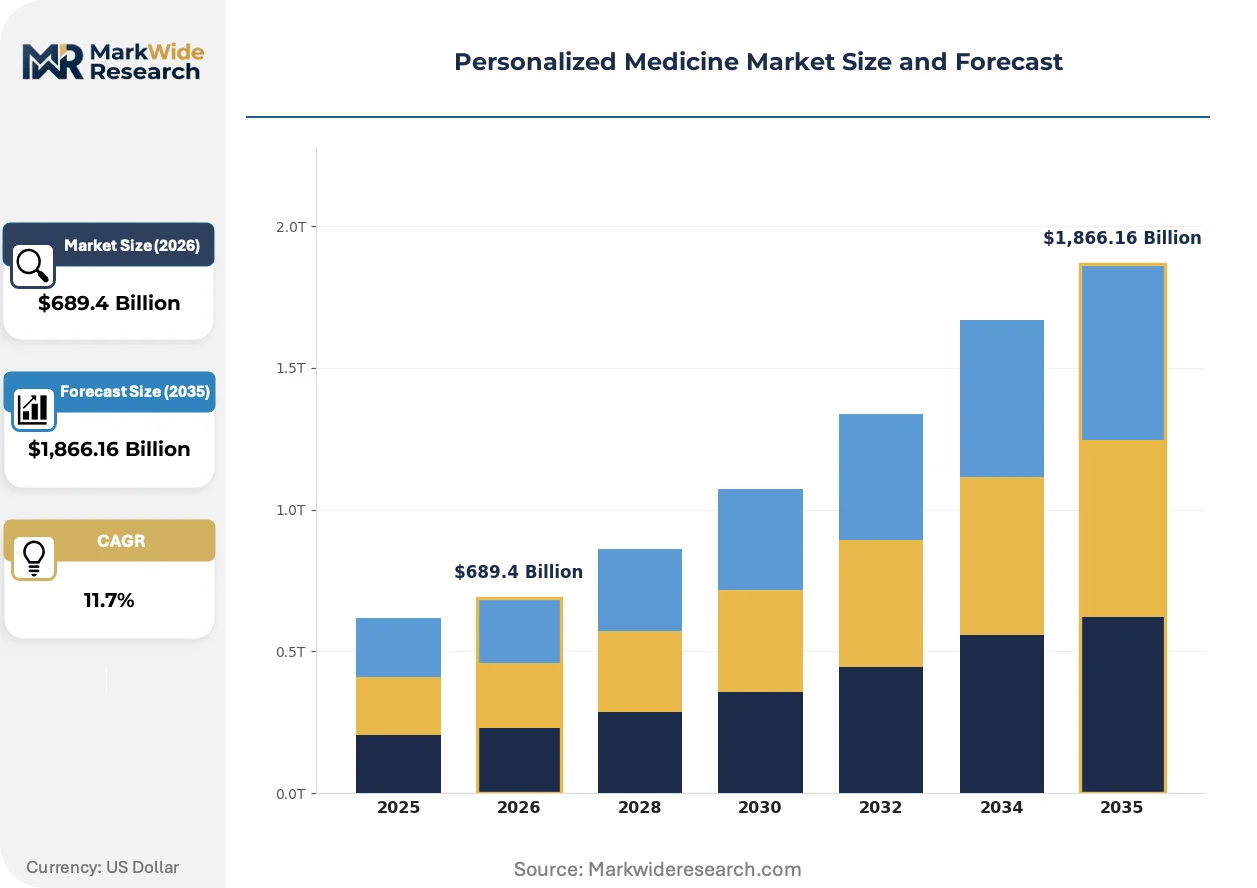
| Market Size in 2026 | $689.4 Billion |
| Market Size in 2035 | $1,866.16 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Companion Diagnostics, Targeted Therapeutics, Pharmacogenomics, Biomarker Testing, Gene Therapy Technology: Next-Generation Sequencing, PCR, Microarray, Proteomics, Digital Pathology Application: Oncology, Rare Disorders, Infectious Diseases, Cardiovascular Conditions, Neurological Disorders End User: Research Institutes, Diagnostic Laboratories, Pharmaceutical Companies, Specialty Clinics, Biotech Startups |
| Companies Covered | Illumina, Inc., GE Healthcare, Abbott Laboratories, Roche, Danaher Corporation, Exact Sciences Corporation, QIAGEN, Novartis AG, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized Medicine Market Strategic Shifts & Innovations
Multi-omics data integration is collapsing the traditional sequential workflow of biomarker discovery, diagnostic development, and therapeutic matching into simultaneous processes. Platform vendors and pharmaceutical sponsors are restructuring collaboration models around real-time evidence generation.
Artificial intelligence variant interpretation tools are rewriting how clinical laboratories process genomic sequencing data. Community hospital networks lacking in-house bioinformatics capacity are outsourcing tertiary analysis to cloud-based platforms. This compression is enabling mid-tier laboratories to offer equivalent test menus to academic medical centers without comparable capital deployment.
The EU AI Act's risk classification system for medical device software imposes conformity obligations on algorithms predicting drug response from polygenic scores. Diagnostic developers must maintain technical documentation and post-market surveillance systems previously required only for hardware devices. Oncology applications face the most stringent scrutiny given the high-risk classification of treatment selection algorithms.
Hospital procurement committees are unbundling molecular diagnostic service contracts from reference laboratory agreements. Health systems are bringing pharmacogenomic testing in-house while maintaining send-out relationships for esoteric oncology panels. This bifurcation is most pronounced in United States integrated delivery networks where laboratory medicine departments report directly to chief medical officers rather than supply chain functions.
Personalized Medicine Market Segmentation
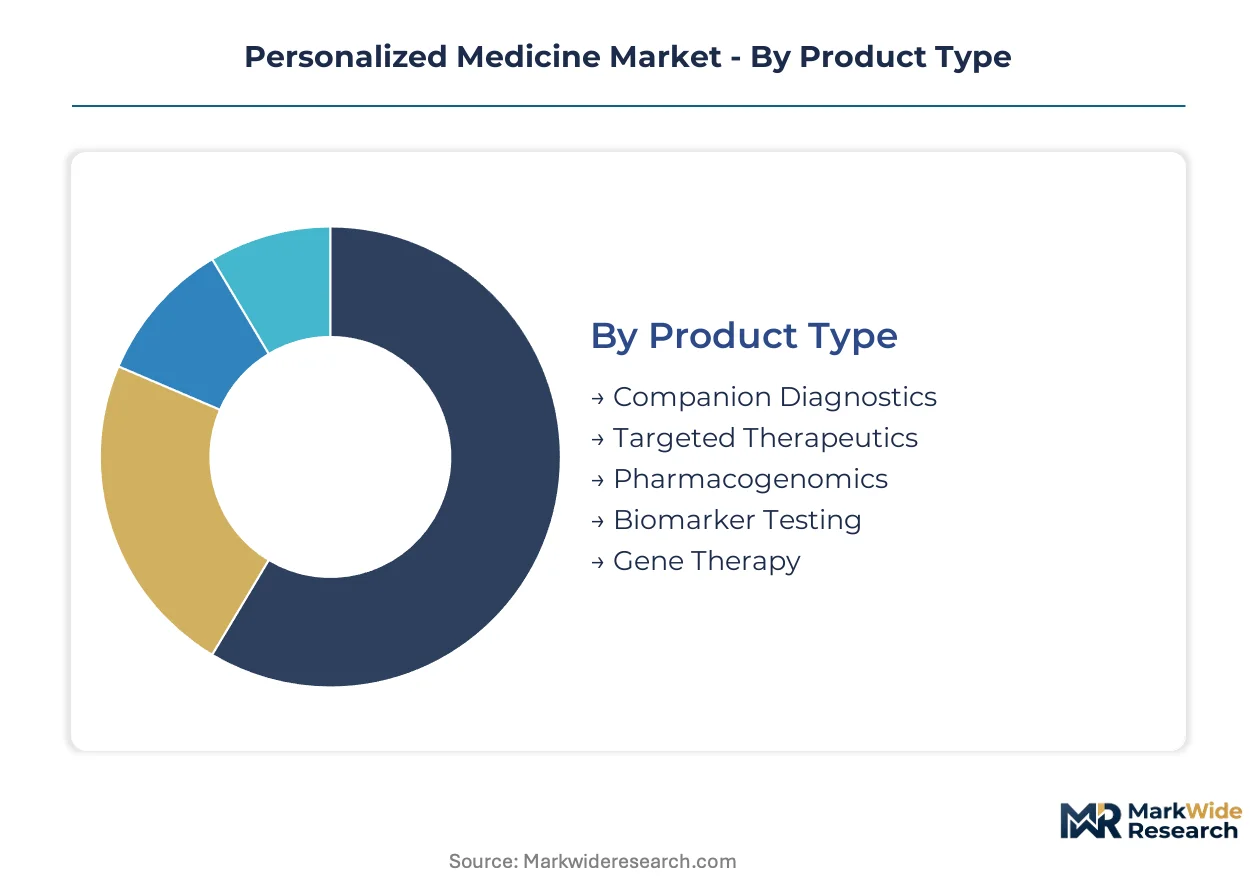
Segmentation in personalized medicine reveals distinct margin profiles and technology readiness levels across product categories. Each dimension carries specific regulatory pathways and capital intensity requirements that shape competitive entry points.
Product Type:
Companion diagnostics command premium pricing through mandatory co-development with therapeutics, while pharmacogenomics scales through volume-driven testing protocols.
- Companion Diagnostics:These assays require simultaneous FDA approval with targeted drugs, creating high barriers and captive revenue streams. Demand concentrates in United States oncology practices where Medicare coverage mandates biomarker confirmation before reimbursement.
- Pharmacogenomics:CYP450 and SLCO1B1 genotyping platforms process high sample volumes with lower per-test margins. Deployment is accelerating in United States cardiovascular clinics and employer wellness programs seeking statin selection guidance.
- Targeted Therapeutics:Biologic agents matched to molecular profiles through validated companion tests.
- Biomarker Testing:Protein and circulating nucleic acid assays supporting trial stratification and monitoring.
- Gene Therapy:Curative interventions requiring pre-treatment molecular profiling for patient eligibility.
Mature deployment sits with companion diagnostics. Newer deployment is concentrated in pharmacogenomics.
Technology:
Platform selection determines consumable economics and bioinformatics infrastructure requirements across laboratory networks.
- Next-Generation Sequencing:Short-read platforms from Illumina dominate solid tumor profiling with established reimbursement codes. United States academic medical centers are standardizing on these systems for multi-gene panels.
- PCR:Real-time and digital PCR methods deliver rapid turnaround for single-gene pharmacogenomic queries. Community hospital laboratories favor this technology for CYP2C19 and warfarin sensitivity testing.
- Microarray:SNP genotyping platforms support polygenic risk scoring and ancestry-informed pharmacogenomics.
- Proteomics:Mass spectrometry-based protein quantification enables biomarker discovery and companion diagnostic development.
- Digital Pathology:Whole-slide imaging with AI-assisted analysis supports morphological biomarker quantification.
Installed base concentration favors next-generation sequencing. Fastest capability expansion is occurring in digital pathology.
Application:
Disease area selection dictates regulatory complexity and payer coverage evolution for molecular profiling services.
- Oncology:Solid tumor and hematologic malignancy profiling represents the most reimbursed indication category. United States Medicare Administrative Contractors have issued favorable local coverage determinations for comprehensive genomic profiling.
- Cardiovascular Conditions:Antiplatelet and statin pharmacogenomics is gaining traction in interventional cardiology. United States integrated delivery networks are piloting CYP2C19 testing for clopidogrel selection.
- Rare Disorders:Whole exome sequencing for undiagnosed pediatric conditions remains underpenetrated.
- Infectious Diseases:Pathogen genotyping guides antimicrobial selection and resistance monitoring.
- Neurological Disorders:Pharmacogenomic testing for antidepressant and antiepileptic selection is emerging.
Reimbursement maturity centers on oncology. Steepest expansion trajectory is occurring in cardiovascular applications.
End User:
Customer type determines sales cycle length, technical support requirements, and contract structuring for platform vendors.
- Diagnostic Laboratories:Reference and hospital-based labs represent the highest volume channel with consolidated purchasing power. United States health systems are unbundling molecular testing from legacy reference contracts.
- Pharmaceutical Companies:Sponsors fund companion diagnostic co-development and embed molecular profiling in clinical trials. EMA biomarker qualification procedures are accelerating their investment in diagnostic partnerships.
- Research Institutes:Academic medical centers drive technology adoption and evidence generation.
- Specialty Clinics:Oncology and cardiology practices are bringing targeted testing in-house.
- Biotech Startups:Emerging therapeutics developers require outsourced diagnostic development capabilities.
Procurement sophistication is highest with pharmaceutical companies. In-house capability building is most pronounced among specialty clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge corridor anchors North American personalized medicine activity, hosting dense concentrations of sequencing platform developers, companion diagnostic laboratories, and pharmaceutical research campuses that shape procurement patterns across hospital networks.
United States
Medicare Administrative Contractors issued favorable local coverage determinations for comprehensive genomic profiling in solid tumors, pulling molecular diagnostics from academic centers into community oncology practices. The FDA's companion diagnostic guidance accelerates biomarker validation timelines for co-developed therapeutics. The Research Triangle Park in North Carolina concentrates pharmacogenomics implementation programs for cardiovascular applications.
Germany
University hospital networks in Heidelberg and Munich are standardizing multi-gene panel testing for oncology patients, creating reference demand for sequencing consumables. The EMA's biomarker qualification procedures streamline companion diagnostic co-development with pharmaceutical sponsors. The Rhine-Main biotech cluster around Frankfurt hosts specialized laboratories performing liquid biopsy analytical validation for regulatory submission support.
Switzerland
Basel's pharmaceutical headquarters drive outsourced companion diagnostic development partnerships with specialized assay developers. Swissmedic maintains aligned review procedures with EMA for molecular profiling device approvals, reducing redundant conformity assessments. The Zurich ETH campus concentrates research activity in AI-assisted variant interpretation algorithms subject to EU AI Act risk classification.
United Kingdom
The NHS Genomic Medicine Service consolidates rare disease testing through designated laboratory hubs in Manchester and Birmingham, standardizing whole exome sequencing protocols. MHRA post-Brexit regulatory autonomy permits accelerated access pathways for innovative diagnostics. The Cambridge-AstraZeneca partnership anchors companion diagnostic co-development for oncology pipelines targeting European markets.
Japan
PMDA's Sakigake designation system accelerates approval timelines for companion diagnostics matched to breakthrough therapeutics in lung and gastric cancers. METI funding programs support pharmacogenomics infrastructure deployment in regional medical centers outside Tokyo. The Osaka-Kobe biomedical cluster concentrates diagnostic platform manufacturing serving Asia-Pacific reference laboratories.
Personalized Medicine Market Key Industry Players
The competitive structure tilts toward platform vendors with installed base concentration and pharmaceutical-anchored diagnostic developers. Three vendor archetypes dominate: sequencing instrument manufacturers capturing consumable revenue streams, integrated diagnostic-therapeutic developers leveraging co-development mandates, and specialized assay providers targeting pharmacogenomics volume applications. Consolidation moves center on laboratory service acquisitions and bioinformatics capability integration.
Among platform-centric developers, Illumina, Inc. and Roche exemplify contrasting strategic positions within the sequencing and companion diagnostic segments respectively. Danaher Corporation occupies a position emphasizing sample preparation workflow integration that feeds downstream analytical processes. These three entities represent the dominant competitive archetypes shaping procurement negotiations with hospital networks and pharmaceutical sponsors.
| Leading Market Players |
|---|
| Illumina, Inc. |
| GE Healthcare |
| Abbott Laboratories |
| Roche |
| Danaher Corporation |
| Exact Sciences Corporation |
| QIAGEN |
| Novartis AG |
| AstraZeneca |
| Others |
Cost & Logistics Intelligence
Next-generation sequencing platform consolidation is compressing per-sample costs while concentrating consumable pricing power among three dominant vendors. This technological transition simultaneously reduces capital barriers for mid-tier laboratories and locks downstream buyers into proprietary reagent ecosystems.
Pricing Analysis
Outcome-linked reimbursement anchors pricing for companion diagnostics, with Medicare coverage determinations validating biomarker confirmation as a mandatory gatekeeper for targeted therapy access. Pricing stratifies across FDA-cleared companion assays, laboratory-developed tests, and research-use-only panels based on regulatory certification tier and clinical evidence depth. Cost compression in pharmacogenomics volumes is intensifying because CYP450 testing protocols are standardizing around automated platforms. Community hospital laboratories exhibit highest price sensitivity, while pharmaceutical sponsors demonstrate lowest sensitivity due to co-development cost absorption.
Supply Chain Analysis
Direct-to-laboratory channels handle sequencing instrument and consumable demand from United States academic medical centers and European hospital networks. Certified reference materials for pharmacogenomic assays draw from United States, Germany, and Switzerland, where three vendors control over four-fifths of supply. Reagent manufacturing rests on fluorophore chemistries, polymerase enzymes, and synthetic oligonucleotide inputs. Single-source vulnerability in certified reference materials poses structural risk. Distribution runs through platform vendors' captive logistics networks and specialized cold-chain partners serving clinical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform vendor consolidation is forcing smaller assay developers into acquisition or exit, as installed base concentration determines consumable revenue capture.
For Market Incumbents: Deploy bioinformatics pipeline acquisitions to lock in tertiary analysis workflows before cloud-based platforms commoditize variant interpretation. Incumbent sequencing platform vendors should secure exclusive reagent supply agreements with pharmacogenomics reference material producers to preempt competitor access. FDA guidance on companion diagnostic co-development creates regulatory moats that pharmaceutical sponsors will pay premiums to navigate. For New Entrants and Emerging Players: The gap between premium companion diagnostic pricing and economy-tier pharmacogenomics testing creates entry space for mid-market assay developers. White-space targets include cardiovascular pharmacogenomics in United States integrated delivery networks and AI-assisted variant interpretation software qualifying under EU AI Act conformity pathways. Pediatric neurology whole exome sequencing offers the most penetrable application segment. A go-to-market angle anchored in employer wellness program direct contracting bypasses hospital procurement consolidation. For Investors and Strategic Acquirers: Re-rating potential sits with specialized pharmacogenomics assay developers given Medicare coverage expansion for multi-gene panel tests. Long-term viability favors entities with dual capability in wet-lab assay development and regulatory submission infrastructure. Acquisition target archetypes include laboratories with validated liquid biopsy analytical validation packages and bioinformatics firms with EU AI Act technical documentation systems. The signal to watch is local coverage determination velocity from Medicare Administrative Contractors as inflection indicator for reimbursement momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | EMA biomarker qualification procedures accelerate parallel FDA submission pathways for oncology therapeutics. |
| Pharmacogenomics Platform Integration | United States hospital networks unbundle molecular testing from legacy reference laboratory agreements. |
| EU AI Act Conformity Assessment | Swissmedic-aligned review procedures reduce redundant documentation for algorithmic diagnostic tools. |
| Sample Preparation Workflow Acquisition | Vertical control over nucleic acid extraction feeds downstream sequencing consumable demand. |
| Direct-to-Employer Wellness Contracting | Employer-sponsored CYP450 and SLCO1B1 testing bypasses traditional hospital procurement channels. |
Research Approach
Multi-period observation of Medicare coverage determination issuance, EMA biomarker qualification timelines, and pharmacogenomics test volume trends anchored the trend analysis, supplemented by interviews with clinical laboratory directors, companion diagnostic development executives, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA 510(k) and PMA filings, EMA scientific advice letters, ClinicalTrials.gov protocol registrations, and CMS local coverage determination databases. Bottom-up test volume modeling and top-down market sizing triangulated value estimates.
Segment-weighting across product type, technology platform, application area, and end-user channel informed the analytical framework over the projection horizon. Oncology companion diagnostics, cardiovascular pharmacogenomics, and neurological rare disease testing represented the primary segmentation dimensions. CAGRs were derived from test volume trajectory analysis and reimbursement code valuation trends. Forecast inputs incorporated Medicare Administrative Contractor decision velocity and EU AI Act implementation timing for algorithmic diagnostics.
Inputs from regulatory filing databases and hospital procurement contract records were available through the study window; gaps in real-time commercial test volume reporting introduce uncertainty bands around near-term estimates. Forecasts reflect assumptions regarding reimbursement expansion continuity and biomarker validation success rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Progressive Pulmonary Fibrosis (PPF) Treatment Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
North America Precision Medicine Market