
 Pancreatic Cancer Diagnostics Market | 2026-2036
Pancreatic Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Pancreatic Cancer Diagnostics Market Outlook
Modular assay bundling is realigning how hospital procurement teams evaluate pancreatic cancer diagnostic platforms. Siemens Healthineers leverages its integrated imaging-to-molecular workflow to anchor multi-year service contracts with academic medical centers. Thermo Fisher Scientific competes through captive supply of reagent chemistries that lock in consumable revenue streams across installed bases.
Pancreatic cancer diagnostics encompasses blood-based biomarker detection, cross-sectional imaging modalities, tissue histopathology, and germline or somatic mutation profiling used to identify, stage, and monitor ductal adenocarcinoma. CT scan technology dominates initial detection workflows due to widespread insurance coverage and sub-millimeter spatial resolution for evaluating vascular involvement. Genetic testing represents the fastest-expanding segment as multi-gene panels for BRCA1, BRCA2, and PALB2 mutations guide PARP inhibitor eligibility and familial screening protocols.
The FDA breakthrough device program and Medicare's national coverage determination framework jointly shape reimbursement access for novel pancreatic cancer assays. EMA's in vitro diagnostic regulation imposes stricter clinical evidence requirements for CE-marked biomarker tests entering European laboratories. Stakeholders must monitor evolving payer evidence thresholds that increasingly demand prospective clinical utility data beyond analytical validation.
Market Dynamics
Liquid biopsy protocols are compressing diagnostic timelines from tissue acquisition to treatment initiation, forcing hospital laboratories to reconfigure molecular pathology workflows around cell-free DNA extraction platforms.
Growth Catalysts
- Medicare national coverage determination:Expanded reimbursement for companion diagnostic testing in the United States reduces out-of-pocket burden for patients undergoing BRCA mutation profiling. Academic medical centers accelerate adoption of multi-gene panels.
- CT scanner density:Sub-millimeter spatial resolution capabilities in cross-sectional imaging enable vascular involvement assessment without invasive staging laparoscopy. Community hospitals upgrade installed bases.
- PARP inhibitor eligibility expansion:Germline testing for BRCA1, BRCA2, and PALB2 mutations creates downstream demand for somatic confirmation assays. Oncology practices integrate testing into standard care pathways.
Market Restraints
- Reagent chemistry concentration:Captive supply agreements for proprietary PCR master mixes and sequencing consumables lock laboratories into single-vendor dependencies. Thermo Fisher Scientific controls critical input channels.
- EMA in vitro diagnostic regulation:Stricter clinical evidence requirements for CE-marked biomarker tests delay European commercialization timelines. Manufacturers must generate prospective utility data beyond analytical validation.
- Tissue acquisition failure rates:Anatomical location and desmoplastic stroma limit successful biopsy yield in up to 30% of suspected cases. Liquid biopsy remains supplementary rather than substitutive.
Strategic Opportunities
- FDA breakthrough device designation:Accelerated review pathways for novel biomarker assays compress time-to-market for pancreatic cancer-specific methylation signatures. Early-stage developers prioritize this route.
- Integrated imaging-to-molecular workflow:Siemens Healthineers anchors multi-year service contracts by bundling CT staging with downstream genetic testing protocols. Academic medical centers value seamless data integration.
- Germline cascade screening:Familial testing protocols for at-risk relatives extend addressable volume beyond index patients. Genetic counseling services expand into community oncology settings.
Industry Challenges
- Molecular pathologist scarcity:Specialized expertise in somatic mutation interpretation and variant classification bottlenecks laboratory throughput. Training programs fail to match demand growth.
- Liquid biopsy analytical validation:Low mutant allele fractions in early-stage disease require ultra-sensitive detection platforms. False-negative rates complicate clinical utility demonstrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancreatic Cancer Diagnostics Market |
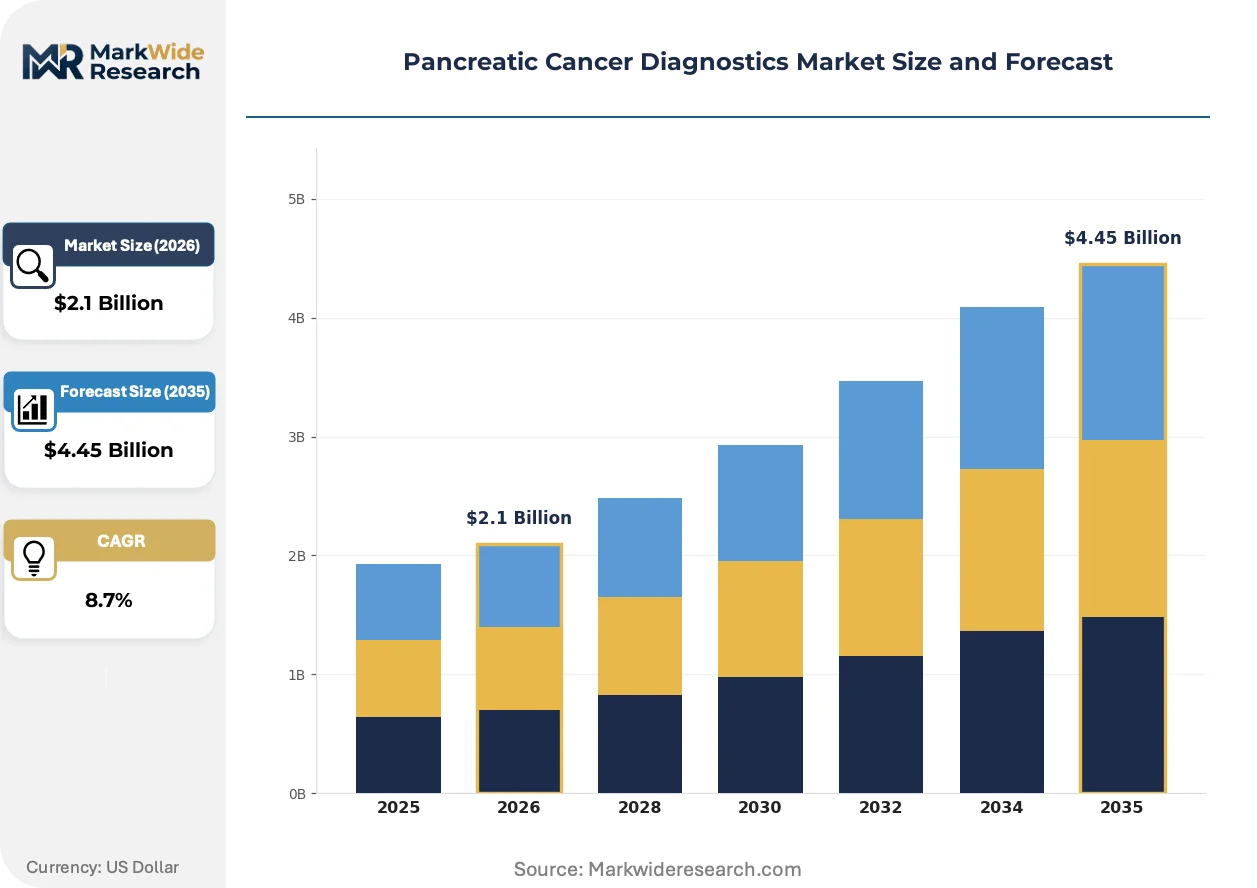
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Blood Tests, Imaging Techniques, Biopsy, Genetic Testing Technology: CT Scan, MRI, Endoscopic Ultrasound, PET Scan End User: Hospitals, Diagnostic Laboratories, Research Institutes, Clinics Application: Screening, Monitoring, Staging, Risk Assessment |
| Companies Covered | Siemens Healthineers, GE Healthcare, F. Hoffmann-La Roche, Koninklijke Philips, Thermo Fisher Scientific, QIAGEN, Illumina, Abbott Laboratories, Myriad Genetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancreatic Cancer Diagnostics Market Strategic Shifts
Diagnostic platforms are converging around single-vendor ecosystems that compress procurement complexity while locking in consumable revenue streams. Three developments are restructuring competitive positioning.
Next-generation sequencing-based liquid biopsy panels are unifying detection of circulating tumor DNA, methylation markers, and protein biomarkers into single blood draws. Hospital-based diagnostic laboratories adopt these multiplexed workflows to reduce patient visits and accelerate turnaround times. The technology is unifying what previously required separate tissue biopsy, imaging, and serum chemistry workflows into coordinated molecular pathology protocols.
The FDA breakthrough device designation pathway compresses premarket review timelines for pancreatic cancer methylation assays and AI-augmented imaging classifiers. Manufacturers must still generate Medicare coverage evidence through prospective clinical utility studies. Multi-gene panel developers prioritize United States launch sequences to capture reimbursement traction before European CE-marking.
Oncology practices are consolidating diagnostic procurement around integrated service contracts that bundle imaging, pathology, and molecular testing under single vendor relationships. Independent reference laboratories lose volume to health system captive laboratories with in-house NGS platforms. This concentration is most visible in United States metropolitan markets where academic medical centers anchor regional referral networks.
Pancreatic Cancer Diagnostics Market Segmentation
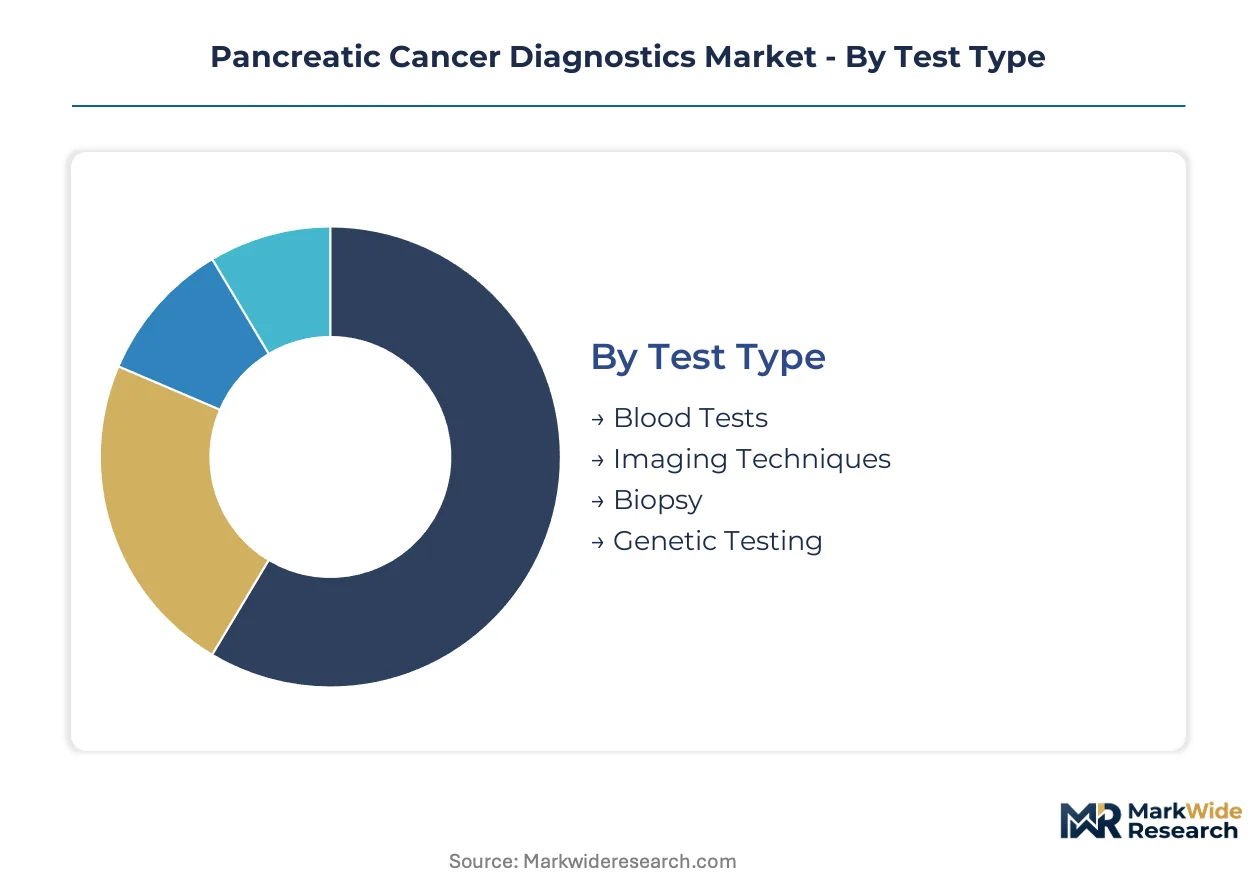
Pancreatic cancer diagnostics require precise matching of test modality to clinical intent. Segmentation reveals where capital-intensive imaging infrastructure concentrates versus where emerging molecular assays gain procedural traction.
Test Type:
Customization spans from standardized imaging protocols to patient-specific multi-omics panels that integrate germline and somatic data streams.
- Imaging Techniques:Cross-sectional modalities deliver sub-millimeter spatial resolution for vascular involvement assessment. Community hospitals in the United States upgrade CT scanner density to reduce staging laparoscopy referrals.
- Genetic Testing:Multi-gene panels for BRCA1, BRCA2, and PALB2 mutations guide PARP inhibitor eligibility and cascade screening protocols. Academic medical centers integrate somatic confirmation assays into standard care pathways.
- Blood Tests:Liquid biopsy protocols measuring circulating tumor DNA and methylation signatures compress diagnostic timelines.
- Biopsy:Tissue acquisition remains the confirmatory standard despite anatomical challenges and desmoplastic stroma limitations.
Leading the category by volume: Imaging Techniques. Expanding most quickly: Genetic Testing.
Technology:
Cost tiers separate premium molecular imaging from commodity anatomical staging tools.
- CT Scan:Sub-millimeter resolution capabilities enable vascular assessment without invasive procedures. Medicare reimbursement coverage drives installed base expansion across United States community hospitals.
- Endoscopic Ultrasound:Tissue acquisition platform with therapeutic intervention capability for biliary drainage. High-volume pancreaticobiliary centers in the United States anchor regional referral networks.
- MRI:Soft tissue contrast superior to CT for liver metastasis detection and treatment response monitoring.
- PET Scan:Metabolic imaging for distant metastasis identification and neoadjuvant therapy response assessment.
Highest procedure volume: CT Scan. Steepest expansion trajectory: Endoscopic Ultrasound.
End User:
Customer type determines procurement complexity from integrated health systems to independent reference laboratories.
- Hospitals:Academic medical centers anchor multi-year service contracts bundling imaging-to-molecular workflows. Siemens Healthineers leverages integrated platforms to lock in consumable revenue streams.
- Diagnostic Laboratories:Hospital-based labs adopt NGS platforms to capture molecular pathology volume previously outsourced to independent reference laboratories.
- Research Institutes:Early-phase biomarker validation and clinical utility studies for FDA breakthrough device designation pathways.
- Clinics:Community oncology settings expanding genetic counseling services for familial cascade screening protocols.
Dominant volume concentration: Hospitals. Fastest infrastructure investment: Diagnostic Laboratories.
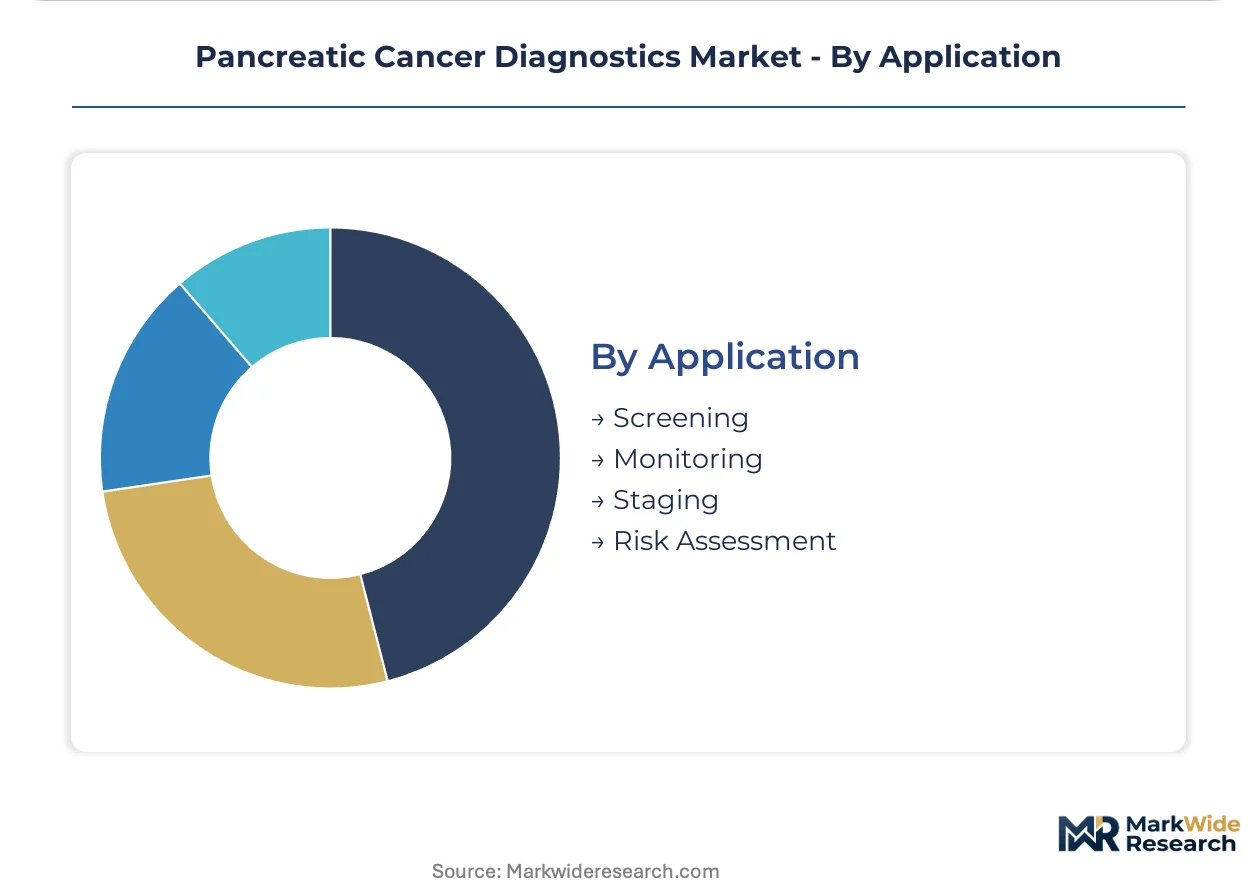
Application:
Clinical utility requirements vary sharply across the disease continuum from asymptomatic screening to metastatic monitoring.
- Staging:Determines resectability through vascular involvement assessment and metastasis detection. CT and EUS modalities coordinate to replace diagnostic laparoscopy in operable candidates.
- Screening:High-risk cohort identification through germline mutation profiling and familial history stratification. Cascade protocols extend testing to at-risk relatives of index patients.
- Monitoring:Liquid biopsy tracking of treatment response and acquired resistance mutations during PARP inhibitor therapy.
- Risk Assessment:Pre-symptomatic evaluation for hereditary pancreatic cancer syndromes in familial clusters.
Primary revenue concentration: Staging. Gaining share fastest: Screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic equipment production clusters in Germany and the United States while patient testing volume concentrates in American and Chinese hospitals. Consumption patterns diverge sharply between mature reimbursement systems and out-of-pocket markets.
United States
Medicare's national coverage determination for companion diagnostics drives multi-gene panel adoption at academic medical centers in Boston and Houston. FDA breakthrough device designations accelerate commercialization timelines for methylation assays. The Mayo Clinic anchors a Midwestern referral network that standardizes liquid biopsy protocols across twelve states.
Germany
Siemens Healthineers leverages domestic manufacturing scale to bundle CT staging with molecular workflows for university hospitals in Munich and Heidelberg. EMA in vitro diagnostic regulation imposes stricter clinical evidence requirements than FDA pathways. The Rhine-Ruhr corridor concentrates diagnostic imaging R&D with integrated supply chains reaching Dutch and Belgian laboratories.
China
NMPA regulatory pathways for innovative medical devices compress review timelines for domestic liquid biopsy developers in Shanghai and Shenzhen. Public hospital procurement reforms favor dual-source CT scanner acquisitions to reduce import dependency. The Yangtze River Delta anchors cell-free DNA platform manufacturing with downstream distribution across provincial cancer centers.
Japan
PMDA consultation programs guide pancreatic cancer assay developers through hybrid evidence requirements combining Japanese and Western clinical data. METI funding for precision medicine infrastructure expands NGS platform installation at National Cancer Center hospitals in Tokyo and Osaka. Kansai region bioclusters specialize in companion diagnostic co-development with domestic pharmaceutical manufacturers.
United Kingdom
NHS England's genomic medicine service mandates BRCA testing for all pancreatic cancer patients at tertiary referral centers in London and Manchester. NICE technology appraisals determine PARP inhibitor eligibility criteria that cascade into diagnostic demand. The Cambridge-Oxford arc concentrates early-stage methylation signature research with venture funding from national life sciences investment programs.
Pancreatic Cancer Diagnostics Market Competitive Environment
The competitive structure tilts toward integrated diagnostic conglomerates with captive imaging and molecular platforms. Siemens Healthineers and GE Healthcare anchor the imaging modality tier while Thermo Fisher Scientific controls reagent chemistry supply chains. Three archetypes dominate: full-stack platform vendors bundling hardware-to-consumables, specialized genetic testing laboratories, and reference labs competing on turnaround time. Consolidation moves center on multi-year service contracts with academic medical centers and vertical integration into proprietary assay chemistries.
Among the integrated platform vendors, Siemens Healthineers and GE Healthcare exemplify the imaging-to-molecular workflow archetype that locks hospital procurement into single-vendor ecosystems. Thermo Fisher Scientific occupies a distinct position controlling PCR master mix and sequencing consumable supply channels that create switching costs for laboratory customers. F. Hoffmann-La Roche represents the companion diagnostic co-development model that pairs assay approval with pharmaceutical therapy launches.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| F. Hoffmann-La Roche |
| Koninklijke Philips |
| Thermo Fisher Scientific |
| QIAGEN |
| Illumina |
| Abbott Laboratories |
| Myriad Genetics |
| Others |
Value Chain & Pricing Dynamics
Academic medical centers in the United States concentrate procurement authority through multi-year service contracts that bundle imaging hardware with molecular testing consumables. Siemens Healthineers leverages this buyer concentration to enforce premium pricing on integrated CT-to-NGS workflows while locking laboratories into proprietary reagent supply agreements.
Pricing Analysis
Margin tightening in consumable tiers reflects Thermo Fisher Scientific's captive control of PCR master mixes and sequencing chemistries that create single-vendor lock-in. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated methylation assays from CE-marked European equivalents and unvalidated research-use-only panels. Cost-down pressure on liquid biopsy platforms accelerates as hospital laboratories internalize NGS workflows previously outsourced to reference laboratories. Community oncology settings exhibit highest price sensitivity due to Medicare reimbursement uncertainty, while academic medical centers absorb premium pricing for integrated imaging-to-molecular bundles.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China coordinate hub-and-spoke patterns for CT scanner components, NGS platforms, and cell-free DNA extraction kits. Manufacturing concentration draws from German precision engineering for imaging hardware, American biotechnology clusters for assay development, and Chinese electronics assembly for sequencing instrument subcomponents. Single-source vulnerability in semiconductor supply for NGS flow cells creates bottlenecks during demand surges. Distribution runs through health system captive laboratories that bypass independent reference laboratories, compressing channel layers and concentrating volume with full-stack platform vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
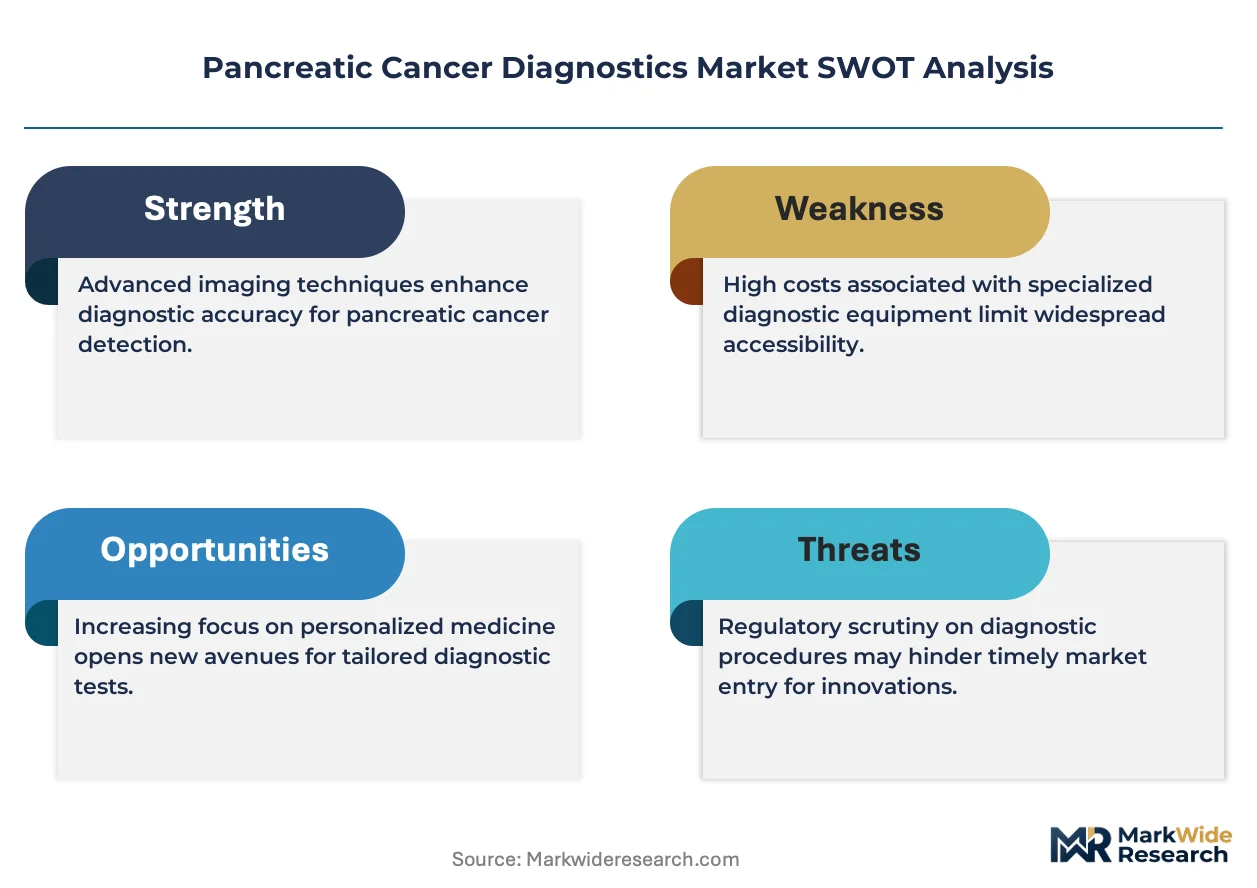
Pancreatic cancer diagnostics is consolidating around integrated platform vendors with captive imaging and molecular capabilities. EMA in vitro diagnostic regulation and Medicare evidence thresholds are forcing sub-scale assay developers toward acquisition or exit.
For Market Incumbents: Anchor multi-year service contracts by bundling CT staging hardware with downstream genetic testing protocols to deepen switching costs. Siemens Healthineers exemplifies this model across academic medical centers. Defend against liquid biopsy substitution by integrating cell-free DNA workflows into existing molecular pathology platforms rather than treating them as separate procurement categories. Certification investment in FDA breakthrough device designation creates regulatory moats that delay European and Asian competitor entry. For New Entrants and Emerging Players: The mid-tier pricing gap between premium integrated platforms and economy reference laboratory services opens white-space for targeted assay specialization. Focus initial penetration on germline cascade screening protocols in community oncology settings where genetic counseling services remain underdeveloped. Target hospital laboratories in the United States Medicare reimbursement corridors where companion diagnostic coverage reduces patient out-of-pocket burden and accelerates physician adoption. Partner with existing NGS platform installers rather than competing on capital equipment. For Investors and Strategic Acquirers: The window for entry favors developers with validated methylation signatures approaching FDA breakthrough device submission. Long-term viability rests on securing Medicare national coverage determination precedents that create sustainable reimbursement economics. Acquisition target archetype: mid-cap liquid biopsy specialists with pancreatic cancer-specific biomarker panels and prospective clinical utility data beyond analytical validation. Watch FDA breakthrough device designation announcements as inflection indicators for reimbursement traction and competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates premarket review timelines for novel methylation assays targeting Medicare coverage. |
| Hospital System Partnership | Siemens Healthineers anchors multi-year contracts bundling CT staging with molecular workflows. |
| Reimbursement Strategy | Medicare national coverage determination for companion diagnostics drives multi-gene panel adoption. |
| CE Marking Pathway | EMA in vitro diagnostic regulation demands prospective clinical utility data beyond analytical validation. |
| Software Companion Development | AI-augmented imaging classifiers integrate with CT platforms to reduce staging laparoscopy referrals. |
Study Parameters
FDA 510(k) and breakthrough device filings, EMA CE marking databases, and CMS Medicare coverage determinations formed the secondary backbone for regulatory pathway mapping. Primary interviews with molecular pathologists, hospital procurement managers, GPO contracts specialists, and companion diagnostic commercial leads validated assay adoption timelines and pricing dynamics. Bottom-up and top-down triangulation reconciled installed base data for CT and NGS platforms with procedure volume estimates across academic medical centers and community hospitals.
Bottom-up modeling segmented the market across test type, technology, end user, and application dimensions throughout the forecast period. Top-down validation checked aggregate outputs against Medicare reimbursement claims data and hospital capital expenditure disclosures. CAGRs were derived from procedure volume growth in liquid biopsy protocols, imaging modality replacement cycles, and genetic testing penetration rates in PARP inhibitor-eligible patient populations. Forecast inputs incorporated regulatory approval timelines for methylation assays and Medicare coverage expansion trajectories for companion diagnostics.
Inputs from FDA breakthrough device designation announcements and Medicare national coverage determinations were available through the study window; gaps in European prospective clinical utility data introduce uncertainty bands around CE-marked assay adoption assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Clinical Oncology NGS Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market