
 AI in Cancer Diagnostics Market | 2026-2036
AI in Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Cancer Diagnostics Market Intelligence
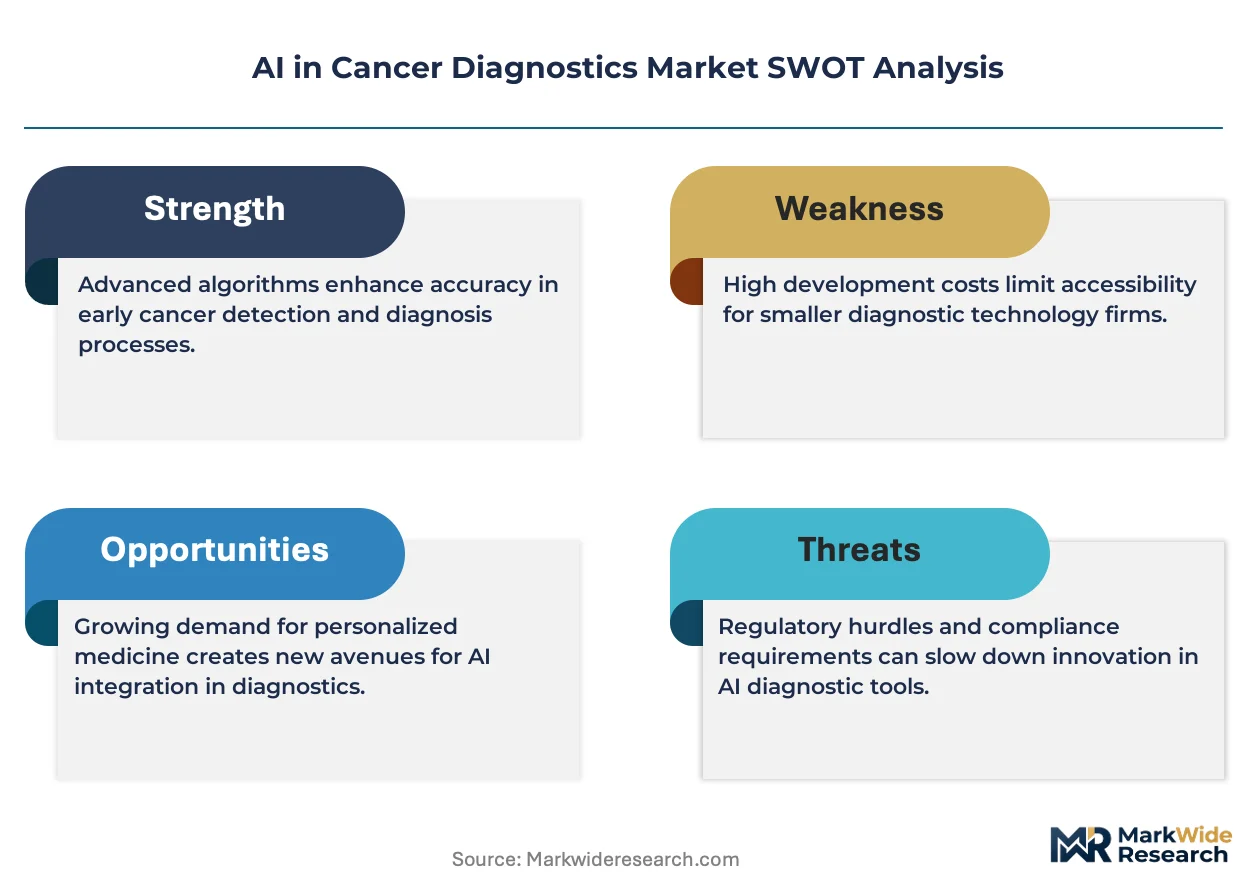
Hospital procurement departments are gaining share over academic medical centers as the primary buyer archetype for AI cancer diagnostics, and this demand rotation is bifurcating the vendor landscape between enterprise sales teams and research-oriented specialists. Siemens Healthineers anchors its position through embedded AI modules within imaging hardware ecosystems. Paige.AI specializes in computational pathology workflows that integrate directly into laboratory information systems. NVIDIA Corporation extends its influence through GPU cloud infrastructure that underpins training pipelines for multiple diagnostic developers.
AI in cancer diagnostics encompasses machine learning algorithms, deep learning neural networks, and natural language processing systems trained on histopathological images, genomic sequences, and clinical records to detect, classify, and stage malignant tissues with diagnostic-grade accuracy. These systems process whole-slide imaging data at resolutions exceeding 100,000 by 100,000 pixels, enabling pathologists to identify cellular anomalies invisible to conventional microscopy. Deep learning architectures currently dominate development pipelines for radiology and pathology applications, while natural language processing tools extract structured oncology insights from unstructured electronic health records. Image analysis platforms command premium pricing due to regulatory validation requirements and specialized hardware dependencies, whereas software-only algorithms face margin compression from open-source alternatives.
FDA software pre-certification programs, EU Medical Device Regulation CE marking pathways, and Japan PMDA adaptive review frameworks collectively determine commercial access timelines for AI diagnostic tools across major markets. These regulatory structures mandate clinical validation datasets, algorithm transparency documentation, and post-market performance monitoring that shape R&D budgets and go-to-market strategies. Stakeholders must monitor evolving reimbursement codes for computational diagnostics in the United States and Germany, as coverage decisions will determine which AI platforms achieve sustainable hospital adoption without grant-dependent revenue models.
Market Dynamics
Hospital procurement departments are displacing academic medical centers as primary buyers for AI cancer diagnostics, bifurcating the vendor landscape between enterprise sales teams and research-oriented specialists. This demand rotation is compressing commercialization timelines and reshaping pricing power across the value chain.
Growth Catalysts
- FDA Pre-Certification Pathways:The FDA's Software as a Medical Device pre-certification program accelerates commercial timelines for computational pathology platforms by enabling streamlined review processes for algorithm updates.
- Reimbursement Framework Maturation:Germany's national reimbursement codes for computational diagnostics create sustainable revenue models independent of grant funding, driving hospital procurement velocity.
- GPU Cloud Infrastructure:Scalable training pipelines for diagnostic developers reduce capital barriers to algorithm development and enable faster model iteration cycles.
Market Restraints
- Specialized Hardware Dependencies:Whole-slide imaging platforms require high-resolution scanners and GPU clusters, locking smaller pathology groups out of AI adoption.
- Algorithm Transparency Mandates:EU Medical Device Regulation documentation requirements for explainable AI increase R&D overhead and extend validation timelines.
- Open-Source Algorithm Pressure:Freely available deep learning frameworks for histopathology compress margins for software-only diagnostic vendors.
Strategic Opportunities
- Japan PMDA Adaptive Review:Japan's streamlined approval pathways for AI diagnostics create first-mover advantages for platforms targeting the Asia-Pacific oncology market.
- Natural Language Processing Convergence:Integration of clinical record extraction with image analysis enables multi-modal diagnostic workflows that command premium positioning.
- Direct Laboratory Information System Integration:Embedded AI modules bypassing standalone platforms reduce deployment friction and capture recurring revenue streams.
Industry Challenges
- Computational Pathology Talent Scarcity:Shortages of professionals trained at the intersection of deep learning and histopathology constrain algorithm development velocity.
- Post-Market Performance Monitoring Burden:Continuous algorithm validation requirements under FDA and PMDA frameworks demand dedicated compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Cancer Diagnostics Market |
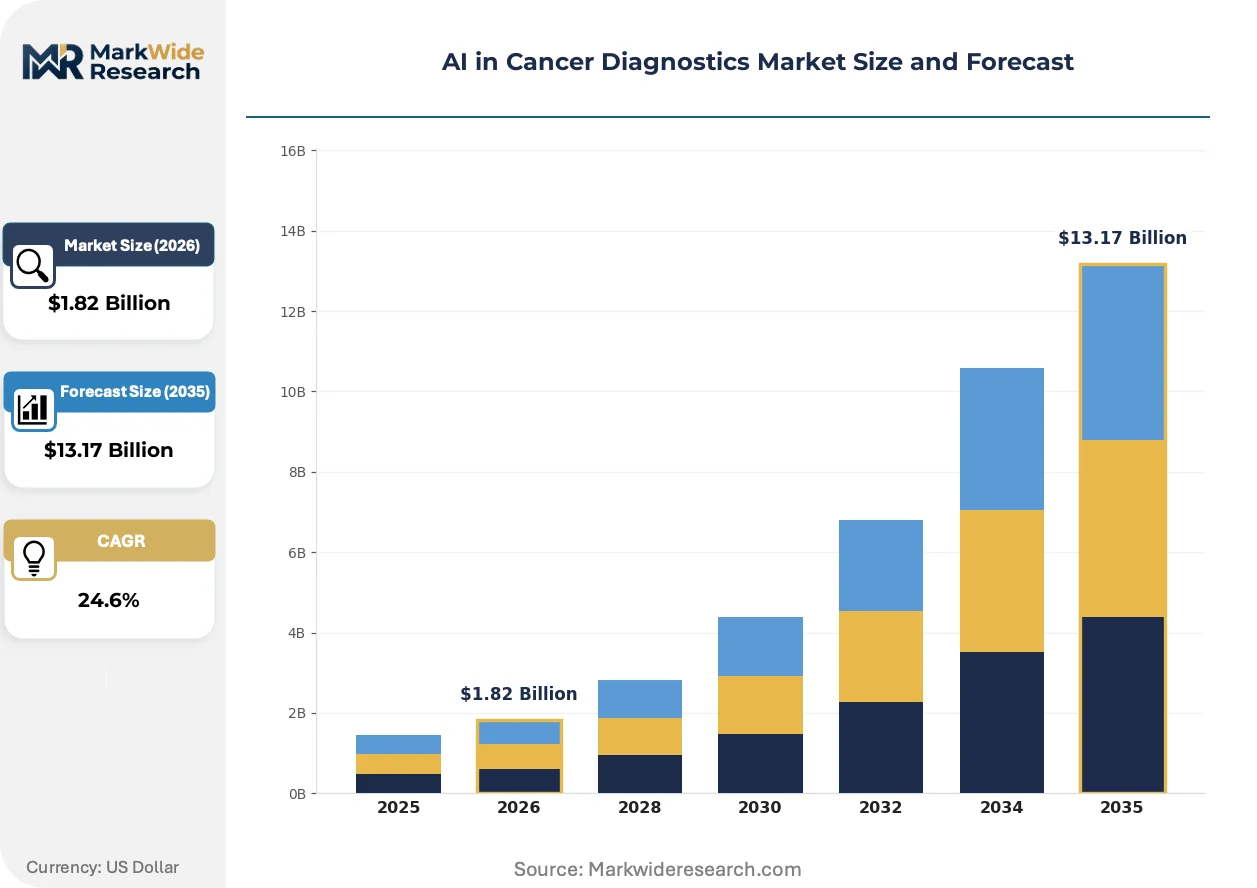
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $13.17 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Deep Learning, Natural Language Processing, Image Analysis Application: Radiology, Pathology, Genetics, Biomarker Discovery End User: Hospitals, Diagnostic Laboratories, Research Institutions, Oncologists Product Type: Software, Platforms, Tools, Algorithms |
| Companies Covered | Aidoc Medical, Lunit Inc., Paige.AI, Ibex Medical Analytics, iCAD Inc., Siemens Healthineers, GE HealthCare, Roche Diagnostics, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Cancer Diagnostics Market Strategic Shifts & Innovations
Deep learning architectures are fragmenting traditional diagnostic workflows across radiology and pathology, while regulatory frameworks and procurement models undergo parallel transformation. These shifts are compressing vendor margins and redistributing value toward integrated platform providers.
Multimodal AI systems combining histopathological imaging with genomic sequencing and electronic health record extraction are fragmenting single-purpose diagnostic tools. Hospital networks in the United States and Germany are adopting these converged platforms at accelerated pace, compressing standalone image analysis vendors into niche positioning or acquisition targets.
EU Medical Device Regulation CE marking pathways for software as a medical device mandate clinical validation datasets and algorithm transparency documentation that reshape R&D budgets. Diagnostic developers are responding by front-loading regulatory compliance into product design, with pathology applications facing the steepest documentation burden due to whole-slide complexity.
Enterprise sales teams are displacing research-oriented specialists as hospital procurement departments consolidate vendor relationships and demand integrated service contracts. This concentration is most visible in United States health systems, where purchasing committees now evaluate total cost of ownership across hardware, software, and maintenance rather than algorithm accuracy metrics alone.
AI in Cancer Diagnostics Market Segmentation
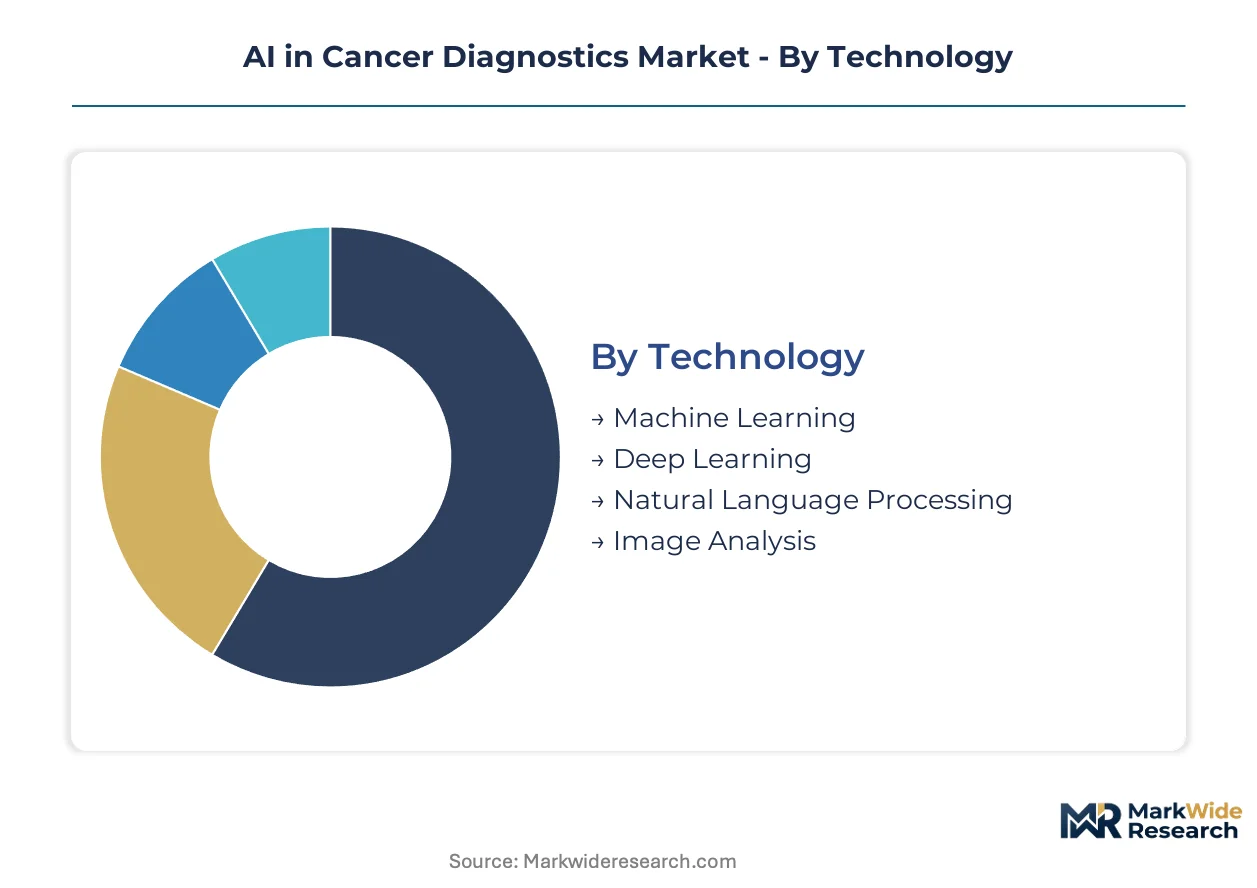
Technology heterogeneity in AI cancer diagnostics creates distinct procurement channels and pricing architectures. Hospital procurement departments evaluate segments through divergent lenses of regulatory risk, integration complexity, and total cost of ownership.
Technology:
Deep learning and machine learning modules flow through enterprise imaging hardware contracts, while natural language processing tools deploy via EHR integration channels. Image analysis platforms command dedicated capital budgets separate from software-only algorithms.
- Deep Learning:Neural network architectures process whole-slide imaging at resolutions exceeding 100,000 by 100,000 pixels, identifying cellular anomalies invisible to conventional microscopy. Demand concentrates in United States hospital networks where FDA pre-certification pathways accelerate procurement timelines for validated algorithms.
- Machine Learning:Supervised learning models trained on structured clinical datasets enable risk stratification and treatment response prediction. Diagnostic laboratories in Germany prioritize these tools for biomarker quantification workflows under maturing national reimbursement codes.
- Natural Language Processing:Clinical record extraction systems parse unstructured oncology notes into structured data for multi-modal diagnostic workflows.
- Image Analysis:High-resolution histopathological processing platforms require specialized scanner hardware and GPU clusters.
Deep learning dominates installed base. Natural language processing is where expansion concentrates.
Application:
Radiology and pathology applications carry divergent regulatory burdens and hardware dependencies that reshape margin structures across the value chain.
- Pathology:Computational analysis of histopathological specimens enables automated cancer detection and grading with diagnostic-grade accuracy. United States academic medical centers drove early adoption, though hospital procurement departments now displace them as primary buyers through consolidated enterprise contracts.
- Radiology:AI-assisted interpretation of CT, MRI, and mammography studies integrates directly into PACS workflows. Siemens Healthineers anchors this segment through embedded modules within imaging hardware ecosystems in Germany and Japan.
- Genetics:Genomic sequence analysis for mutation detection and therapeutic target identification.
- Biomarker Discovery:AI-driven identification of novel diagnostic and prognostic indicators from multi-omics datasets.
Pathology captures premium pricing due to whole-slide complexity. Radiology is climbing the fastest as hardware-embedded deployment reduces friction.
End User:
Procurement authority rotations between hospital networks and diagnostic laboratories determine vendor sales force configurations and contract structures.
- Hospitals:Integrated health systems demand bundled contracts spanning hardware, software, and maintenance with total cost of ownership metrics superseding algorithm accuracy alone. United States purchasing committees now evaluate vendor relationships through multi-year enterprise frameworks.
- Diagnostic Laboratories:High-throughput pathology services prioritize direct laboratory information system integration over standalone platforms. Paige.AI specializes in this channel with embedded computational pathology workflows.
- Research Institutions:Academic medical centers concentrate on algorithm development and clinical validation studies.
- Oncologists:Individual practitioner adoption remains constrained by reimbursement uncertainty and workflow integration costs.
Hospitals dominate installed base. Diagnostic laboratories are gaining share fastest as commercial-scale deployment accelerates.
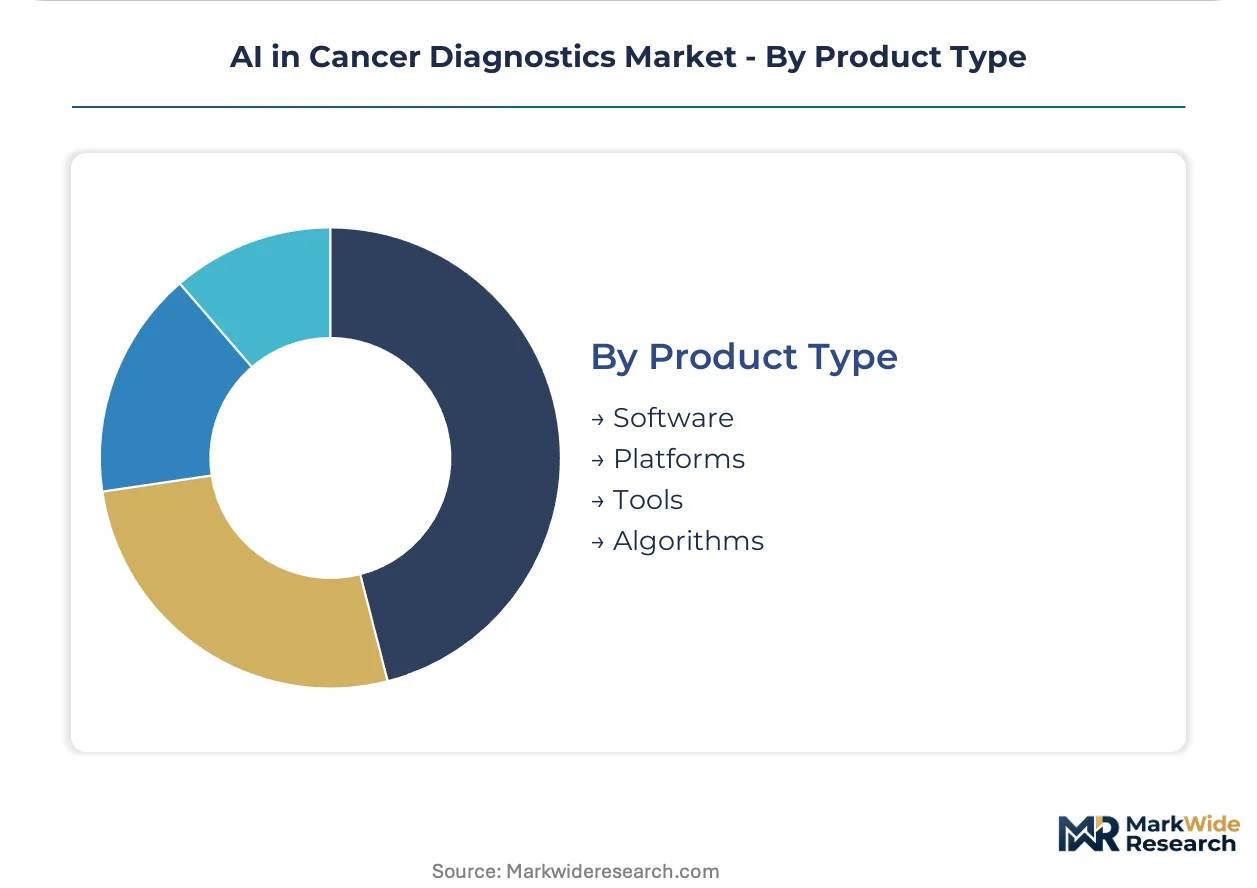
Product Type:
Product architecture determines capital intensity, recurring revenue potential, and exposure to open-source competitive pressure.
- Platforms:Integrated hardware-software systems combining scanners, GPU clusters, and analysis software command premium pricing and long deployment cycles. FDA and PMDA validation requirements for these systems create sustained competitive moats.
- Software:Cloud-deployable algorithms face margin compression from freely available deep learning frameworks but enable faster iteration cycles.
- Tools:Point solutions for specific diagnostic tasks with limited integration requirements.
- Algorithms:Standalone computational methods requiring customer-side integration and validation.
Platforms dominate installed base. Software is where expansion concentrates as cloud infrastructure reduces capital barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU cloud infrastructure and computational pathology talent concentrate in three distinct national clusters. FDA pre-certification pathways in the United States, Germany's maturing reimbursement codes, and Japan's PMDA adaptive review frameworks collectively determine commercial access timelines across major markets.
United States
Hospital procurement departments in integrated health systems now drive enterprise-scale AI diagnostic adoption. FDA software pre-certification programs accelerate commercial timelines for computational pathology platforms through streamlined algorithm update reviews. The Greater Boston and San Francisco Bay Area clusters host dense concentrations of pathology-AI development labs and venture-backed diagnostic startups.
Germany
Diagnostic laboratories prioritize machine learning tools for biomarker quantification under national reimbursement codes for computational diagnostics. EU Medical Device Regulation CE marking pathways mandate clinical validation datasets and algorithm transparency documentation that reshape R&D budgets. Siemens Healthineers anchors embedded AI module deployment within imaging hardware ecosystems across Bavaria and North Rhine-Westphalia hospital networks.
Japan
PMDA adaptive review frameworks create first-mover advantages for platforms targeting the Asia-Pacific oncology market. METI-coordinated digital health initiatives accelerate regulatory harmonization for software as a medical device. The Kanto region around Tokyo concentrates GPU cloud infrastructure investments supporting training pipelines for multiple diagnostic developers.
United Kingdom
NHS procurement frameworks increasingly evaluate total cost of ownership across hardware, software, and maintenance for AI cancer diagnostics. MHRA alignment with EU MDR documentation requirements shapes post-Brexit regulatory compliance strategies. London and Cambridge host computational pathology research clusters bridging academic medical centers and commercial algorithm developers.
South Korea
MFDS streamlined approval pathways for AI-assisted diagnostics attract multinational platform deployments. Government-funded national cancer screening programs generate structured datasets for algorithm training and validation. The Seoul Capital Area concentrates digital pathology infrastructure investments from major hospital networks and diagnostic laboratory chains.
AI in Cancer Diagnostics Market Key Industry Players
Concentration sits with integrated imaging hardware manufacturers and specialized computational pathology developers. The vendor landscape bifurcates between enterprise sales teams serving hospital procurement departments and research-oriented specialists targeting academic medical centers. Three archetypes dominate: embedded AI module providers within scanner ecosystems, standalone software algorithm vendors, and GPU cloud infrastructure suppliers. Competitive moves center on direct laboratory information system integration partnerships and regulatory pre-certification achievements.
Within the embedded AI tier, Siemens Healthineers and GE HealthCare exemplify hardware-anchored platform strategies. Paige.AI occupies a position representing specialized computational pathology workflows. NVIDIA Corporation sits within the infrastructure layer, supplying GPU cloud resources that underpin training pipelines for multiple diagnostic developers.
| Leading Market Players |
|---|
| Aidoc Medical |
| Lunit Inc. |
| Paige.AI |
| Ibex Medical Analytics |
| iCAD Inc. |
| Siemens Healthineers |
| GE HealthCare |
| Roche Diagnostics |
| NVIDIA Corporation |
| Others |
Cost & Logistics Intelligence
Ninety-to-one-hundred-twenty-day validation timelines for FDA pre-certification pathways concentrate pricing power among integrated platform vendors while compressing margins for standalone algorithm developers. Hospital procurement departments exploit this supply-side concentration to demand bundled service contracts spanning hardware, software, and maintenance.
Pricing Analysis
FDA software pre-certification pathways dictate the pricing tier structure across the AI cancer diagnostics market. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated platforms from CE-marked alternatives and open-source tools. Price differentiation centers on regulatory certification grade and after-sales service bundling. Cost compression in the software-only tier intensifies because freely available deep learning frameworks erode licensing value. Diagnostic laboratories exhibit highest price sensitivity due to volume procurement mandates, while academic medical centers prioritize algorithm accuracy metrics over total cost of ownership.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for GPU clusters and whole-slide imaging scanners. Supply concentrates in the United States, Germany, and Japan where FDA, EU MDR, and PMDA regulatory validation creates captive production ecosystems. The value chain draws from specialized semiconductor foundries, high-resolution optical sensor manufacturers, and cloud infrastructure providers. Single-source vulnerability around NVIDIA GPU architectures threatens training pipeline continuity for multiple diagnostic developers. Distribution runs through direct enterprise sales teams serving hospital procurement departments and specialized channel partners targeting diagnostic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement department consolidation into integrated health systems has shifted buyer power decisively toward enterprise-scale purchasers, fragmenting vendor pricing autonomy across the AI cancer diagnostics value chain.
For Market Incumbents: Shield embedded market position by deepening direct laboratory information system integration partnerships and accelerating FDA pre-certification achievements for algorithm update streams. Open-source deep learning frameworks threaten software-only revenue streams; vertical integration into GPU cloud infrastructure reduces dependency on external training pipeline providers. For New Entrants and Emerging Players: Japan PMDA adaptive review fast-tracks offer the most penetrable regulatory pathway for Asia-Pacific market entry. Target diagnostic laboratories in Germany seeking biomarker quantification tools under national reimbursement codes. Pursue white-space positioning in natural language processing convergence with image analysis, where multi-modal workflows command premium positioning absent dominant incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from imaging hardware manufacturers seeking to divest non-core AI software divisions. Long-term viability centers on platforms achieving sustainable hospital adoption without grant-dependent revenue models. Watch FDA reimbursement code decisions for computational diagnostics as the critical inflection signal determining which AI platforms achieve scalable commercial traction.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Streamlined algorithm update reviews accelerate commercial timelines for validated computational pathology platforms. |
| Hospital System Partnership | Enterprise contracts spanning hardware, software, and maintenance capture recurring revenue from consolidated procurement departments. |
| CE Marking Pathway | EU MDR documentation requirements for explainable AI create competitive moats through clinical validation dataset mandates. |
| Software Companion Development | Embedded modules within laboratory information systems reduce deployment friction and deepen customer switching costs. |
| Reimbursement Strategy | Germany's national codes for computational diagnostics enable sustainable revenue models independent of grant funding. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR CE marking databases, and hospital procurement contract disclosures. Primary interviews engaged pathology department heads, hospital purchasing committee chairs, diagnostic laboratory directors, and regulatory affairs leads at computational pathology developers. Bottom-up triangulation across algorithm deployment volumes and top-down validation against GPU cloud infrastructure spending patterns ensure cross-verified market sizing.
Segmentation dimensions modeled include technology architecture, application workflow, end-user procurement authority, and product integration depth across the analysis window. CAGRs derive from regression analysis of historical adoption curves in computational diagnostics, adjusted for regulatory approval velocity and reimbursement framework maturation. Forecast inputs incorporate whole-slide imaging scanner installation bases and pathology-AI development lab formation rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA pre-certification program expansion and stable GPU cloud infrastructure pricing would require recalibration. Forecasts reflect assumptions regarding reimbursement code adoption timelines and hospital procurement department consolidation trajectories. Algorithm transparency mandate intensification under EU MDR or PMDA frameworks could compress commercialization timelines beyond modeled parameters. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market