
 Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market | 2026-2036
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market Foresight
Capital-intensity divergence between large pharmaceutical manufacturers and specialized diagnostic firms is reorganizing competitive dynamics across the region. Pfizer Inc. leverages its established oncology portfolio to sustain institutional contracts with major hospital systems. Thermo Fisher Scientific Inc. differentiates through molecular diagnostic platforms that anchor laboratory workflows in cancer treatment centers.
Bladder cancer therapeutics and diagnostics encompasses pharmaceutical interventions, medical devices, and laboratory services designed to detect, treat, and monitor urothelial malignancies through targeted drug delivery, imaging modalities, and biomarker analysis. Immunotherapy agents such as checkpoint inhibitors function by blocking PD-1/PD-L1 pathways to restore T-cell mediated tumor suppression. Chemotherapy retains the largest volume share among product types due to established reimbursement pathways, while targeted therapy represents the fastest-expanding category as biomarker-guided protocols penetrate academic medical centers. Cancer treatment centers command the highest margin pools within end-user segments because of bundled service pricing for integrated diagnostic-therapeutic protocols.
South Africa's Health Products Regulatory Authority, Egypt's Drug Authority, and Saudi Arabia's SFDA collectively shape market access through divergent biologic registration requirements and import licensing frameworks. These regulators enforce varying standards for clinical trial data acceptance, creating compliance complexity for multinational sponsors seeking regional product approvals. Stakeholders must monitor harmonization initiatives between national authorities and the African Medicines Agency to anticipate streamlined pathways.
Market Dynamics
The convergence of biomarker-guided therapy protocols with institutional procurement reform is restructuring how bladder cancer care is delivered across Middle East and Africa hospital networks.
Growth Catalysts
- EMA alignment by South Africa's Health Products Regulatory Authority:Biologic drug approval timelines are compressing for multinational sponsors, accelerating patient access to checkpoint inhibitors in Johannesburg academic medical centers.
- Egypt's National Cancer Institute network expansion:Molecular diagnostic capabilities are embedding into treatment workflows, creating integrated diagnostic-therapeutic protocols that reduce referral friction.
- PD-L1 companion diagnostic penetration:Pathology laboratories in Saudi Arabia are adopting automated immunohistochemistry platforms that qualify patients for pembrolizumab and atezolizumab protocols.
Market Restraints
- Cold-chain biologic distribution costs:Temperature-controlled logistics for checkpoint inhibitors impose 15-25% markup burdens on landed costs in Nigeria and Kenya, constraining formulary inclusion.
- Single-source reagent dependency:Egypt's molecular diagnostic laboratories rely predominantly on European Union-manufactured PCR kits, exposing testing continuity to euro-denominated price volatility and import licensing delays.
- Limited pathology specialization:Urological pathology fellowship programs graduate fewer than 30 specialists annually across the entire Middle East and Africa region, creating diagnostic bottleneck capacity.
Strategic Opportunities
- Underpenetrated East African markets:Ethiopia and Tanzania currently lack dedicated uro-oncology units, presenting first-mover positioning for mobile cystoscopy screening units partnered with regional hospital systems.
- Saudi Vision 2030 healthcare localization:The Kingdom's biomanufacturing incentives are creating joint-venture pathways for regional fill-finish capacity that reduces import dependency for intravesical chemotherapy agents.
- Artificial intelligence-augmented cystoscopy:Computer-vision algorithms for real-time tumor margin detection are converging with flexible endoscope hardware, enabling community hospital adoption of advanced diagnostic capability without specialist density.
Industry Challenges
- Multinational clinical trial data acceptance variance:Egypt's Drug Authority, Saudi Arabia's SFDA, and South Africa's Health Products Regulatory Authority maintain non-harmonized requirements for biologic efficacy submissions, forcing sponsors to conduct redundant bridging studies.
- Legacy chemotherapy infrastructure lock-in:Hospital pharmacy compounding facilities across the region are optimized for BCG and mitomycin preparation, creating physical and workflow friction for cold-chain biologic integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market |
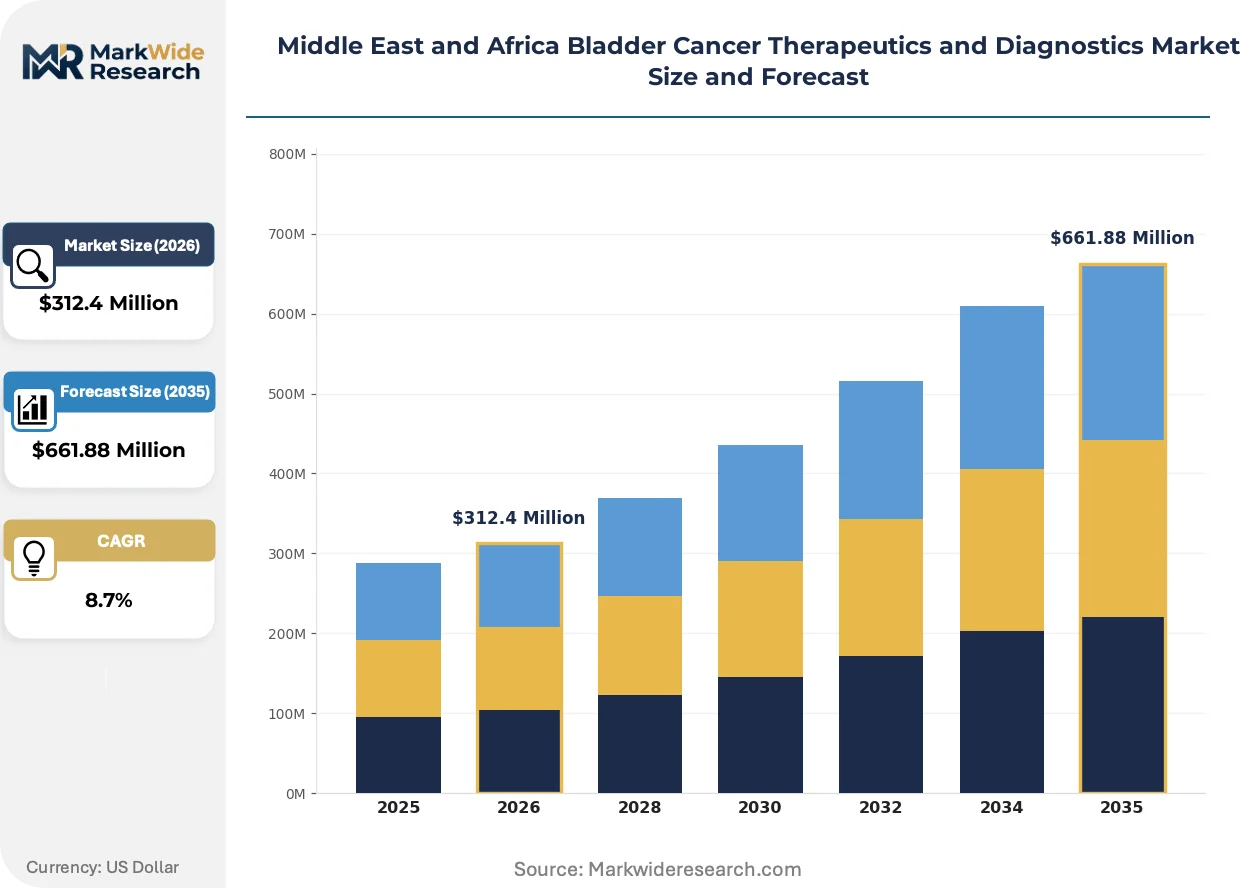
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy End User: Hospitals, Clinics, Cancer Treatment Centers, Research Institutions Delivery Mode: Intravesical, Systemic, Oral, Injectable Application: Diagnosis, Treatment, Monitoring, Research |
| Companies Covered | Pfizer Inc., Johnson and Johnson, AstraZeneca Plc., Bristol Myers Squibb, Merck & Co., Inc., F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., Koninklijke Philips N.V., Bio-Rad Laboratories, Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market Shifts & Advancements
Next-generation sequencing platforms are penetrating Middle East and Africa pathology laboratories at accelerating velocity, compressing the diagnostic timeline from tissue acquisition to therapy selection and enabling real-time molecular tumor board consultations.
Liquid biopsy circulating tumor DNA assays are fragmenting the tissue-dependent diagnostic paradigm. Oncology departments in Cairo and Casablanca are adopting plasma-based BRAF and FGFR3 mutation profiling to circumvent repeat transurethral resection sampling. The technology is fragmenting referral patterns by enabling community hospitals to initiate molecular characterization without centralized pathology infrastructure.
Saudi Arabia's SFDA has implemented accelerated review pathways for oncology biologics demonstrating EMA or FDA prior approval, compressing registration timelines from 24 months to 12 months. This regulatory convergence is redirecting multinational sponsor resource allocation toward the Kingdom's treatment centers. Regional pharmaceutical distributors are responding by building dedicated oncology cold-chain capabilities to capture institutional contract opportunities.
Hospital procurement committees across the Middle East and Africa are unbundling diagnostic and therapeutic purchasing decisions, previously consolidated under single vendor relationships. Cancer treatment centers in Johannesburg and Alexandria are separately contracting with molecular diagnostic platforms and pharmaceutical suppliers, compressing switching costs and intensifying price transparency. This pattern is most visible in South Africa's private hospital networks, where radiology and pathology services operate as profit centers with independent vendor selection authority.
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market Segmentation
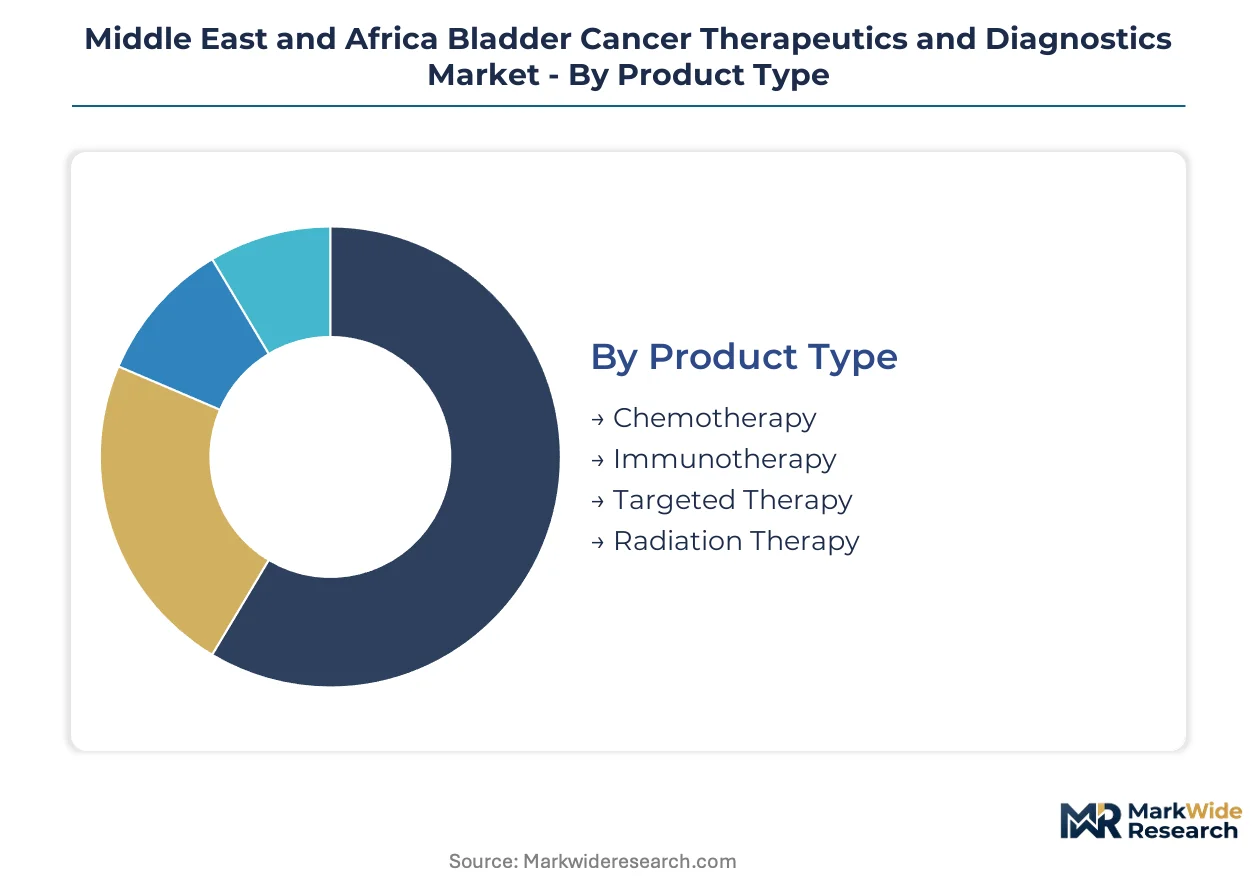
Bladder cancer care delivery in the Middle East and Africa fragments across institutional hierarchies, reimbursement tiers, and technical capabilities that shape how therapeutic and diagnostic products reach patients. Each segmentation dimension reveals distinct channel economics and access barriers that determine commercial viability for multinational sponsors and regional distributors.
Product Type:
Chemotherapy flows through government procurement tenders and hospital pharmacy compounding networks, while immunotherapy and targeted therapy concentrate in private hospital chains with cold-chain infrastructure.
- Chemotherapy:Intravesical BCG and mitomycin preparations remain the backbone of non-muscle invasive bladder cancer protocols across Egypt's National Cancer Institute network. South Africa's public sector oncology programs rely on centralized procurement contracts that prioritize cost containment over therapeutic innovation, limiting access to platinum-based systemic regimens in Johannesburg academic medical centers.
- Immunotherapy:Checkpoint inhibitors including pembrolizumab and atezolizumab require PD-L1 companion diagnostic qualification and temperature-controlled distribution. Saudi Arabia's SFDA accelerated approval pathways have compressed registration timelines, redirecting multinational sponsor investment toward Riyadh and Jeddah treatment centers with dedicated biologic handling capabilities.
- Targeted Therapy:FGFR3 inhibitors and antibody-drug conjugates penetrate Egypt's private hospital sector where molecular tumor boards guide therapy selection.
- Radiation Therapy:External beam and brachytherapy modalities concentrate in South Africa's radiotherapy centers with cobalt-60 or linear accelerator infrastructure.
Chemotherapy dominates installed base across public hospital networks. Immunotherapy is where expansion concentrates as SFDA and South Africa's Health Products Regulatory Authority compress biologic approval timelines.
End User:
Institutional purchasing power and reimbursement sophistication create sharp tiering in product access, with cancer treatment centers commanding premium pricing for bundled diagnostic-therapeutic protocols.
- Hospitals:General hospital oncology departments across Nigeria and Kenya manage high patient volumes with limited pathology specialization, creating diagnostic bottlenecks that delay therapy initiation. Egypt's public hospital network serves as the primary access point for chemotherapy-eligible patients without private insurance coverage.
- Cancer Treatment Centers:Dedicated uro-oncology units in Cairo, Johannesburg, and Riyadh integrate cystoscopy, molecular diagnostics, and systemic therapy under single institutional contracts. These centers capture margin pools through bundled service pricing that unifies diagnostic platform selection with pharmaceutical procurement decisions.
- Clinics:Urology clinics in Casablanca and Tunis perform initial hematuria workups and cystoscopic surveillance.
- Research Institutions:Academic medical centers in Cape Town and Alexandria conduct investigator-initiated trials for novel immunotherapy combinations.
Hospitals anchor patient volume across the region. Cancer treatment centers are where margin expansion concentrates as procurement committees unbundle vendor relationships.
Delivery Mode:
Route of administration determines cold-chain requirements, compounding infrastructure, and patient compliance monitoring that shape distribution economics across institutional settings.
- Intravesical:Direct bladder instillation of BCG and chemotherapy agents requires urology suite availability and sterile preparation facilities. South Africa's hospital pharmacy compounding infrastructure is optimized for this modality, creating workflow friction for systemic biologic integration.
- Systemic:Intravenous checkpoint inhibitors and platinum-based regimens demand oncology infusion units with adverse event management protocols. Saudi Arabia's private hospital networks are expanding day-ward capacity to capture systemic therapy volume.
- Oral:FGFR inhibitor tablets enable community-based administration without infusion center dependency.
- Injectable:Subcutaneous immunotherapy formulations reduce infusion duration and facility capacity constraints.
Intravesical delivery dominates installed base in Egypt and South Africa public sectors. Systemic administration is where capacity investment concentrates as biologic penetration deepens.
Application:
Clinical utility across the care continuum determines reimbursement coding, regulatory classification, and vendor contracting structures that segment commercial opportunity.
- Diagnosis:Cystoscopy, urine cytology, and molecular biomarker testing anchor initial staging and recurrence surveillance protocols. Egypt's National Cancer Institute network expansion is embedding fluorescence cystoscopy and NGS platforms into diagnostic workflows.
- Treatment:Curative-intent transurethral resection, neoadjuvant chemotherapy, and radical cystectomy with urinary diversion concentrate in high-volume centers. South Africa's academic medical centers maintain surgical oncology fellowship programs that sustain technical capability.
- Monitoring:Liquid biopsy ctDNA assays for minimal residual disease detection are fragmenting referral patterns in Cairo and Casablanca.
- Research:Biomarker-driven clinical trial enrollment connects Middle East and Africa sites to multinational sponsor networks.
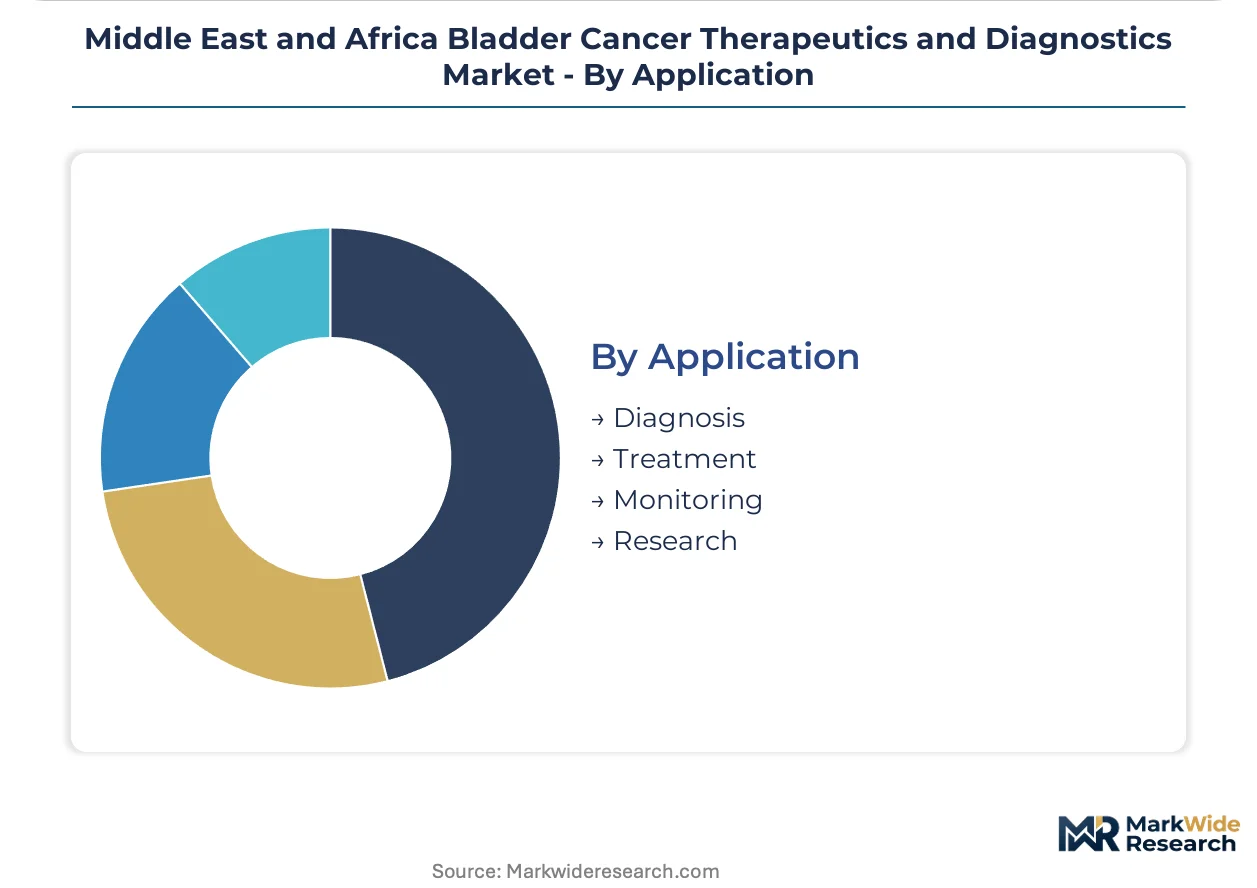
Treatment commands the largest revenue share across institutional procurement. Diagnosis is where technology substitution concentrates as NGS and liquid biopsy displace conventional pathology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the region. Egypt's public sector oncology programs exhibit extreme price sensitivity, while Saudi Arabia's private hospital networks absorb premium biologic pricing with minimal volume contraction.
Saudi Arabia
SFDA accelerated approval pathways compress biologic registration timelines from 24 months to 12 months for EMA-approved products. The Kingdom's Vision 2030 biomanufacturing incentives create joint-venture pathways for regional fill-finish capacity. Riyadh and Jeddah treatment centers anchor institutional procurement for checkpoint inhibitors with dedicated cold-chain infrastructure.
Egypt
The National Cancer Institute network expansion embeds molecular diagnostic capabilities into treatment workflows across Cairo and Alexandria. Egypt's Drug Authority maintains distinct clinical trial data requirements from Saudi Arabia and South Africa, forcing redundant bridging studies. Cairo's private hospital sector concentrates FGFR inhibitor adoption where molecular tumor boards guide therapy selection.
South Africa
Health Products Regulatory Authority alignment with EMA standards accelerates biologic approval timelines for multinational sponsors. Johannesburg academic medical centers sustain institutional contracts with established oncology portfolios. The country's public sector oncology programs rely on centralized procurement contracts that prioritize cost containment over therapeutic innovation.
United Arab Emirates
MOHAP regulatory frameworks facilitate rapid registration of oncology biologics with prior FDA or EMA approval. Dubai's private hospital networks expand day-ward capacity to capture systemic therapy volume. The emirate's cancer treatment centers command premium pricing for bundled diagnostic-therapeutic protocols.
Nigeria
Cold-chain biologic distribution costs impose 15-25% markup burdens on landed checkpoint inhibitor costs, constraining formulary inclusion in Lagos and Abuja hospital systems. The country's national pharmaceutical regulator enforces import licensing frameworks that delay molecular diagnostic kit availability. General hospital oncology departments manage high patient volumes with limited pathology specialization.
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive structure. Large pharmaceutical manufacturers leverage established oncology portfolios to sustain institutional contracts with major hospital systems. Specialized diagnostic firms differentiate through molecular platform anchoring of laboratory workflows. The dominant competitive moves are strategic partnerships for cold-chain distribution and portfolio diversification into companion diagnostics.
Within the integrated pharmaceutical tier, Pfizer Inc. and AstraZeneca Plc. exemplify archetypes positioned to capture institutional contract opportunities as SFDA and South Africa's Health Products Regulatory Authority compress biologic approval timelines. Thermo Fisher Scientific Inc. occupies a distinct position among diagnostic platform specialists, representing the laboratory workflow anchoring strategy visible across Cairo and Riyadh cancer treatment centers.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson and Johnson |
| AstraZeneca Plc. |
| Bristol Myers Squibb |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| Koninklijke Philips N.V. |
| Bio-Rad Laboratories, Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for PD-L1 companion diagnostic reagents determine margin compression across Egyptian and South African laboratory networks, concentrating pricing power with European Union manufacturers while amplifying landed cost markups for temperature-sensitive biologics in distributed oncology centers.
Pricing Analysis
Service contract bundling for automated immunohistochemistry platforms drives lifetime value for diagnostic vendors in Riyadh and Cairo cancer treatment centers. Three-tier pricing structure across premium, standard, and economy levels segments institutional buyers by molecular diagnostic capability and patient volume. Price differentiation rests on SFDA approval status and cold-chain infrastructure certification. Pricing pressure stems from euro-denominated reagent volatility squeezing Egyptian public hospital budgets. Government procurement tenders exhibit extreme price sensitivity; private hospital networks in Saudi Arabia absorb premium biologic pricing with minimal volume contraction.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for PCR kit shipments destined for Lagos and Nairobi pathology laboratories. Manufacturing concentration in Germany, the Netherlands, and the United States supplies automated diagnostic platforms and biologic drug substances. Raw material dependencies include recombinant antibodies, fluorophore reagents, and sterile vial components. Single-source vulnerability pervades European-manufactured companion diagnostic kits, exposing testing continuity to import licensing delays. Distribution runs through regional pharmaceutical distributors with dedicated oncology cold-chain capabilities serving institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA accelerated approval pathways compressing biologic registration timelines from 24 months to 12 months constitute a regulatory inflection that disrupts competitive positioning across Middle East and Africa oncology markets.
For Market Incumbents: Shield institutional contract positions in Johannesburg and Riyadh by deepening backward integration into regional fill-finish capacity for intravesical chemotherapy agents. Secure exclusive service agreements for automated diagnostic platforms to lock out emerging molecular diagnostic specialists. Cold-chain infrastructure gaps in Nigeria and Kenya present vulnerability to low-cost entrants with mobile distribution units. For New Entrants and Emerging Players: Community hospital AI-augmented cystoscopy deployment represents the most penetrable service layer where incumbent specialists concentrate in academic medical centers. Ethiopia and Tanzania lack dedicated uro-oncology units entirely. Partner with regional hospital systems for mobile screening units. Target liquid biopsy ctDNA assay adoption in Casablanca and Tunis urology clinics bypassing centralized pathology infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical manufacturers divesting non-core oncology assets in Middle East and Africa distribution networks. Five-to-ten-year viability hinges on biomarker-guided therapy protocol penetration and regulatory harmonization progress. Monitor African Medicines Agency harmonization initiatives as the critical inflection signal for streamlined market access and valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | SFDA accelerated review compresses biologic registration timelines for EMA-approved checkpoint inhibitors. |
| Hospital System Partnership | Cairo and Alexandria cancer treatment centers bundle diagnostic platform selection with pharmaceutical procurement. |
| Manufacturing Scale-Up | Saudi Vision 2030 biomanufacturing incentives enable regional fill-finish capacity for intravesical agents. |
| Software Companion Development | AI-augmented cystoscopy algorithms reduce specialist dependency for community hospital adoption. |
| Reimbursement Strategy | Egypt's National Cancer Institute network expansion creates integrated diagnostic-therapeutic protocol funding. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with oncology stakeholders and secondary validation across regulatory and procurement databases. Interview subjects included drug development executives at multinational sponsors, regulatory affairs leads navigating SFDA and Egypt's Drug Authority requirements, hospital procurement managers in Johannesburg and Riyadh, formulary directors at Egypt's National Cancer Institute, and payer access specialists. Secondary sources encompassed SFDA registration filings, EMA submission documents, ClinicalTrials.gov protocol records, hospital procurement databases, and GPO contract disclosures. Bottom-up patient volume modeling and top-down market sizing triangulated segment estimates.
Across the projection horizon, the analytical framework modeled segmentation by product type, end-user institution tier, delivery mode, and application across the care continuum. Compound annual growth rates derived from therapy line penetration curves, biomarker testing adoption velocities, and institutional procurement unbundling trends. Forecast inputs included regulatory approval timeline compression rates, cold-chain infrastructure investment flows, and molecular diagnostic platform installation data.
Material uncertainties — regulatory harmonization delays, biologic distribution cost volatility, pathology specialist graduation rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about EMA alignment progression and SFDA pathway stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Global Clinical Oncology NGS Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market