
 Neurodegenerative Disease Treatment Market | 2026-2036
Neurodegenerative Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Neurodegenerative Disease Treatment Market Intelligence
Buyer concentration among hospital networks and integrated delivery systems is pivoting toward centralized purchasing agreements for high-cost biologics. Biogen Inc. leverages its established neurology infrastructure to sustain infusion center relationships. Roche anchors its position through diagnostic-therapeutic pairing in Alzheimer's care. UCB SA competes via specialized epilepsy and Parkinson's portfolios that differentiate beyond primary neurodegeneration.
Neurodegenerative disease treatment encompasses pharmacological and biologic interventions targeting progressive neuronal death, including monoclonal antibodies engineered to clear amyloid-beta plaques and small molecules modulating synaptic signaling pathways. These therapies serve the core purpose of slowing functional decline in conditions such as Alzheimer's and Parkinson's diseases. Monoclonal antibodies command premium positioning due to manufacturing complexity and targeted mechanism, while gene therapy represents the fastest-expanding modality as viral vector delivery matures. Oral small molecules retain volume leadership in Parkinson's Disease where chronic daily administration dominates patient preference.
The FDA's accelerated approval framework and EMA's conditional marketing authorization pathway shape development economics by permitting earlier revenue generation based on surrogate endpoints. Japan's PMDA has streamlined reviews for Alzheimer's therapies under its Sakigake designation, redirecting clinical trial investment toward Tokyo-Osaka medical corridors. Stakeholders must monitor biomarker qualification progress across regulators, as surrogate endpoint acceptance determines which modalities achieve reimbursable status without decade-long confirmatory trials.
Market Dynamics
Hospital procurement consolidation is compressing commercial timelines for biologic therapies, forcing manufacturers to restructure field forces around integrated delivery networks rather than individual prescriber relationships.
Growth Catalysts
- FDA Accelerated Approval Pathway:Surrogate endpoint acceptance for Alzheimer's therapies permits earlier revenue generation and redirects R&D investment toward biomarker qualification studies.
- Japan's Sakigake Designation:Priority review status for novel neurology treatments concentrates clinical trial infrastructure in Tokyo-Osaka medical corridors.
- Monoclonal Antibody Manufacturing Scale-Up:Viral vector production maturation is expanding gene therapy capacity for Parkinson's disease programs.
Market Restraints
- Biologic Cold Chain Complexity:Infusion center capacity constraints in rural United States limit patient access to amyloid-clearing therapies.
- EMA Conditional Marketing Authorization Requirements:Confirmatory trial obligations create reimbursement uncertainty across European hospital systems.
- Small Molecule Substitution Pressure:Oral Parkinson's therapies retain volume preference where daily administration patterns dominate chronic disease management.
Strategic Opportunities
- Diagnostic-Therapeutic Pairing:Cerebrospinal fluid biomarker integration with treatment protocols creates stickiness in Alzheimer's care pathways.
- Home Infusion Channel Development:Subcutaneous formulation advances enable hospital-at-home programs for neurodegenerative biologics.
- Germany's Hospital Reform Act:Bundled payment structures for neurological episodes incentivize integrated care model adoption.
Industry Challenges
- Specialized Neurology Workforce Scarcity:Movement disorder specialist shortages constrain clinical trial site activation timelines.
- Legacy Electronic Health Record Integration:Cognitive assessment data standardization delays real-world evidence collection for payor negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurodegenerative Disease Treatment Market |
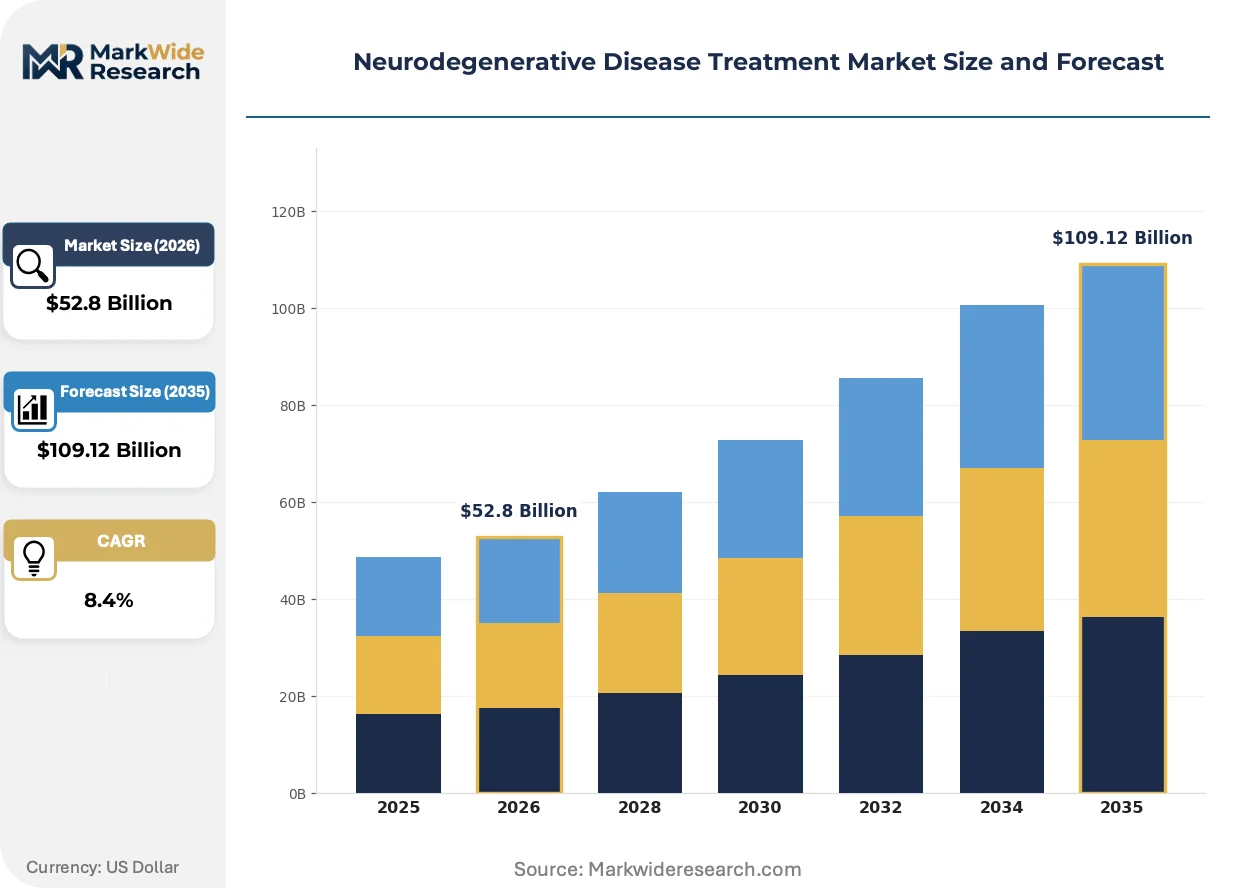
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $109.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecules, Gene Therapy, Combination Therapy Indication: Alzheimer's Disease, Parkinson's Disease, Huntington's Disease, Amyotrophic Lateral Sclerosis Delivery Mode: Intravenous, Oral, Intramuscular, Subcutaneous End User: Hospitals, Home Care, Specialty Clinics, Research Institutions |
| Companies Covered | Eisai Co., Ltd., Merck & Co., Biogen Inc., UCB SA, Boehringer Ingelheim International GmbH, Roche, Novartis AG, Teva Pharmaceuticals Industries Ltd., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurodegenerative Disease Treatment Market Strategic Shifts & Innovations
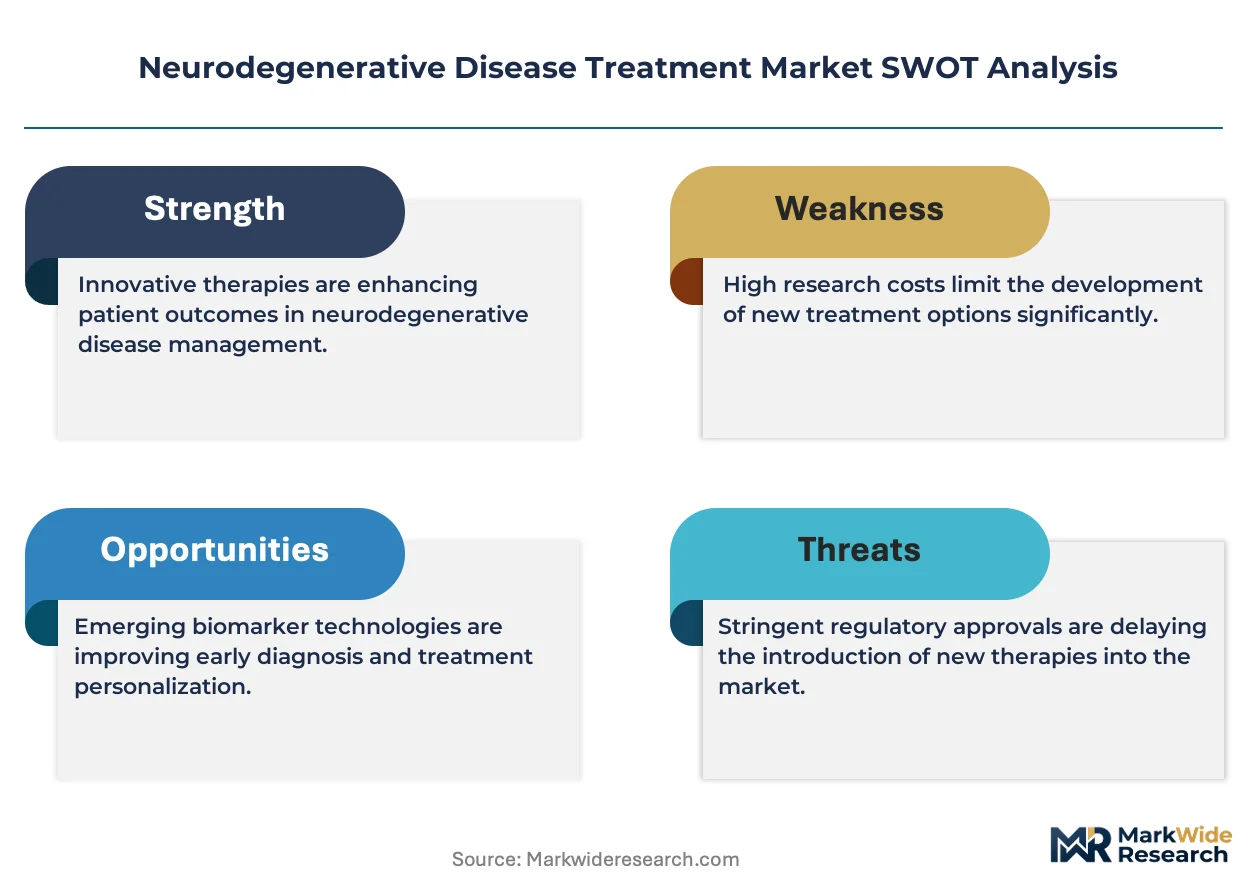
Neurodegenerative treatment development is pivoting from symptomatic management toward disease-modifying mechanisms, with biomarker-driven patient selection becoming the dominant trial design paradigm.
Antisense oligonucleotide platforms targeting superoxide dismutase mutations are absorbing preclinical investment previously directed toward small molecule approaches. Biogen and Roche are advancing intrathecal delivery programs for amyotrophic lateral sclerosis. The technology is absorbing manufacturing capacity from mature monoclonal antibody lines as viral vector production scales.
Japan's PMDA has expanded its Sakigake fast-track designation to include gene therapies for rare neurodegenerative conditions. Domestic sponsors gain priority consultation and shortened review timelines. Japanese hospital systems are responding by consolidating neurology departments into designated core facilities.
Integrated delivery networks in the United States are unbundling infusion services from pharmaceutical procurement, creating separate contracting tracks for drug acquisition and administration. Hospital systems are replacing traditional buy-and-bill models with white-bag specialty pharmacy arrangements. This restructuring is most visible in Medicare Advantage populations where risk-bearing entities control site-of-care decisions.
Neurodegenerative Disease Treatment Market Segmentation
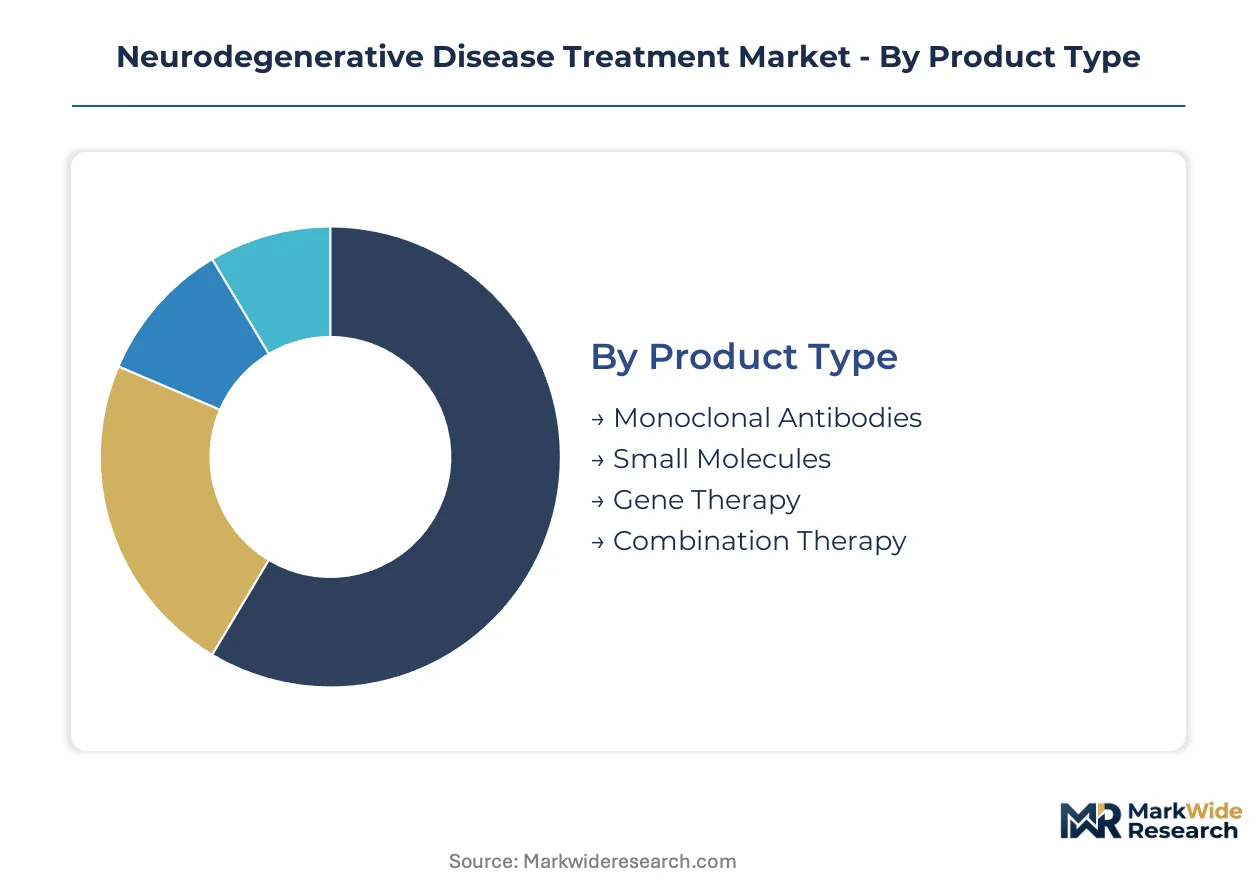
Neurodegenerative disease treatment segmentation reveals divergent commercial models across therapeutic modalities. Hospital procurement consolidation and patient administration preferences are reshaping segment economics. Each dimension carries distinct margin profiles and regulatory pathways that determine competitive positioning.
Product Type:
Buyers differentiate primarily by manufacturing complexity and reimbursement tier, with premium biologics commanding separate contracting tracks from commoditized small molecules.
- Monoclonal Antibodies:Engineered immunoglobulins targeting amyloid-beta plaques require cold chain infrastructure and infusion center capacity. Demand concentrates in Medicare Advantage networks where risk-bearing entities control site-of-care decisions, constrained by rural infusion capacity shortages.
- Gene Therapy:Viral vector-delivered genetic constructs targeting Parkinson's disease pathophysiology. Investment is absorbing manufacturing capacity from mature monoclonal antibody lines as AAV production scales, with fastest-expanding capacity in Tokyo-Osaka medical corridors under Japan's PMDA Sakigake designation.
- Small Molecules:Oral compounds modulating synaptic signaling pathways retain volume leadership where daily chronic administration dominates patient preference in Parkinson's Disease management.
- Combination Therapy:Integrated pharmacological regimens pairing disease-modifying biologics with symptomatic agents across Alzheimer's care pathways.
Small molecules lead volumes today; gene therapy is gaining share fastest.
Indication:
Segment economics track directly to biomarker qualification progress and surrogate endpoint acceptance by major regulators.
- Alzheimer's Disease:Amyloid-clearing therapies dominate R&D investment following FDA accelerated approval pathway expansion. Diagnostic-therapeutic pairing with cerebrospinal fluid biomarker integration creates care pathway stickiness in integrated delivery networks.
- Parkinson's Disease:Oral dopaminergic agents retain volume preference while gene therapy programs advance for motor complication management. Subcutaneous formulation development is enabling hospital-at-home program expansion.
- Huntington's Disease:Antisense oligonucleotide platforms targeting mutant huntingtin protein are absorbing preclinical investment previously directed toward small molecule approaches.
- Amyotrophic Lateral Sclerosis:Intrathecal delivery programs for superoxide dismutase mutations are advancing through specialty neurology centers with movement disorder specialist concentration.
Alzheimer's Disease commands the steepest R&D investment trajectory; Parkinson's Disease maintains the broadest prescriber base.
Delivery Mode:
Administration route determines site-of-care economics and patient access geography, with hospital-at-home programs restructuring traditional channel relationships.
- Intravenous:Infusion-dependent biologics requiring specialized nursing infrastructure. Hospital systems are unbundling infusion services from pharmaceutical procurement, creating separate contracting tracks for drug acquisition and administration.
- Oral:Daily administration patterns dominate chronic disease management preferences, particularly in Parkinson's Disease where patient autonomy in dosing timing supports adherence.
- Intramuscular:Depot formulations extending dosing intervals for symptomatic agents in movement disorder management.
- Subcutaneous:Formulation advances enabling home infusion channel development for neurodegenerative biologics, bypassing hospital capacity constraints.
Oral administration retains the largest patient touchpoint volume; subcutaneous delivery is expanding most quickly through home care channels.
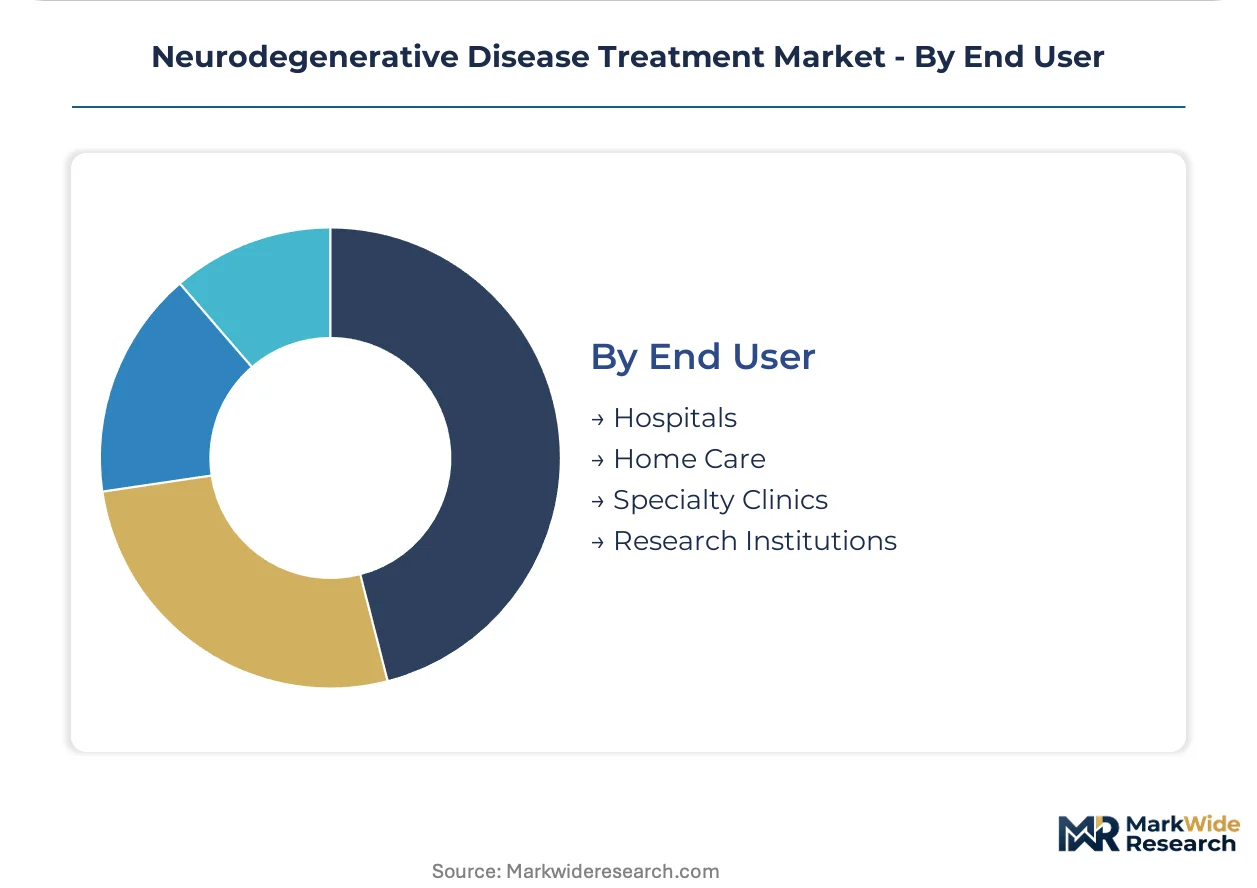
End User:
Channel concentration reflects reimbursement control points and risk-bearing entity influence over treatment site selection.
- Hospitals:Integrated delivery networks are consolidating procurement for high-cost biologics, replacing traditional buy-and-bill models with white-bag specialty pharmacy arrangements.
- Home Care:Hospital-at-home programs for neurodegenerative biologics are expanding through subcutaneous formulation advances, particularly visible in Medicare Advantage populations.
- Specialty Clinics:Movement disorder centers with concentrated specialist expertise serve as clinical trial site activation hubs and advanced therapy administration points.
- Research Institutions:Academic medical centers anchor biomarker qualification studies and real-world evidence collection for payor negotiations.
Hospitals capture the highest-value therapy administration; home care is climbing the fastest as site-of-care shifts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks command premium biologic procurement volumes while Japan's PMDA regulatory pathway accelerates clinical trial migration toward Tokyo-Osaka corridors. Germany's bundled payment reforms reshape neurological episode economics. These three markets anchor divergent commercial models for neurodegenerative therapeutics.
United States
Medicare Advantage risk-bearing entities drive site-of-care decisions for amyloid-clearing infusions, concentrating demand in integrated delivery networks. FDA accelerated approval for Alzheimer's therapies permits earlier revenue generation based on surrogate endpoints. Infusion capacity constraints persist in rural markets, redirecting investment toward hospital-at-home programs in Medicare Advantage corridors.
Japan
Aging demographics and concentrated specialist infrastructure concentrate demand for disease-modifying neurology therapies. PMDA's Sakigake designation grants priority review and shortened consultation timelines for novel treatments. Tokyo-Osaka medical corridors absorb expanded clinical trial infrastructure as domestic sponsors and multinational firms redirect Parkinson's and Alzheimer's programs toward Japanese sites.
Germany
Hospital procurement consolidation under the Hospital Reform Act creates bundled payment structures for neurological episodes. EMA conditional marketing authorization requirements generate reimbursement uncertainty that shapes formulary placement timelines. Bavaria and North Rhine-Westphalia anchor the highest concentration of movement disorder specialist centers and clinical trial site activation capacity.
United Kingdom
NHS England's specialized commissioning framework concentrates high-cost biologic access through designated neurological centers. MHRA post-Brexit regulatory autonomy permits accelerated assessment pathways for innovative medicines. Greater London and the Midlands host the dominant academic medical center infrastructure for biomarker qualification studies and real-world evidence collection.
Switzerland
Swissmedic's streamlined review procedures for orphan neurological indications attract clinical trial sponsorship from European biotech firms. Cantonal hospital systems maintain decentralized procurement autonomy that preserves prescriber-level contracting relationships. Basel and Zurich anchor the primary concentration of neurology specialty centers and diagnostic-therapeutic integration programs.
Neurodegenerative Disease Treatment Market Key Industry Players
United States-based biopharmaceutical conglomerates anchor the premium-tier monoclonal antibody segment; European specialists hold positions in diagnostic-therapeutic pairing and antisense platforms. Market structure tilts toward consolidated procurement relationships with integrated delivery networks rather than fragmented prescriber-level competition. Three archetypes dominate: large-cap biologics manufacturers with neurology infrastructure, mid-cap specialists in movement disorder portfolios, and emerging gene therapy platform developers. Competitive moves center on diagnostic-therapeutic integration partnerships and subcutaneous formulation advances that bypass hospital capacity constraints.
Within the established biologics tier, Biogen Inc. and Roche occupy positions defined by infusion center relationships and diagnostic pairing capabilities. UCB SA exemplifies the mid-cap specialist archetype through differentiated epilepsy and Parkinson's portfolios. These three entities represent contrasting strategic postures: infrastructure-heavy commercial execution, integrated diagnostic-therapeutic ecosystems, and focused neurology specialization beyond primary neurodegeneration indications.
| Leading Market Players |
|---|
| Eisai Co., Ltd. |
| Merck & Co. |
| Biogen Inc. |
| UCB SA |
| Boehringer Ingelheim International GmbH |
| Roche |
| Novartis AG |
| Teva Pharmaceuticals Industries Ltd. |
| Eli Lilly and Company |
| Others |
Cost & Logistics Intelligence
Monoclonal antibody cold chain premiums diverging from small molecule commoditization create distinct pricing architectures across the neurodegenerative treatment landscape, with infusion center capacity constraints in rural United States compressing margins while gene therapy manufacturing scale-up in Japan commands premium positioning through Sakigake-designated supply security.
Pricing Analysis
Capacity additions in Japan's Tokyo-Osaka medical corridors are reshaping price floors for gene therapy manufacturing, while monoclonal antibody production in the United States and Switzerland maintains premium tiers through diagnostic-therapeutic bundling. Three-tier pricing structure across premium biologics, standard small molecules, and economy generics separates infusion-dependent therapies from oral chronic administration. Pricing pressure stems from Medicare Advantage risk-bearing entities unbundling drug acquisition from administration services. Hospital procurement managers show highest price sensitivity; integrated delivery network formulary directors exhibit lowest sensitivity where biomarker-integrated protocols lock in therapeutic pairing.
Supply Chain Analysis
Regional distribution centers in the United States, Switzerland, and Japan anchor hub-and-spoke patterns for temperature-sensitive biologics, with Tokyo-Osaka corridors absorbing viral vector manufacturing capacity expansion. Active pharmaceutical ingredients for small molecules draw from India and China, while monoclonal antibody cell lines rest on Swiss and German bioreactor infrastructure. Single-source vulnerability concentrates in AAV vector production for Parkinson's gene therapy programs. Distribution runs through white-bag specialty pharmacy arrangements replacing traditional hospital buy-and-bill models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in neurodegenerative therapeutics hinges on subcutaneous formulation advances that bypass hospital capacity constraints and enable hospital-at-home premium capture.
For Market Incumbents: Anchor diagnostic-therapeutic pairing relationships through cerebrospinal fluid biomarker integration to defend against emerging antisense oligonucleotide platforms. Deepen backward integration into viral vector manufacturing capacity in Japan's Sakigake-designated corridors. Consolidate infusion center networks before Medicare Advantage risk-bearing entities complete site-of-care unbundling. For New Entrants and Emerging Players: FDA accelerated approval pathway expansion in the United States opens a window for surrogate endpoint-based Alzheimer's therapies that bypass decade-long confirmatory trial requirements. Target subcutaneous formulation white spaces where hospital-at-home programs lack biologic administration options. Pursue licensing arrangements with established neurology infrastructure holders rather than building de novo field forces. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital procurement consolidation has fragmented prescriber-level contracting relationships into integrated delivery network gatekeeping. Five-to-ten-year viability favors antisense oligonucleotide platform developers with intrathecal delivery capabilities over small molecule-dependent portfolios. Watch biomarker qualification progress across FDA and EMA as the inflection signal for which modalities achieve reimbursable status without confirmatory trial completion.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Pairing | Cerebrospinal fluid biomarker integration with Alzheimer's protocols creates formulary stickiness in integrated delivery networks. |
| Subcutaneous Formulation Development | Hospital-at-home program expansion bypasses rural infusion capacity constraints in Medicare Advantage corridors. |
| Viral Vector Manufacturing Scale-Up | Tokyo-Osaka capacity expansion under PMDA Sakigake designation secures gene therapy supply for Parkinson's programs. |
| White-Bag Specialty Pharmacy Arrangement | Unbundled procurement tracks separate drug acquisition from administration in risk-bearing entity contracts. |
| Biomarker Qualification Investment | Surrogate endpoint acceptance by FDA and EMA determines reimbursable status without confirmatory trials. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down biologic manufacturing capacity tracking forms the analytical core of this study. Primary interviews with formulary directors, movement disorder specialists, payer access specialists, and infusion center administrators combined with secondary validation against FDA accelerated approval filings, EMA conditional marketing authorization submissions, ClinicalTrials.gov neurology program databases, and Medicare Advantage formulary databases. Triangulation across these sources ensures supply-side capacity estimates align with demand-side reimbursement pathway assumptions.
Input-output matrices map monoclonal antibody, gene therapy, small molecule, and combination therapy production across indication and delivery mode dimensions throughout the forecast period. Treatment line stratification, administration route economics, patient population severity tiers, and regional regulatory cluster differentiation segment volume and value outputs. CAGRs derive from capacity expansion timelines in Japan's Sakigake corridors, FDA accelerated approval pathway utilization rates, and infusion center capacity constraints in rural United States markets.
Revisions become necessary when biomarker qualification progress stalls at FDA or EMA, when hospital procurement consolidation accelerates beyond modeled integrated delivery network concentration thresholds, or when subcutaneous formulation advances displace intravenous administration faster than projected. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Multiple Sclerosis Therapies Market
Neurology
Interventional Neurology Market
Neurology
Hepatic Encephalopathy Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
Middle-East and Africa Neurology Monitoring Market
Neurology
Neurology Devices Market
Neurology
Neurology Digital Therapeutics Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Europe Pediatric Neurology Device Market
Neurology
South Korea Neurology Devices Market
Neurology
Multiple Sclerosis Treatment Market
Neurology
Pediatric Neurology Device Market
Neurology
Optic Neuritis Treatment Market
Neurology
AIDS Related Primary CNS Lymphoma Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
CNS Treatment and Therapy Market