
 Global Hemato Oncology Testing Market | 2026-2036
Global Hemato Oncology Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemato Oncology Testing Market Foresight
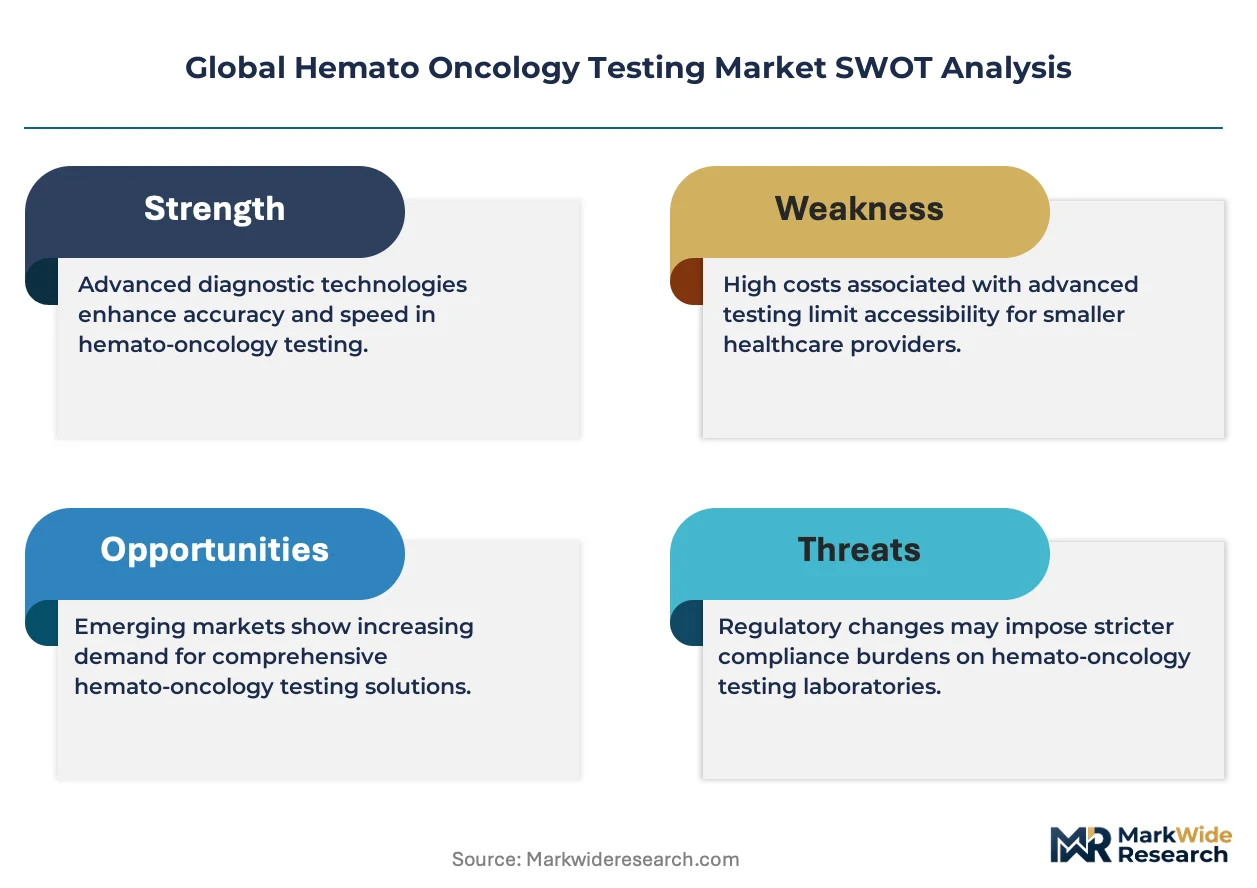
CLIA certification for high-complexity molecular diagnostics is rotating the competitive set toward laboratories with proven quality management systems. F. Hoffmann-La Roche Ltd. leverages its integrated instrument-reagent platforms to dominate clinical flow cytometry workflows. Illumina Inc. anchors the next-generation sequencing segment through sustained R&D intensity in hematologic cancer panels. Sysmex Corporation competes aggressively in automated hematology analyzers with strong channel control across Asian diagnostic networks.
Hemato oncology testing encompasses laboratory methodologies that detect, classify, and monitor blood cancers through cellular morphology analysis, immunophenotyping, chromosomal evaluation, and nucleic acid sequencing, typically requiring specimen volumes of 2-5 milliliters of bone marrow aspirate or peripheral blood collected in EDTA tubes. The primary commercial purpose is to enable precision therapy selection and minimal residual disease monitoring in acute leukemias, lymphomas, and myeloproliferative conditions. Molecular diagnostics captures expanding margin pools as oncologists demand actionable mutation data for targeted therapy decisions. Next-generation sequencing grows fastest among product categories as panel costs decline and turnaround times compress. Flow cytometry remains the mature workhorse for initial leukemia-lymphoma immunophenotyping across pathology labs worldwide.
The FDA regulates companion diagnostic claims for hematologic malignancies through its Center for Devices and Radiological Health, while the EMA's In Vitro Diagnostic Medical Devices Regulation tightens performance requirements across European laboratories. Japan's PMDA accelerates review pathways for novel cancer biomarker assays, directly shaping where manufacturers prioritize clinical trial investments. Stakeholders must monitor evolving reimbursement codes for liquid biopsy applications in minimal residual disease testing as payers recalibrate coverage policies for blood-based monitoring protocols.
Market Dynamics
Companion diagnostic mandates from the FDA and EMA are compressing development timelines for hematologic malignancy assays, forcing laboratories to validate biomarker panels before drug approval rather than retrofitting post-launch. This regulatory synchronization is redrawing competitive boundaries between instrument manufacturers and molecular testing service providers.
Growth Catalysts
- EMA In Vitro Diagnostic Medical Devices Regulation:The MDR's stricter performance requirements are consolidating laboratory demand toward certified high-complexity molecular diagnostic providers with established quality management systems.
- Academic medical centers:These institutions are expanding molecular profiling adoption for leukemia and lymphoma diagnostics, creating volume anchors for next-generation sequencing panel manufacturers.
- Liquid biopsy protocols:Blood-based minimal residual disease monitoring is displacing bone marrow aspiration for longitudinal patient surveillance, reducing procedural burden and expanding testing frequency.
Market Restraints
- Reimbursement code lag:Payers in the United States and Germany maintain limited coverage for circulating tumor DNA assays in hematologic malignancies, constraining commercialization of novel blood-based monitoring tests.
- Input cost volatility:Specialized fluorescent dyes and rare-earth magnetic beads for flow cytometry face supply concentration from Japanese and German chemical suppliers, creating margin pressure for reagent manufacturers.
- Technical limitation:Current next-generation sequencing platforms require 2-5 milliliter specimen volumes that exceed feasible collection from pediatric oncology patients or severely cytopenic adults.
Strategic Opportunities
- India's diagnostic network expansion:The country's PLI scheme for medical devices and fragmented pathology infrastructure create entry points for automated hematology analyzer deployment in tier-2 and tier-3 cities.
- Technology convergence:Artificial intelligence-assisted morphology analysis integrated with digital flow cytometry is enabling remote diagnostic interpretation, opening rural and underserved markets.
- Japan's PMDA accelerated review:The regulator's fast-track pathway for novel cancer biomarker assays directs manufacturer clinical trial investment toward hematologic malignancy applications.
Industry Challenges
- Molecular pathologist shortage:The specialized training required for interpreting complex genomic findings in hematologic neoplasms exceeds current fellowship output in the United States and Germany.
- CLIA certification timelines:High-complexity molecular diagnostics laboratories face 12-18 month validation periods for new assay platforms, delaying commercial service launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemato Oncology Testing Market |
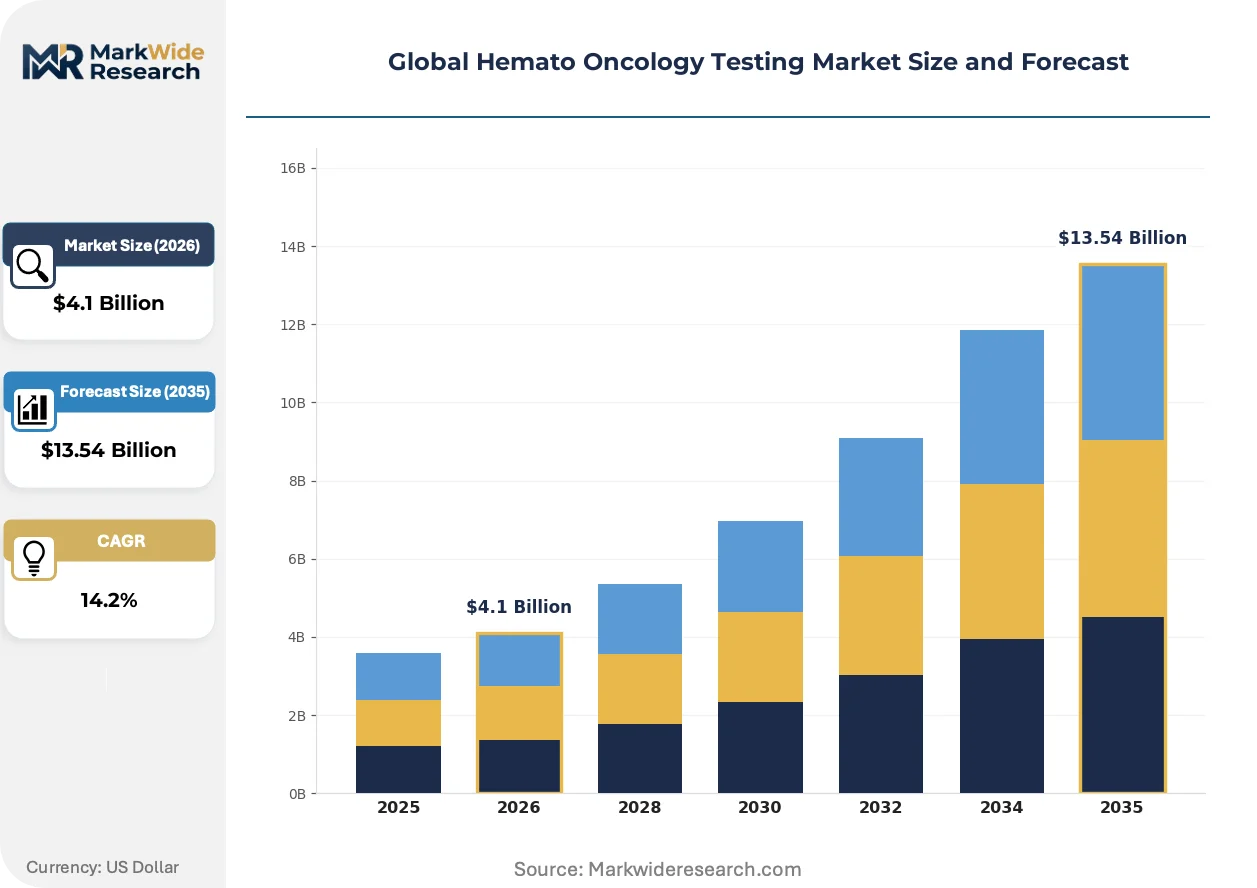
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $13.54 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometry, Immunohistochemistry, Molecular Diagnostics, Cytogenetics, Next-Generation Sequencing Therapy Area: Leukemia, Lymphoma, Multiple Myeloma, Myelodysplastic Syndromes, Chronic Myeloproliferative Disorders End User: Pathology Labs, Research Institutes, Diagnostic Laboratories, Specialty Clinics, Academic Hospitals Testing Methodology: Qualitative Assays, Quantitative Assays, Cytogenetic Analysis, Molecular Profiling, Biomarker Identification |
| Companies Covered | F. Hoffmann-La Roche Ltd., Abbott Laboratories, Thermo Fisher Scientific Inc., QIAGEN N.V., Danaher Corporation, Bio-Rad Laboratories Inc., Illumina Inc., Sysmex Corporation, Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemato Oncology Testing Market Shifts & Advancements
Digital pathology platforms and artificial intelligence-assisted diagnostic tools are compressing interpretation timelines for complex hematologic specimens. These technologies are redistributing expertise from centralized academic centers toward community pathology laboratories.
Next-generation sequencing panels with expanded gene coverage are displacing single-gene PCR assays and fluorescent in situ hybridization for initial leukemia classification. Academic hospitals in the United States and Germany are adopting these comprehensive platforms within 18-24 month procurement cycles. The shift is compressing reimbursement negotiations and forcing reagent manufacturers to bundle content rather than sell discrete tests.
The FDA's continued guidance on companion diagnostics for hematologic malignancies through its Center for Devices and Radiological Health is harmonizing assay validation requirements with drug approval pathways. This regulatory convergence is reducing redundant clinical trials for biomarker test developers. Lymphoma and acute myeloid leukemia therapeutic categories are experiencing the most pronounced alignment between diagnostic and pharmaceutical regulatory review.
Hospital procurement departments are consolidating vendor relationships for hematology analyzers and molecular diagnostic platforms, favoring integrated instrument-reagent contracts over best-of-breed component sourcing. This concentration is displacing smaller specialty reagent suppliers from institutional formulary positions. The United States and Japan exhibit the most aggressive procurement consolidation, with multi-year sole-source agreements replacing competitive bidding for routine testing workflows.
Global Hemato Oncology Testing Market Segmentation
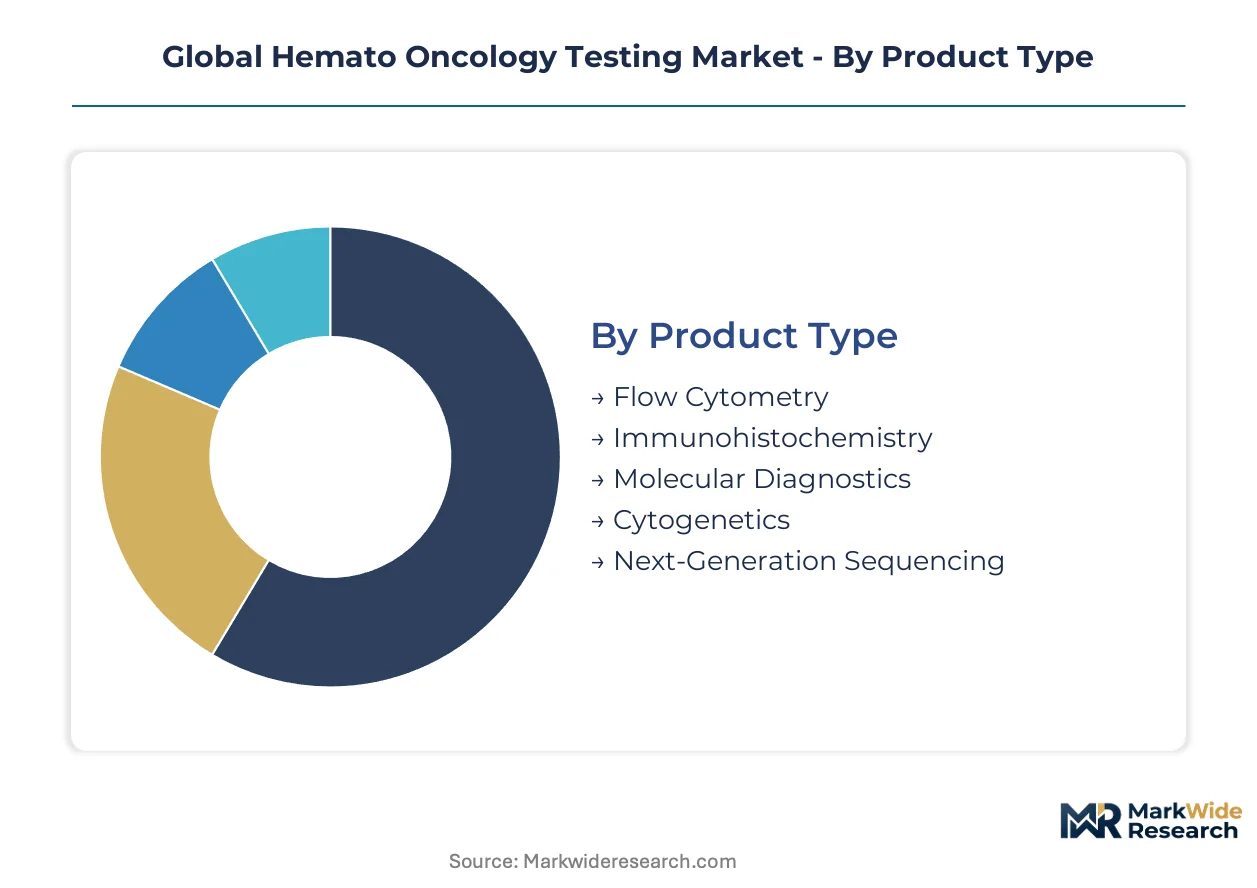
Segmentation in hemato oncology testing reveals how technological substitution and clinical workflow integration reshape purchasing decisions across laboratories. Product categories face divergent pressure from automated platforms, while therapy areas and end users concentrate demand based on disease prevalence and reimbursement infrastructure.
Product Type:
Next-generation sequencing platforms are displacing single-gene PCR assays fastest, forcing incumbent technologies to defend installed bases through bundled reagent contracts.
- Flow Cytometry:Laser-based cell sorting and fluorescence detection systems process 10,000-50,000 events per second for leukemia immunophenotyping. Academic hospitals in the United States and Germany maintain the highest throughput volumes, though instrument refresh cycles have extended to 7-10 years as laboratories prioritize molecular platform investments.
- Next-Generation Sequencing:Targeted gene panels spanning 50-500 genes deliver mutation profiles for therapy selection and minimal residual disease monitoring. Demand concentrates in academic medical centers where pathologists interpret complex genomic findings for clinical trials; panel costs below $400 are compressing gross margins for reagent manufacturers.
- Molecular Diagnostics:Real-time PCR and digital PCR platforms detect fusion transcripts and mutation burdens with sensitivity thresholds of 0.01% variant allele frequency.
- Immunohistochemistry:Antibody-based protein detection on formalin-fixed tissue sections supports lymphoma subtyping in community pathology settings.
- Cytogenetics:Karyotyping and FISH analysis for chromosomal translocations retains regulatory importance for initial leukemia classification despite slower turnaround times.
Flow cytometry retains volume leadership across pathology laboratories worldwide; next-generation sequencing holds the steepest expansion curve as panel standardization accelerates.
Therapy Area:
Leukemia diagnostics command the highest testing frequency per patient due to longitudinal minimal residual disease monitoring requirements.
- Leukemia:Acute myeloid leukemia and acute lymphoblastic leukemia drive intensive testing protocols spanning diagnosis, risk stratification, treatment response, and relapse surveillance. Academic hospitals in the United States and Japan process the highest per-patient test volumes, with molecular profiling now standard for FLT3, NPM1, and BCR-ABL1 mutation assessment.
- Lymphoma:Diffuse large B-cell lymphoma and follicular lymphoma require immunophenotyping and clonality assessment for subtype classification. Germany's specialized pathology networks concentrate demand for comprehensive molecular characterization, particularly for CAR-T therapy eligibility screening.
- Multiple Myeloma:Serum protein electrophoresis and free light chain assays combine with bone marrow molecular testing for disease staging.
- Myelodysplastic Syndromes:Cytogenetic and sequencing panels guide prognosis and transplant timing decisions in specialized hematology centers.
- Chronic Myeloproliferative Disorders:JAK2, CALR, and MPL mutation testing supports diagnosis of polycythemia vera and essential thrombocythemia.
Leukemia generates the highest revenue per diagnosed patient; lymphoma shows the strongest testing volume growth as novel immunotherapies expand eligible populations.
End User:
Procurement authority is consolidating toward health system central laboratories, displacing independent reference laboratory relationships.
- Academic Hospitals:Integrated cancer centers combine clinical service with research biobanking, creating dual revenue streams for molecular testing platforms. The United States maintains the highest concentration of NCI-designated comprehensive cancer centers with dedicated hemato oncology pathology divisions.
- Pathology Labs:Community and hospital-based laboratories perform initial immunophenotyping and morphology review before referring complex cases. Germany's regional pathology networks standardize testing menus across affiliated hospitals, concentrating purchasing power at network level.
- Diagnostic Laboratories:National reference laboratories process high-volume send-out testing with automated workflow integration.
- Research Institutes:Discovery-focused sequencing supports biomarker validation and companion diagnostic development programs.
- Specialty Clinics:Hematology-focused ambulatory centers rely on external laboratory partnerships for molecular testing access.
Academic hospitals anchor premium pricing for complex molecular assays; diagnostic laboratories capture scale economies through automated platform standardization.
Testing Methodology:
Quantitative assay capabilities are becoming table stakes as laboratories compete for minimal residual disease monitoring contracts.
- Molecular Profiling:Comprehensive genomic characterization using NGS and digital PCR platforms enables therapy selection and resistance monitoring. Academic medical centers in Japan and the United States are expanding in-house profiling capacity to reduce send-out turnaround times below 10 days.
- Quantitative Assays:Droplet digital PCR and quantitative PCR deliver precise variant allele frequency measurements for measurable residual disease tracking. Germany's reference laboratories have standardized on quantitative BCR-ABL1 monitoring for chronic myeloid leukemia management.
- Qualitative Assays:Presence-absence mutation detection supports initial diagnostic screening and therapy eligibility determination.
- Cytogenetic Analysis:Chromosomal microarray and conventional karyotyping retain regulatory significance for myelodysplastic syndrome classification.
- Biomarker Identification:Prospective biomarker discovery programs in research settings feed companion diagnostic development pipelines.
Molecular profiling commands the highest reimbursement rates; quantitative assays are gaining share fastest as longitudinal monitoring protocols expand across leukemia and lymphoma indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's Center for Devices and Radiological Health in Silver Spring, Maryland anchors regulatory precedent for companion diagnostic approvals. Academic medical centers along the Boston-Washington corridor process the highest per-capita molecular testing volumes for hematologic malignancies.
United States
NCI-designated comprehensive cancer centers in Houston and New York City drive adoption of next-generation sequencing panels for leukemia classification. The FDA's continued guidance on companion diagnostics shapes validation timelines for biomarker assay developers. Academic hospitals in the Research Triangle and Greater Boston concentrate clinical trial recruitment for novel hematologic cancer tests.
Germany
Specialized pathology networks in Munich and Heidelberg standardize molecular profiling menus across affiliated hospital systems. The EMA's In Vitro Diagnostic Medical Devices Regulation tightens performance requirements for laboratories serving the Rhine-Ruhr metropolitan region. Reference laboratories in Berlin consolidate purchasing power for automated hematology analyzers through multi-year procurement frameworks.
Japan
The PMDA's accelerated review pathway for novel cancer biomarker assays directs manufacturer investment toward Tokyo and Osaka clinical trial sites. Academic medical centers in Kobe and Nagoya expand in-house sequencing capacity to reduce send-out turnaround times. Sysmex Corporation's channel control across diagnostic networks reinforces instrument placement in prefectural hospital laboratories.
India
The PLI scheme for medical devices supports automated hematology analyzer deployment in tier-2 cities across Maharashtra and Karnataka. Fragmented pathology infrastructure in Gujarat and Tamil Nadu creates entry points for integrated instrument-reagent platforms. Diagnostic networks in Hyderabad and Chennai pilot artificial intelligence-assisted morphology analysis for leukemia screening.
United Kingdom
NHS England's specialized commissioning frameworks concentrate complex molecular testing in London and Manchester academic centers. The MHRA's post-Brexit regulatory pathway for in vitro diagnostics shapes validation requirements for Cambridge and Oxford biotech clusters. Regional pathology networks in the Midlands standardize immunophenotyping protocols across district general hospitals.
Global Hemato Oncology Testing Market Competitive Landscape
Listed leaders compete with private specialists across instrument-reagent integration and molecular platform development. The competitive set rotates toward laboratories with proven quality management systems as CLIA certification requirements tighten. Three archetypes dominate: integrated diagnostic conglomerates with captive reagent supply, pure-play sequencing platform developers, and automated hematology specialists with regional channel control. Consolidation favors multi-year sole-source agreements over competitive bidding; technology licensing accelerates panel content expansion.
Within the integrated diagnostic tier, F. Hoffmann-La Roche Ltd. and Danaher Corporation exemplify instrument-reagent bundling strategies. Illumina Inc. occupies a position representing next-generation sequencing platform specialization. Sysmex Corporation anchors the automated hematology analyzer segment with established presence across Asian diagnostic networks. These three companies collectively illustrate the competitive tension between comprehensive platform ownership and focused technology leadership.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| Danaher Corporation |
| Bio-Rad Laboratories Inc. |
| Illumina Inc. |
| Sysmex Corporation |
| Agilent Technologies Inc. |
| Others |
Supply & Pricing Matrix
Fourteen-to-eighteen-month CLIA certification timelines for high-complexity molecular diagnostics compress inventory cycles and concentrate pricing power with laboratories holding established quality credentials. Supply concentration in Japanese fluorescent dye production and German magnetic bead manufacturing amplifies cost pass-through capacity for certified reagent suppliers serving academic medical centers.
Pricing Analysis
Volume-discount tiering separates NCI-designated comprehensive cancer centers from community pathology laboratories and research institutes. Three-tier pricing structure across premium, standard, and economy levels reflects CLIA certification status, panel complexity, and after-sales interpretive support bundling. Cost compression in next-generation sequencing panels stems from declining gene-coverage costs and compressed turnaround-time competition. Community pathology laboratories exhibit highest price sensitivity due to constrained capital budgets; academic medical centers prioritize turnaround reliability over per-test economics.
Supply Chain Analysis
Specialized fluorescent dye manufacturing concentrates in Japan and Germany, creating single-source vulnerability for flow cytometry reagent producers. Hemato oncology testing draws from rare-earth magnetic beads, synthetic oligonucleotides, and high-purity polymerases as critical inputs. Tariff exposure on Japanese chemical imports threatens margin stability for North American reagent manufacturers. Distribution runs through integrated instrument-reagent contracts with multi-year sole-source agreements displacing competitive bidding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation toward health system central laboratories shifts bargaining power toward buyers with consolidated testing volumes. Academic medical center network expansion concentrates demand and compresses vendor margins.
For Market Incumbents: Fortify CLIA-certified laboratory relationships through captive reagent supply and extended service-level agreements. Deepen channel control in automated hematology analyzers to defend against molecular platform substitution. Prioritize backward integration into fluorescent dye production to offset Japanese supplier concentration risk.
For New Entrants and Emerging Players: Lead with artificial intelligence-assisted morphology analysis for India's tier-2 and tier-3 diagnostic networks. India's fragmented pathology infrastructure and PLI scheme for medical devices represent the most penetrable entry corridor. Pursue hospital system partnerships emphasizing remote diagnostic interpretation capabilities.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement authority centralization favors scaled platform providers over specialty reagent suppliers. Target laboratories with established FDA companion diagnostic validation pathways and academic medical center anchor contracts. Monitor EMA MDR enforcement intensity as inflection indicator for European laboratory consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Certification Investment | Quality credentials unlock academic medical center contracts and premium pricing tiers. |
| Companion Diagnostic Partnership | FDA-aligned validation pathways reduce redundant clinical trials for biomarker developers. |
| Liquid Biopsy Protocol Development | Blood-based minimal residual disease monitoring expands testing frequency and recurring revenue. |
| AI-Assisted Morphology Integration | Digital pathology platforms redistribute expertise toward underserved rural markets. |
| Integrated Instrument-Reagent Contracting | Multi-year sole-source agreements displace competitive bidding and lock in vendor positions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with molecular pathologists, hospital procurement managers, CLIA laboratory directors, and diagnostic reagent manufacturers; and secondary validation against FDA 510(k) filings, EMA In Vitro Diagnostic Medical Devices Regulation guidance documents, CMS Medicare reimbursement databases, and hospital GPO contract disclosures. Bottom-up testing volume estimates triangulated with top-down market sizing across instrument placements and reagent consumption patterns.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, therapy area, end user category, and testing methodology complexity. CAGRs derived from regression analysis of historical instrument installation bases and reagent pull-through rates. Industry-specific inputs incorporated academic medical center expansion plans, companion diagnostic approval velocities, and liquid biopsy protocol adoption curves.
Forecasts assume regulatory continuity in FDA companion diagnostic guidance and EMA MDR enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as payer reimbursement recalibration for circulating tumor DNA assays evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market