
 Bladder Cancer Detection Kit Market | 2026-2036
Bladder Cancer Detection Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Bladder Cancer Detection Kit Market Analysis
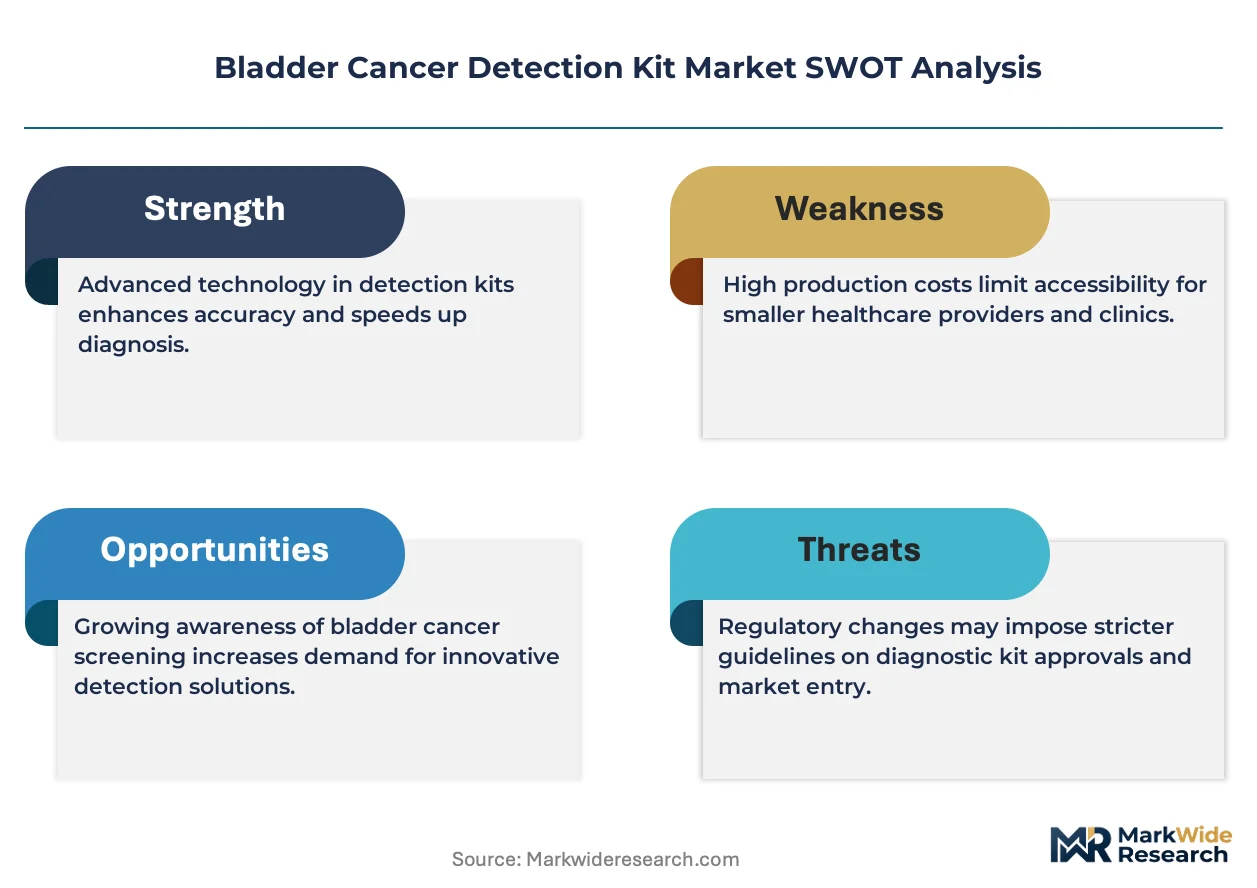
CE marking under the EU Medical Device Regulation is redrawing competitive access across Europe. Siemens Healthineers leverages its imaging-integrated diagnostics platform to anchor hospital procurement decisions. Thermo Fisher Scientific sustains molecular assay leadership through captive reagent supply chains. Danaher Corporation competes on workflow automation density in high-throughput laboratories.
Bladder cancer detection kits comprise in vitro diagnostic systems that identify malignant urothelial cells through protein biomarkers, nucleic acid amplification, or optical imaging modalities, with sensitivity thresholds typically exceeding 80% for high-grade tumors. Their commercial purpose centers on enabling earlier intervention before muscle invasion, reducing cystoscopy burden, and supporting surveillance monitoring. Urinary biomarkers command expanding share as point-of-care formats mature, while molecular diagnostics capture margin pools through companion diagnostic linkages. Cystoscopy devices retain procedural anchoring in urology suites despite patient aversion to invasive examination.
The FDA governs premarket submission pathways through the 510(k) and de novo frameworks, while the EMA's In Vitro Diagnostic Medical Devices Regulation imposes post-market surveillance obligations that elevate quality system investments. Japan's PMDA maintains distinct clinical trial requirements for oncology diagnostics that delay entry relative to Western timelines. Stakeholders must weigh regulatory capital intensity against the pricing autonomy conferred by differentiated sensitivity specifications.
Market Dynamics
Hospital procurement committees now prioritize non-invasive urinary biomarker panels that reduce cystoscopy dependency, compressing adoption timelines for novel diagnostics and redrawing vendor qualification criteria across urology departments.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways compress commercialization timelines from 18-24 months to 8-12 months for qualifying bladder cancer assays, enabling earlier revenue capture.
- Point-of-Care Formats:Lateral flow and cartridge-based platforms are migrating biomarker testing from centralized laboratories into urology clinics, expanding addressable test volumes.
- Germany's Statutory Health Insurance:Reimbursement codes for urinary biomarker surveillance in high-risk patients create predictable payment streams that justify capital deployment.
Market Restraints
- Antibody Supply Concentration:Capture reagents for NMP22 and BTA assays originate from fewer than five specialized biologics suppliers, exposing kit manufacturers to batch variability and allocation risk.
- PMDA Clinical Trial Requirements:Japan's distinct oncology diagnostic validation protocols mandate local patient cohorts that extend entry timelines by 14-20 months versus Western markets.
- Cystoscopy Substitution Limits:Current urinary biomarker sensitivity for low-grade tumors remains below 60%, preserving invasive examination as the diagnostic anchor for initial diagnosis.
Strategic Opportunities
- Companion Diagnostic Linkages:PD-L1 and FGFR3 biomarker panels paired with immunotherapy pipelines create margin pools exceeding standard surveillance kits by 3-4x.
- Direct-to-Consumer Channels:Telehealth-integrated home collection kits bypass hospital procurement committees entirely, capturing patients with hematuria prior to specialist referral.
- EMA MDR Transition Windows:Smaller manufacturers lacking notified body relationships face 2027-2028 certification cliffs, creating acquisition targets for firms with established quality systems.
Industry Challenges
- Bioinformatics Talent Scarcity:Multi-omics assay development requires computational biologists capable of integrating methylation, mutation, and protein signatures, a skill set concentrated in oncology pharmaceutical firms.
- Legacy LIS Integration:Hospital laboratory information systems operate on 1990s-era HL7 standards that resist API connectivity with cloud-based biomarker interpretation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bladder Cancer Detection Kit Market |
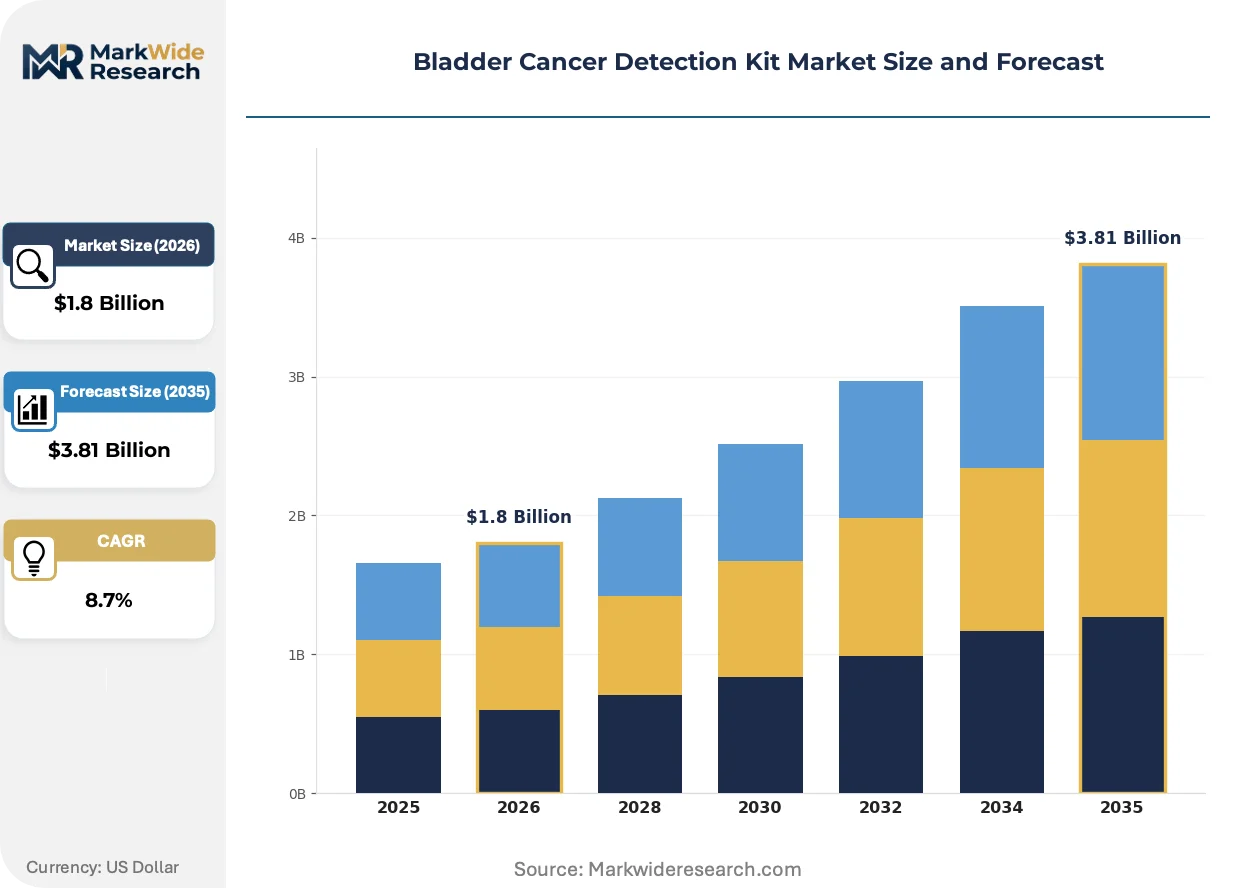
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urinary Biomarkers, Cystoscopy Devices, Imaging Systems, Laboratory Kits Delivery Mode: Home Use, Hospital Use, Laboratory Use, Telehealth End User: Oncologists, Urologists, Diagnostic Labs, Research Institutions Technology: Molecular Diagnostics, Imaging Techniques, Cytology, Pathology |
| Companies Covered | Siemens Healthineers, Thermo Fisher Scientific, Danaher Corporation, Roche Diagnostics, Abbott Laboratories, Hoffmann-La Roche, BioMerieux SA, Becton, Dickinson and Company, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bladder Cancer Detection Kit Market Emerging Trajectories
Urinary biomarker technology is converging with digital pathology and artificial intelligence to compress diagnostic decision cycles, while regulatory frameworks on both sides of the Atlantic accelerate approval velocity for qualifying innovations.
Microfluidic cartridge systems for nucleic acid amplification are miniaturizing molecular diagnostic workflows from benchtop equipment to handheld devices. Community urology practices in the United States are piloting these platforms for same-visit result delivery. This compression is eliminating the 48-72 hour send-out delay that previously fragmented patient pathways.
The EU Medical Device Regulation's post-market surveillance obligations are elevating quality system investments across European kit manufacturers. Clinical evidence generation requirements now extend beyond premarket submission into lifecycle monitoring. Mid-tier diagnostic firms without established vigilance infrastructure are outsourcing pharmacovigilance to specialized service providers.
Hospital value-analysis committees are unbundling biomarker test procurement from legacy group purchasing organization contracts. Integrated delivery networks in the United States are negotiating direct agreements with assay developers for preferred panel access. This disintermediation is most visible in the Southeast, where systems like HCA and Tenet are consolidating laboratory spend under centralized specialty pharmacy arrangements.
Bladder Cancer Detection Kit Market Segmentation
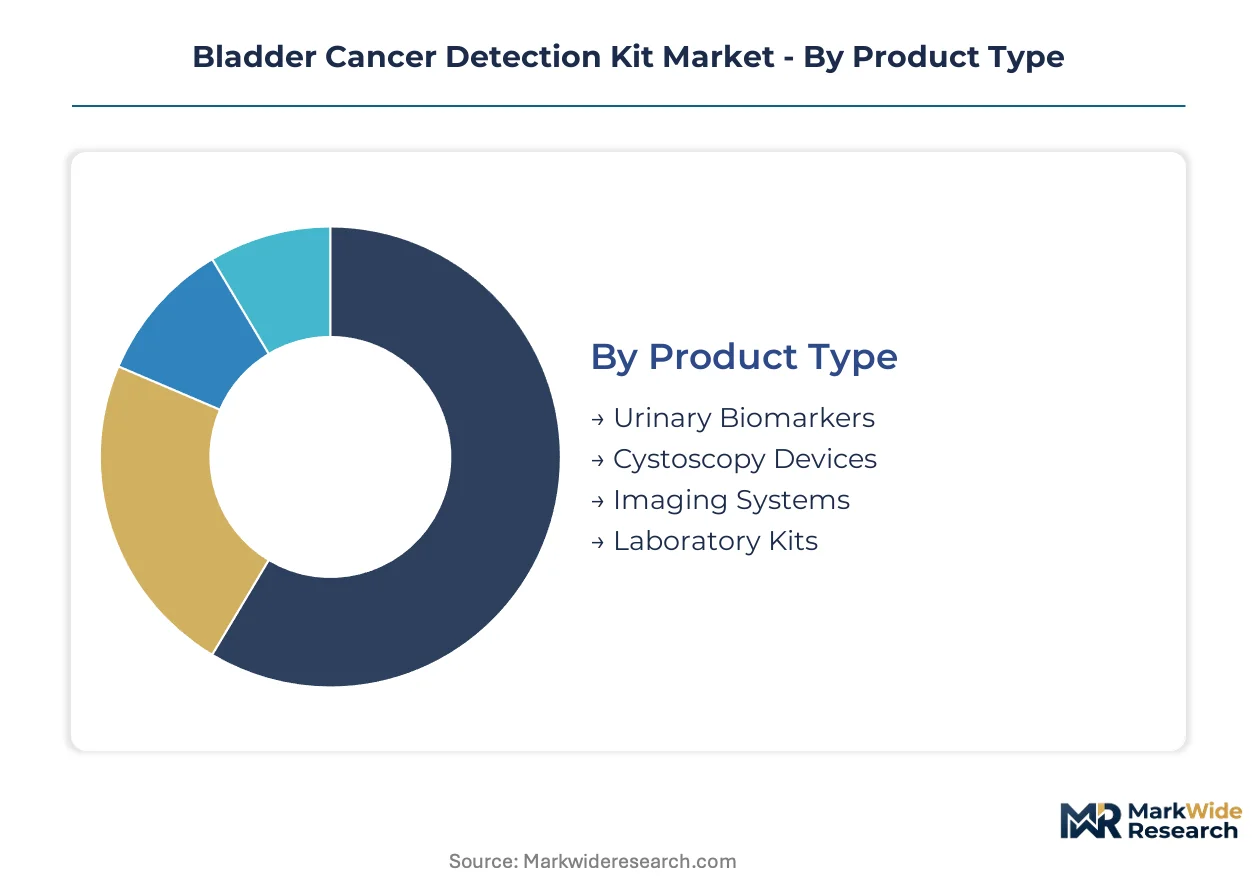
Bladder cancer detection kit segmentation reveals distinct channel economics where urinary biomarkers flow through telehealth and home collection routes while cystoscopy devices anchor hospital procurement. Technology-platform choices determine margin structure and regulatory capital intensity across each segment cluster.
Product Type:
Urinary biomarkers and cystoscopy devices command divergent distribution channels, with biomarker panels penetrating direct-to-consumer and telehealth pathways while endoscopic systems require capital equipment sales forces.
- Urinary Biomarkers:Protein and nucleic acid-based assays detect NMP22, BTA, and FGFR3 alterations in voided urine samples. Demand concentrates in Germany and Japan where statutory reimbursement codes for surveillance monitoring reduce patient cost burden. Point-of-care cartridge formats are displacing centralized laboratory send-outs in United States urology clinics.
- Cystoscopy Devices:Flexible and rigid endoscopic systems with optical or digital imaging capability enable direct visual inspection of bladder mucosa. Hospital procurement committees in the United States prioritize single-use scopes to eliminate reprocessing liability, while German ambulatory surgery centers favor durable equipment with extended service contracts.
- Imaging Systems:Fluorescence and narrow-band imaging modalities enhance mucosal contrast during endoscopic examination.
- Laboratory Kits:Benchtop assay platforms with automated sample processing serve high-throughput reference laboratories.
Urinary biomarkers dominate installed base in surveillance applications. Cystoscopy devices are where expansion concentrates for initial diagnosis protocols.
Delivery Mode:
Cost tier stratification separates premium hospital-integrated systems from economy home collection formats, with telehealth platforms capturing margin through subscription bundling.
- Home Use:Patient-collected urine specimens shipped to processing laboratories or analyzed with lateral flow devices. United States telehealth providers integrate these kits into hematuria triage workflows, bypassing traditional specialist referral pathways. FDA 510(k) clearance for over-the-counter formats remains limited, constraining mass-market penetration.
- Hospital Use:Inpatient and same-day surgical settings deploy integrated diagnostic platforms with immediate result availability. Japanese hospital procurement favors multi-parameter systems that consolidate oncology and infectious disease testing to maximize equipment utilization rates.
- Laboratory Use:Reference laboratories process batched specimens with automated molecular analyzers. Germany's statutory health insurance reimbursement structure supports dedicated bladder cancer surveillance panels in regional laboratory networks.
- Telehealth:Virtual care platforms coordinate home specimen collection with remote interpretation and specialist referral. United States digital health companies leverage this channel to capture patients prior to health system affiliation.
Hospital use retains the highest average revenue per test. Telehealth delivery is gaining share fastest among newly diagnosed patients.
End User:
Customer type determines purchasing authority, with oncologists driving companion diagnostic adoption and urologists controlling surveillance testing volumes.
- Oncologists:Medical oncology practices order PD-L1 and FGFR3 biomarker panels to guide immunotherapy and targeted therapy selection. United States academic medical centers concentrate this demand where clinical trial access shapes testing protocols. Reimbursement through Medicare's molecular pathology schedule creates predictable payment streams.
- Urologists:Surgical and medical urology practices manage the majority of bladder cancer surveillance testing. Community practices in the United States Southeast are consolidating laboratory spend under integrated delivery network arrangements, compressing vendor qualification timelines.
- Diagnostic Labs:Independent and hospital-affiliated laboratories serve as intermediaries for biomarker processing.
- Research Institutions:Academic centers validate novel biomarker signatures and conduct clinical utility studies.
Urologists dominate installed base for surveillance monitoring. Oncologists represent the steepest expansion trajectory through companion diagnostic linkages.
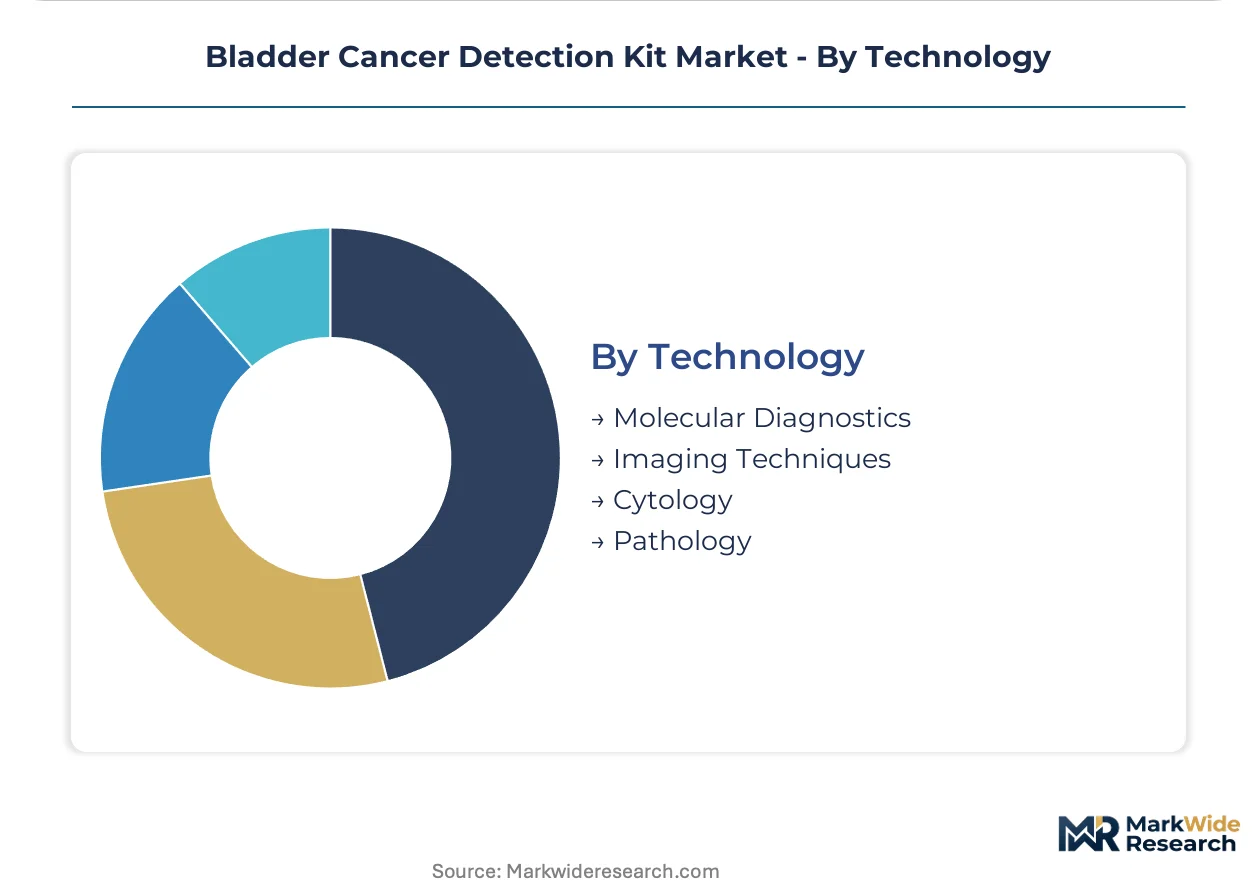
Technology:
Maturity curves separate established cytology methods from emerging molecular platforms, with imaging techniques occupying intermediate adoption positions.
- Molecular Diagnostics:PCR, NGS, and methylation-based assays detect genetic alterations with sensitivity exceeding 80% for high-grade tumors. Japanese PMDA clinical trial requirements delay commercial entry relative to FDA timelines, concentrating near-term revenue in Western markets. Multi-omics platforms integrating mutation, methylation, and protein signatures command premium pricing.
- Imaging Techniques:Fluorescence cystoscopy and optical coherence tomography enhance mucosal visualization beyond white-light examination. German hospital procurement committees evaluate these technologies based on reduction of second-look procedures and improved detection of carcinoma in situ.
- Cytology:Conventional and liquid-based urine cytology remain the reference standard for initial screening despite suboptimal sensitivity for low-grade lesions.
- Pathology:Digital pathology and AI-assisted image analysis streamline specimen interpretation.
Cytology dominates installed base as the reference standard. Molecular diagnostics is where expansion concentrates for high-risk patient stratification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in aging economies drive the majority of bladder cancer detection kit volumes. Buyer concentration clusters in health systems with established urology service lines and statutory reimbursement frameworks for surveillance monitoring.
United States
Medicare's molecular pathology schedule creates predictable payment streams for PD-L1 and FGFR3 companion diagnostics. The FDA's breakthrough device designation compresses commercialization timelines for qualifying assays. Integrated delivery networks in the Southeast consolidate laboratory spend under centralized specialty pharmacy arrangements.
Germany
Statutory health insurance reimbursement codes for urinary biomarker surveillance in high-risk patients justify capital deployment for regional laboratory networks. The EU Medical Device Regulation's post-market surveillance obligations elevate quality system investments for domestic kit manufacturers. The Rhine-Ruhr metropolitan region hosts dense clusters of reference laboratories processing batched specimens.
Japan
Aging demographics expand screening volumes for non-invasive urinary biomarker panels in hospital-based urology departments. The PMDA maintains distinct clinical trial requirements for oncology diagnostics that delay entry timelines relative to Western markets. Tokyo's academic medical centers concentrate demand where clinical trial access shapes testing protocols.
United Kingdom
NHS England's Cancer Programme targets earlier detection through streamlined hematuria referral pathways. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for post-market surveillance obligations. London's integrated care systems pilot telehealth-integrated home collection kits to bypass traditional specialist referral pathways.
China
Rising incidence of bladder cancer in industrialized provinces expands addressable patient populations for molecular diagnostic platforms. The National Medical Products Administration accelerates review pathways for innovative diagnostics meeting unmet clinical needs. Shanghai's Pudong New Area attracts multinational assay developers establishing regional headquarters and manufacturing facilities.
Bladder Cancer Detection Kit Market Vendor Landscape
Player mix skews toward diversified life science conglomerates with captive reagent supply chains and established hospital procurement relationships. Market structure concentrates around three to five integrated diagnostic platforms that anchor multi-year group purchasing organization contracts. Strategic archetypes include imaging-integrated diagnostics providers, molecular assay specialists with workflow automation density, and point-of-care format innovators. Dominant competitive moves encompass vertical integration into antibody supply chains and strategic partnerships with telehealth platforms for direct-to-consumer channel access.
Among diversified diagnostic conglomerates, Siemens Healthineers, Thermo Fisher Scientific, and Danaher Corporation exemplify contrasting strategic positions. Siemens Healthineers occupies a position as an imaging-integrated diagnostics platform leveraging hospital procurement relationships. Thermo Fisher Scientific represents molecular assay leadership through captive reagent supply chains. Danaher Corporation anchors the workflow automation density archetype in high-throughput laboratory environments.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Roche Diagnostics |
| Abbott Laboratories |
| Hoffmann-La Roche |
| BioMerieux SA |
| Becton, Dickinson and Company |
| Sysmex Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-day antibody inventory cycles at specialized biologics suppliers concentrate pricing power for capture reagents, tethering kit manufacturers to volatile input costs while hospital procurement committees exploit volume consolidation to compress margins on standardized assays.
Pricing Analysis
Cost-plus contracts with antibody suppliers indexed to biologics manufacturing input costs dominate procurement arrangements for NMP22 and BTA assay manufacturers. Pricing stratifies across premium, standard, and economy tiers based on sensitivity specifications and FDA breakthrough device certification status. Cost compression in point-of-care formats is intensifying because cartridge miniaturization demands specialized microfluidic engineering talent. Community urology practices exhibit highest price sensitivity, while academic medical centers prioritize sensitivity thresholds over per-test economics.
Supply Chain Analysis
Antibody production chokepoints in Switzerland, Germany, and the United States expose kit manufacturers to allocation risk during biologics manufacturing campaigns. Capture reagents draw from mammalian cell culture facilities and recombinant protein synthesis operations concentrated in Basel and Boston metropolitan clusters. Single-source vulnerability for high-affinity monoclonal antibodies creates supply disruption exposure during facility contamination events. Distribution runs through captive reagent supply chains at diversified life science conglomerates and specialized biologics distributors serving regional laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bladder cancer detection kits occupy an early-cycle expansion trajectory as point-of-care formats displace centralized laboratory workflows, with FDA breakthrough device designation compressing commercialization timelines for qualifying molecular diagnostics.
For Market Incumbents: Consolidate antibody supply relationships through captive biologics manufacturing or exclusive licensing arrangements with Swiss and German specialty suppliers. Lock in multi-year preferred provider status with integrated delivery networks in the United States Southeast before telehealth platforms capture patient volumes upstream. Defend against direct-to-consumer channel erosion by embedding interpretation software into urology clinic workflows. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers the most penetrable regulatory pathway for novel multi-omics panels, compressing review timelines versus standard 510(k) submissions. Target Germany's statutory health insurance reimbursement codes for urinary biomarker surveillance, where predictable payment streams reduce commercialization risk. Pursue telehealth-integrated home collection kit partnerships to bypass hospital procurement committee gatekeeping entirely. For Investors and Strategic Acquirers: Long-term, this sits as a diagnostics platform consolidation play because companion diagnostic linkages to immunotherapy pipelines create margin pools exceeding standard surveillance kits by multiples. Acquisition targets center on mid-tier molecular assay developers with established quality systems but lacking notified body relationships for EU MDR transition. Watch FDA breakthrough device designation grant velocity as an inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Device Designation Pursuit | FDA accelerated review compresses commercialization timelines from standard pathways for qualifying bladder cancer assays. |
| Antibody Supply Chain Captivity | Backward integration into biologics manufacturing reduces batch variability exposure for NMP22 and BTA capture reagents. |
| Telehealth Platform Partnership | Direct-to-consumer channel access bypasses hospital procurement committees and captures hematuria patients prior to referral. |
| EU MDR Certification Investment | Notified body relationships create acquisition currency as smaller manufacturers face certification cliffs. |
| Companion Diagnostic Linkage Development | PD-L1 and FGFR3 panel pairing with immunotherapy pipelines commands premium pricing through oncology channel access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and de novo submission databases, EMA MDR transition filings, and hospital procurement contract disclosures. Interviews with urology department heads, hospital laboratory directors, GPO contracts managers, and molecular assay R&D executives informed demand-side validation. Secondary sources include ClinicalTrials.gov oncology diagnostic protocols, CMS Medicare molecular pathology schedule updates, and statutory health insurance reimbursement code registers in Germany and Japan. Bottom-up test volume modeling triangulates against top-down market sizing from diagnostic equipment installed base estimates.
Segmentation dimensions modeled span product type, delivery mode, end user, and technology platform across the analysis window. Urinary biomarker versus cystoscopy device splits, point-of-care versus laboratory deployment configurations, and urologist versus oncologist purchasing authority shape volume allocation. CAGRs derive from test volume elasticity to reimbursement policy changes and sensitivity specification improvements. Forecast inputs incorporate PMDA clinical trial timeline differentials for Japanese market entry and EU MDR post-market surveillance cost escalation.
Underlying assumptions cover stable statutory reimbursement codes in Germany, FDA breakthrough device designation velocity, and antibody supply chain concentration, with deviation risk concentrated in PMDA regulatory delays and telehealth platform channel capture rates. Revision becomes warranted when point-of-care sensitivity thresholds for low-grade tumors cross clinically validated thresholds that alter cystoscopy substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market