
 Multi Cancer Early Detection Market | 2026-2036
Multi Cancer Early Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Cancer Early Detection Market Intelligence
Oncology clinics are redrawing procurement priorities toward blood-based screening programs, while hospitals retain larger volume contracts for diagnostic confirmation. GRAIL leverages extensive cfDNA methylation databases to anchor its commercial position in asymptomatic screening. Exact Sciences Corporation sustains diversified revenue across colorectal and emerging multi-cancer portfolios. Guardant Health competes through liquid biopsy platforms that span both treatment selection and early detection use cases.
Multi cancer early detection comprises molecular diagnostic platforms that simultaneously interrogate circulating biomarkers—cell-free DNA, proteins, metabolites, or exosomal contents—across multiple cancer types from a single specimen draw, typically requiring 10-20 mL of peripheral blood and achieving analytical specificity above 99% through massively parallel sequencing or affinity-based capture methods. Blood tests command the dominant revenue share given minimal invasiveness and scalable collection infrastructure, while next-generation sequencing platforms absorb the majority of instrument placement investments due to throughput requirements and multiplexing depth. Liquid biopsy technology segments attract accelerated R&D allocation as proteomic and methylation panel combinations broaden detectable cancer signal breadth.
The FDA breakthrough device program and CMS national coverage determination processes govern market access timelines and reimbursement viability for multi-cancer tests in the United States. EMA's in vitro diagnostic regulation and health technology assessment frameworks across Germany, France, and the United Kingdom shape European commercialization pathways and evidence generation requirements. Stakeholders must monitor evolving regulatory evidentiary standards for asymptomatic screening claims and corresponding payer willingness to fund population-scale deployment without established mortality benefit data.
Market Dynamics
The central structural force reshaping multi-cancer early detection is the FDA breakthrough device designation pathway, which compresses commercialization timelines and triggers parallel CMS national coverage determination processes that determine Medicare reimbursement viability.
Growth Catalysts
- CMS National Coverage Determination:Medicare reimbursement deliberations in the United States create immediate private payer follow-on coverage, expanding addressable patient populations for blood-based screening panels.
- cfDNA Methylation Platforms:Methylation pattern analysis combined with machine learning classification algorithms improves cancer signal origin prediction, driving clinical validation studies across oncology networks.
- Diagnostic Laboratory Expansion:Reference laboratories in the United States are scaling high-throughput sequencing infrastructure to process 10-20 mL blood specimens at population health volumes.
Market Restraints
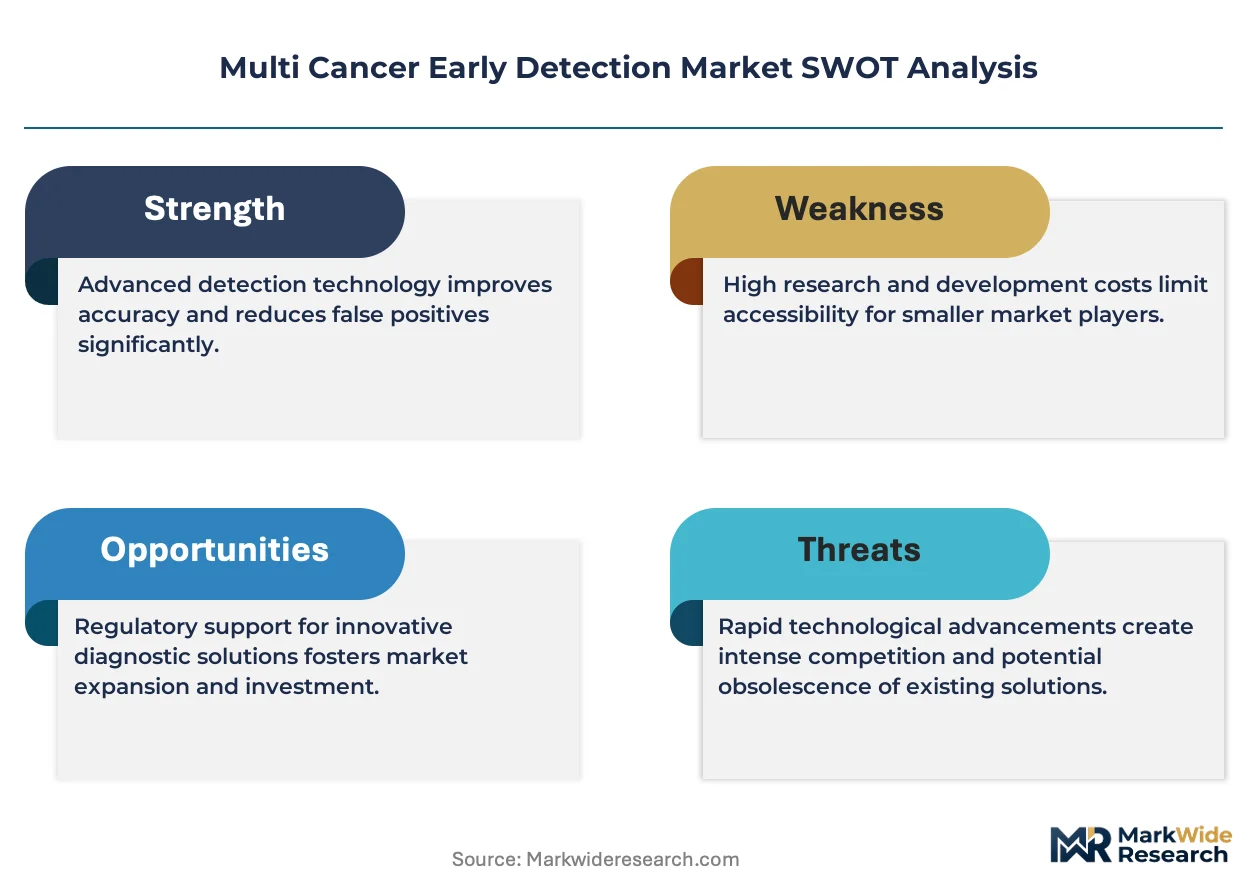
- Evidence Generation Burden:The FDA requires mortality benefit demonstration for asymptomatic screening claims, extending pivotal trial timelines beyond typical diagnostic validation cycles.
- Sequencing Reagent Concentration:Illumina and Thermo Fisher control 80% of next-generation sequencing consumables, creating input cost volatility for test developers.
- False Positive Management:Analytical specificity above 99% still generates clinically significant false positive rates at population scale, requiring expensive downstream diagnostic confirmation.
Strategic Opportunities
- Employer-Sponsored Wellness:Self-insured employers in the United States are piloting blood-based screening as differentiated health benefit offerings, bypassing traditional payer prior authorization.
- Proteomic Panel Convergence:Combination assays integrating circulating protein signatures with cfDNA methylation patterns promise expanded cancer type coverage without proportional cost increase.
- EMA IVDR Transition:The European Union's In Vitro Diagnostic Regulation creates first-mover advantage for manufacturers completing performance studies under new notified body requirements.
Industry Challenges
- Bioinformatics Talent Scarcity:Computational biology and machine learning engineering functions face acute hiring competition from technology and pharmaceutical sectors.
- CLIA Laboratory Certification:High-complexity molecular diagnostic laboratory accreditation requires 12-18 month facility validation timelines that delay market entry.
- EHR Integration Complexity:Electronic health record connectivity for screening result delivery and care coordination demands fragmented interoperability standards across hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Cancer Early Detection Market |
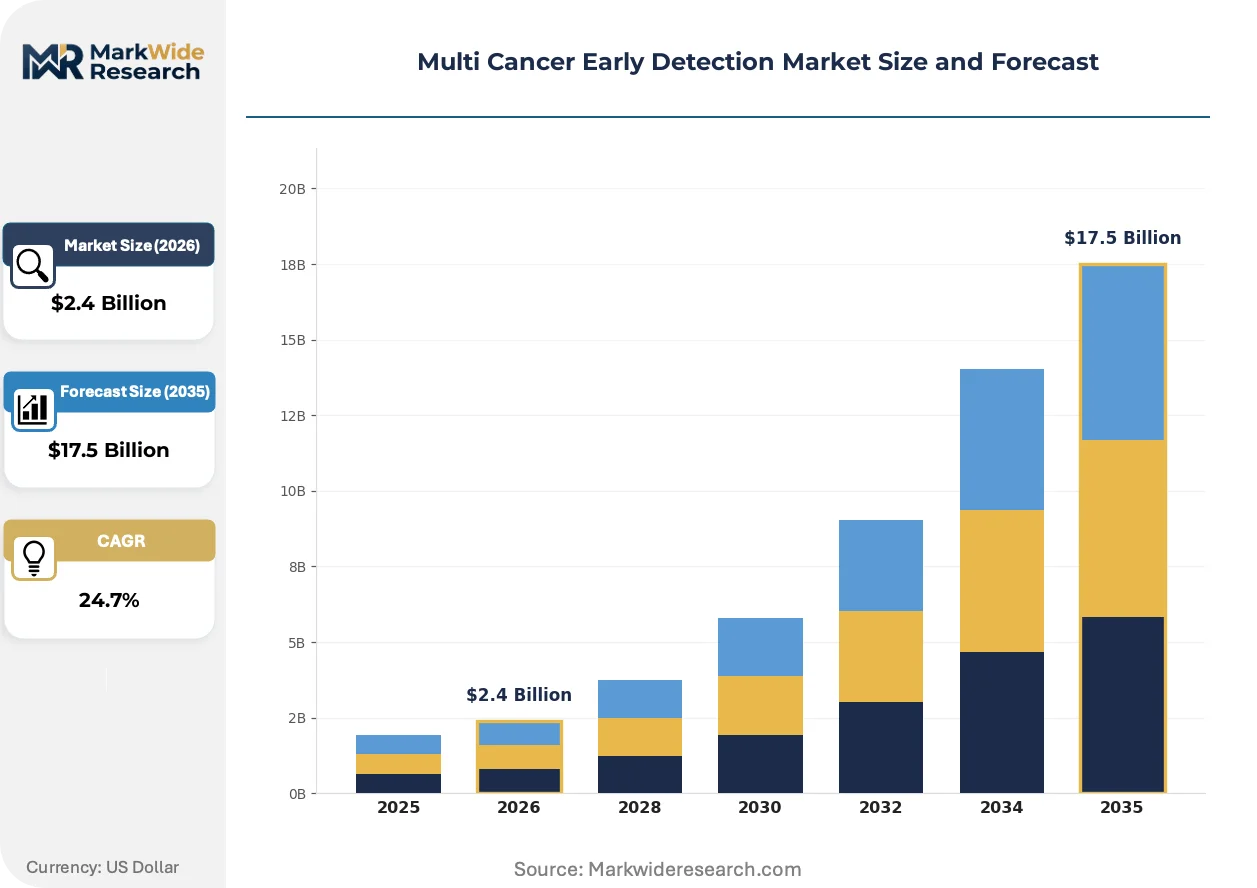
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $17.5 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Tests, Imaging Tests, Biopsy Tests, Urine Tests End User: Hospitals, Diagnostic Laboratories, Research Institutes, Oncology Clinics Technology: Next-Generation Sequencing, Liquid Biopsy, PCR, Proteomics Application: Screening, Diagnosis, Prognosis, Monitoring |
| Companies Covered | Exact Sciences Corporation, GRAIL, Guardant Health, Freenome Holdings, Illumina, Burning Rock Biotech, FOUNDATION MEDICINE, AnchorDx, Elypta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Cancer Early Detection Market Strategic Shifts & Innovations
Three distinct vectors are reshaping competitive positioning in multi-cancer detection: instrument footprint reduction, regulatory evidence standard evolution, and procurement model transformation toward risk-based contracting.
Microfluidic sample preparation systems are miniaturizing pre-analytical workflows for circulating biomarker extraction. Community oncology practices and employer health clinics are adopting these integrated platforms to reduce send-out laboratory dependencies. The technology is compressing capital requirements for point-of-care screening deployment, enabling decentralized testing networks outside major academic medical centers.
REACH and RoHS substance restrictions in the European Union are forcing reengineering of sequencing reagent chemistries and plastic consumable compositions. Manufacturers are reformulating buffer solutions and transitioning to recyclable collection tube materials to maintain CE marking eligibility. The MDR classification of software-as-medical-device components is additionally requiring algorithm version control documentation that affects cloud-based analysis platforms.
Oncology clinics are consolidating purchasing decisions through group purchasing organizations that negotiate multi-year screening program contracts. Hospital systems are unbundling test pricing from interpretation services, creating transparent fee schedules that shift margin pressure to laboratory operators. This restructuring is most advanced in the United States, where Medicare Advantage plans are piloting episode-based reimbursement for positive screen follow-up care.
Multi Cancer Early Detection Market Segmentation
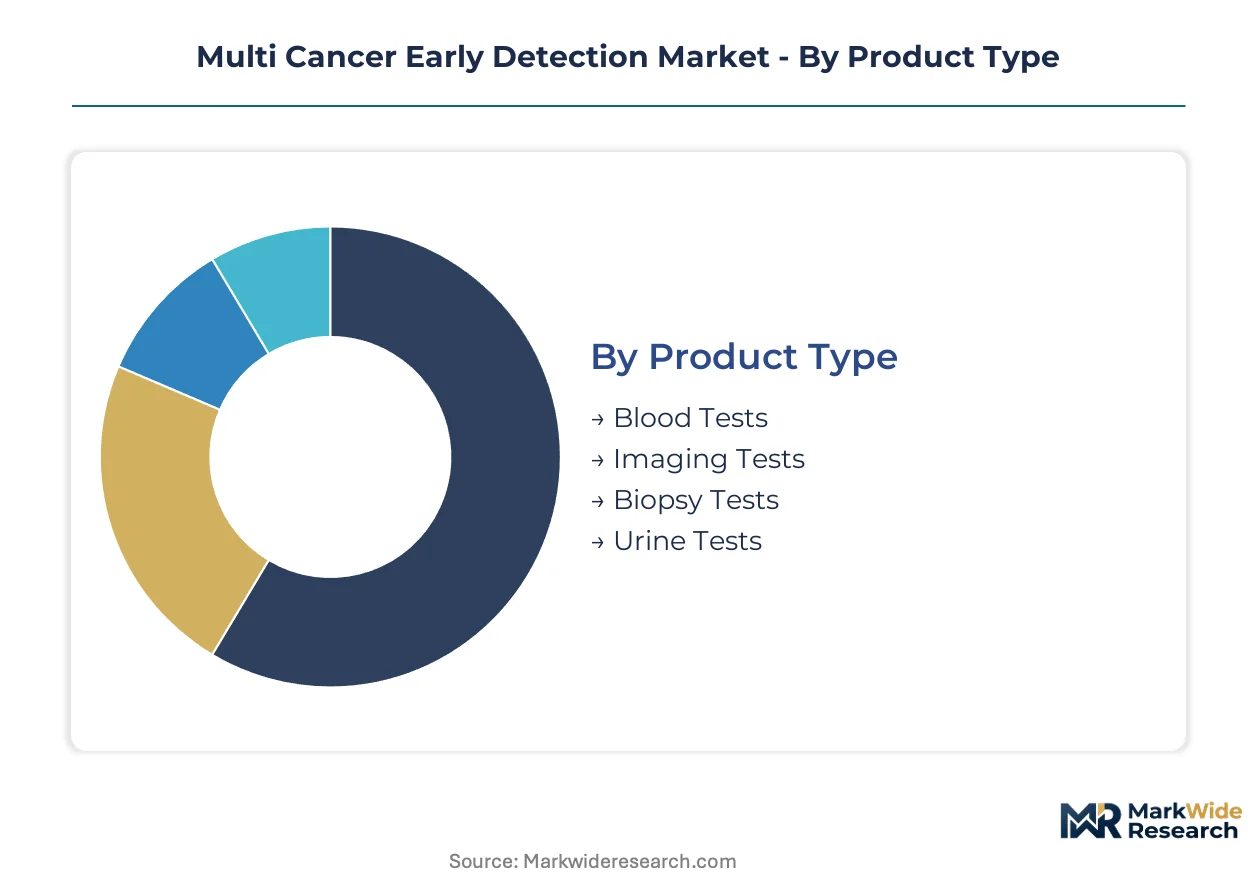
Segmentation in multi-cancer early detection reveals how regulatory pathways, clinical workflows, and technology economics allocate value across the $17.5 billion market. Each dimension exposes distinct barriers to entry and margin structures that shape competitive positioning.
Product Type:
FDA breakthrough device designation and CMS national coverage determination processes create divergent commercialization timelines across specimen categories, with blood-based platforms securing accelerated market access.
- Blood Tests:These platforms interrogate 10-20 mL peripheral blood specimens for circulating cell-free DNA, methylation patterns, and protein signatures. Diagnostic laboratories in the United States concentrate procurement here, driven by scalable collection infrastructure and minimal patient invasiveness that supports population-scale screening programs.
- Imaging Tests:Computed tomography, magnetic resonance imaging, and positron emission tomography provide anatomical localization following positive molecular screens. Hospital systems retain larger volume contracts for diagnostic confirmation, though reimbursement compression under Medicare fee schedules constrains margin expansion.
- Biopsy Tests:Tissue acquisition and histopathological analysis deliver definitive cancer classification through immunohistochemistry and molecular profiling.
- Urine Tests:Non-invasive specimen collection enables detection of urological and select solid tumor biomarkers with lower analytical sensitivity than blood-based alternatives.
Blood tests handle the majority of throughput; urine tests are the fastest mover on share as proteomic detection sensitivity improves.
End User:
Procurement authority is consolidating through group purchasing organizations that negotiate multi-year screening program contracts, reshaping vendor-customer economics.
- Hospitals:Academic medical centers and integrated delivery networks anchor diagnostic confirmation workflows with high-complexity molecular pathology laboratories. Medicare reimbursement deliberations directly shape capital allocation for sequencing infrastructure.
- Diagnostic Laboratories:Reference laboratories including Quest Diagnostics and LabCorp scale high-throughput next-generation sequencing to process population health volumes. Self-insured employers increasingly contract directly for blood-based screening panels.
- Research Institutes:National Cancer Institute-designated cancer centers and academic consortia conduct pivotal clinical validation studies for asymptomatic screening claims.
- Oncology Clinics:Community oncology practices are redrawing procurement priorities toward decentralized blood-based screening to reduce send-out dependencies.
Diagnostic laboratories command the dominant procurement volume; oncology clinics are expanding most quickly as microfluidic platforms enable point-of-care deployment.
Technology:
Sequencing reagent concentration among Illumina and Thermo Fisher creates input cost volatility that compresses margins for test developers across platform categories.
- Next-Generation Sequencing:Massively parallel sequencing of cfDNA methylation libraries achieves analytical specificity above 99% through multiplexed detection. This platform absorbs the majority of instrument placement investments due to throughput requirements.
- Liquid Biopsy:Circulating tumor DNA and exosomal RNA analysis enables real-time monitoring of treatment response and minimal residual disease detection. R&D allocation is accelerating as proteomic and methylation panel combinations broaden detectable cancer signal breadth.
- PCR:Digital and quantitative polymerase chain reaction provides rapid, cost-effective detection of known oncogenic mutations with limited multiplexing capacity.
- Proteomics:Affinity-based capture of circulating protein signatures offers complementary detection mechanisms to nucleic acid analysis.
Next-generation sequencing carries the steepest expansion trajectory; liquid biopsy is gaining share fastest through dual use in treatment selection and early detection.
Application:
Evidence generation requirements vary sharply by use case, with asymptomatic screening claims demanding mortality benefit demonstration that extends pivotal trial timelines.
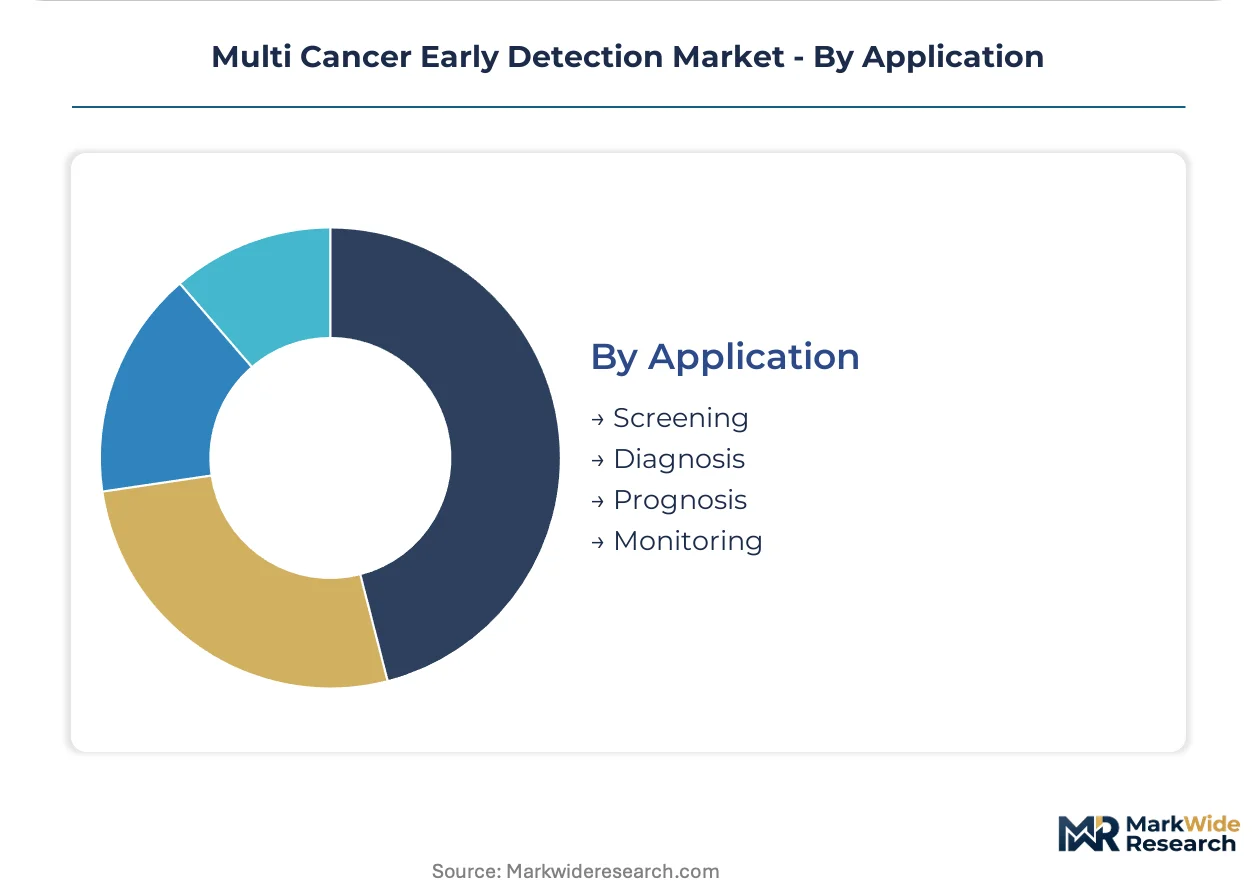
- Screening:Asymptomatic population-scale detection through blood-based panels targets stage shift toward earlier, curable disease. FDA requires mortality benefit data for approval, creating the highest evidentiary barrier.
- Diagnosis:Symptomatic patient evaluation and tissue-of-origin prediction following incidental findings or abnormal imaging. Private payer coverage is more established here than for screening indications.
- Prognosis:Risk stratification and recurrence prediction based on molecular residual disease quantification.
- Monitoring:Serial liquid biopsy testing to assess treatment response and detect emerging resistance mechanisms.
Screening applications concentrate the largest addressable population; monitoring is climbing the fastest as longitudinal reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based diagnostic developers export blood-based screening platforms to Germany, Japan, and the United Kingdom, establishing transatlantic and transpacific trade corridors for cfDNA methylation technology.
United States
Medicare reimbursement deliberations and self-insured employer demand drive procurement volume for blood-based panels. FDA breakthrough device designation accelerates commercialization timelines for asymptomatic screening claims. The Boston-Cambridge biotech corridor anchors GRAIL and Guardant Health operations, scaling high-throughput sequencing infrastructure for population health deployment.
Germany
Reference laboratories in Bavaria and North Rhine-Westphalia process molecular diagnostic specimens for Central European distribution. EMA's in vitro diagnostic regulation and BfArM health technology assessment frameworks govern CE marking eligibility and reimbursement pathways. The Munich-Heidelberg medical technology cluster concentrates cfDNA platform validation studies under new IVDR notified body requirements.
United Kingdom
NHS England's accelerated access collaborative evaluates multi-cancer tests for national screening program integration. MHRA post-Brexit regulatory autonomy enables streamlined approval pathways while maintaining alignment with EMA evidentiary standards. The Cambridge-London life sciences corridor hosts GRAIL's European headquarters and clinical trial operations for methylation-based detection.
Japan
PMDA's sakigake designation system prioritizes review of novel oncology diagnostics, compressing approval timelines for liquid biopsy platforms. METI's healthcare technology export initiative promotes domestic diagnostic manufacturers across Asia-Pacific markets. The Tokyo-Osaka biopharmaceutical corridor concentrates Burning Rock Biotech's regional partnerships and clinical validation networks.
China
NMPA's innovative medical device approval pathway enables accelerated market entry for methylation-based screening tests. National cancer screening program expansion in urban centers drives demand for non-invasive detection platforms. The Shanghai-Suzhou diagnostic manufacturing hub anchors Burning Rock Biotech and AnchorDx production capacity for domestic and export markets.
Multi Cancer Early Detection Market Key Industry Players
Player mix skews toward integrated diagnostic platform developers with captive sequencing infrastructure and specialized liquid biopsy laboratories with outsourced analytics partnerships. Market structure concentrates around three strategic archetypes: vertically integrated test developers controlling sample-to-answer workflows, reference laboratory networks scaling high-throughput processing, and sequencing instrument incumbents supplying reagent ecosystems. Dominant competitive moves include strategic partnerships between test developers and diagnostic laboratory networks, plus portfolio diversification from single-cancer into multi-cancer detection menus.
Within the integrated platform tier, Exact Sciences Corporation and GRAIL occupy positions spanning colorectal screening expansion and asymptomatic multi-cancer detection respectively. Guardant Health exemplifies the dual-use archetype, anchoring liquid biopsy applications across treatment selection and early detection use cases. These three developers represent contrasting commercialization strategies: laboratory-developed test models, pharmaceutical partnership structures, and direct-to-payer contracting approaches.
| Leading Market Players |
|---|
| Exact Sciences Corporation |
| GRAIL |
| Guardant Health |
| Freenome Holdings |
| Illumina |
| Burning Rock Biotech |
| FOUNDATION MEDICINE |
| AnchorDx |
| Elypta |
| Others |
Cost & Logistics Intelligence
FDA breakthrough device designation and CLIA high-complexity laboratory certification simultaneously gate supply qualification and create three-tier pricing stratification across premium, standard, and economy service levels in multi-cancer early detection. Medicare national coverage determination timelines concentrate purchasing power among integrated delivery networks that negotiate multi-year screening program contracts, compressing margins for standalone test developers while rewarding vertically integrated platform operators.
Pricing Analysis
Next-generation sequencing platforms command premium pricing against PCR-based alternatives and emerging proteomic assays, with machine learning algorithm sophistication and methylation panel breadth driving tier differentiation. Price differentiation centers on analytical specificity thresholds and FDA approval status versus laboratory-developed test classification, with self-insured employers showing lowest price sensitivity due to wellness program positioning. Cost compression in standard-tier liquid biopsy services is intensifying as reference laboratories scale high-throughput processing infrastructure, while economy-tier research-use-only panels face price erosion from Asian diagnostic manufacturers.
Supply Chain Analysis
Sequencing reagent inventories at diagnostic laboratories typically maintain 60-90 day coverage given Illumina and Thermo Fisher's concentrated manufacturing in the United States, Singapore, and the Netherlands. Supply chains draw from specialized fluorophore chemistries, semiconductor-grade flow cells, and synthetic oligonucleotide libraries, with single-source vulnerability concentrated in next-generation sequencing instrument platforms. Distribution runs through cold-chain logistics networks anchored by Quest Diagnostics and LabCorp processing facilities, with regulatory restriction risk from REACH substance limitations affecting European reagent importation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-cancer early detection is emerging from a capital-intensive evidence-generation trough, with Medicare reimbursement deliberations and employer wellness program adoption forming the cyclical recovery mechanism that will revalue platform developers over the next expansion phase.
For Market Incumbents: Compound defensive positioning through captive sequencing infrastructure and exclusive GPO contracts that lock out emerging proteomic assay competitors. Prioritize backward integration into methylation database assets and machine learning training pipelines to preserve margin structure against reference laboratory price competition. Anchor capacity expansion in the Boston-Cambridge corridor to capture Medicare Advantage pilot program volume. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track enables accelerated market entry for microfluidic sample preparation platforms targeting community oncology clinic decentralization. White-space concentration sits in employer-sponsored wellness bypassing traditional payer authorization, with European IVDR transition creating parallel first-mover opportunity in Germany and the United Kingdom. Pursue direct-to-employer contracting alongside diagnostic laboratory partnerships to circumvent established GPO gatekeepers. For Investors and Strategic Acquirers: CMS national coverage determination reshapes the acquisition landscape by separating reimbursement-viable platform developers from laboratory-developed test operators facing margin compression. Long-term viability favors vertically integrated test developers with captive cfDNA methylation databases and cloud-based analysis infrastructure. Monitor FDA pivotal trial readouts as the primary inflection signal for platform revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses commercialization timelines for methylation-based screening panels. |
| CMS National Coverage Determination | Medicare reimbursement triggers private payer follow-on coverage expansion. |
| Diagnostic Laboratory Partnership | Quest Diagnostics and LabCorp provide population-scale specimen processing infrastructure. |
| Proteomic Panel Convergence | Protein signature integration broadens detectable cancer type coverage without proportional cost increase. |
| Employer Wellness Program Contracting | Self-insured employers pilot blood-based screening as differentiated health benefit offerings. |
Research Approach
Initial hypotheses were tested against primary input from diagnostic laboratory directors, oncology clinic procurement officers, regulatory affairs specialists at platform developers, and Medicare reimbursement consultants, then refined through secondary validation against FDA 510(k) and breakthrough device designation filings, CMS national coverage determination records, ClinicalTrials.gov registry entries, and hospital GPO contract databases. Bottom-up volume estimates from laboratory instrument placement data were triangulated against top-down market sizing from payer coverage expansion models.
Variance decomposition across the projection horizon isolates contribution from screening application penetration, liquid biopsy technology share shifts, and regional reimbursement policy evolution. Segmentation dimensions modeled include specimen type, end-user procurement authority, sequencing platform generation, and clinical use case across asymptomatic screening and diagnostic confirmation workflows. CAGRs were derived from instrument placement trajectories and reagent consumption curves, with cfDNA methylation assay adoption rates and microfluidic platform deployment timelines serving as key forecast inputs.
Underlying assumptions cover Medicare Advantage pilot program expansion, FDA evidentiary standards for asymptomatic screening claims, and Illumina-Thermo Fisher reagent pricing stability, with deviation risk concentrated in mortality benefit demonstration timelines and EMA IVDR notified body capacity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market