
 Global Ebola Virus Vaccine Market | 2026-2036
Global Ebola Virus Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ebola Virus Vaccine Market Foresight
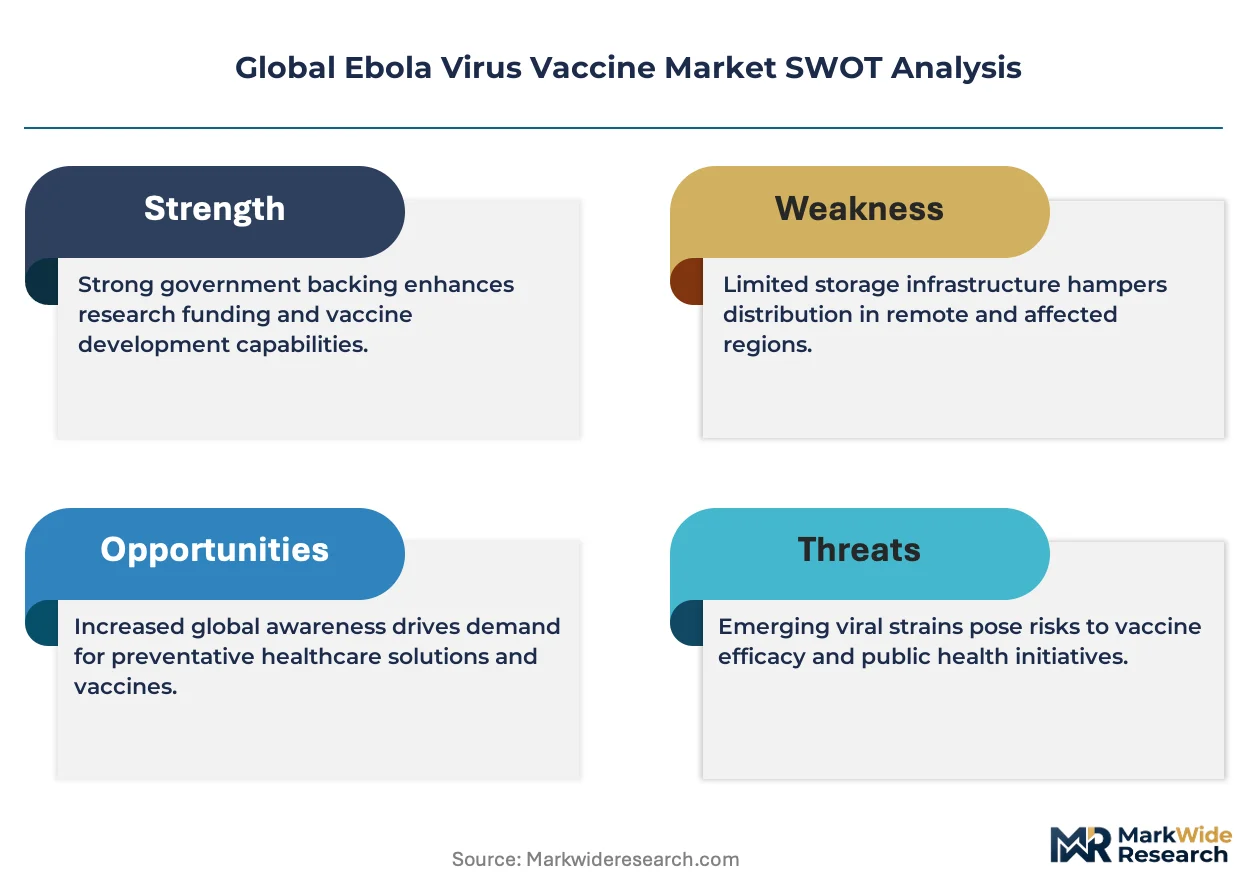
The WHO Emergency Use Listing procedure is restructuring how Ebola vaccine developers secure procurement contracts from Gavi and government stockpilers. Merck & Co., Inc. dominates the rVSV-ZEBOV franchise through manufacturing scale and established cold-chain partnerships in outbreak zones. Johnson & Johnson leverages its two-dose Ad26.ZEBOV/MVA-BN-Filo regimen to differentiate in preventive immunization settings where durable protection matters. Emergent BioSolutions Inc. anchors its position through upstream control over viral vector manufacturing infrastructure.
Ebola virus vaccines are sterile biological preparations containing attenuated or vectored Zaire ebolavirus glycoprotein antigens, formulated for intramuscular administration at 2–8°C or cryogenic storage depending on platform stability. Their primary purpose is to elicit neutralizing antibodies that prevent viral entry into host cells, thereby interrupting human-to-human transmission chains during outbreaks or protecting high-risk personnel in endemic regions. Viral vector platforms occupy the largest value share owing to proven immunogenicity and regulatory familiarity, while DNA-based candidates represent the fastest-growing category as thermostable formulations reduce last-mile distribution costs in tropical climates. The target population segmentation shows healthcare workers and emergency responders commanding premium pricing due to immediate deployment requirements, whereas biodefense programs generate stable recurring revenue through national stockpile replenishment cycles.
FDA, EMA, and WHO prequalification standards collectively determine which Ebola vaccines gain access to procurement pools managed by UNICEF and the Strategic Advisory Group of Experts on Immunization. These frameworks mandate cGMP compliance, Phase III efficacy data in outbreak settings, and post-marketing pharmacovigilance systems that shape development timelines and capital allocation decisions. Stakeholders must monitor how the EU MDR and forthcoming African Medicines Regulatory Harmonization guidelines alter clinical trial site requirements and approval reciprocity across endemic countries.
Market Dynamics
Stockpiling mandates from national biodefense agencies are compressing procurement cycles and concentrating demand among manufacturers with established WHO Emergency Use Listing credentials, reshaping competitive access to outbreak-response contracts.
Growth Catalysts
- Emergency Use Listing pathway:WHO prequalification accelerates access to Gavi procurement pools and government stockpile tenders, reducing time-to-revenue for compliant developers.
- Healthcare worker immunization mandates:Frontline personnel in endemic regions require immediate deployment-ready vaccines, sustaining premium pricing for rapid-response formulations.
- Cold-chain infrastructure expansion:Last-mile distribution networks in tropical climates enable broader access to temperature-sensitive viral vector platforms previously limited to urban centers.
Market Restraints
- Ultra-low temperature requirements:Cryogenic storage infrastructure limits distribution to regions with reliable liquid nitrogen supply chains, excluding remote outbreak zones.
- Single-pathogen focus:Zaire ebolavirus-specific formulations offer no cross-protection against Sudan ebolavirus or Marburg virus, forcing parallel development investments.
- EMA batch release protocols:European manufacturing compliance adds 6-12 weeks to delivery timelines, constraining rapid-response procurement flexibility.
Strategic Opportunities
- Pan-filovirus platform development:Multivalent candidates targeting Zaire, Sudan, and Marburg strains would consolidate stockpiling budgets and simplify national preparedness planning.
- African Medicines Regulatory Harmonization:Streamlined approval reciprocity across endemic countries reduces redundant clinical trials and accelerates market entry for regional manufacturers.
- Thermostable DNA platform adoption:Ambient-temperature stability eliminates cold-chain dependency, opening last-mile access in Guinea, Sierra Leone, and rural DRC provinces.
Industry Challenges
- Pharmacovigilance infrastructure gaps:Post-marketing safety surveillance systems remain underdeveloped in outbreak-prone regions, complicating regulatory maintenance and WHO prequalification renewal.
- Fill-finish capacity bottlenecks:Viral vector manufacturing requires specialized aseptic facilities with limited global availability, constraining surge production during multi-country outbreaks.
- Clinical trial site activation:Ethical review board delays in endemic countries extend Phase III initiation timelines, compressing development windows between outbreak cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ebola Virus Vaccine Market |
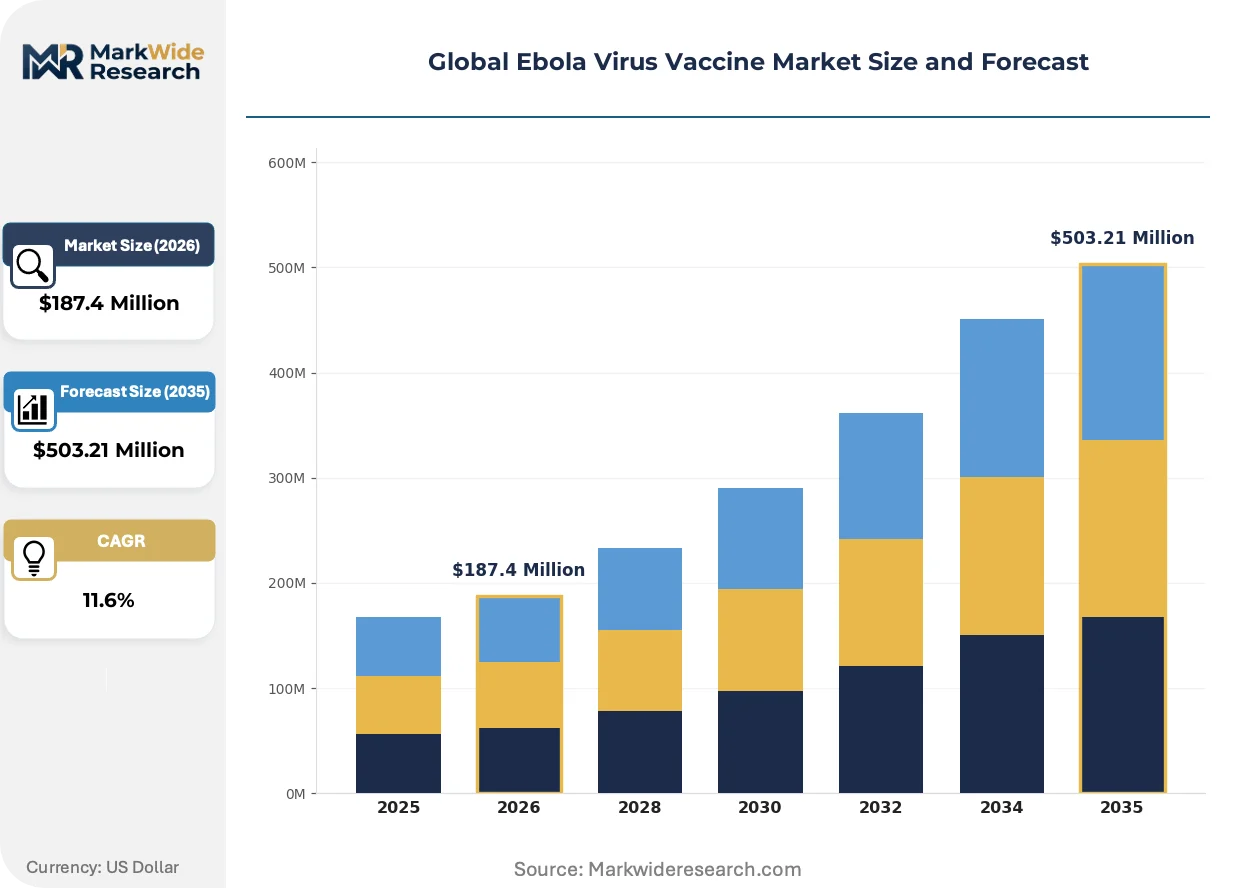
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Viral Vector, Subunit, DNA-based, Recombinant, Protein-based Target Population: Healthcare Workers, Travelers, Laboratory Personnel, Researchers, Military Personnel, Emergency Responders Application Setting: Outbreak Control, Preventive Immunization, Post-exposure Prophylaxis, Clinical Trials, Research Studies, Biodefense Programs Distribution Channel: Government Health Agencies, Non-Governmental Organizations, Private Clinics, International Health Organizations, Vaccination Centers, Mobile Clinics |
| Companies Covered | Merck & Co., Inc, Johnson & Johnson, GlaxoSmithKline plc, Bavarian Nordic, Emergent BioSolutions Inc., Novavax Inc., Inovio Pharmaceuticals, Inc., GeoVax Labs, Inc., Mapp Biopharmaceutical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ebola Virus Vaccine Market Shifts & Advancements
Platform diversification and regulatory pathway convergence are compressing development timelines while expanding addressable populations beyond traditional outbreak-response scenarios.
Lyophilized viral vector formulations are rewriting cold-chain economics for tropical distribution. National immunization programs in West Africa are adopting these thermostable alternatives to reduce last-mile logistics costs. The shift is compressing the total cost of ownership gap between premium viral vectors and lower-efficacy alternatives, forcing platform competitors to accelerate stability investments.
EU MDR Annex I clinical evaluation requirements are tightening post-market surveillance obligations for biological medicinal products. Manufacturers must now maintain active safety databases with direct healthcare provider reporting channels. The regulation most impacts developers seeking CE marking for preventive immunization indications, driving investment in automated adverse event collection systems.
Biodefense stockpile managers are consolidating procurement under multi-year framework agreements with performance-based replenishment clauses. Government buyers in the United States and European Union are replacing single-source contracts with dual-qualified supplier arrangements to mitigate manufacturing risk. This behavioral shift is most visible in NATO-aligned countries, where pandemic preparedness budgets now mandate supply redundancy for strategic medical countermeasures.
Global Ebola Virus Vaccine Market Segmentation
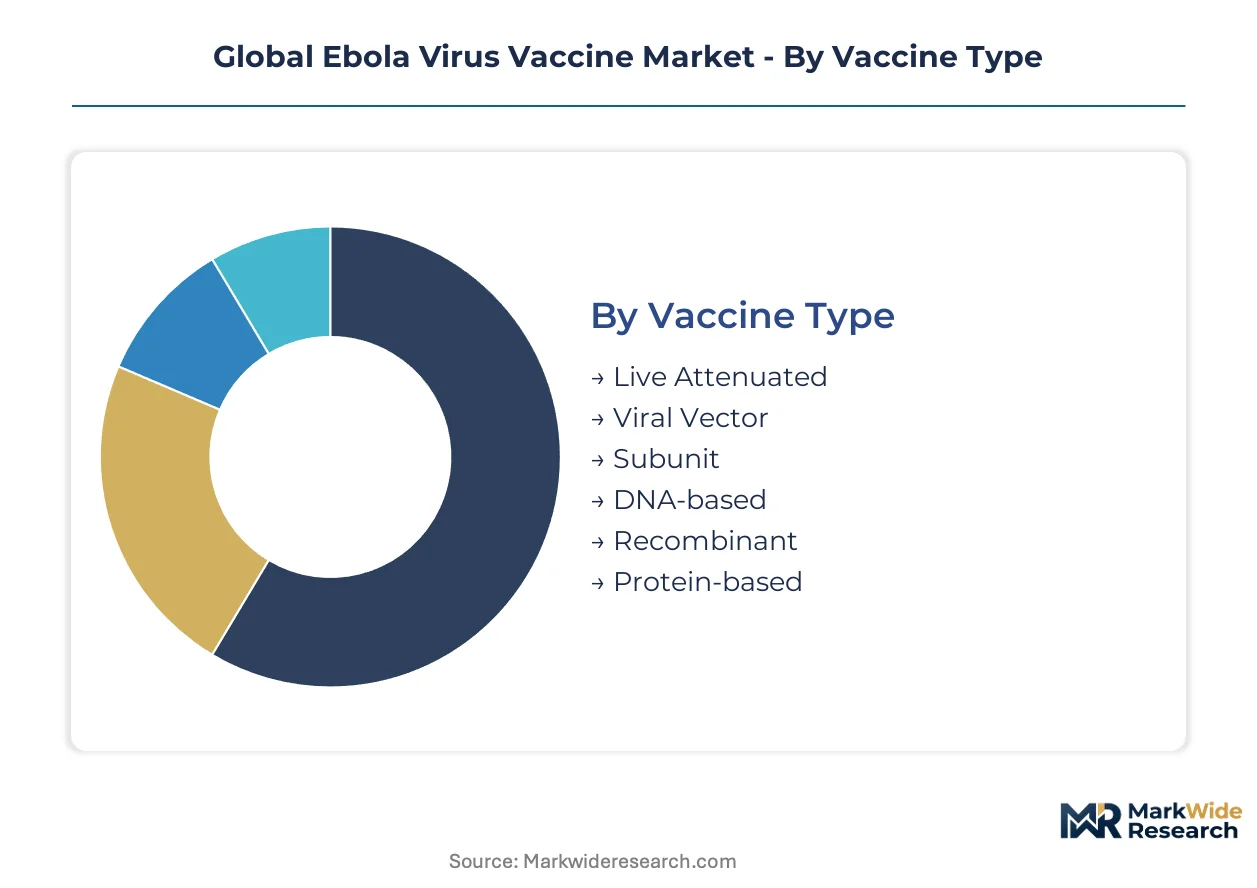
Ebola vaccine procurement concentrates around platform-specific cold-chain capabilities and population risk profiles. Manufacturers align formulation investments with the divergent stability requirements of outbreak response versus preventive immunization.
Vaccine Type:
Manufacturing scale and fill-finish capacity concentrate among viral vector platforms with established WHO Emergency Use Listing credentials.
- Viral Vector:Recombinant adenovirus and vesicular stomatitis virus backbones deliver Zaire ebolavirus glycoprotein antigens with proven Phase III efficacy. Demand clusters in the Democratic Republic of Congo and Guinea where outbreak-response procurement prioritizes rapid deployment over storage flexibility.
- DNA-based:Plasmid-encoded antigen expression enables ambient-temperature stability, eliminating liquid nitrogen dependency. Distribution expansion into rural Sierra Leone and remote Liberian provinces accelerates as last-mile cold-chain infrastructure remains unreliable.
- Live Attenuated:Replication-competent vaccines require stringent containment manufacturing.
- Subunit:Purified protein formulations offer established regulatory pathways.
- Recombinant:Bacterial and yeast expression systems enable cost-efficient bulk production.
- Protein-based:Nanoparticle-displayed antigens target improved thermostability profiles.
Today's leader: Viral Vector. Tomorrow's challenger: DNA-based.
Target Population:
Pricing power stratifies across deployment urgency and occupational exposure risk.
- Healthcare Workers:Frontline personnel in Ebola Treatment Units require immediate post-exposure protection. Guinea's Ministry of Health and the DRC's INRB mandate pre-deployment immunization, sustaining premium pricing for single-dose regimens.
- Emergency Responders:WHO GOARN deployers and Médecins Sans Frontières field teams need rapid-response formulations with minimal cold-chain burden. Stockpiling contracts from the United States Strategic National Stockpile and the European Union's rescEU mechanism generate recurring revenue.
- Travelers:Business and humanitarian visitors to endemic regions seek preventive options.
- Laboratory Personnel:BSL-4 facility workers handling live virus samples require specialized protocols.
- Researchers:Academic and pharmaceutical investigators drive clinical trial demand.
- Military Personnel:Peacekeeping and biodefense units in outbreak zones need mission-ready protection.
Premium pricing concentrates in Healthcare Workers. Volume expansion sits with Emergency Responders.
Application Setting:
Procurement cycle length and regulatory pathway complexity vary sharply across deployment scenarios.
- Outbreak Control:Ring vaccination campaigns demand surge manufacturing capacity and WHO Emergency Use Listing compliance. The DRC's Ministry of Health and Guinea's National Coordination for the Fight against Ebola activate contingency procurement within 72 hours of case confirmation.
- Biodefense Programs:National stockpiling in the United States, the United Kingdom, and France operates on multi-year framework agreements with performance-based replenishment clauses. BARDA and the UK Health Security Agency mandate dual-qualified suppliers.
- Preventive Immunization:Routine immunization programs in endemic regions require stable supply.
- Post-exposure Prophylaxis:Immediate administration following needlestick or exposure events.
- Clinical Trials:Phase I-III studies in endemic and non-endemic settings.
- Research Studies:Immunology and correlates-of-protection investigations.
Revenue stability resides in Biodefense Programs. Growth velocity belongs to Outbreak Control.
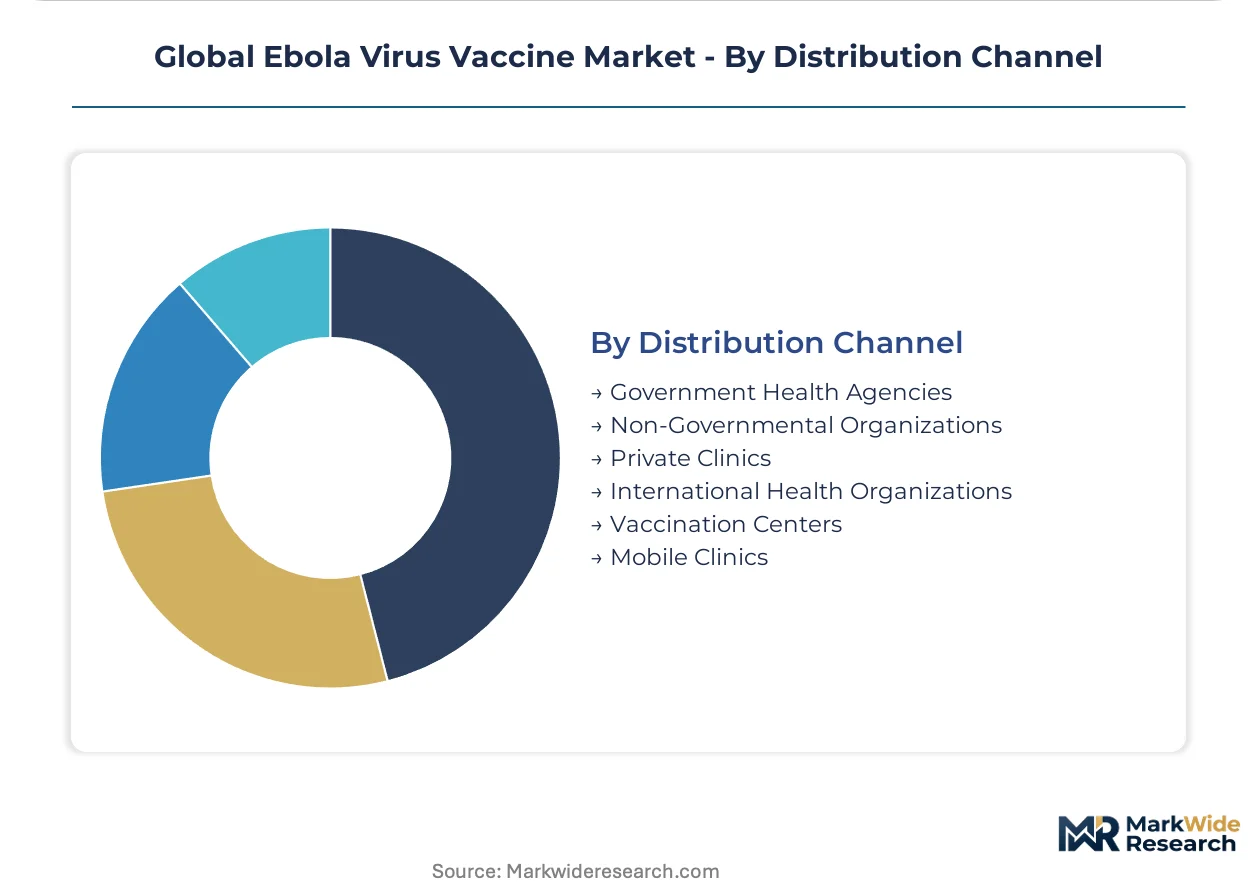
Distribution Channel:
Cold-chain infrastructure ownership determines channel economics and geographic reach.
- Government Health Agencies:National Ministries of Health in the United States, the DRC, and Guinea direct centralized procurement through emergency preparedness budgets. FDA and WHO prequalification standards gate access to these tenders.
- International Health Organizations:Gavi, UNICEF, and the WHO manage pooled procurement for outbreak response. The WHO Emergency Use Listing pathway accelerates access to these procurement pools for compliant manufacturers.
- Non-Governmental Organizations:Médecins Sans Frontières and International Medical Corps operate field procurement.
- Private Clinics:Travel medicine and occupational health providers serve corporate clients.
- Vaccination Centers:Fixed-site immunization in urban outbreak zones.
- Mobile Clinics:Deployable units for remote area access.
Procurement volume concentrates in Government Health Agencies. Channel expansion flows through International Health Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized virology researchers and biodefense procurement officers cluster in government laboratories across the United States, the Democratic Republic of Congo, Guinea, the United Kingdom, and Germany. These talent concentrations anchor national stockpiling programs and outbreak-response infrastructure.
United States
BARDA and the Strategic National Stockpile drive multi-year framework agreements for Ebola vaccine procurement. FDA Emergency Use Authorization pathways accelerate deployment readiness for federal responders. Research Triangle Park in North Carolina hosts viral vector manufacturing facilities serving biodefense contracts.
Democratic of Congo
The Institut National de Recherche Biomédicale coordinates ring vaccination campaigns during active outbreaks. Ministry of Health emergency protocols activate procurement within 72 hours of case confirmation. Kinshasa-based cold-chain hubs distribute vaccines to eastern provinces where outbreak zones concentrate.
Guinea
Healthcare worker immunization mandates from the Ministry of Health sustain demand for rapid-deployment formulations. National Coordination for the Fight against Ebola manages contingency procurement through WHO Emergency Use Listing pathways. Conakry serves as the regional distribution anchor for West African outbreak response.
United Kingdom
The UK Health Security Agency mandates dual-qualified suppliers for national stockpile replenishment. MHRA batch release protocols govern European manufacturing compliance for exported doses. Porton Down biodefense laboratories anchor research collaboration with commercial manufacturers.
Germany
Paul-Ehrlich-Institut regulates viral vector manufacturing for European distribution networks. Federal Ministry of Health stockpiling budgets prioritize WHO-prequalified candidates. Marburg and Hamburg host specialized aseptic fill-finish facilities with surge capacity for outbreak response.
Global Ebola Virus Vaccine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Ebola vaccine landscape. Viral vector manufacturers with captive fill-finish infrastructure dominate outbreak-response procurement, while platform-technology developers pursue thermostable alternatives. Three archetypes define competitive positioning: established pharmaceutical conglomerates with biodefense contracts, mid-cap biotech specialists with viral vector expertise, and emerging platform developers targeting ambient-temperature stability. Capacity expansion and strategic partnerships with national stockpile managers constitute the dominant competitive moves reshaping procurement access.
Within the established pharmaceutical tier, Merck & Co., Inc. and Johnson & Johnson occupy positions defined by manufacturing scale and regulatory credentialing. Emergent BioSolutions Inc. exemplifies the infrastructure-specialist archetype through upstream control over viral vector production capabilities. These three anchors demonstrate how WHO Emergency Use Listing credentials and cold-chain partnerships determine competitive access to Gavi procurement pools and government stockpile tenders.
| Leading Market Players |
|---|
| Merck & Co., Inc |
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Bavarian Nordic |
| Emergent BioSolutions Inc. |
| Novavax Inc. |
| Inovio Pharmaceuticals, Inc. |
| GeoVax Labs, Inc. |
| Mapp Biopharmaceutical, Inc. |
| Others |
Supply & Pricing Matrix
Specialized aseptic manufacturing technicians in Germany and North Carolina command wage premiums that compress margins on standard-grade viral vector doses while widening spreads for premium formulations with enhanced stability profiles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with WHO Emergency Use Listing certification and fill-finish scale serving as the primary price differentiation drivers. Cost compression in standard viral vector tiers is intensifying because EMA batch release protocols extend delivery timelines and erode competitive positioning. Government stockpile managers in the United States and United Kingdom exhibit lowest price sensitivity due to biodefense mandate urgency, while rural Ministries of Health in West Africa face acute budget constraints.
Supply Chain Analysis
Workforce availability for viral vector manufacturing clusters in the United States, Germany, and Belgium, where specialized aseptic technicians remain scarce relative to biologics demand growth. Production draws from plasmid DNA sources, mammalian cell culture substrates, and single-use bioreactor components. Single-source vulnerability in fill-finish capacity constrains surge response during multi-country outbreak activation. Distribution runs through government health agencies and international health organizations with established cold-chain partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on thermostable platform adoption reducing last-mile logistics costs and enabling premium pricing for ambient-temperature formulations in tropical distribution.
For Market Incumbents: Cement WHO prequalification renewal timelines through automated pharmacovigilance database investments, countering emerging DNA-platform competitors with regulatory speed. Add captive fill-finish capacity in Kinshasa or Conakry to compress outbreak-response delivery windows and defend against regional manufacturing aspirants. For New Entrants and Emerging Players: Begin with ambient-temperature stability claims in Sierra Leone and rural Liberian provinces where cold-chain infrastructure gaps exclude incumbent viral vectors. Pursue African Medicines Regulatory Harmonization pathway acceleration as the primary go-to-market angle, leveraging streamlined approval reciprocity to bypass redundant clinical trials. For Investors and Strategic Acquirers: Valuations sit cheapest among platform-technology developers with thermostable candidates pending Phase II completion, offering acquisition entry points before WHO Emergency Use Listing credentialing. Long-term viability over the next decade hinges on pan-filovirus multivalent pipeline positioning. Watch for Sudan ebolavirus outbreak declaration as inflection signal triggering stockpile procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Emergency Use Listing Pathway Acceleration | Prequalification unlocks Gavi procurement pools and government tender access for compliant developers. |
| Lyophilized Viral Vector Formulation Development | Thermostability investments compress total cost of ownership gaps against DNA-platform competitors in tropical climates. |
| Pan-Filovirus Platform Diversification | Multivalent candidates targeting Zaire, Sudan, and Marburg strains consolidate fragmented stockpiling budgets under single procurement. |
| African Fill-Finish Capacity Expansion | Regional manufacturing footprint reduces EMA batch release dependency and accelerates outbreak-response deployment timelines. |
| Automated Pharmacovigilance Infrastructure Deployment | Active safety databases satisfy EU MDR Annex I surveillance obligations for biological medicinal products. |
Research Methodology
Bottom-up biodefense procurement modeling reconciled against top-down viral vector manufacturing capacity tracking forms the analytical core of this study. Primary interviews with vaccine development executives, regulatory affairs leads at national health agencies, formulary directors at Gavi, and hospital procurement managers in endemic regions combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases. Cross-referencing manufacturer production disclosures against government stockpile tender announcements enabled demand-supply reconciliation.
Input-output matrices mapped platform-specific cold-chain requirements to geographic distribution feasibility across endemic and non-endemic markets. Segmentation dimensions modeled include vaccine platform type, target population risk tier, application setting urgency, and regional regulatory cluster alignment. CAGRs were derived from procurement cycle analysis and stockpile replenishment pattern projection across the analysis window. Forecast inputs incorporated WHO Emergency Use Listing approval velocity and African Medicines Regulatory Harmonization implementation progress.
Several conditions sit outside the modeled scope, including unanticipated filovirus strain emergence, abrupt WHO prequalification standard revision, and geopolitical disruption of cold-chain infrastructure in outbreak zones. Forecasts reflect documented assumptions regarding regulatory pathway stability and manufacturer capacity expansion execution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mail Order Pharmacy Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Tissue Plasminogen Activator Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Anthelmintic Drugs Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market