
 X-Ray Positioning Devices Market | 2026-2036
X-Ray Positioning Devices Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Positioning Devices Market Outlook
ISO 13485 certification is reorganizing competitive access in the X-Ray Positioning Devices Market, filtering out contract manufacturers that lack quality management systems for medical devices. GE Healthcare leverages in-house production of radiographic tables to control supply timelines for hospital networks. Siemens Healthineers anchors its positioning portfolio through deep integration with angiography suites. Koninklijke Philips competes by bundling positioning systems with digital radiography detectors.
X-ray positioning devices are mechanical or electromechanical apparatuses engineered to immobilize, align, and orient patients during diagnostic imaging, typically constructed from carbon-fiber composites or aluminum alloys to minimize radiation attenuation while supporting patient loads exceeding 200 kg. Their primary purpose is to ensure reproducible anatomical alignment for radiographic, fluoroscopic, or tomographic acquisition. Fixed installations dominate hospital radiology departments where throughput requirements justify permanent infrastructure, while portable units capture the fastest expansion as point-of-care imaging migrates to emergency departments and intensive care settings. Foam and composite materials command premium positioning in pediatric and bariatric applications where pressure distribution and dose reduction carry disproportionate clinical weight.
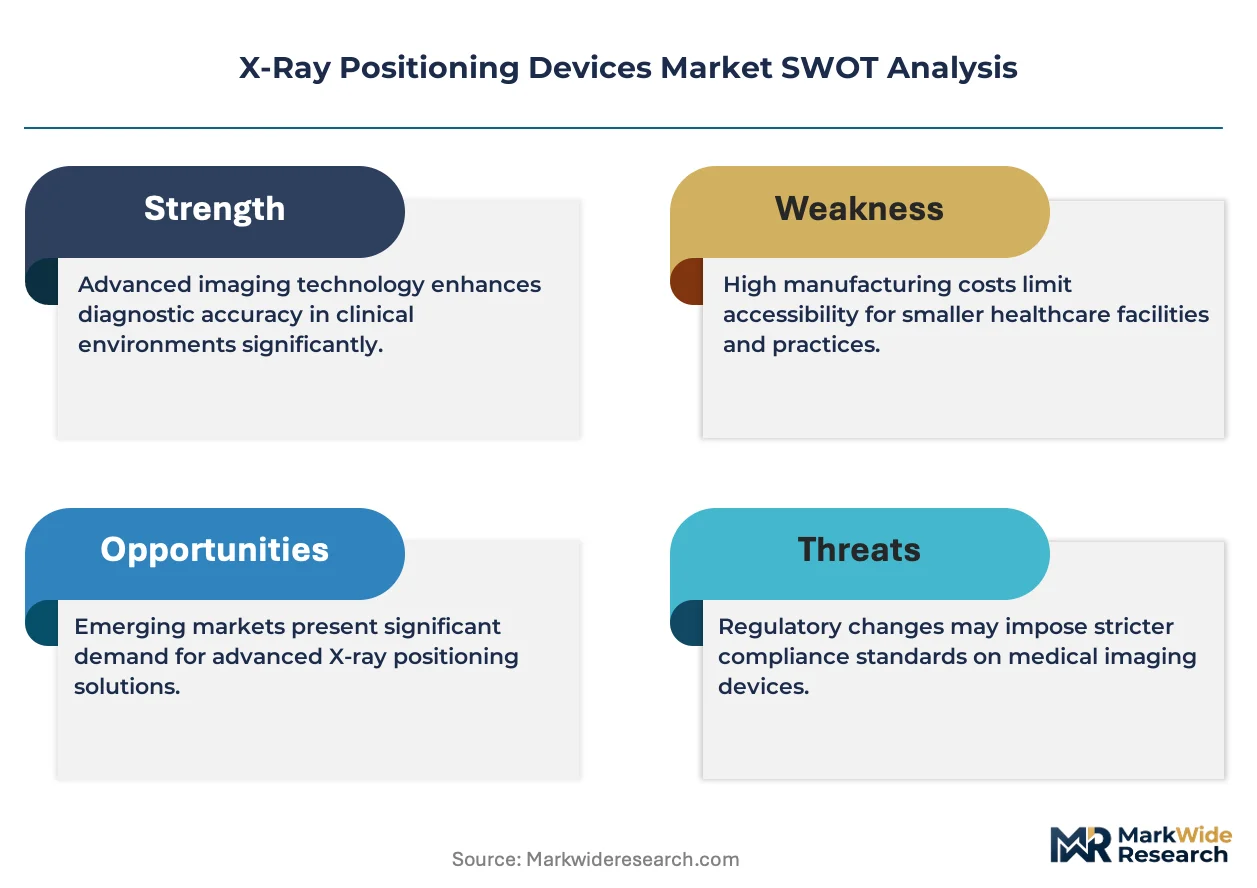
The FDA's 510(k) premarket notification framework gates U.S. commercial entry for positioning devices, compelling manufacturers to demonstrate substantial equivalence to predicate devices before deployment in clinical settings. The EU Medical Device Regulation imposes stricter clinical evidence requirements than its predecessor directive, extending conformity assessment timelines for systems sold across European member states. Stakeholders must monitor how evolving radiation safety standards from the IEC reshape material specifications and design tolerances in next-generation positioning platforms.
Market Dynamics
Carbon-fiber composite adoption is compressing supply chains as hospitals demand lighter tables that reduce radiation dose without sacrificing load capacity, forcing aluminum-dependent manufacturers to retool fabrication lines or cede trauma-center contracts.
Growth Catalysts
- EU Medical Device Regulation:Stricter clinical evidence requirements are filtering out low-quality suppliers and consolidating procurement toward ISO 13485-certified vendors with established technical documentation.
- Ambulatory surgical centers:Freestanding ASCs in the United States are upgrading imaging suites to capture orthopedic and pain-management procedures migrating from hospital campuses.
- Motorized positioning actuators:Electromechanical table adjustments are replacing manual cranks in bariatric suites, reducing staff injury claims and improving patient throughput.
Market Restraints
- Carbon-fiber prepreg supply:Aerospace and automotive demand is constraining medical-grade composite availability, extending lead times for radiographic table manufacturers by 8-14 weeks.
- Technical limitation:Electromagnetic interference between motorized positioning systems and MRI magnets prevents unified table platforms from serving hybrid imaging suites without shielding retrofits.
- Regulatory friction:The FDA's 510(k) substantial-equivalence pathway creates predicate-dependency traps where novel materials face extended review cycles despite clinical equivalence.
Strategic Opportunities
- Intensive care units:Portable positioning systems are penetrating medical-surgical ICUs where ventilated patients require bedside chest imaging without transport risks.
- Japan's aging infrastructure:METI subsidies for hospital modernization are opening replacement cycles for fixed radiographic installations in prefectural medical centers.
- Digital radiography convergence:Positioning tables with integrated detector docking are capturing bundled procurement decisions as hospitals consolidate vendor relationships.
Industry Challenges
- Biomedical engineering talent:Shortages of professionals with combined expertise in mechanical positioning and DICOM interoperability are delaying product development cycles.
- Legacy system integration:New electromechanical tables must interface with 15-20 year-old PACS architectures through proprietary middleware, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Positioning Devices Market |
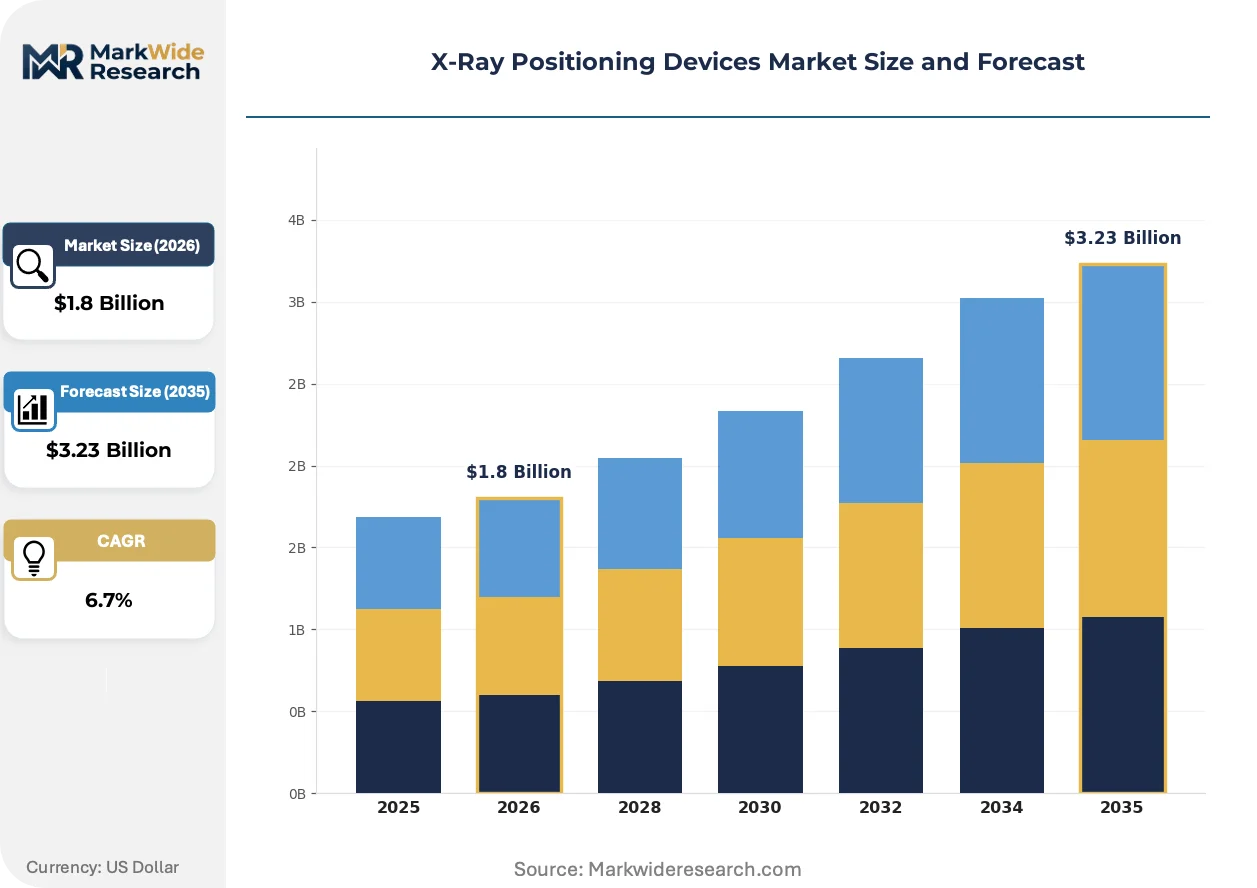
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Portable, Adjustable, Multifunctional End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Material: Plastic, Metal, Composite, Foam Functionality: Radiography, Fluoroscopy, Tomography, Other |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, Fujifilm Holdings, Shimadzu Corporation, Carestream Health, Hologic, Varex Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Positioning Devices Market Strategic Shifts
Automation and material science are converging to redefine how positioning systems balance radiation physics with ergonomic demands, compressing the gap between premium fixed installations and portable alternatives.
Carbon-fiber sandwich construction with aluminum honeycomb cores is supplanting solid aluminum table tops in mid-tier radiographic systems. Community hospitals and imaging centers are adopting these hybrid platforms to achieve dose reduction comparable to premium systems at 60-70% of the capital outlay. The technology is supplanting conventional aluminum in trauma bay installations where weight reduction enables faster patient positioning without ceiling-suspended tube support.
The EU Medical Device Regulation's clinical evidence requirements are extending conformity assessment timelines for positioning systems sold across member states. Manufacturers must now generate post-market surveillance data comparable to Class IIa active devices, compressing the competitive advantage of legacy suppliers with established technical files. German and French notified bodies are applying the strictest interpretations, pushing smaller vendors toward third-party clinical evaluation report providers.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchases, forcing positioning device vendors to compete on discrete service line items. Independent service organizations are capturing preventive maintenance contracts previously held by OEMs, particularly in the United States where third-party imaging equipment servicers have secured CMS recognition. This disintermediation is most visible in multi-hospital systems standardizing on single positioning platforms to simplify spare parts inventory and technician training.
X-Ray Positioning Devices Market Segmentation
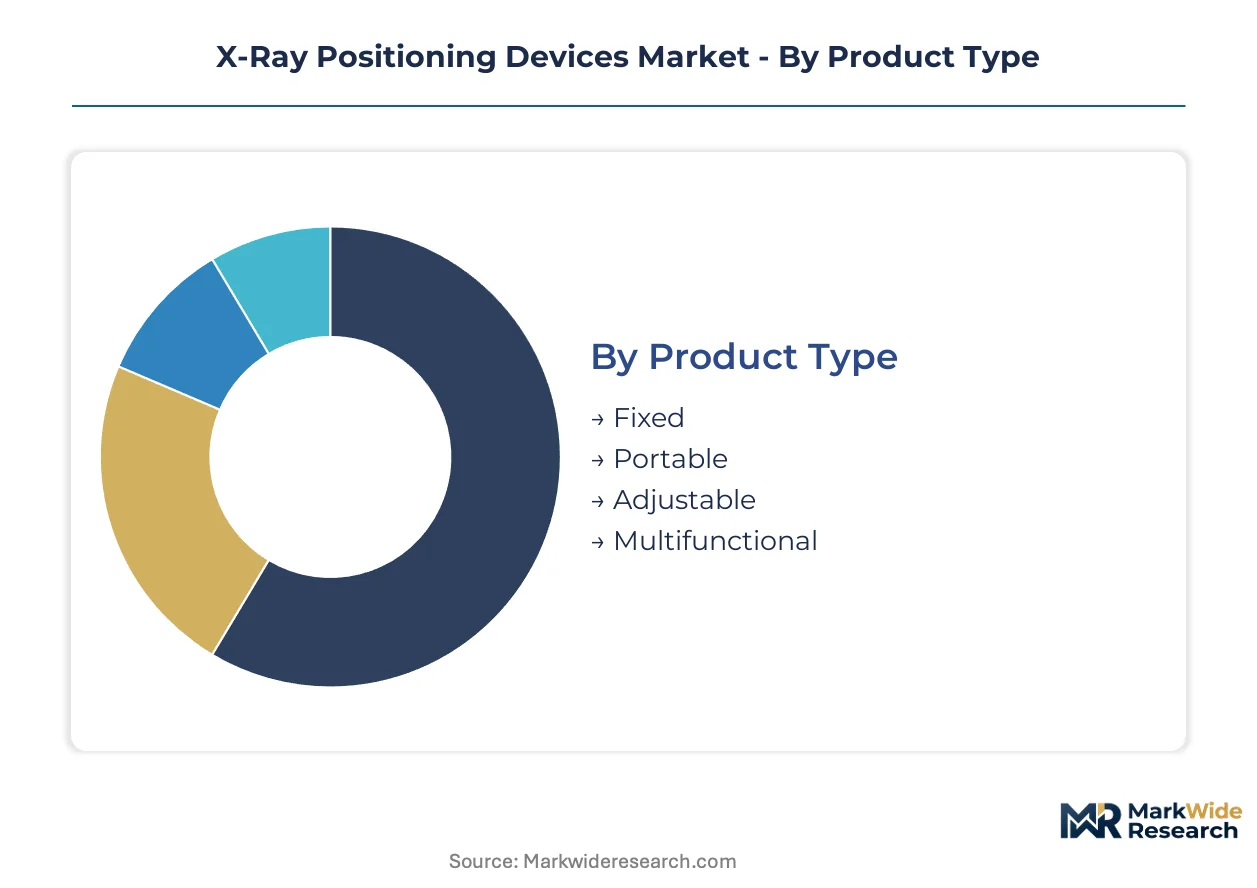
X-ray positioning devices fragment across four dimensions that reshape procurement priorities. Product architecture determines capital intensity and site preparation requirements. Material selection directly attenuates radiation dose and load-bearing capacity. End-user concentration in hospital radiology departments versus distributed imaging networks alters service contract structures.
Product Type:
Portable systems face the strongest substitution pressure from fixed installations in high-throughput settings, though point-of-care migration creates countervailing demand.
- Fixed:Permanent radiographic tables with motorized elevation and tilt functions occupy dedicated rooms in hospital radiology departments. Siemens Healthineers and GE Healthcare dominate procurement at academic medical centers in Germany and the United States where throughput exceeds 150 studies daily. These installations anchor the volume base while portable systems gain share at the steepest rate.
- Portable:Mobile units with collapsible frames and battery-powered positioning serve ICU and emergency department applications. Demand concentrates at trauma centers in Texas and Florida where patient transport risks outweigh image quality trade-offs.
- Adjustable:Manual or semi-electric tables with height and angle modification target mid-tier imaging centers balancing flexibility against capital constraints.
- Multifunctional:Hybrid platforms supporting both radiography and limited fluoroscopy capture bundled procurement decisions at ambulatory surgical centers upgrading from single-modality equipment.
Fixed installations retain the revenue base while portable configurations expand most quickly into bedside imaging workflows.
End User:
Cost tier stratification separates capital-rich hospital networks from price-sensitive independent imaging centers.
- Hospitals:Integrated delivery networks in the United States consolidate positioning procurement across radiology, surgery, and emergency departments. The FDA's 510(k) clearance pathway shapes vendor selection timelines for these multi-system purchases.
- Diagnostic Centers:Freestanding facilities in India and Brazil prioritize throughput-optimized fixed tables with rapid detector docking for high-volume outpatient workflows.
- Research Institutions:University medical centers in Japan and the Netherlands demand precision positioning for longitudinal imaging studies with sub-millimeter reproducibility requirements.
- Imaging Clinics:Independent operators in suburban United States markets favor refurbished fixed systems and portable units to minimize depreciation exposure.
Hospitals anchor procurement volume while diagnostic centers drive replacement cycles in emerging markets.
Material:
Supply concentration in aerospace-grade carbon fiber constrains medical device manufacturers against aluminum and foam alternatives.
- Composite:Carbon-fiber sandwich construction with aluminum honeycomb cores reduces radiation attenuation by 40% versus solid aluminum. Japanese manufacturers leverage METI-subsidized domestic composite supply for prefectural hospital modernization programs.
- Metal:Aluminum alloys remain standard for budget-tier tables in community hospitals where load capacity exceeds 200 kg but dose optimization carries lower priority.
- Plastic:Radiolucent polymers serve disposable positioning accessories and pediatric immobilization devices with limited reusability requirements.
- Foam:Pressure-distributing polyurethane systems dominate bariatric and pediatric positioning where patient comfort and pressure injury prevention outweigh material durability.
Composite materials command premium positioning while metal constructions retain the installed base.
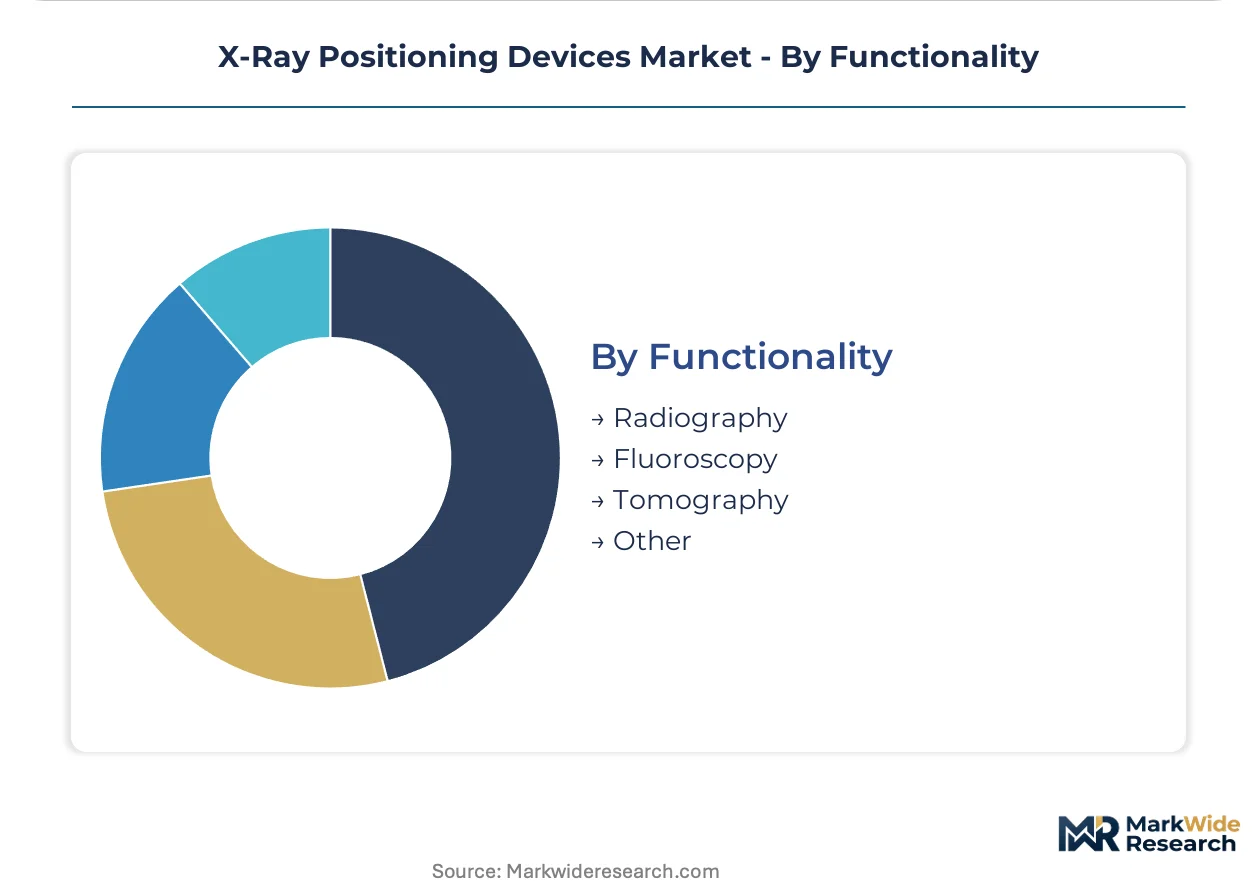
Functionality:
Maturity gradients separate established radiography applications from emerging tomography integration requirements.
- Radiography:Static image acquisition tables constitute the foundational positioning category across all end-user segments. The EU Medical Device Regulation's clinical evidence requirements extend conformity timelines for these systems in German and French markets.
- Fluoroscopy:Real-time positioning systems with C-arm compatibility serve interventional suites at cardiac centers in the United States and South Korea.
- Tomography:CT-compatible positioning with slip-ring interfaces captures upgrade demand at hospitals replacing first-generation 16-slice scanners.
- Other:Mammography-specific compression paddles and dental panoramic positioning represent niche applications with dedicated regulatory pathways.
Radiography functionality anchors the installed base while tomography-integrated positioning climbs the fastest as hospitals consolidate imaging platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States concentrate the largest share of positioning device demand, though replacement cycles in Japan and capacity expansion in Germany reshape regional ordering patterns.
United States
Ambulatory surgical centers in Texas and Florida drive portable system procurement as orthopedic procedures migrate from hospital campuses. The FDA's 510(k) clearance pathway governs commercial entry timelines for all radiological positioning equipment. Trauma centers in Houston and Miami prioritize battery-powered mobile units that eliminate patient transport risks in intensive care workflows.
Germany
Academic medical centers in Bavaria and Baden-Württemberg anchor fixed installation demand where daily throughput exceeds 150 studies. The EU Medical Device Regulation extends conformity assessment timelines through stricter clinical evidence requirements than its predecessor directive. Siemens Healthineers leverages its Forchheim manufacturing base to control supply timelines for hospital networks across Central Europe.
Japan
Prefectural medical centers in Kanto and Kansai regions pursue replacement cycles for aging fixed radiographic installations. METI subsidies for hospital modernization accelerate procurement decisions for carbon-fiber composite tables. Domestic manufacturers in Nagoya exploit subsidized composite supply chains to serve municipal hospital modernization programs.
China
Imaging centers in Shanghai and Beijing prioritize throughput-optimized fixed tables with rapid detector docking for high-volume outpatient workflows. The National Medical Products Administration regulates device registration through technical review processes that emphasize clinical validation. Provincial hospital clusters in Guangdong and Jiangsu expand radiology departments to serve aging urban populations.
India
Freestanding diagnostic facilities in Maharashtra and Karnataka favor refurbished fixed systems and portable units to minimize capital depreciation. The Central Drugs Standard Control Organization oversees import licensing and quality certification for radiological equipment. Imaging chains in Mumbai and Bengaluru consolidate vendor relationships to simplify spare parts inventory across multi-site operations.
X-Ray Positioning Devices Market Competitive Environment
Player mix skews toward diversified medical imaging conglomerates with captive positioning portfolios rather than pure-play specialists. Consolidation pressure favors vendors with integrated detector docking capabilities and established ISO 13485 quality systems. Two strategic archetypes dominate: full-platform imaging vendors bundling positioning with digital radiography detectors, and component suppliers serving third-party table manufacturers. Competitive moves center on backward integration into carbon-fiber fabrication and geographic expansion through distribution partnerships in Asia-Pacific markets.
Among diversified imaging vendors, GE Healthcare, Siemens Healthineers, and Koninklijke Philips occupy positions that exemplify platform-level competition. These corporations anchor the premium tier through in-house production of radiographic tables and deep integration with angiography suites. Their market presence reflects the broader pattern where hospital procurement committees favor consolidated vendor relationships over discrete component sourcing.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| Fujifilm Holdings |
| Shimadzu Corporation |
| Carestream Health |
| Hologic |
| Varex Imaging |
| Others |
Value Chain & Pricing Dynamics
Carbon-fiber prepreg capacity utilization above 85% at Japanese and German suppliers compresses margin structures for mid-tier table manufacturers while anchoring price floors for premium positioning systems. Hospital procurement committees exploit this concentration by consolidating annual purchase volumes into multi-year frame agreements with indexation clauses tied to aerospace composite spot markets.
Pricing Analysis
Cost-plus contracts with carbon-fiber indexation dominate procurement between radiographic table OEMs and hospital networks, insulating vendors from raw material volatility while capping upside. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified systems with integrated detector docking from refurbished aluminum tables and bare-bone manual units. Cost compression in the standard tier intensifies because independent service organizations now compete for preventive maintenance contracts previously bundled with equipment sales. Diagnostic centers in India and Brazil exhibit the highest price sensitivity, deferring replacement cycles and favoring refurbished fixed systems, while academic medical centers in Germany and the United States prioritize throughput-optimized configurations with minimal total-cost-of-ownership negotiation.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg extends inbound logistics timelines for carbon-fiber prepregs sourced from Japanese manufacturers, forcing table fabricators to hold larger safety stocks of aluminum honeycomb cores. Manufacturing concentrates in Germany, Japan, and the United States, with Siemens Healthineers anchoring European supply from its Forchheim facility and GE Healthcare controlling North American production timelines through in-house radiographic table fabrication. Medical-grade composite supply draws from aerospace-qualified weavers in Nagoya and Munich, exposing positioning device manufacturers to commodity allocation decisions by Boeing and Airbus procurement teams. Single-source vulnerability in Toray Industries' medical carbon-fiber grades creates concentration risk for vendors without dual-qualified suppliers. Distribution runs through hospital GPO contracts in the United States and direct tenders by prefectural medical centers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated delivery networks consolidating positioning procurement across radiology, surgery, and emergency departments, fragmenting the vendor base into full-platform imaging conglomerates and component suppliers fighting for discrete service line items.
For Market Incumbents: Fortify ISO 13485 certification barriers by accelerating post-market surveillance data collection to match EU Medical Device Regulation timelines, compressing the competitive window for smaller vendors lacking established technical files. Deepen backward integration into carbon-fiber sandwich fabrication to control supply timelines against aerospace demand competition, or risk ceding trauma-center contracts to Japanese manufacturers with METI-subsidized composite supply chains.
For New Entrants and Emerging Players: FDA 510(k) substantial-equivalence fast-tracks for predicate-matched aluminum tables offer the most penetrable entry path, particularly for portable systems targeting Texas and Florida trauma centers where patient transport risks outweigh brand loyalty. Target intensive care unit bedside imaging workflows with battery-powered mobile units, exploiting the gap between premium fixed installations and refurbished legacy equipment. Lead with independent service organization partnerships to disintermediate OEM after-sales contracts and capture preventive maintenance revenue streams.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component suppliers with captive carbon-fiber fabrication capabilities and established detector docking interfaces, as hospitals consolidate vendor relationships around bundled procurement decisions. Long-term viability hinges on backward integration depth and DICOM interoperability expertise, with five-to-ten year windows favoring vendors that bridge mechanical positioning and digital radiography convergence. Watch for inflection signals in METI subsidy renewal timelines for Japanese hospital modernization, which would accelerate replacement cycles for aging fixed radiographic installations.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Filters out contract manufacturers lacking quality management systems for FDA 510(k) pathway access. |
| Carbon-Fiber Backward Integration | Controls supply timelines against aerospace demand competition for medical-grade composite allocation. |
| Hospital GPO Contract Consolidation | Captures multi-system procurement decisions by integrated delivery networks standardizing on single platforms. |
| Portable System ICU Penetration | Addresses bedside imaging demand at trauma centers where patient transport risks outweigh image quality trade-offs. |
| Independent Service Organization Partnership | Disintermediates OEM after-sales contracts as procurement committees unbundle service line items. |
Study Parameters
A spread of perspectives from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and radiology department heads converged on the working assumptions for demand modeling and replacement cycle timing. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, EU Medical Device Regulation technical documentation, hospital procurement records, and carbon-fiber composite trade flow data. Bottom-up unit economics for fixed, portable, and multifunctional positioning systems triangulated against top-down market sizing by end-user concentration and geographic replacement cycles.
Segmentation dimensions modeled include product architecture, material composition, end-user category, and functional application across the projection horizon. CAGRs derived from logistic growth curve fitting to historical procurement data, adjusted for regulatory timeline shifts and subsidy program renewals. Industry-specific forecast inputs incorporated METI modernization subsidy schedules, FDA 510(k) review cycle durations, and carbon-fiber prepreg lead time fluctuations.
Decision-makers should treat outputs as directional under assumptions of stable regulatory pathways and continued aerospace composite demand; material deviation would warrant model refresh. Specific risk factors include EU MDR clinical evidence requirement tightening, single-source carbon-fiber supply disruptions, and electromagnetic interference standards reshaping motorized positioning system designs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Penile Implants Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Trocars Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Directed Energy Based Surgical Systems Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
EEG Amplifiers Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
Global Angiography Catheters Market
Medical Devices
Artificial Disc Market
Medical Devices
Point of Care Ultrasound Systems Market