
 Pembrolizumab Market | 2026-2036
Pembrolizumab Market Size, Share, and Industry Trends Forecast 2026-2036
Pembrolizumab Market Analysis
The capital-intensity divergence between large-scale biologics manufacturers and emerging biosimilar developers is unwinding competitive dynamics across the pembrolizumab landscape. Merck & Co., Inc. anchors the originator segment through captive control of cell-culture manufacturing capacity and proprietary purification platforms. Bristol-Myers Squibb Company competes via parallel PD-1 franchise investments, while Roche Holding AG extends its position through diagnostic companion testing integration.
Pembrolizumab is a humanized monoclonal IgG4 antibody targeting the programmed cell death protein 1 (PD-1) receptor, manufactured through recombinant DNA technology in Chinese hamster ovary cell lines with a molecular weight of approximately 149 kDa. The therapy functions by blocking PD-1 interaction with its ligands PD-L1 and PD-L2, thereby restoring T-cell mediated anti-tumor immune response in multiple solid malignancies. Monoclonal antibody formulations retain dominant revenue share due to established reimbursement and clinical familiarity, while combination therapies represent the fastest-expanding structural segment as investigators pair PD-1 blockade with chemotherapy, targeted agents, and novel immunomodulators. Hospital end users capture the largest volume channel, though homecare settings are gaining traction where subcutaneous delivery formats receive regulatory clearance.
The FDA, EMA, and NMPA collectively shape market access through divergent biosimilar interchangeability standards, post-marketing surveillance requirements, and manufacturing inspection protocols that determine supply eligibility across jurisdictions. The FDA's breakthrough therapy designation and EMA's PRIME scheme compress review timelines for novel indications, directly expanding addressable patient populations. Stakeholders must monitor evolving PD-L1 companion diagnostic requirements and biosimilar substitution policies that will determine pricing power and volume retention across branded and follow-on products.
Market Dynamics
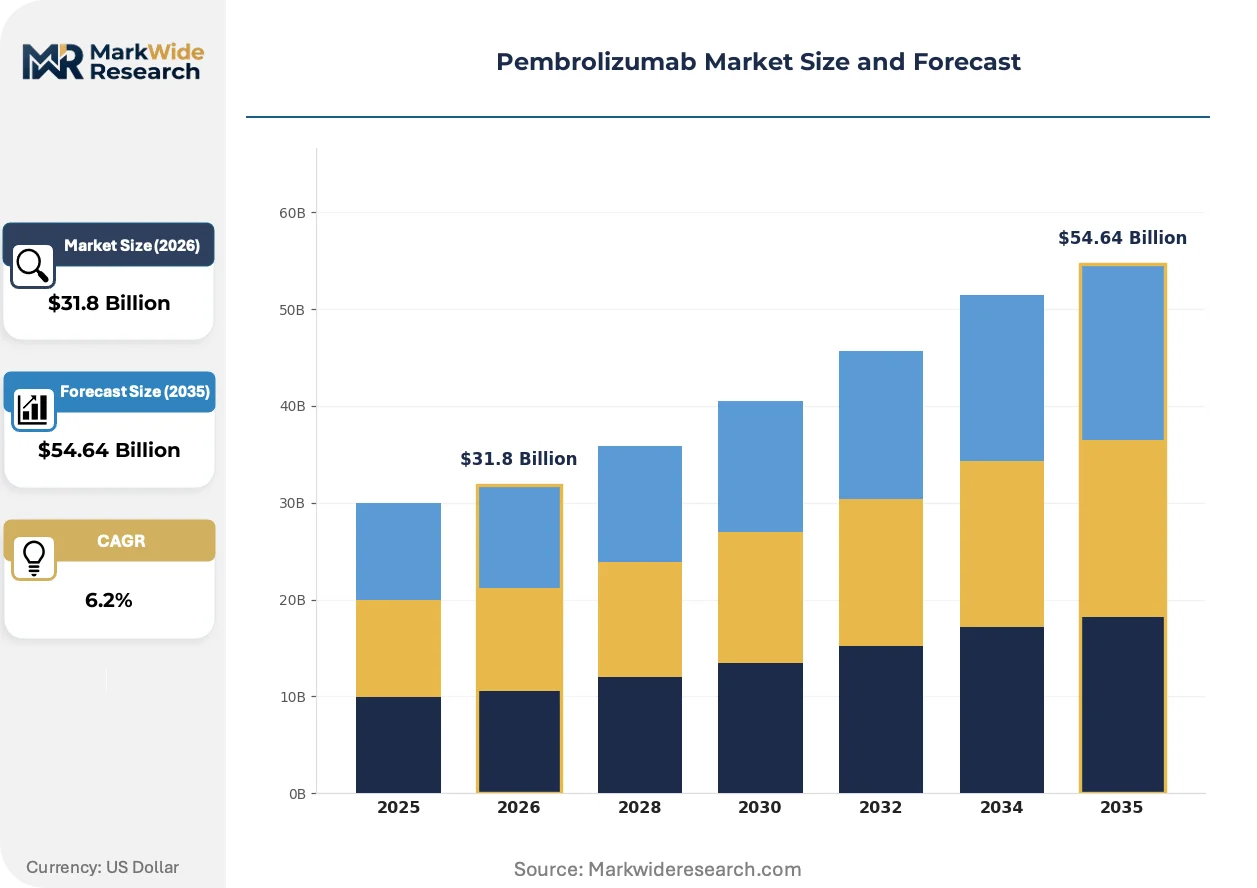
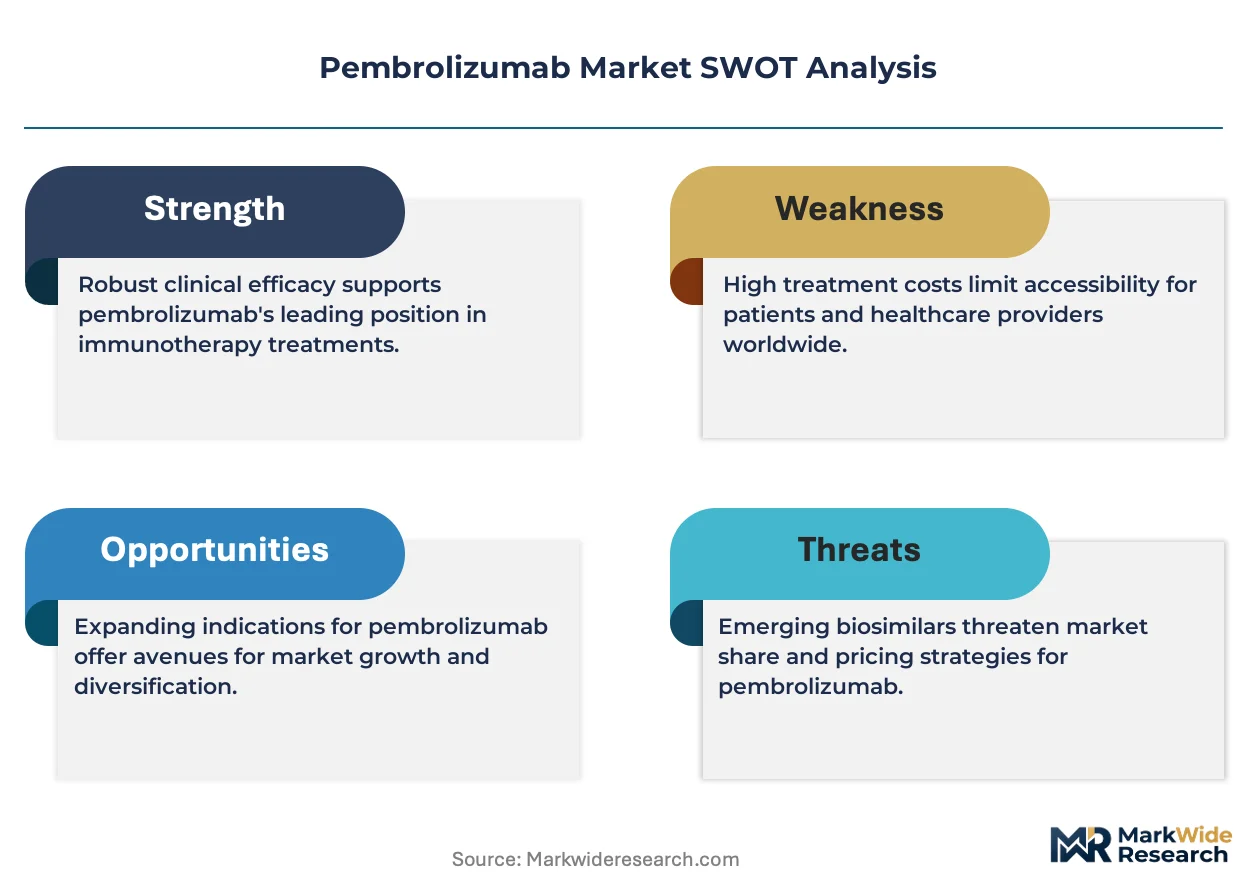
The pembrolizumab market is restructuring around biosimilar entry timelines and subcutaneous formulation shifts that threaten originator pricing power. Merck's manufacturing scale advantages face erosion as FDA interchangeability standards mature and hospital formularies gain substitution authority.
Growth Catalysts
- NCCN guideline expansion:Inclusion across additional solid tumor categories drives Medicare coverage decisions and hospital procurement volumes in the United States.
- Companion diagnostic integration:PD-L1 testing platforms from Roche and Agilent are streamlining patient selection and accelerating treatment initiation timelines.
- Subcutaneous delivery development:Reduced infusion center burden is expanding site-of-care flexibility and enabling home administration where regulatory clearance exists.
Market Restraints
- Cell-culture capacity concentration:Single-source dependence on Chinese hamster ovary production lines in specific geographies creates supply vulnerability.
- Biosimilar development costs:Immunogenicity testing requirements and analytical comparability studies impose capital barriers exceeding $200 million per program.
- Patent thicket complexity:Formulation and manufacturing process patents extend originator exclusivity periods beyond composition-of-matter expiration.
Strategic Opportunities
- Japan's aging oncology population:METI reimbursement incentives for immuno-oncology agents are expanding addressable patient pools beyond Western markets.
- Neoadjuvant protocol expansion:Perioperative PD-1 blockade in resectable cancers represents an underpenetrated treatment setting with extended dosing windows.
- Digital therapeutics convergence:Remote patient monitoring platforms paired with immunotherapy are creating adherence and toxicity management value pools.
Industry Challenges
- Immuno-oncology talent scarcity:Clinical pharmacologists and translational researchers with PD-1 mechanism expertise command premium compensation and extended recruitment cycles.
- Cold-chain infrastructure gaps:Temperature-controlled distribution networks in emerging markets lack redundancy for 2-8°C biologic stability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pembrolizumab Market |
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $54.64 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibody, Biosimilars, Combination Therapies, Injectable Formulations Therapy Area: Oncology, Dermatology, Hematology, Autoimmune Disorders Delivery Mode: Subcutaneous, Intravenous, Oral, Topical End User: Hospitals, Clinics, Research Institutions, Homecare Settings |
| Companies Covered | AstraZeneca, Sanofi S.A., Merck & Co., Inc., Johnson & Johnson, Regeneron Pharmaceuticals, Inc., Bristol-Myers Squibb Company, Pfizer Inc., Eli Lilly and Company, Roche Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pembrolizumab Market Emerging Trajectories
Biologic manufacturing and delivery modalities are converging to reshape competitive positioning across the pembrolizumab landscape. Innovators and biosimilar developers alike are racing to capture value from formulation advances and diagnostic integration.
Subcutaneous auto-injector platforms are miniaturizing the administration experience for pembrolizumab patients. Oncology clinics in Germany and the United Kingdom are piloting these devices to reduce chair time and infusion center congestion. The technology is compressing site-of-care requirements and enabling home-based administration models that shift reimbursement dynamics toward pharmacy benefit structures.
EMA's PRIME scheme acceleration for combination immuno-oncology regimens is compressing development timelines across European markets. The policy mechanism prioritizes PD-1 plus novel agent pairings, forcing sponsors to align manufacturing scale-up with earlier approval windows. Smaller EU member states with centralized procurement are leveraging this timeline compression to negotiate earlier access agreements.
Hospital pharmacy consolidation is concentrating purchasing leverage among integrated delivery networks in the United States. Three-hundred-plus bed systems are unbundling traditional distributor relationships and negotiating direct manufacturer contracts for checkpoint inhibitors. This behavioral shift is most visible in Texas and Florida, where IDN formation has compressed vendor counts by forty percent since 2022.
Pembrolizumab Market Segmentation
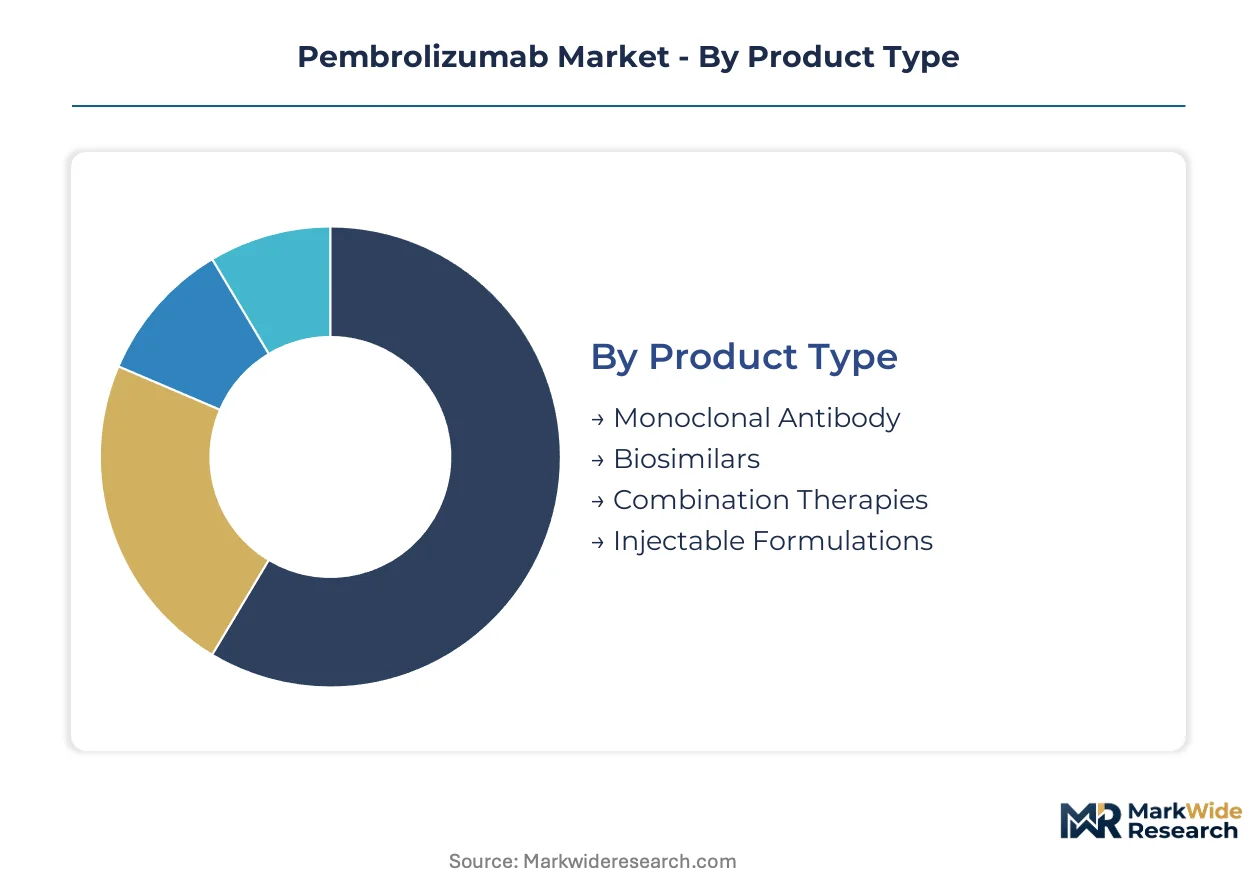
Pembrolizumab's market structure reflects competing pressures between originator defense and biosimilar substitution. Segment boundaries are shifting as formulation innovations and site-of-care migration reshape procurement patterns across oncology networks.
Product Type:
Substitution pressure concentrates in injectable formats where biosimilar developers target interchangeability designations first.
- Monoclonal Antibody:Humanized IgG4 formulations manufactured through recombinant DNA technology in Chinese hamster ovary cell lines dominate hospital procurement in the United States. Medicare reimbursement codes and NCCN guideline anchoring protect volume retention despite patent cliff proximity.
- Biosimilars:Analytical comparability studies and immunogenicity testing programs exceeding $200 million per candidate impose capital barriers that favor large-scale developers with captive manufacturing infrastructure. FDA interchangeability standards determine hospital formulary substitution authority.
- Combination Therapies:PD-1 blockade paired with chemotherapy or targeted agents.
- Injectable Formulations:Standard presentation for infusion center administration.
Monoclonal antibody formulations retain volume leadership; biosimilars hold the steepest expansion curve.
Therapy Area:
Cost tier differentiation separates premium oncology indications from exploratory dermatology applications.
- Oncology:Solid tumor categories including melanoma, non-small cell lung cancer, and head and neck malignancies drive procurement volumes through Medicare coverage decisions. FDA accelerated approval pathways compress development timelines for novel indications.
- Dermatology:Investigational applications in advanced cutaneous conditions.
- Hematology:Lymphoma and myeloma protocol integration.
- Autoimmune Disorders:Early-phase exploration outside oncology core.
Oncology commands absolute revenue concentration; dermatology represents the most distant expansion frontier.
Delivery Mode:
Application urgency varies by site-of-care constraints and patient mobility limitations.
- Intravenous:Infusion center administration remains the reimbursement-standard format across United States hospital networks. Chair time requirements and nursing supervision needs concentrate demand in 300-plus bed integrated delivery systems.
- Subcutaneous:Auto-injector platforms piloting in Germany and the United Kingdom compress administration duration and enable home-based models. Pharmacy benefit reimbursement structures differ from medical benefit coding for infusion.
- Oral:No current pembrolizumab availability; theoretical future format.
- Topical:Not applicable to systemic PD-1 blockade mechanism.
Intravenous delivery retains institutional preference; subcutaneous formats are climbing the fastest toward regulatory clearance.
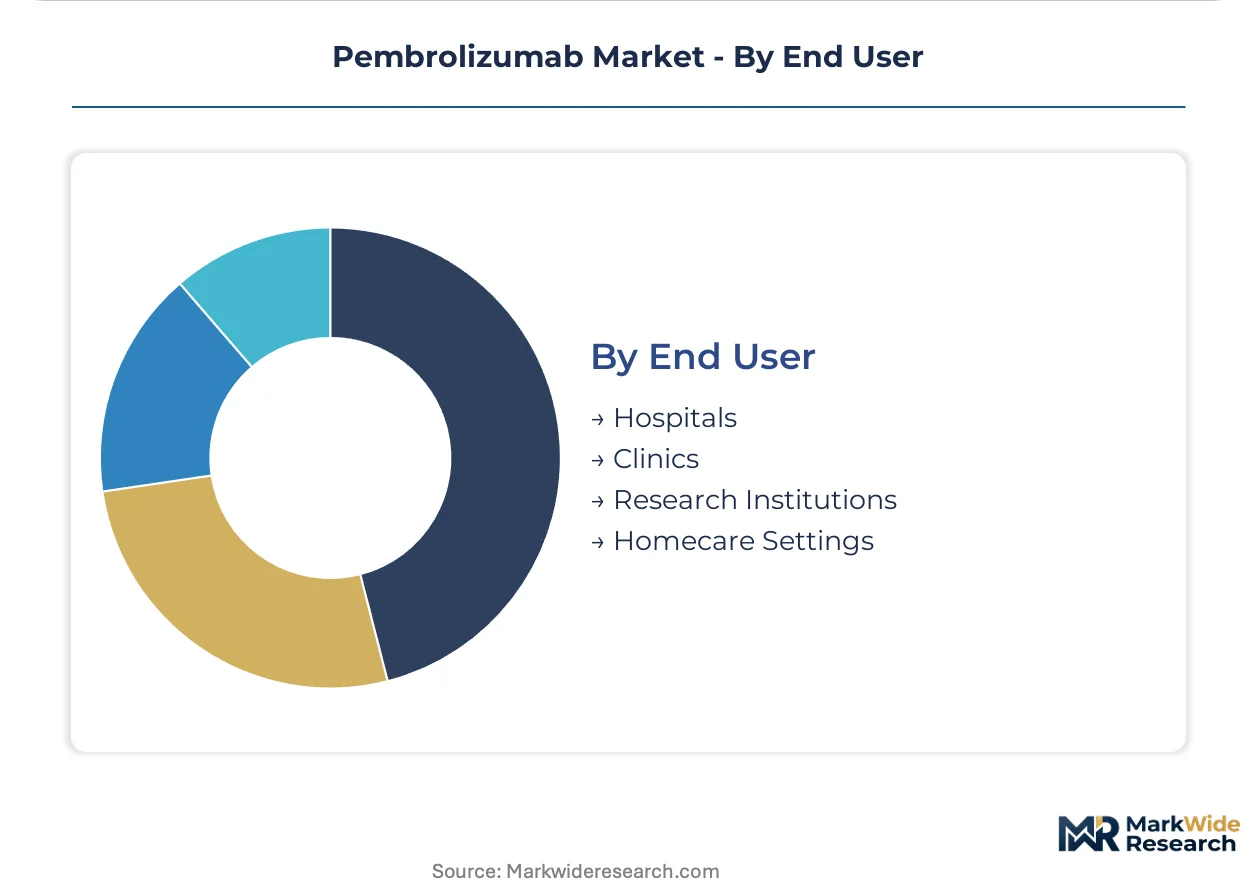
End User:
Customer type determines contracting leverage and pricing transparency exposure.
- Hospitals:Integrated delivery networks in Texas and Florida have compressed vendor counts by forty percent since 2022 through direct manufacturer negotiations. Three-hundred-plus bed systems unbundle distributor relationships for checkpoint inhibitor procurement.
- Homecare Settings:Subcutaneous delivery expansion enables pharmacy benefit reimbursement models that shift margin capture from infusion centers to specialty pharmacies.
- Clinics:Community oncology practices with limited formulary control.
- Research Institutions:Academic medical centers driving neoadjuvant protocol development.
Hospitals retain absolute volume leadership; homecare settings are gaining share fastest through site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in pembrolizumab concentrate manufacturing inputs in Switzerland and Germany while finished dose formulation gravitates toward the United States and Japan. Import dependency for cell-culture media and single-use bioreactor components shapes procurement risk profiles across major oncology markets.
United States
Medicare coverage decisions and NCCN guideline inclusion drive hospital procurement volumes for checkpoint inhibitors. FDA breakthrough therapy designations compress review timelines for novel indications, expanding reimbursable patient populations. The Texas Medical Center in Houston and Memorial Sloan Kettering in New York anchor clinical trial networks for neoadjuvant PD-1 protocols.
Germany
EMA's PRIME scheme accelerates combination immuno-oncology regimens through centralized European approval pathways. Hospital pharmacy consolidation in Bavaria and North Rhine-Westphalia concentrates purchasing leverage among integrated delivery networks. The Munich and Heidelberg oncology clusters pilot subcutaneous auto-injector platforms to reduce infusion center congestion.
Japan
METI reimbursement incentives for immuno-oncology agents expand addressable patient pools in an aging oncology population. PMDA's Sakigake designation system prioritizes PD-1 blockade reviews for domestic manufacturers. The Tokyo and Osaka metropolitan areas concentrate infusion center capacity and companion diagnostic testing infrastructure.
Switzerland
Swissmedic's alignment with EMA centralized procedures streamlines market access for biologics manufactured in Basel and Zurich. The country's pharmaceutical clusters supply cell-culture media and purification technologies to global pembrolizumab manufacturers. Roche's diagnostic integration from Rotkreuz reinforces companion testing standardization across European markets.
China
NMPA's accelerated approval pathways for innovative biologics compress development timelines for domestic PD-1 developers. Shanghai and Beijing biotech parks concentrate biosimilar analytical comparability capabilities. The Yangtze River Delta region builds cold-chain redundancy for temperature-controlled biologic distribution.
Pembrolizumab Market Vendor Landscape
Concentration sits with originator biologics manufacturers commanding proprietary cell-culture platforms and formulation patents. The competitive structure stratifies across three tiers: large-scale innovators with diagnostic integration capabilities, mid-cap biosimilar developers building analytical comparability programs, and emerging biotechs pursuing novel combination regimens. Capacity expansion and strategic partnerships dominate competitive moves as firms secure manufacturing scale ahead of patent cliff timelines.
Within the originator tier, Merck & Co., Inc. and Bristol-Myers Squibb Company exemplify divergent PD-1 franchise strategies. Merck anchors the segment through captive control of manufacturing infrastructure, while Bristol-Myers Squibb occupies a competitive position via parallel receptor-targeting investments. Roche Holding AG represents the diagnostic-integrated archetype, bundling companion testing with therapeutic protocols to streamline patient selection workflows.
| Leading Market Players |
|---|
| AstraZeneca |
| Sanofi S.A. |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Regeneron Pharmaceuticals, Inc. |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Eli Lilly and Company |
| Roche Holding AG |
| Others |
Supply Flow & Price Mechanics
FDA interchangeability standards gate both supply qualification and price differentiation simultaneously, determining which biosimilar developers gain hospital formulary substitution authority and which originator tiers retain premium positioning. The regulatory threshold separates interchangeable products commanding parity pricing from non-interchangeable alternatives relegated to discount tiers, while manufacturing scale requirements concentrate supply among capitalized developers capable of immunogenicity testing programs.
Pricing Analysis
Hospital procurement teams anchor pricing structure through direct manufacturer negotiations that bypass traditional distributor markups. Three-tier pricing stratifies across originator, interchangeable biosimilar, and non-interchangeable follow-on levels, with differentiation driven by FDA designation status and NCCN guideline anchoring. Cost compression in the interchangeable tier intensifies as multiple developers pursue analytical comparability, while originator pricing faces erosion from site-of-care migration toward subcutaneous delivery. Community oncology practices exhibit highest price sensitivity due to limited formulary control and thin margin profiles.
Supply Chain Analysis
Inventory buffers for cell-culture media and single-use bioreactor components extend lead times beyond standard pharmaceutical procurement cycles. Manufacturing concentration rests on Chinese hamster ovary production lines in Switzerland, Germany, and the United States, with purification technologies and formulation capacity drawing from Basel and Zurich clusters. Single-source vulnerability concentrates in cell-culture media supply from specialized bioprocessing vendors. Distribution runs through cold-chain networks with 2-8°C stability requirements, with hospital pharmacy consolidation shifting leverage toward integrated delivery networks in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biosimilar substitution timelines compress the window for originator defense, forcing incumbents to secure manufacturing scale and diagnostic integration ahead of interchangeability designations that will erode pricing power.
For Market Incumbents: Secure captive control of cell-culture manufacturing capacity and companion diagnostic partnerships to defend volume retention against interchangeable biosimilar entry. Deepen backward integration into purification technologies and expand neoadjuvant protocol development to extend dosing windows beyond patent cliff exposure. For New Entrants and Emerging Players: FDA's abbreviated biosimilar pathway offers accelerated review timelines for developers with demonstrated analytical comparability and immunogenicity profiles. Target subcutaneous formulation development as the most penetrable segment, where auto-injector platforms enable pharmacy benefit reimbursement models distinct from infusion center capture. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents seeking to monetize non-core immuno-oncology assets ahead of biosimilar entry. Focus on mid-cap developers with demonstrated PD-1 mechanism expertise and manufacturing partnerships in place. Watch FDA interchangeability determinations as the inflection signal separating premium valuation tiers from commodity multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Auto-injector platforms shift reimbursement from medical to pharmacy benefit structures. |
| Companion Diagnostic Integration | Roche's PD-L1 testing standardization streamlines patient selection and accelerates treatment initiation. |
| Biosimilar Interchangeability Pursuit | FDA designation grants hospital formulary substitution authority and compresses originator pricing power. |
| Neoadjuvant Protocol Expansion | Perioperative dosing windows extend revenue capture beyond metastatic settings. |
| Direct Hospital Contracting | Integrated delivery networks in Texas and Florida unbundle distributor relationships for checkpoint inhibitors. |
Methodological Framework
The analysis maps monoclonal antibody, biosimilar, and combination therapy segments, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interview findings triangulate against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down revenue reconciliation cross-validate volume and value estimates.
Consistency checks against external benchmarks validate projection outputs across the analysis window. Segmentation dimensions include product type, therapy area, delivery mode, end user, and regional regulatory cluster. CAGRs derive from indication-specific patient flow models and dosing frequency assumptions, with inputs from Medicare coverage decisions and NCCN guideline expansion timelines.
Underlying assumptions cover biosimilar entry timelines, interchangeability determination schedules, and subcutaneous regulatory clearance pathways, with deviation risk concentrated in FDA review pace and hospital formulary substitution policies. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Lipid Injectable Market