
 Chronic Myelogenous Leukemia Treatment Market | 2026-2036
Chronic Myelogenous Leukemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Myelogenous Leukemia Treatment Market Analysis
Buyer concentration across oncology centers is rebalancing as hospital networks consolidate cancer service lines while independent hematology clinics multiply in suburban markets. Novartis AG leverages its deep manufacturing scale in kinase inhibitor production to sustain supply commitments across integrated delivery networks. Bristol-Myers Squibb anchors its position through differentiated second-line formulations that compete directly with generic imatinib pressures.
Chronic Myelogenous Leukemia Treatment encompasses targeted molecular therapies, stem cell interventions, and immunomodulatory protocols designed to suppress the BCR-ABL fusion protein driving malignant myeloid proliferation; tyrosine kinase inhibitors constitute the foundational pharmacologic mechanism, requiring sustained plasma concentration monitoring to maintain cytogenetic response. The product type dimension shows imatinib dominating volume through generic substitution while dasatinib and nilotinib capture margin pools in resistance-mutation segments; within therapy area, targeted therapy leads utilization as stem cell transplant contracts to relapsed-refractory niches with limited donor availability.
FDA oncology center of excellence designations and EMA priority medicines eligibility create divergent access timelines that shape commercial launch sequencing across North American and European markets; HIPAA data governance constraints and GDPR clinical trial transparency requirements add compliance layers to real-world evidence collection for label expansion. Stakeholders must monitor FDA breakthrough therapy designation accumulations and payer evidence requirements for next-generation TKI sequencing to anticipate reimbursement positioning before pipeline assets reach pivotal readouts.
Market Dynamics
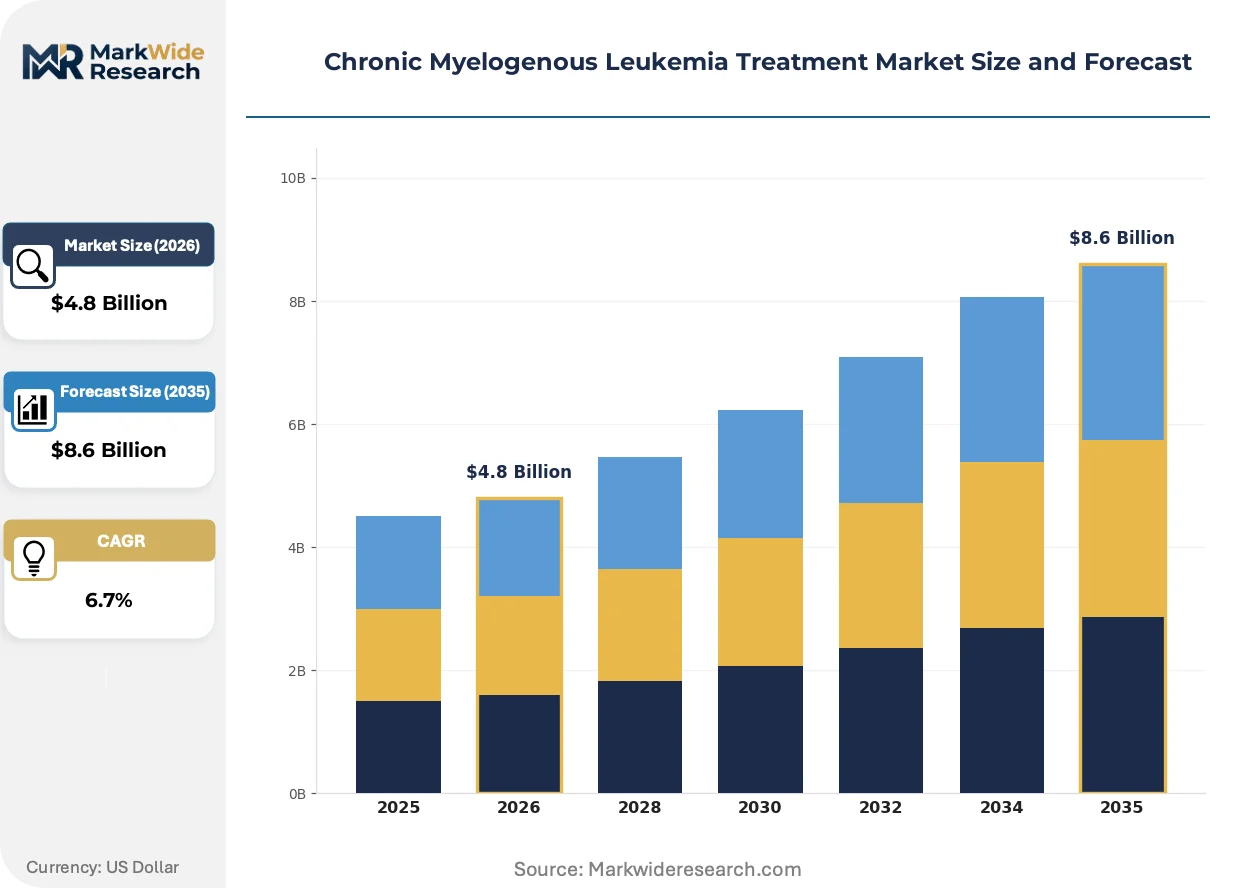
The Chronic Myelogenous Leukemia Treatment Market pivots on the tension between generic imatinib commoditization and next-generation tyrosine kinase inhibitor premium capture. FDA accelerated approval pathways compress development timelines while oncology center consolidation reshapes formulary access decisions.
Growth Catalysts
- EMA Priority Medicines Eligibility:European regulators fast-track novel BCR-ABL inhibitors, compressing commercial launch windows by 12-18 months versus standard review cycles.
- Resistance Mutation Profiling:Next-generation sequencing adoption in hematology clinics identifies T315I and other kinase domain mutations, driving demand for ponatinib and asciminib.
- Japan's Aging Hematology Population:METI-supported geriatric oncology initiatives expand reimbursement for oral kinase inhibitors in patients over 75, a historically transplant-averse cohort.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Over 70% of imatinib API originates from Chinese contract manufacturers, exposing supply chains to SAMR export license volatility.
- Stem Cell Donor Scarcity:Limited HLA-matched unrelated donor availability restricts allogeneic transplant to relapsed-refractory cases, capping procedural revenue pools.
- GDPR Clinical Data Friction:European real-world evidence collection faces CNIL-level consent requirements that delay label expansion submissions by 8-14 months.
Strategic Opportunities
- Suburban Hematology Clinic Networks:Independent infusion centers in Texas, Florida, and Arizona bypass hospital outpatient department billing caps, capturing Medicare Part B margin spreads.
- Combination TKI-Immunotherapy Protocols:Pembrozilumab-ponatinib sequencing in Philadelphia-positive acute lymphoblastic leukemia creates off-label prescriber experimentation zones.
- India's CDSCO Biosimilar Pathway:Accelerated comparability guidelines for imatinib copies open volume penetration in price-sensitive emerging markets.
Industry Challenges
- Pharmacokinetic Monitoring Specialist Shortage:Therapeutic drug monitoring for nilotinib QTc prolongation risk requires certified clinical pharmacists, a credential concentrated at NCI-designated centers.
- BCR-ABL Transcript Standardization:International Scale harmonization across ISHAGE-accredited laboratories remains incomplete, complicating molecular response adjudication for clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Myelogenous Leukemia Treatment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imatinib, Dasatinib, Nilotinib, Bosutinib Therapy Area: Targeted Therapy, Stem Cell Transplant, Chemotherapy, Immunotherapy Care Setting: Outpatient Clinics, Hospitals, Research Facilities, Home Care End User: Oncology Centers, Hematology Clinics, Pharmaceutical Companies, Patients |
| Companies Covered | Novartis AG, Bristol-Myers Squibb, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Takeda Pharmaceutical Co. Ltd., Sanofi, Incyte Corp., Merck & Co., Inc., Ascentage Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Myelogenous Leukemia Treatment Market Emerging Trajectories
Precision hematology is fragmenting the CML treatment algorithm into mutation-specific niches. Clinicians now sequence therapies based on compound kinase domain profiles rather than linear resistance progression.
Allosteric ABL1 inhibitors targeting the myristoyl pocket are expanding into front-line settings previously reserved for ATP-competitive TKIs. Community oncology practices in Germany and the Netherlands are piloting asciminib monotherapy in newly diagnosed chronic phase patients. This mechanism is compressing the addressable market for second-generation dasatinib and nilotinib by capturing treatment-naive volume.
FDA's Project Orbis creates synchronized oncology review with Health Canada and TGA Australia, collapsing multi-territory launch gaps for novel TKIs. Manufacturers now submit single dossiers across three regulators, reducing regulatory consulting spend. Small-cap developers without Orbis coordination face 18-24 month launch delays versus synchronized filers.
Oncology procurement groups at IDN headquarters are unbundling drug distribution from clinical service contracts. Premier and Vizient members in the United States now source imatinib through specialty pharmacy carve-outs while retaining infusion administration revenue. This bifurcation is most advanced in California and New York, where 340B contract pharmacy networks capture oral oncology dispensing margin from hospital-owned retail pharmacies.
Chronic Myelogenous Leukemia Treatment Market Segmentation
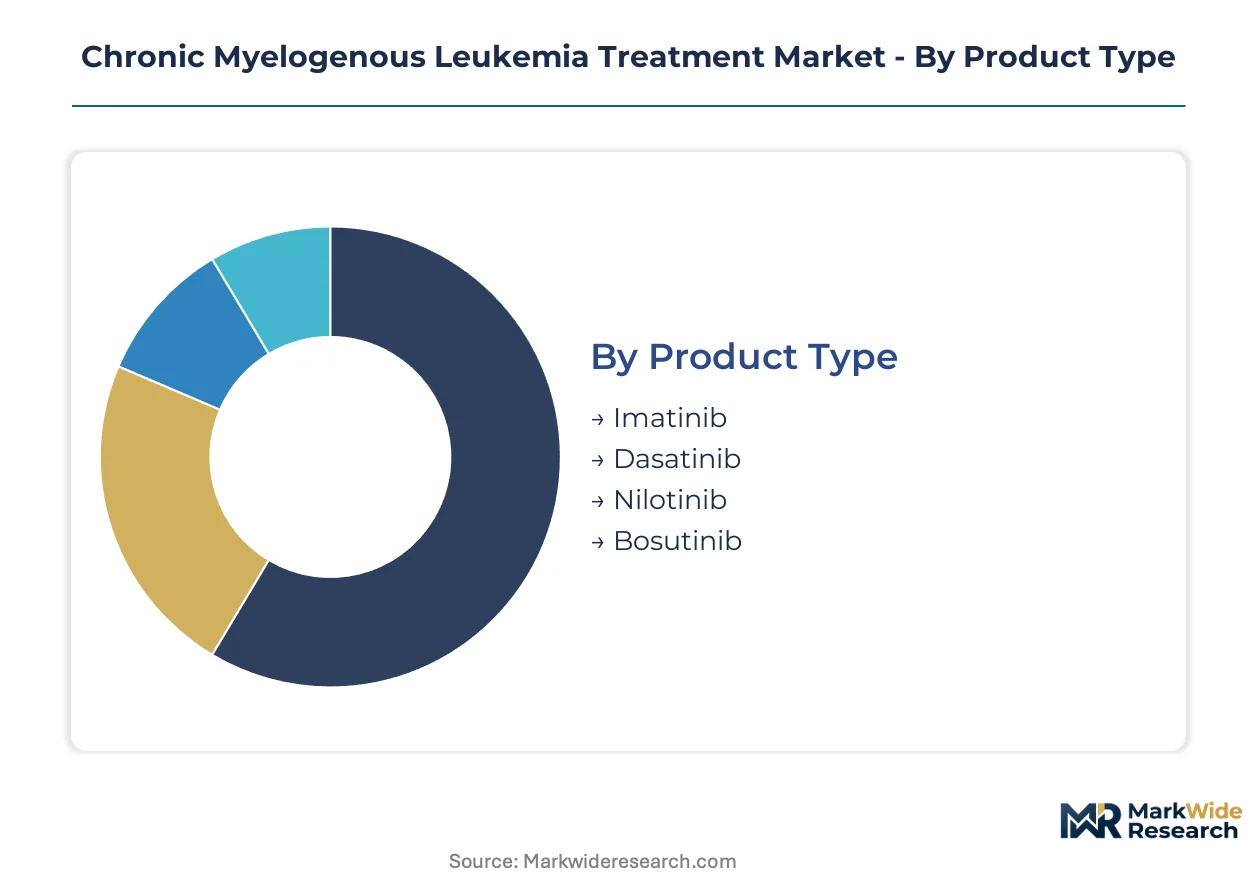
Chronic Myelogenous Leukemia treatment stratification reflects the tension between commoditized first-line generics and precision-matched next-generation inhibitors. Each segmentation axis reveals distinct margin pools, prescriber behaviors, and access pathways that reshape commercial strategy.
Product Type:
Tyrosine kinase inhibitor chemistry determines resistance profiles, dosing schedules, and monitoring requirements that differentiate clinical utility across mutation spectrums.
- Imatinib:ATP-competitive BCR-ABL inhibitor with established cytogenetic response rates serves as the foundational chronic phase therapy. Volume concentrates in Medicare Part D and emerging market tenders where generic substitution has compressed net pricing; FDA bioequivalence standards for copies sustain prescriber confidence despite manufacturing source diversity.
- Dasatinib:Dual SRC/ABL inhibitor with CNS penetration addresses accelerated phase progression and imatinib resistance with distinct pleural effusion risk profile. Demand clusters at NCI-designated centers performing T315I pre-screening; EMA conditional renewal requirements for vascular events shape risk-minimization protocols in European hematology networks.
- Nilotinib:Selective BCR-ABL inhibitor with superior molecular response depth in early chronic phase.
- Bosutinib:Dual ABL/SRC inhibitor positioned for intolerance rather than resistance sequences.
Imatinib leads on scale; dasatinib leads on momentum.
Therapy Area:
Clinical modality selection hinges on disease phase, comorbidity burden, and donor availability rather than cost optimization alone.
- Targeted Therapy:Oral kinase inhibitor protocols suppress BCR-ABL transcript burden through continuous ATP-site or allosteric pocket blockade. Utilization dominates in Germany and Japan where outpatient oral oncology reimbursement minimizes hospital dependency; asciminib myristoyl pocket mechanism is displacing second-generation ATP competitors in treatment-naive trials.
- Stem Cell Transplant:Allogeneic hematopoietic cell replacement offers curative potential through graft-versus-leukemia effect. Procedure volume restricts to relapsed-refractory Philadelphia-positive cases with matched unrelated donors; Japan's aging donor pool constraints and Germany's EBMT-accredited center consolidation limit addressable candidates.
- Chemotherapy:Cytarabine-based induction bridges to transplant in blast crisis transformation.
- Immunotherapy:Checkpoint inhibitor combinations explore Philadelphia-positive acute lymphoblastic leukemia overlap syndromes.
Targeted therapy commands volume concentration; immunotherapy climbs the fastest.
Care Setting:
Site of service economics determine infusion versus oral dispensing margins and nursing intensity requirements.
- Outpatient Clinics:Community hematology practices and hospital-based infusion centers manage oral TKI adherence and molecular monitoring. Growth concentrates in Texas and Florida where independent clinic billing bypasses hospital outpatient department caps; Medicare sequestration adjustments compress margin spreads versus 340B-eligible hospital pharmacies.
- Hospitals:Academic medical centers handle blast crisis admissions, transplant conditioning, and clinical trial enrollment. Tertiary centers in New York and California anchor phase I/II novel inhibitor development; EMA priority medicines eligibility accelerates European site activation timelines.
- Research Facilities:Dedicated clinical trial units conduct BCR-ABL mutation-directed protocol assignments.
- Home Care:Specialty pharmacy distribution supports oral therapy adherence monitoring.
Outpatient clinics lead on scale; home care leads on momentum.
End User:
Purchasing authority fragmentation across clinical, commercial, and patient-funded channels complicates account targeting.
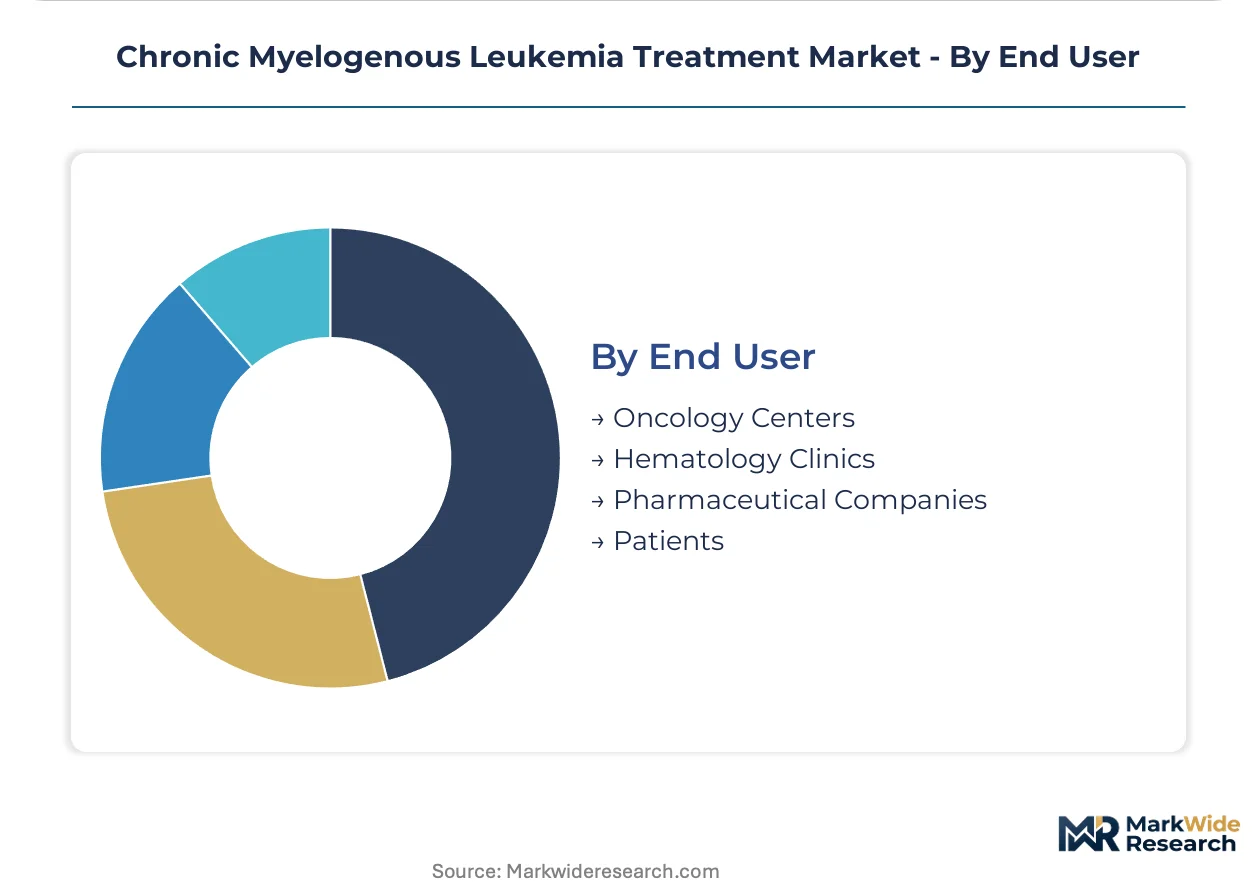
- Oncology Centers:Integrated delivery networks and NCI-designated comprehensive cancer centers aggregate formulary decision-making for oral oncology. Consolidation in Arizona and Pennsylvania creates concentrated contracting leverage; FDA breakthrough therapy designations trigger rapid P&T committee reviews at IDN headquarters.
- Hematology Clinics:Independent subspecialty practices in suburban markets capture Medicare Part B infusion margins. Networks in Florida and North Carolina bypass hospital billing structures; therapeutic drug monitoring for nilotinib QTc risk requires clinical pharmacist credentialing concentrated at larger sites.
- Pharmaceutical Companies:License holders and API purchasers negotiate contract manufacturing and co-development terms.
- Patients:Direct-pay channels emerge where prior authorization delays exceed clinical tolerance.
Oncology centers lead on scale; hematology clinics lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement frameworks favor next-generation tyrosine kinase inhibitors while Germany's statutory health insurance maintains broader access to stem cell transplant protocols, creating divergent therapy sequencing patterns across the two largest Western markets.
United States
Medicare Part D oral oncology benefits and 340B contract pharmacy networks concentrate dispensing volume in hospital-affiliated retail channels. FDA breakthrough therapy designations trigger rapid P&T committee reviews at integrated delivery network headquarters in Texas and Florida. Community hematology clinics in Arizona bypass hospital outpatient department billing caps to capture margin spreads.
Germany
Statutory health insurance funds reimburse asciminib and other next-generation inhibitors through AMNOG early benefit assessments, accelerating patient access versus standard HTA timelines. EMA priority medicines eligibility compresses commercial launch windows by 12-18 months. EBMT-accredited transplant centers in North Rhine-Westphalia consolidate allogeneic procedure volume as donor registries face aging pool constraints.
Japan
METI-supported geriatric oncology initiatives expand reimbursement for oral kinase inhibitors in patients over 75, a historically transplant-averse cohort. PMDA sakigake designation fast-tracks novel BCR-ABL inhibitors through priority review. Hematology networks in the Kansai region pilot therapeutic drug monitoring protocols for nilotinib QTc risk management.
India
CDSCO accelerated comparability guidelines for imatinib biosimilars open volume penetration in price-sensitive government tenders and private insurance segments. State-level oncology missions in Maharashtra and Karnataka expand molecular diagnostic capacity for resistance mutation profiling. Domestic API manufacturers in Gujarat and Telangana supply contract manufacturers serving regulated export markets.
United Kingdom
NICE technology appraisals sequence TKI access through cost-effectiveness thresholds that delay next-generation inhibitor availability versus European peers. NHS England cancer drugs fund provides conditional reimbursement for ponatinib in T315I-mutated cases. Academic medical centers in London and Manchester anchor phase I/II trials for allosteric ABL1 inhibitors.
Chronic Myelogenous Leukemia Treatment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the CML treatment spectrum, creating a tiered structure where manufacturing scale and kinase inhibitor development depth determine formulary positioning. Large-cap pharmaceutical companies anchor the premium segment through FDA-accelerated approvals and integrated delivery network contracting leverage. Mid-cap biotech developers concentrate on resistance-mutation niches and allosteric mechanism differentiation. The dominant competitive moves involve portfolio diversification into combination immunotherapy protocols and strategic partnerships for real-world evidence generation.
Within the large-cap diversified tier, Novartis AG and Bristol-Myers Squibb occupy anchor positions representing contrasting strategic archetypes. Novartis exemplifies deep manufacturing scale in kinase inhibitor production sustaining supply commitments across global integrated delivery networks. Bristol-Myers Squibb represents differentiated second-line formulation development competing directly with generic imatinib commoditization pressures. Pfizer Inc. sits within the same tier, its diversified oncology portfolio spanning both targeted therapy and immunotherapy modalities.
| Leading Market Players |
|---|
| Novartis AG |
| Bristol-Myers Squibb |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Takeda Pharmaceutical Co. Ltd. |
| Sanofi |
| Incyte Corp. |
| Merck & Co., Inc. |
| Ascentage Pharma |
| Others |
Supply Flow & Price Mechanics
Certified clinical pharmacists concentrated at NCI-designated centers in the United States command wage premiums that widen pricing spreads between premium-tier nilotinib monitoring protocols and standard imatinib generic dispensing. Labor-cost differentials between specialized therapeutic drug monitoring hubs and community infusion sites feed directly into three-tier pricing structure across premium, standard, and economy levels for kinase inhibitor therapy.
Pricing Analysis
Capacity additions in Chinese API manufacturing zones are reshaping price floors for generic imatinib while constraining premium-tier spreads for next-generation inhibitors. Contract-based long-term offtake agreements dominate procurement between integrated delivery networks and specialty pharmacy distributors, with FDA bioequivalence certification and volume scale serving as the primary price differentiation drivers. Cost compression in the generic tier is intensifying because Indian CDSCO biosimilar approvals accelerate tender competition. Government tenders in emerging markets exhibit highest price sensitivity; NCI-designated centers in the United States show lowest sensitivity due to bundled reimbursement for molecular monitoring.
Supply Chain Analysis
Workforce availability for certified clinical pharmacists constrains manufacturing scale-up in India and Germany where therapeutic drug monitoring integration is deepening. API production draws from Chinese contract manufacturers, Indian bulk chemical specialists, and Swiss finishing facilities, with imatinib mesylate, dasatinib free base, and asciminib intermediates serving as critical inputs. Single-source vulnerability in Chinese SAMR-licensed API export permits poses structural risk. Distribution runs through hospital-owned specialty pharmacies, independent hematology clinic infusion centers, and mail-order oncology dispensers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion runway as allosteric inhibitor premium capture displaces second-generation ATP-competitive commoditization and molecular monitoring bundling deepens per-patient revenue.
For Market Incumbents: Acquire resistance-mutation diagnostic platforms to lock in sequencing-driven prescribing workflows before generic imatinib pressures intensify. Secure backward integration into BCR-ABL transcript testing through partnerships with ISHAGE-accredited laboratories, defending against channel disintermediation by independent hematology networks in Texas and Florida. For New Entrants and Emerging Players: FDA accelerated approval pathways in the United States open a window for allosteric mechanism differentiation in front-line chronic phase segments previously reserved for ATP-competitive incumbents. Target suburban Medicare Part B billing zones where independent infusion centers bypass hospital outpatient department caps; lead with therapeutic drug monitoring service bundling rather than molecule pricing alone. For Investors and Strategic Acquirers: Large-cap oncology conglomerates with existing kinase inhibitor infrastructure are the most active acquirers in this space, seeking pipeline fill-ins rather than platform bets. Focus on mid-cap developers with asciminib-class allosteric assets and completed phase I/II readouts; watch FDA breakthrough therapy designation accumulations as inflection signals for rapid P&T committee access at consolidated IDN headquarters.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses commercial launch timelines by 12-18 months versus standard review. |
| Manufacturing Scale-Up | Deep kinase inhibitor production capacity at Novartis sustains supply commitments across global integrated delivery networks. |
| Pipeline Diversification | Allosteric ABL1 inhibitors targeting the myristoyl pocket expand into front-line settings previously reserved for ATP-competitive TKIs. |
| Strategic Partnership | Collaboration with ISHAGE-accredited laboratories standardizes BCR-ABL transcript harmonization for clinical trial enrollment. |
| Reimbursement Strategy | Medicare Part D oral oncology benefits and 340B contract pharmacy networks concentrate dispensing volume in hospital-affiliated retail channels. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down reimbursement spend analysis were triangulated to constrain variance.
Segment-weighting approaches applied differential growth assumptions across therapy area, product type, care setting, and end user dimensions over the projection horizon. CAGRs were derived from fitted trend extrapolation anchored to historical approval-to-uptake curves for kinase inhibitor classes. Forecast inputs incorporated resistance mutation prevalence rates and transplant eligibility criteria shifts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAMR export license disruptions or sudden EMA conditional renewal withdrawals. Forecasts reflect documented assumptions regarding payer evidence requirements and molecular diagnostic adoption curves. Material deviation in FDA breakthrough therapy designation velocity or 340B contract pharmacy network expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Perennial Allergic Rhinitis Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market