
 Viral Conjunctivitis Pipeline Drugs Market | 2026-2036
Viral Conjunctivitis Pipeline Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Conjunctivitis Pipeline Drugs Market Outlook
Ophthalmic virology expertise is unwinding as a bottleneck, with fellowship-trained specialists migrating toward gene therapy and retinal subspecialties. NovaBay Pharmaceuticals leverages its auriclosene platform to sustain leadership in broad-spectrum antiviral ocular therapy. Novartis AG anchors its position through integrated ophthalmology R&D spanning corticosteroid and antiviral combinations. Adenovir Pharma AB specializes in adenovirus-specific pipeline candidates, differentiating through targeted mechanism approaches rather than broad-spectrum coverage.
Viral conjunctivitis pipeline drugs comprise investigational antiviral, anti-inflammatory, and immunomodulatory formulations designed for ocular surface administration, typically formulated as preserved or preservative-free topical solutions with pH-buffered isotonic profiles compatible with tear film physiology. These candidates aim to reduce disease duration, prevent corneal complications, and limit transmission in clinical and community settings. Antiviral drug types command the deepest pipeline investment, while ocular delivery modes attract formulation innovation focused on enhanced corneal penetration and reduced dosing frequency. Acute viral conjunctivitis dominates indication-level development activity, though herpetic keratitis programs target higher per-patient value pools through orphan drug positioning.
FDA oversight governs IND-enabling studies and Phase I-III ophthalmic trial design, while EMA's centralized marketing authorization pathway shapes European market access timelines for viral conjunctivitis therapeutics. The WHO's inclusion of eye care within universal health coverage frameworks influences national reimbursement decisions for novel antiviral agents in emerging markets. Stakeholders must monitor regulatory precedent from adenoviral and herpetic keratitis approvals to anticipate evidentiary standards for conjunctivitis-specific indications.
Market Dynamics
The FDA's streamlined orphan drug designation pathway for adenoviral therapeutics is compressing clinical trial enrollment timelines and redirecting R&D investment toward mechanism-specific rather than broad-spectrum candidates.
Growth Catalysts
- NIH-Funded Research Networks:Specialized eye care institutions in the United States channel federal grants into early-phase antiviral development, accelerating candidate progression from bench to bedside.
- EMA Centralized Marketing Authorization:The European pathway reduces regulatory fragmentation across member states, enabling synchronized multi-country trial protocols for adenoviral therapeutics.
- Outpatient Antiviral Administration:Ophthalmology clinics deploy point-of-care diagnostic and treatment protocols that reduce hospital referral bottlenecks and expand addressable patient volumes.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Isotonic buffer and preservative supply chains cluster among specialty chemical manufacturers in Germany and Switzerland, creating input vulnerability.
- Fellowship Pipeline Collapse:Ophthalmic virology training programs lose candidates to gene therapy and retinal subspecialties, constraining clinical trial investigator availability.
- Generic Corticosteroid Substitution:Off-label dexamethasone and prednisolone eye drops remain first-line community practice despite inferior viral clearance profiles.
Strategic Opportunities
- Preservative-Free Formulation White Space:Tear film-compatible pH-buffered solutions without benzalkonium chloride address unmet needs in contact lens wearers and chronic dry eye populations.
- WHO Universal Health Coverage Integration:National reimbursement frameworks in emerging markets incorporate novel antiviral agents as essential medicines, expanding access-driven volume pools.
- Teleophthalmology Channel Expansion:Remote diagnostic platforms enable community-based screening and referral, reducing specialist visit burden while maintaining protocol adherence.
Industry Challenges
- Corneal Penetration Bioengineering:Formulation scientists must balance enhanced drug delivery with epithelial toxicity thresholds, extending preclinical optimization cycles.
- Adenoviral Serotype Coverage Gaps:Narrow-spectrum candidates require serotyping infrastructure unavailable in most primary care settings, complicating trial enrollment and post-market surveillance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Conjunctivitis Pipeline Drugs Market |
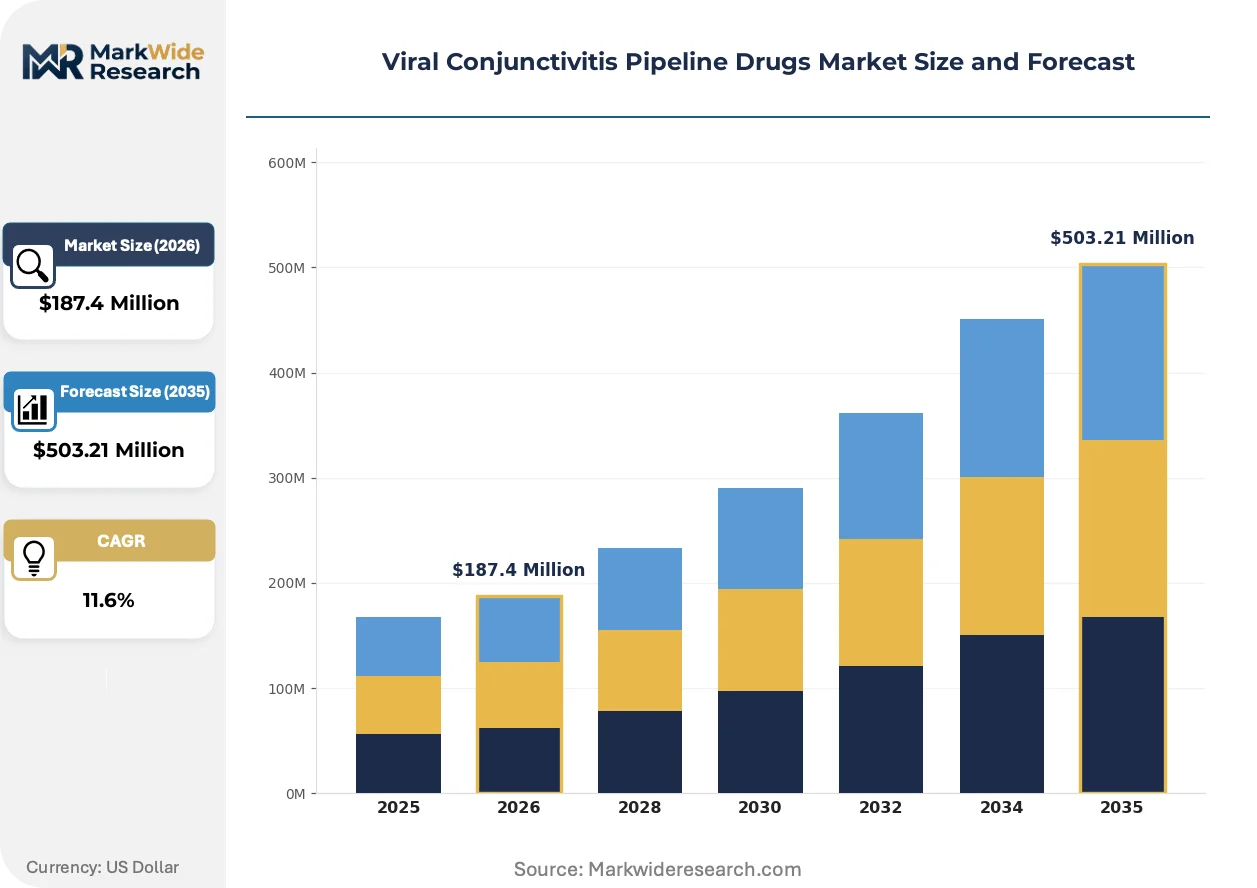
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Antivirals, Corticosteroids, Anti-inflammatory, Antihistamines Delivery Mode: Topical, Oral, Injectable, Ocular Indication: Acute Viral Conjunctivitis, Herpetic Keratitis, Adenoviral Infection, Viral Uveitis End User: Ophthalmology Clinics, Hospitals, Home Care, Research Institutions |
| Companies Covered | Shire Plc, NovaBay Pharmaceuticals Inc., Novartis AG, Panoptes Pharma GES.M.B.H., NicOx S.A., Adenovir Pharma AB, Allergan Plc, NanoViricides Inc., IACTA Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Conjunctivitis Pipeline Drugs Market Strategic Shifts
Antiviral ocular therapy is bifurcating between mechanism-targeted precision candidates and reformulated broad-spectrum platforms, with formulation science emerging as the decisive competitive differentiator.
Nanostructured lipid carriers and mucoadhesive polymers are supplanting conventional aqueous solutions in Phase II trials, enabling sustained release and reduced dosing frequency. Ophthalmology clinics in the United States and Germany pilot these platforms for adenoviral conjunctivitis, compressing treatment duration from fourteen days to seven. The structural consequence is a shift toward premium-priced specialty formulations that justify reimbursement through compliance improvement and corneal complication prevention.
The FDA's orphan drug designation pathway for adenoviral and herpetic keratitis indications is accelerating evidentiary standards for conjunctivitis-specific programs, requiring smaller patient populations for efficacy demonstration. Sponsors now design adaptive trial protocols that bridge keratitis and conjunctivitis indications, reducing per-program capital requirements. European sponsors leverage EMA's centralized pathway to synchronize US and EU enrollment, compressing total development timelines by twelve to eighteen months.
Specialized eye care networks are consolidating procurement authority through group purchasing organizations, displacing individual clinic formulary autonomy with standardized antiviral protocols. This concentration shifts vendor selection criteria toward supply security and clinical education support rather than unit pricing alone. The phenomenon is most visible in the United States, where vertically integrated ophthalmology platforms negotiate enterprise contracts covering dozens of satellite clinics.
Viral Conjunctivitis Pipeline Drugs Market Segmentation
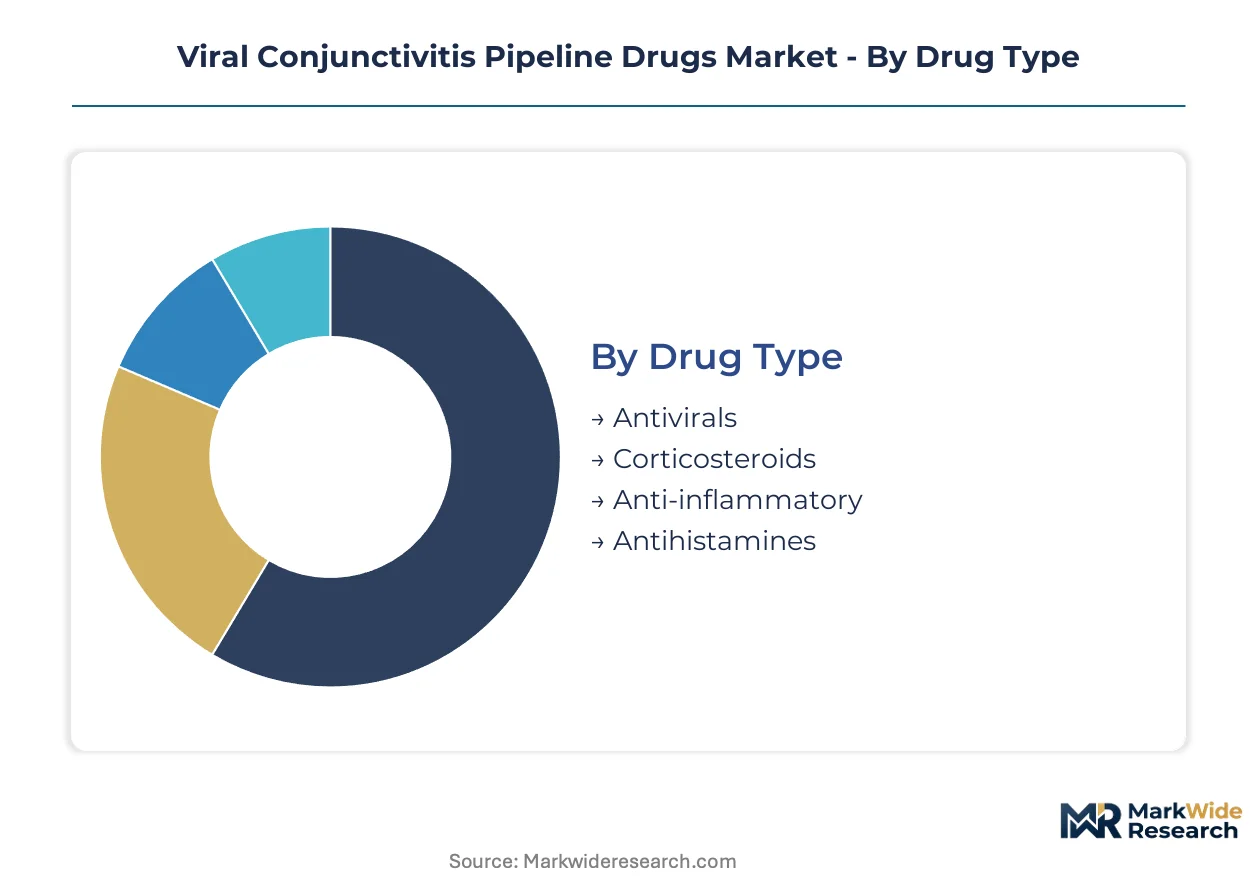
Pipeline segmentation reveals divergent investment priorities across mechanism classes and administration settings. Developers optimize formulation strategies against reimbursement pathways and prescriber concentration in specialized eye care networks.
Drug Type:
Antiviral candidates dominate domestic R&D pipelines in the United States, while corticosteroid combinations attract European export-oriented development programs seeking centralized EMA authorization.
- Antivirals:Mechanism-targeted candidates such as auriclosene and adenovirus-specific nucleoside analogs form the deepest clinical pipeline. NIH-funded networks in Bethesda and San Francisco concentrate Phase II enrollment for adenoviral indications, though serotype coverage gaps complicate primary care adoption.
- Corticosteroids:Combination formulations pairing dexamethasone with antiviral payloads address inflammation-driven corneal complications. German and Swiss specialty chemical manufacturers supply isotonic buffer systems for these preserved solutions, creating input dependencies for U.S. sponsors.
- Anti-inflammatory:Non-steroidal immunomodulators target contact lens wearers and chronic dry eye populations with benzalkonium chloride-free profiles.
- Antihistamines:Dual-action candidates address allergic-viral overlap presentations in community pharmacy settings.
Antivirals command the established base. The steepest expansion runs through corticosteroid combinations bridging inflammation control with viral clearance.
Delivery Mode:
Topical solutions absorb the majority of formulation investment, while injectable platforms concentrate in hospital-based herpetic keratitis programs commanding orphan drug premiums.
- Topical:Preserved and preservative-free ophthalmic solutions with pH-buffered isotonic profiles dominate outpatient protocols. Nanostructured lipid carriers in Phase II trials enable sustained release, compressing adenoviral treatment duration from fourteen days to seven in U.S. and German clinic pilots.
- Ocular:Subconjunctival and intravitreal depot formulations target posterior segment viral uveitis with extended-release polymers. Swissmedic-authorized manufacturing sites in Basel supply these specialty platforms to European hospital networks.
- Oral:Systemic antivirals with ocular penetration profiles serve immunocompromised patient populations.
- Injectable:Intravitreal antiviral delivery addresses sight-threatening herpetic retinitis in tertiary care centers.
Topical administration retains volume leadership. Ocular depot systems are climbing the fastest as complication prevention justifies premium reimbursement.
Indication:
Acute viral conjunctivitis development concentrates in U.S. outpatient networks, while herpetic keratitis programs leverage FDA orphan designation pathways for accelerated enrollment.
- Acute Viral Conjunctivitis:Adenoviral surface infection programs target the largest addressable patient pool through ophthalmology clinic channels. Point-of-care diagnostic protocols in U.S. integrated eye care networks enable rapid enrollment, though generic corticosteroid substitution persists in community practice.
- Herpetic Keratitis:Herpes simplex virus corneal infection candidates command the highest per-patient value pools through orphan drug positioning. Adaptive trial designs bridge keratitis and conjunctivitis indications, reducing capital requirements for sponsors leveraging EMA centralized pathways.
- Adenoviral Infection:Serotype-specific candidates require diagnostic infrastructure unavailable in most primary care settings.
- Viral Uveitis:Posterior segment inflammation programs target hospital-based specialists with injectable platforms.
Acute viral conjunctivitis anchors the commercial base. Herpetic keratitis is gaining share fastest through orphan drug economics.
End User:
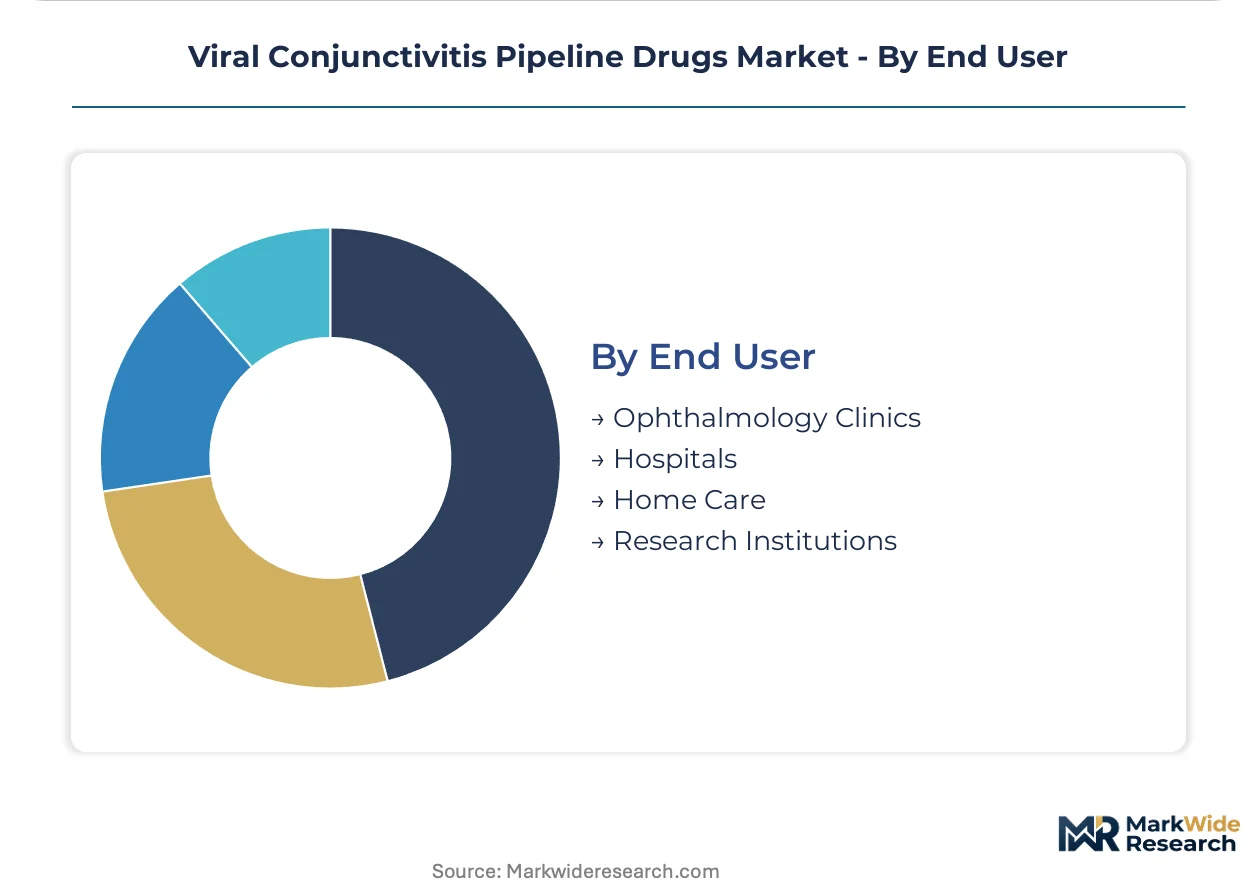
Ophthalmology clinics drive domestic demand growth through outpatient antiviral administration protocols, while research institutions channel federal grants into early-phase candidate progression.
- Ophthalmology Clinics:Specialized eye care networks consolidate procurement through group purchasing organizations, displacing individual formulary autonomy with standardized protocols. Vertically integrated U.S. platforms negotiate enterprise contracts covering dozens of satellite clinics, shifting vendor selection toward supply security and clinical education support.
- Research Institutions:NIH-funded centers in the United States accelerate bench-to-bedside translation through dedicated ophthalmic virology fellowship programs, though candidate migration toward gene therapy subspecialties constrains investigator availability.
- Hospitals:Tertiary centers manage sight-threatening complications and immunocompromised patient populations.
- Home Care:Teleophthalmology-enabled remote screening expands community-based access with specialist oversight.
Ophthalmology clinics hold the established volume position. Research institutions are expanding most quickly as federal grant concentration accelerates early-phase pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European markets compress margins through centralized procurement. German and Swiss manufacturers capture premium input markets through specialty chemical dominance. Emerging Asian demand centers lack diagnostic infrastructure to support mechanism-targeted therapies.
United States
NIH-funded research networks in Bethesda and San Francisco accelerate Phase II enrollment for adenoviral candidates. FDA orphan drug designation compresses evidentiary requirements for herpetic keratitis programs. Vertically integrated ophthalmology platforms in the Southeast and Pacific Northwest negotiate enterprise contracts covering dozens of satellite clinics.
Germany
Specialty chemical manufacturers in Ludwigshafen and Leverkusen supply isotonic buffer systems for preserved ophthalmic solutions. EMA centralized marketing authorization enables synchronized multi-country trial protocols. Bavarian and North Rhine-Westphalian ophthalmology clinics pilot nanostructured lipid carrier formulations.
Switzerland
Swissmedic-authorized manufacturing sites in Basel produce subconjunctival depot formulations for hospital networks. The country's pharmaceutical cluster commands premium pricing for corneal penetration technologies. Geneva and Zurich research institutions channel federal grants into formulation science innovation.
Japan
PMDA regulatory pathways favor mechanism-targeted candidates with biomarker endpoints. Tokyo and Osaka ophthalmology centers deploy point-of-care diagnostic protocols for rapid patient stratification. METI-funded consortia address preservative-free formulation gaps in contact lens wearer populations.
India
CDSCO marketing authorization timelines lag Western benchmarks by eighteen to twenty-four months. Generic corticosteroid substitution dominates community practice in Maharashtra and Karnataka. Emerging teleophthalmology networks in Delhi-NCR and Hyderabad expand screening access without specialist density.
Viral Conjunctivitis Pipeline Drugs Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with mechanism-targeted specialists commanding premium positioning against broad-spectrum formulators. The market structure fragments across three tiers: integrated pharmaceutical conglomerates with ophthalmology divisions, mid-cap antiviral specialists, and platform-technology licensors. Dominant competitive moves include adaptive trial designs bridging keratitis and conjunctivitis indications and formulation partnerships with German specialty chemical suppliers.
Within the antiviral specialist tier, NovaBay Pharmaceuticals and Adenovir Pharma AB occupy differentiated positions. NovaBay exemplifies broad-spectrum platform leverage through its auriclosene chemistry, while Adenovir Pharma represents narrow-spectrum mechanism targeting. Novartis AG anchors the integrated conglomerate archetype, spanning corticosteroid and antiviral combination development through internal R&D networks.
| Leading Market Players |
|---|
| Shire Plc |
| NovaBay Pharmaceuticals Inc. |
| Novartis AG |
| Panoptes Pharma GES.M.B.H. |
| NicOx S.A. |
| Adenovir Pharma AB |
| Allergan Plc |
| NanoViricides Inc. |
| IACTA Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
FDA orphan drug designation gates both supply qualification and price differentiation simultaneously, compressing evidentiary requirements for mechanism-targeted candidates while enabling premium positioning against generic corticosteroid substitutes. This regulatory pathway shapes vendor economics across formulation tiers.
Pricing Analysis
United States pricing spreads 40-60% above German and Swiss benchmarks for comparable adenoviral therapeutics, reflecting FDA-accelerated approval premiums and vertically integrated ophthalmology platform procurement power. Three-tier pricing structure across premium orphan-designated, standard broad-spectrum, and economy generic corticosteroid levels stratifies the market. Cost compression in the standard tier intensifies as nanostructured lipid carriers extend patent protection timelines. Community pharmacy buyers exhibit highest price sensitivity, while hospital formulary committees accept orphan drug premiums for sight-threatening indications.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for isotonic buffer raw materials, compressing margins for U.S.-based formulation sponsors dependent on German and Swiss specialty chemical inputs. Supply concentrates in Ludwigshafen and Leverkusen for benzalkonium chloride alternatives, Basel for subconjunctival depot polymers, and San Francisco for pH-buffered aqueous solutions. Raw material dependencies span acyclovir nucleoside analogs, lipid carrier excipients, and preservative-free packaging components. Single-source vulnerability in Swissmedic-authorized manufacturing sites for depot formulations threatens supply security. Distribution runs through vertically integrated ophthalmology group purchasing organizations displacing individual clinic autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ophthalmic virology fellowship-trained investigator availability constrains clinical trial enrollment velocity, creating a bottleneck that favors sponsors with established academic medical center relationships over capital-rich newcomers lacking protocol experience.
For Market Incumbents: Shield formulation leadership through captive supply agreements with Ludwigshafen specialty chemical manufacturers, securing isotonic buffer allocation priority against emerging entrant demand surges. Deepen backward integration into preservative-free packaging production to offset German input cost volatility. FDA serotype coverage guidance shifts threaten narrow-spectrum candidates; broaden mechanism-targeted pipelines through adaptive trial designs bridging keratitis and conjunctivitis indications. For New Entrants and Emerging Players: FDA streamlined orphan drug designation fast-tracks regulatory timelines for adenoviral therapeutics, opening white space in mechanism-specific candidates underserved by broad-spectrum incumbents. Teleophthalmology-enabled home care channels remain underpenetrated relative to clinic-based protocols, offering lower customer acquisition costs for digitally native entrants. Preservative-free formulation gaps in contact lens wearer populations present the most penetrable segment for differentiated positioning against benzalkonium chloride-preserved standards. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across nanostructured lipid carrier platforms as formulation science matures and contract manufacturing capacity expands. Long-term viability over the next decade rests on pipeline diversification across antiviral, anti-inflammatory, and immunomodulatory mechanisms rather than single-molecule concentration. Acquisition target archetype: mid-cap antiviral specialists with EMA centralized pathway experience and existing German chemical supplier relationships. Monitor FDA adenoviral serotype coverage guidance revisions as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Implementation | Bridges keratitis and conjunctivitis indications, reducing per-program capital requirements for sponsors. |
| Preservative-Free Formulation Development | Addresses unmet needs in contact lens wearers and chronic dry eye populations with benzalkonium chloride-free profiles. |
| German Specialty Chemical Partnership | Secures isotonic buffer and lipid carrier supply priority against input concentration in Ludwigshafen and Leverkusen. |
| Teleophthalmology Channel Expansion | Enables community-based screening and referral, reducing specialist visit burden while maintaining protocol adherence. |
| Orphan Drug Designation Pursuit | Compresses FDA evidentiary requirements and accelerates enrollment timelines for adenoviral and herpetic indications. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down pharmaceutical R&D expenditure triangulation anchored market sizing. Primary fieldwork concentrated on U.S. integrated ophthalmology platforms and German specialty chemical manufacturers.
Across the analysis window, forecasts employed treatment line, dosage form, administration route, and regional regulatory cluster segmentation dimensions. CAGRs derived from patent expiry timelines, generic entry assumptions, and orphan drug exclusivity period modeling. Pipeline stage transition probabilities and investigator enrollment capacity constraints shaped probability-adjusted revenue projections.
Underlying assumptions cover FDA serotype coverage guidance stability, EMA centralized pathway continuity, and German-Swiss specialty chemical supply reliability, with deviation risk concentrated in ophthalmic virology fellowship pipeline collapse and generic corticosteroid substitution persistence. Practitioners should keep alternative scenarios live as regulatory evidentiary standards and teleophthalmology reimbursement frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Global Atrial Fibrillation Drugs Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Anti-Inflammatory Drugs Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market