
 Contraceptive Drugs Market | 2026-2036
Contraceptive Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Contraceptive Drugs Market Intelligence
Consolidation of active pharmaceutical ingredient (API) manufacturing for hormonal contraceptives in China and India is realigning the supply chain for finished drug products. Bayer AG leverages its extensive portfolio of combined oral contraceptives to maintain a significant market presence. Meanwhile, Organon Group specializes in long-acting reversible contraceptives (LARCs) like implants. Viatris Inc. competes by offering a broad range of generic contraceptive options.
Contraceptive drugs are pharmaceutical preparations designed to prevent pregnancy through hormonal or non-hormonal mechanisms. These formulations often contain synthetic progestins and estrogens, such as levonorgestrel or ethinylestradiol, to inhibit ovulation, thicken cervical mucus, or alter the uterine lining. Oral pills remain the dominant product type by volume, but injectable and implantable delivery modes are gaining share due to longer efficacy cycles. The intrauterine device segment, particularly hormonal IUDs, commands higher margins and is associated with healthcare provider-led family planning.
Market access is governed by national drug authorities like the US FDA, the European Medicines Agency (EMA), and Japan's PMDA. These bodies enforce stringent clinical trial requirements for safety and efficacy, directly influencing development timelines and costs for new drug approvals. Stakeholders must now decide whether to invest in next-generation non-hormonal options or focus on expanding access to existing long-acting reversible contraceptives.
Market Dynamics
The central structural force shaping the contraceptive drugs market is the geographic consolidation of active pharmaceutical ingredient manufacturing. Heavy reliance on suppliers in China and India for hormonal APIs creates both cost efficiencies and significant supply chain vulnerabilities for finished drug manufacturers.
Growth Catalysts
- Public Health Initiatives:Government-led family planning programs in countries like India and Brazil are expanding access and subsidizing costs for contraceptives, directly stimulating volume demand for affordable oral pills and injectables.
- Formulation Innovation:The development of novel non-hormonal drug candidates and alternative delivery systems, such as transdermal patches, is attracting new user segments who seek to avoid hormonal side effects.
- Expanded OTC Access:Regulatory shifts allowing over-the-counter sales of certain contraceptive pills in markets like the United States and the UK are broadening distribution channels beyond prescription-based models, increasing accessibility.
Market Restraints
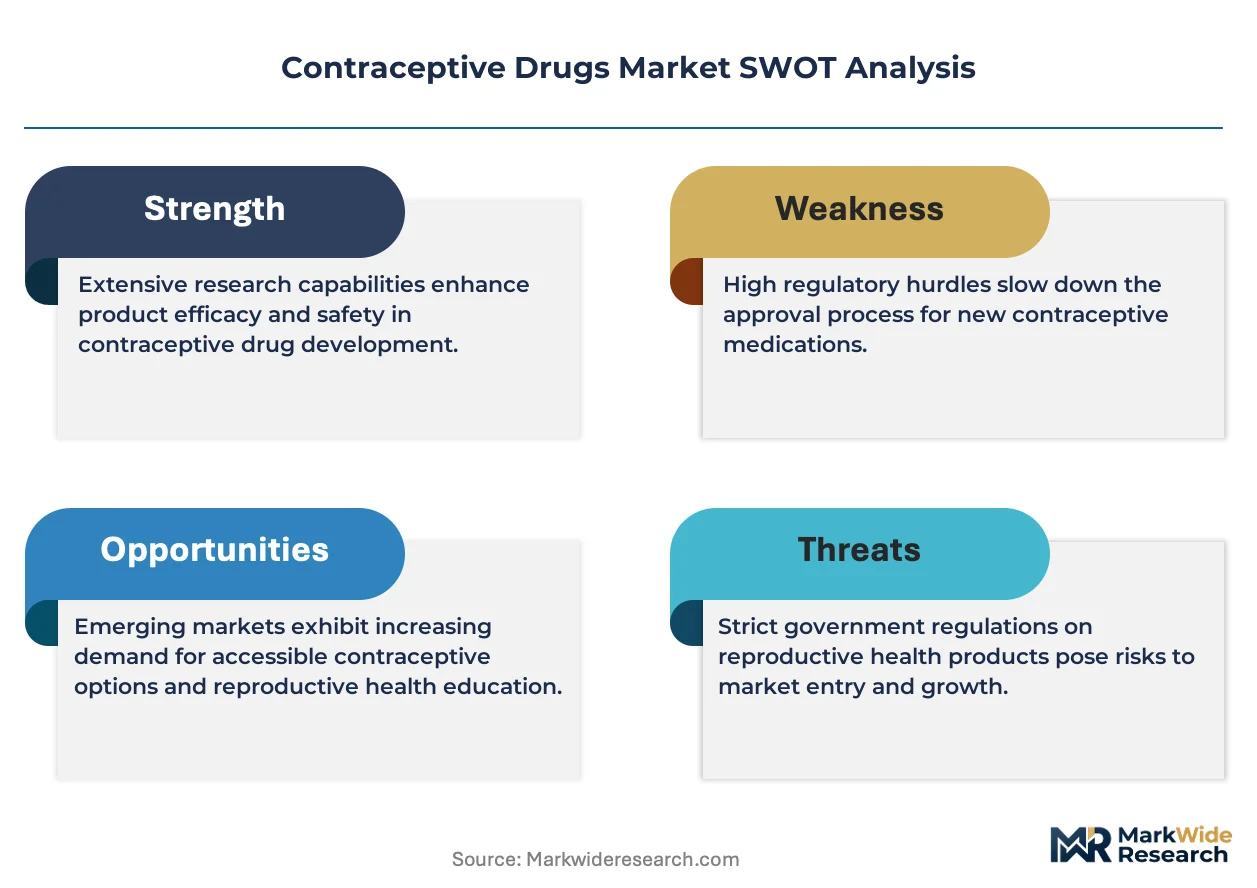
- API Supply Concentration:The high concentration of hormonal API manufacturing in China and India exposes the global supply chain to geopolitical risks, trade policy shifts, and localized production disruptions.
- Stringent Regulatory Hurdles:Extensive and costly clinical trials required by bodies like the US FDA and EMA for new drug approvals create high barriers to entry and lengthen development timelines, particularly for novel mechanisms of action.
- Cultural and Social Barriers:Persistent social stigma, misinformation, and religious opposition to contraception in certain regions limit uptake and create challenges for market education and public health campaigns.
Strategic Opportunities
- Non-Hormonal Male Contraceptives:Developing the first approved non-hormonal, reversible male contraceptive pill represents a significant untapped market, addressing the need for shared responsibility in family planning.
- Telemedicine Integration:Partnering with digital health platforms for remote consultations and electronic prescriptions can streamline access to oral contraceptives and patches, especially in geographically dispersed or underserved areas.
- Underserved Markets in Africa:Focusing on market entry in fast-growing sub-Saharan African nations with supportive public health policies offers substantial volume growth potential for both LARCs and low-cost oral contraceptives.
Industry Challenges
- Managing Cold Chain Logistics:Certain injectable contraceptives require stringent temperature controls during transport and storage, posing a significant logistical and cost challenge, particularly in regions with underdeveloped infrastructure.
- Navigating Patent Cliffs:The looming expiration of patents for several high-revenue branded contraceptives, including certain hormonal IUDs and implants, presents a major challenge of generic erosion for incumbent manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contraceptive Drugs Market |
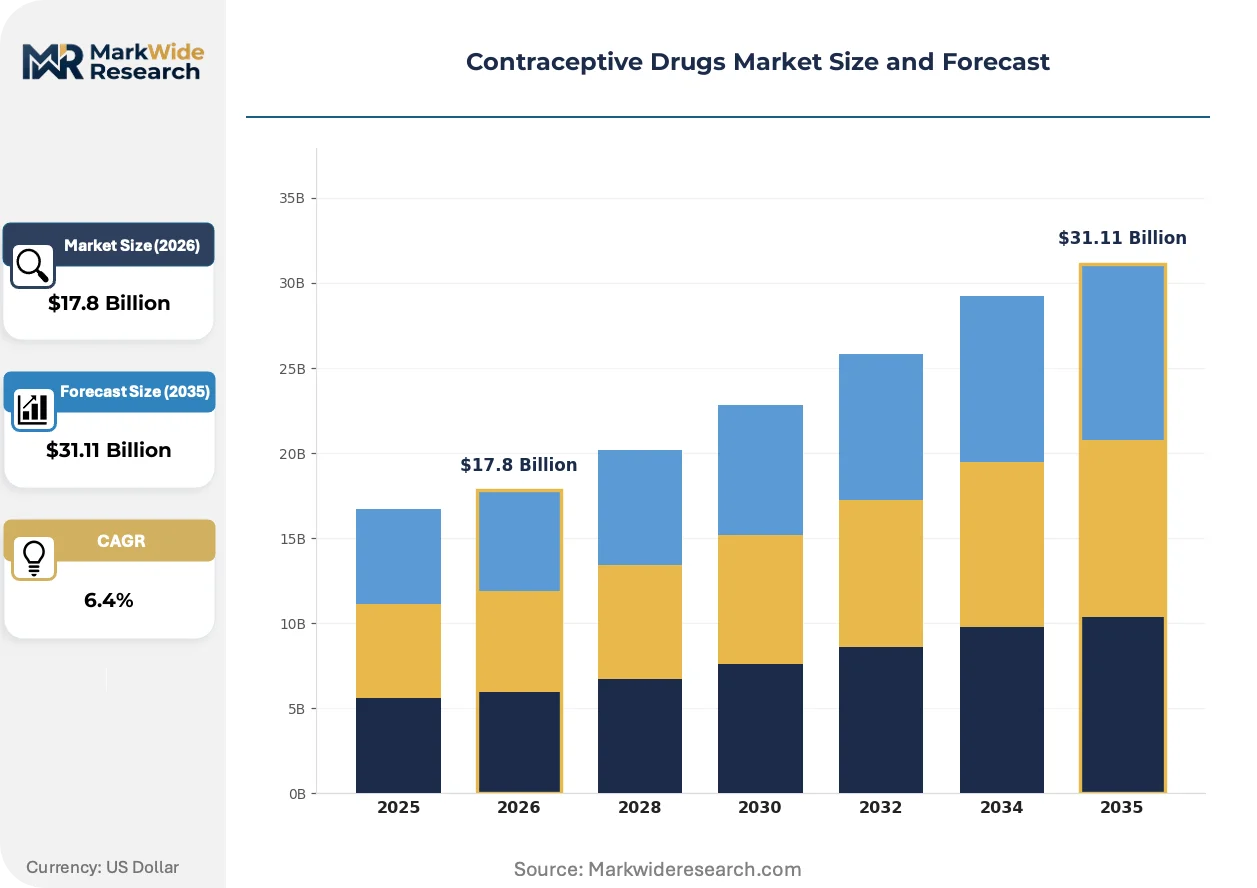
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Injections, Implants, Intrauterine Devices Delivery Mode: Oral, Injectable, Transdermal, Intrauterine End User: Women, Couples, Healthcare Providers, Pharmacies Therapy Area: Family Planning, Menstrual Regulation, Hormonal Disorders, Others |
| Companies Covered | Bayer AG, Pfizer Inc., Johnson & Johnson Services, Inc., AbbVie Inc., Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Novartis AG, Organon Group, Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contraceptive Drugs Market Strategic Shifts & Innovations
A fundamental bifurcation defines the market's evolution, with parallel efforts to expand access for established long-acting technologies while R&D investment pivots toward entirely new non-hormonal platforms. This dual-track progression is reshaping product pipelines and market access strategies.
Non-hormonal drug platforms that target sperm motility or egg-sperm interaction are a primary focus of early-stage research. Adoption is currently centered within academic institutions and specialized biotechnology firms, driven by grants and venture capital. This pursuit of distinct, targeted mechanisms of action is modularizing the scientific approach to contraception, creating alternatives to systemic hormonal intervention.
Regulatory bodies, including the US FDA and UK's MHRA, are reclassifying certain progestin-only pills from prescription-only to over-the-counter (OTC) status. This policy change directly reduces barriers to access by eliminating the need for a physician's appointment for specific products. The oral contraceptive segment is most affected, forcing brand differentiation based on pharmacy shelf presence and consumer marketing rather than solely on prescriber relationships.
A patient preference shift toward "set-and-forget" methods is gaining momentum, favoring convenience and long-term efficacy over daily adherence. This consumer behavior disrupts the traditional, high-volume market for oral pills and channels demand toward provider-administered products like implants and hormonal IUDs. The trend is most visible in developed markets across North America and Europe, where healthcare access facilitates the necessary clinical procedures.
Contraceptive Drugs Market Segmentation
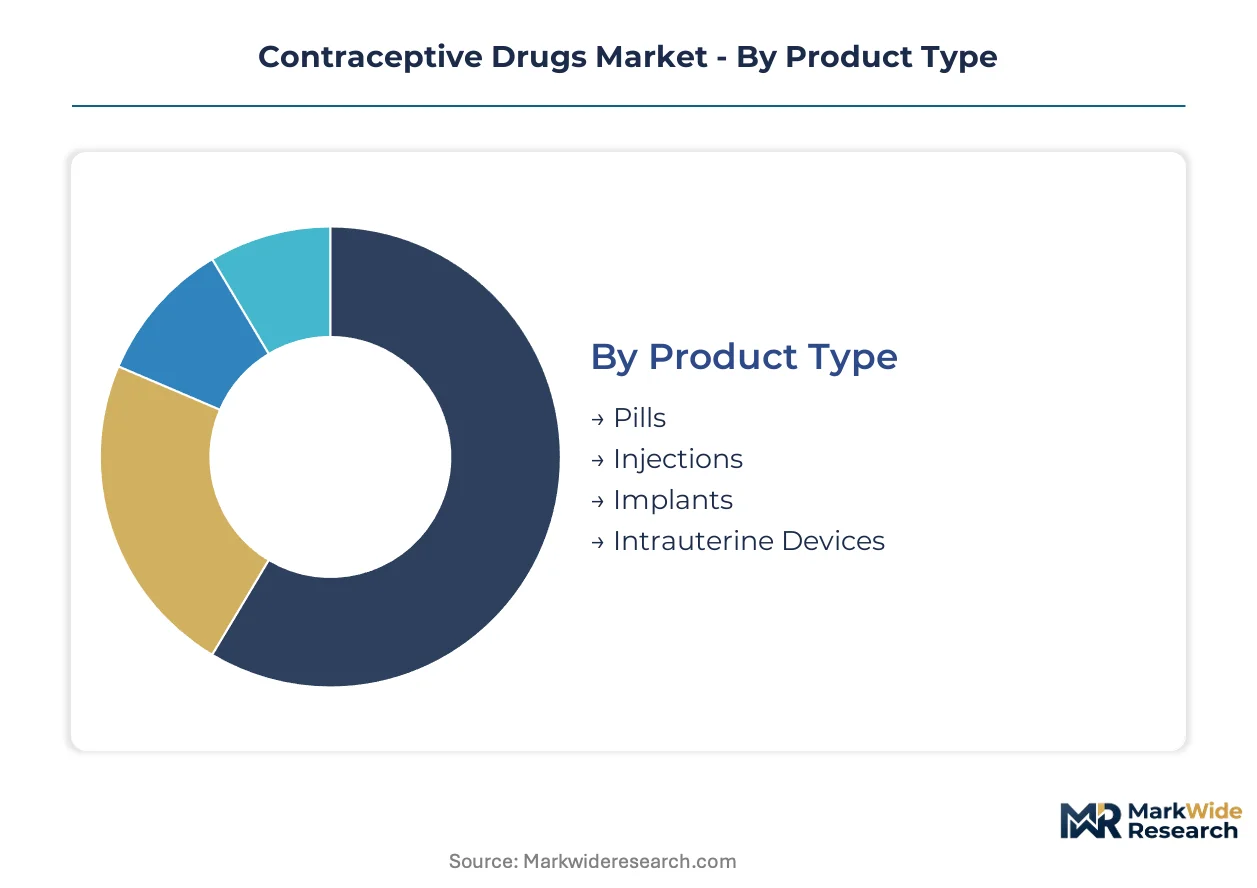
The contraceptive drugs market segmentation provides a granular view of product types, delivery mechanisms, and end-user dynamics. This detailed breakdown helps stakeholders understand where demand concentrates and how innovation influences market shifts. Analyzing these segments is crucial for strategic planning across diverse global regions.
Product Type:
The contraceptive drugs market bifurcates across high-volume, cost-effective options and premium, provider-administered solutions.
- Pills:Oral pills contain synthetic progestins and estrogens, designed to inhibit ovulation or alter cervical mucus. Demand concentrates in India and Brazil due to public health initiatives subsidizing costs for broad access.
- Injections:Injectable contraceptives deliver hormones over several months, offering extended protection. These are often used in public health programs for their convenience.
- Implants:Subdermal implants release hormones for multi-year contraception, providing a "set-and-forget" option.
- Intrauterine Devices:IUDs are small, T-shaped devices inserted into the uterus, offering long-term contraception. These devices command higher margins in developed markets like the United States, driven by healthcare provider-led family planning.
Today's leader: Pills. Tomorrow's challenger: Intrauterine Devices.
Delivery Mode:
Delivery mode preferences are shifting towards convenience and long-term efficacy, influencing product development and user adherence.
- Oral:Oral delivery involves daily pill ingestion, primarily for hormonal contraception. This mode dominates volume in emerging economies where accessibility is paramount.
- Injectable:Injectable delivery provides contraception through periodic injections, often favored for its extended protection.
- Transdermal:Transdermal patches deliver hormones through the skin, appealing to users seeking non-daily administration.
- Intrauterine:Intrauterine delivery involves devices placed in the uterus, offering long-acting reversible contraception. This method is gaining traction in Europe and North America due to patient preference for extended efficacy.
The injectable delivery mode is expanding most quickly in public health programs, while transdermal options target new user segments.
End User:
The end-user segmentation highlights the diverse stakeholders involved in contraceptive access and decision-making.
- Women:Women are the primary users of contraceptive drugs, making informed choices about family planning methods. Demand among women in the United States is influenced by expanding OTC access for certain pill formulations.
- Couples:Couples jointly make family planning decisions, often considering shared responsibility for contraception.
- Healthcare Providers:Healthcare providers administer methods like implants and IUDs, guiding patient selection and ensuring proper usage. Their role is critical in markets like Germany for long-acting reversible contraceptives.
- Pharmacies:Pharmacies serve as distribution points, increasingly offering over-the-counter access to specific contraceptive pills.
Supply concentration for end-users is shifting from primarily healthcare provider-led to include pharmacy-based access.
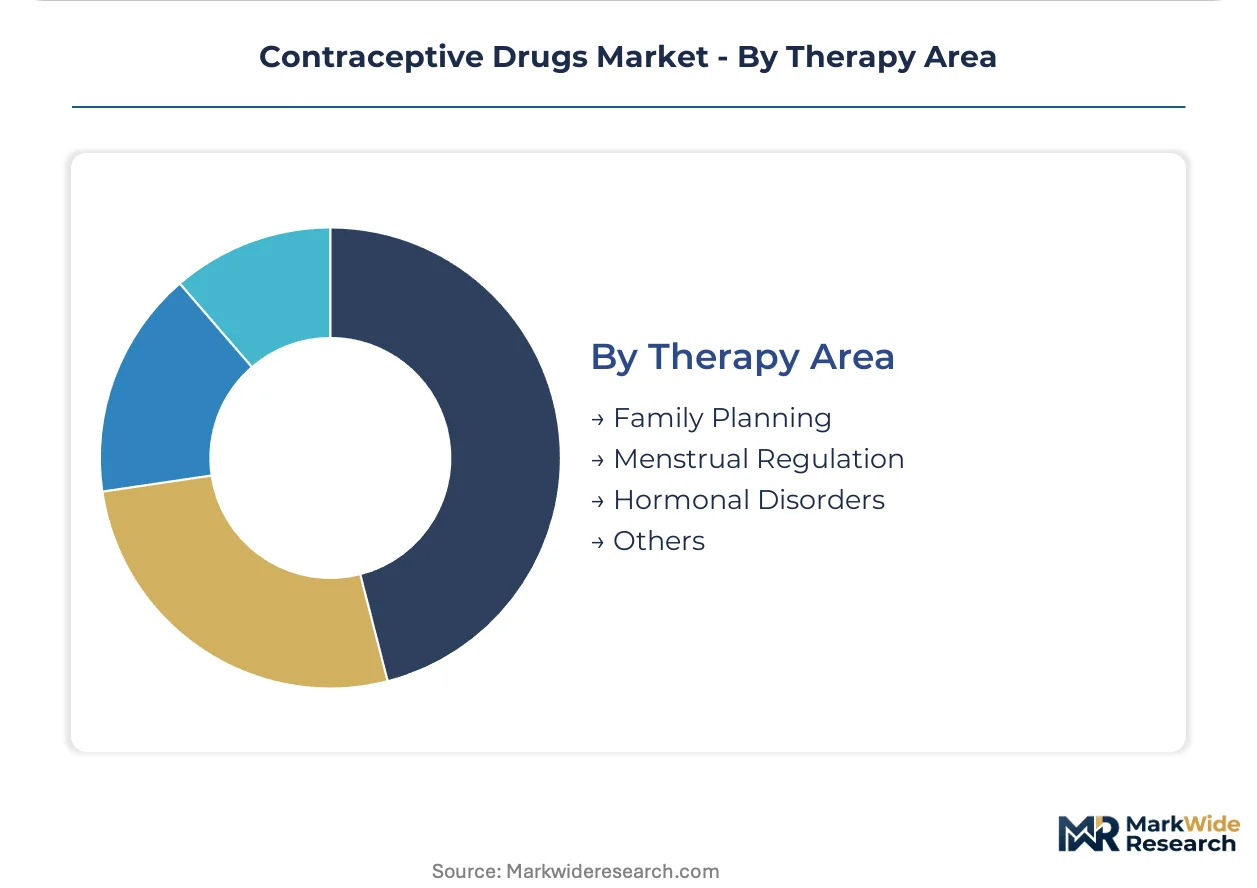
Therapy Area:
Therapy area diversification reveals both the primary use cases and niche applications driving specific product developments.
- Family Planning:Family planning represents the core application for contraceptive drugs, preventing unintended pregnancies. Public health initiatives in Brazil specifically target this area to improve maternal health outcomes.
- Menstrual Regulation:Certain contraceptive formulations help regulate menstrual cycles, addressing issues like heavy bleeding.
- Hormonal Disorders:Contraceptive drugs are also used to manage conditions like polycystic ovary syndrome or endometriosis. This application often involves specialized formulations and prescriber relationships in markets like France.
- Others:This segment includes various ancillary uses where hormonal modulation is beneficial, such as acne treatment.
Family planning remains the most mature therapy area, while hormonal disorders drive innovation in specific drug formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergences and varying cost structures drive strategic manufacturing decisions for contraceptive drugs. This creates an arbitrage opportunity, where production of active pharmaceutical ingredients often shifts to regions with less stringent oversight or lower operational costs. Finished drug product assembly and distribution then adapt to these upstream supply chain realignments.
India
India's demand for affordable contraceptives stems from extensive government-led family planning programs. The CDSCO oversees drug approvals, ensuring product quality and accessibility for a large population base. Hyderabad and Ahmedabad are major pharmaceutical hubs, concentrating API production for global markets.
China
Chinese manufacturers heavily influence the global supply chain, particularly for hormonal contraceptive active pharmaceutical ingredients. The NMPA regulates pharmaceutical manufacturing and export quality, impacting global availability. Shandong and Zhejiang provinces house significant chemical and pharmaceutical manufacturing, serving as critical global API suppliers.
United States
American demand is shaped by a shift towards expanded over-the-counter access for specific oral contraceptives. The US FDA's reclassification of certain pills to OTC status impacts distribution channels. The Northeast Corridor, including New Jersey and Pennsylvania, remains a hub for pharmaceutical R&D and finished product manufacturing.
Germany
German healthcare providers guide patient selection for long-acting reversible contraceptives, driving demand for innovative solutions. The European Medicines Agency (EMA) sets stringent approval standards for new drug formulations, influencing market entry. Cities like Berlin and Munich host significant pharmaceutical research and development, focusing on advanced contraceptive technologies.
Brazil
Brazilian public health initiatives significantly boost demand for affordable oral pills and injectables, making contraception widely accessible. ANVISA regulates drug approvals, supporting national family planning programs and local production efforts. São Paulo and Rio de Janeiro are key areas for pharmaceutical distribution and local production, catering to public health sector needs.
Contraceptive Drugs Market Key Industry Players
Indian and Chinese producers anchor one tier, specializing in high-volume active pharmaceutical ingredient manufacturing; Western pharmaceutical specialists hold positions in finished drug product development. The market exhibits a tiered structure, with large multinational corporations at the premium end and generic manufacturers competing on cost. Key strategic archetypes include R&D-intensive innovators, established portfolio managers, and cost-efficient generic suppliers. Companies pursue portfolio diversification and geographic expansion to secure market share.
Within the established portfolio managers, Bayer AG represents a multinational corporation leveraging an extensive portfolio of combined oral contraceptives. Organon Group exemplifies a specialist focusing on long-acting reversible contraceptives like implants, catering to patient preferences for convenience. Viatris Inc. occupies the generic segment, offering a broad range of cost-effective contraceptive options across various delivery modes. These companies collectively illustrate the diverse strategies employed across the market, from innovation to accessibility. Their global reach and established distribution networks contribute significantly to market stability and product availability across different user demographics.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Organon Group |
| Viatris Inc. |
| Others |
Cost & Logistics Intelligence
Public health initiatives in India and Brazil drive demand for affordable contraceptives, forcing manufacturers to optimize cost structures. Such demand pressure directly influences pricing strategies for high-volume products. This dynamic requires robust supply chain efficiency to maintain accessibility.
Pricing Analysis
Distributor margins for generic oral contraceptives remain compressed due to high volume demand from public health programs. The dominant pricing structure is contract-based long-term offtake for government tenders, alongside per-unit transactional sales for pharmacy channels. Price differentiation drivers include regulatory approval status (e.g., US FDA vs. local standards) and brand premium for innovative long-acting reversible contraceptives. Pricing pressure stems from generic competition and government subsidies for essential medicines. Public health programs in Brazil and India are highly price-sensitive, seeking low-cost oral pills and injectables, while developed market consumers for hormonal IUDs show less price sensitivity.
Supply Chain Analysis
Regional distribution centers form a hub-and-spoke pattern for finished contraceptive drug products. China and India concentrate hormonal active pharmaceutical ingredient (API) manufacturing, drawing from a global base of chemical precursors. Key raw material dependencies include synthetic progestins and estrogens like levonorgestrel or ethinylestradiol. Single-source vulnerability from geopolitical risks in China and India represents a significant supply chain risk. Distribution runs through a network reaching pharmacies and healthcare providers, with cold chain logistics posing a challenge for certain injectable contraceptives in regions with underdeveloped infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contraceptive drugs market functions as a stable compounder, driven by consistent global demand for family planning solutions. Public health initiatives and expanding access models provide a resilient growth foundation.
For Market Incumbents:Acquire non-hormonal drug pipelines from specialized biotechnology firms to counter generic erosion. Established portfolio managers like Bayer AG must invest in novel mechanisms of action to diversify beyond patent-expiring combined oral contraceptives. This strategy addresses the threat of patient preference shifts towards "set-and-forget" methods. Incumbents can also strengthen channel control by partnering with digital health platforms for remote consultations and electronic prescriptions.
For New Entrants and Emerging Players:Non-hormonal drug platforms targeting sperm motility represent a technology-first wedge for new entrants. Specialized biotechnology firms can focus on underserved segments seeking alternatives to systemic hormonal intervention. The most penetrable segment is reversible male contraception, offering significant market potential. Go-to-market strategies should emphasize clinical differentiation and patient education on novel mechanisms, leveraging direct-to-consumer models where regulatory shifts allow.
For Investors and Strategic Acquirers:Asymmetric upside sits with early-stage biotechnology firms developing non-hormonal contraceptive solutions. These companies offer long-term viability over a five to ten-year window, driven by unmet medical needs and patient preference shifts. Investors should target R&D-intensive innovators with strong intellectual property in novel drug candidates. The signal to watch is successful Phase II clinical trial data for non-hormonal male or female contraceptives, indicating future market disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expediting Phase III trials for non-hormonal options validates novel mechanisms for patient safety. |
| Regulatory Approval Pathway | Navigating US FDA and EMA reclassification for OTC access expands distribution channels. |
| Licensing Agreement | Securing rights to promising non-hormonal compounds diversifies product portfolios for incumbents. |
| Manufacturing Scale-Up | Increasing API production capacity in diversified geographies reduces supply chain vulnerabilities. |
| Pipeline Diversification | Investing in LARCs and specialized formulations addresses evolving patient preferences and market demand. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and internal databases — were reconciled for this analysis. Industry stakeholders included pharmaceutical R&D directors, regulatory affairs specialists, public health officials, and pharmacy chain procurement managers. Secondary data sources encompassed US FDA filings, EMA submissions, and national health statistics from Brazil and India. Bottom-up and top-down triangulation validated volume and value projections.
Historical market performance cross-referenced against expert panel input established the forecast framework. Segmentation dimensions modeled included product type, delivery mode, end-user, and therapy area, alongside regional regulatory clusters. Compound annual growth rates were derived from a multi-factor analysis considering regulatory changes and public health spending across the modeling period. Key forecast inputs included global population growth and women's healthcare access trends.
The model holds under current regulatory frameworks and public health funding levels; deviation in geopolitical stability or API supply chain disruptions would shift projections. Forecasts reflect assumptions regarding long-term family planning demand and technological innovation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Warts Therapeutics Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
South Africa Diabetes Drugs Market
Pharmaceuticals
Global Pharmaceutical Gelatin Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Bladder Cancer Treatment Drugs Market