
 Global Human Rabies Vaccine Market | 2026-2036
Global Human Rabies Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human Rabies Vaccine Market Foresight
Public procurement channels across endemic regions is reconfiguring how manufacturers secure volume commitments. Sanofi leverages its established cold-chain infrastructure to sustain tender participation in African and Southeast Asian markets. Serum Institute of India Pvt. Ltd anchors supply for government immunization programs through cost-competitive purified Vero cell output. Bharat Biotech International Limited differentiates via recombinant platform investments that position it for next-generation prequalification.
Human rabies vaccines are sterile immunobiological preparations derived from inactivated rabies virus propagated in cell substrates or embryonated eggs, formulated to induce neutralizing antibody titers exceeding 0.5 IU/mL as measured by the rapid fluorescent focus inhibition test. These products serve the primary commercial purpose of preventing fatal encephalitis following suspected rabies virus exposure, with manufacturing requiring biosafety level-3 containment and viral inactivation validation. Purified Vero cell vaccines command the dominant volume position due to established safety profiles and WHO prequalification prevalence, while recombinant platforms represent the fastest-growing technology segment as manufacturers seek elimination of residual neural tissue risks. Post-exposure prophylaxis dosing schedules generate the majority of revenue pools given the urgency-driven clinical decision-making that limits price sensitivity in acute care settings.
FDA lot-release protocols, WHO prequalification standards, and India's CDSCO manufacturing licensing collectively shape market access through divergent purity and potency benchmarks that regional suppliers must simultaneously satisfy. The EU's EMA centralised marketing authorisation and REACH-derived residual host-cell DNA limits add compliance layers for European-bound exports. Stakeholders must monitor evolving NMPA pathway harmonisation in China and emerging real-world evidence requirements from national immunization technical advisory groups as procurement criteria shift toward total cost of immunization rather than per-dose pricing.
Market Dynamics
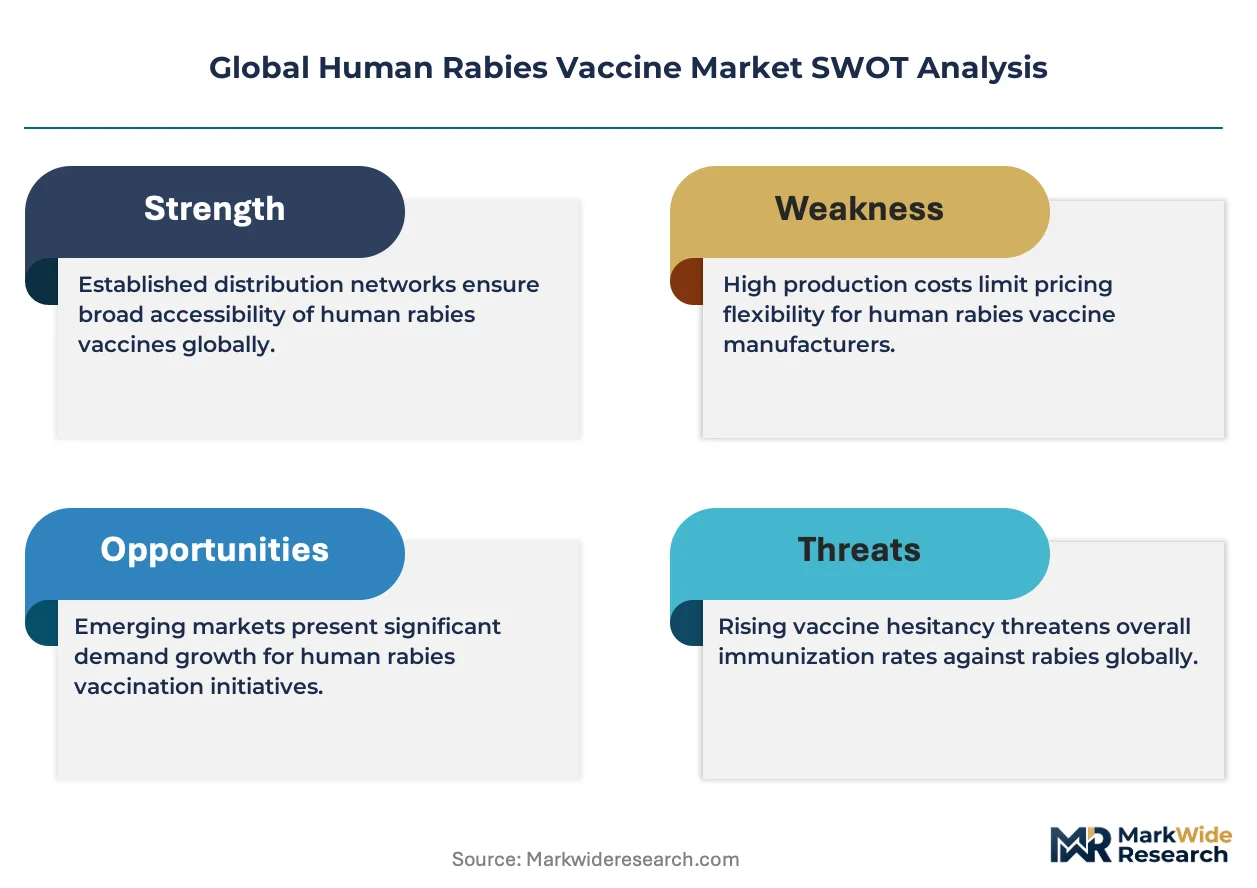
WHO prequalification standards and China's NMPA pathway reforms are compressing manufacturing compliance timelines, forcing purification technology upgrades across Vero cell and recombinant production lines while public procurement volumes concentrate in rural veterinary clinics across endemic regions.
Growth Catalysts
- Post-exposure prophylaxis urgency:Acute care settings in India, Brazil, and Nigeria drive procurement volumes where clinical decision-making limits price sensitivity during suspected rabies virus exposure incidents.
- WHO prequalification expansion:Manufacturing compliance with international potency benchmarks unlocks tender participation across African and Southeast Asian immunization programs.
- Recombinant platform maturation:Elimination of residual neural tissue risks through recombinant technologies accelerates regulatory approval timelines for next-generation vaccine candidates.
Market Restraints
- Biosafety level-3 containment costs:Viral inactivation validation and specialized facility requirements impose capital intensity that limits new entrant participation in purified Vero cell manufacturing.
- Cold-chain infrastructure gaps:Last-mile distribution failures in rural veterinary clinics across Nigeria and rural India degrade vaccine potency and create coverage inequities.
- Divergent regulatory benchmarks:Simultaneous compliance with FDA lot-release protocols, EMA REACH-derived residual host-cell DNA limits, and CDSCO licensing creates friction for multi-territory suppliers.
Strategic Opportunities
- Pre-exposure prophylaxis expansion:Veterinary workers and laboratory personnel in high-risk occupations across Brazil present underpenetrated demand pools beyond acute post-exposure settings.
- Real-world evidence integration:National immunization technical advisory groups in India and Nigeria are incorporating total cost of immunization metrics into procurement criteria, favoring suppliers with pharmacoeconomic data packages.
- Single-dose regimen development:Immunogenicity research converging with intradermal delivery technologies promises schedule compression that reduces programmatic costs for government buyers.
Industry Challenges
- Skilled biosafety technician scarcity:BSL-3 facility operation and viral inactivation protocol validation require specialized training pipelines that lag manufacturing expansion in emerging supply regions.
- Prequalification timeline compression:WHO dossier review and site inspection backlogs extend time-to-market for recombinant platform submissions, delaying revenue recognition for platform investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Rabies Vaccine Market |
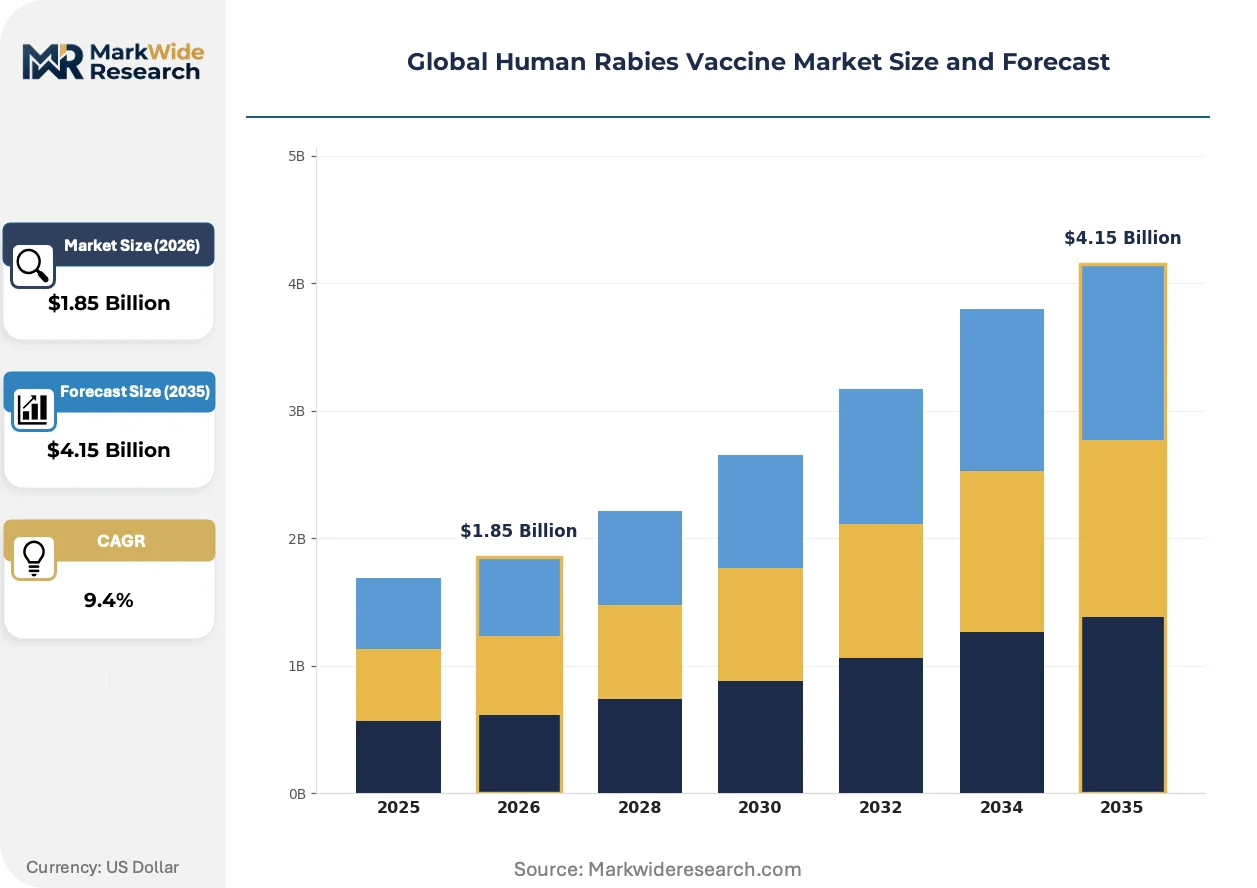
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Cell Culture, Embryonated Egg, Purified Vero Cell, Neural Tissue, Recombinant, Inactivated Dosing Schedule: Pre-Exposure Prophylaxis, Post-Exposure Prophylaxis, Single Dose, Multiple Dose, Booster Dose End User: Public Health Departments, Travel Clinics, Research Laboratories, Veterinary Services, Military Health Agencies Distribution Channel: Hospital Pharmacies, Government Vaccination Programs, Retail Pharmacies, Online Pharmacies, NGO Campaigns |
| Companies Covered | Sanofi, GlaxoSmithKline plc, Merck & Co., Inc., Serum Institute of India Pvt. Ltd, Bharat Biotech International Limited, Novartis AG, Cadila Pharmaceuticals, Boehringer Ingelheim International GmbH, Zoetis Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Rabies Vaccine Market Shifts & Advancements
Manufacturing technology convergence and procurement metric evolution are restructuring competitive advantage around purification efficiency and pharmacoeconomic evidence rather than per-dose pricing alone.
Recombinant glycoprotein expression systems are rendering obsolete the residual risk profiles of neural tissue-derived vaccines that dominated historical production. Government immunization programs in India and Brazil are accelerating adoption timelines for these platforms. The structural consequence is compression of prequalification windows for legacy inactivated virus manufacturers.
China's NMPA pathway harmonization with WHO prequalification standards is eliminating redundant stability testing requirements for export-bound production. Domestic manufacturers gain accelerated access to African tender markets previously requiring separate dossier submissions. Vero cell vaccine suppliers with existing WHO listings face competitive pressure from NMPA-registered competitors in Southeast Asian procurement.
Bulk purchasing consortia across West African health systems are consolidating procurement authority away from fragmented clinic-level ordering. National central medical stores in Nigeria and regional vaccine security mechanisms are displacing distributor-mediated spot purchasing. This concentration is most visible in post-exposure prophylaxis programs where volume commitments now precede manufacturing scheduling.
Global Human Rabies Vaccine Market Segmentation
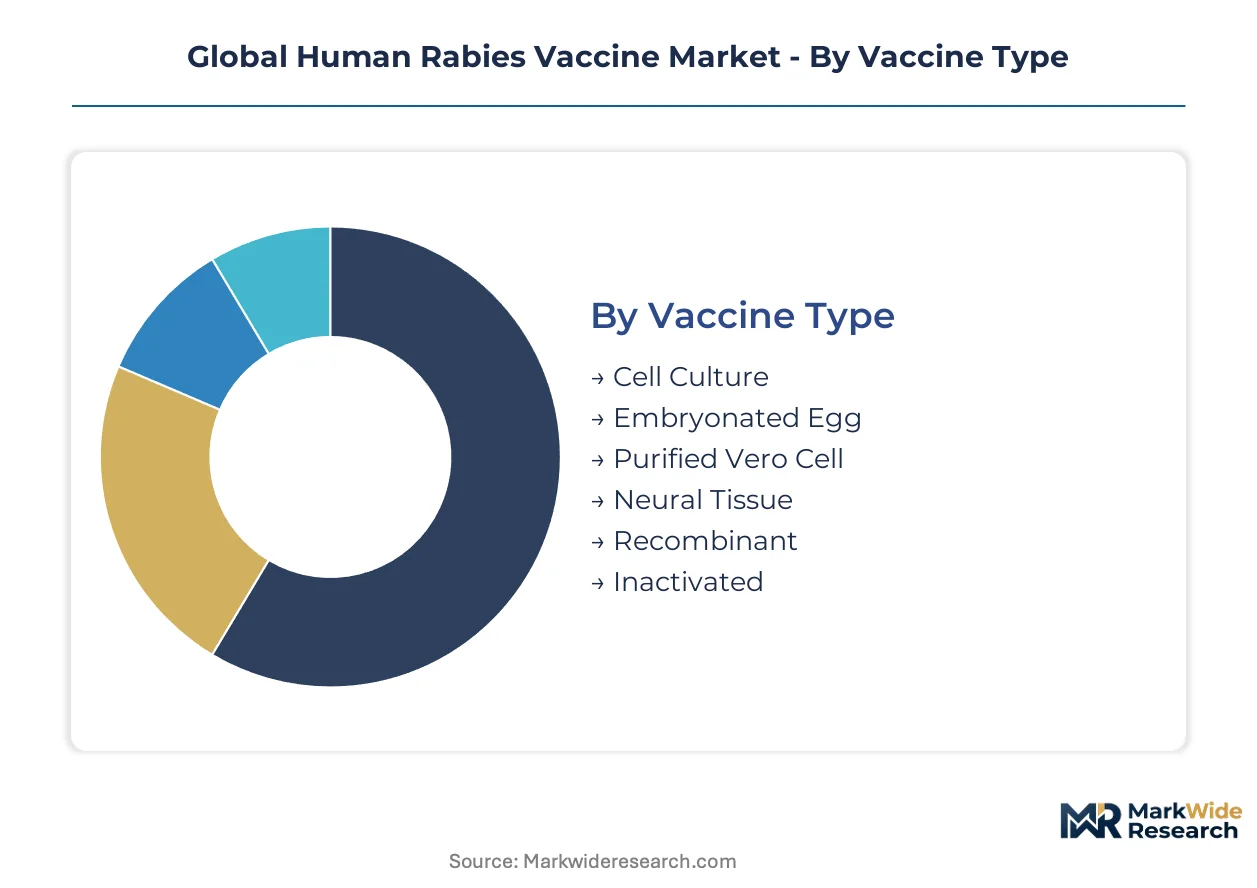
Segmentation reveals how procurement authority, clinical urgency, and manufacturing technology intersect to shape competitive positioning across the human rabies vaccine value chain. Understanding these dimensions exposes where margin pools concentrate and which technology transitions threaten incumbent suppliers.
Vaccine Type:
Mature purification platforms anchor current supply volumes while emerging recombinant technologies redefine safety benchmarks and regulatory pathways.
- Purified Vero Cell:Inactivated rabies virus propagated in Vero cell substrates with chromatography-based purification achieves WHO prequalification prevalence unmatched by alternatives. Demand concentrates in Indian and Nigerian government immunization programs where established cold-chain compatibility and decades of safety data override price sensitivity in post-exposure emergency procurement.
- Recombinant:Glycoprotein expression systems eliminate residual neural tissue risks entirely, accelerating regulatory approval timelines for next-generation candidates. Brazil's ANVISA and India's CDSCO are prioritizing these platforms in tender evaluations as pharmacovigilance databases mature.
- Cell Culture:Broad category encompassing various mammalian substrate systems with divergent purification requirements.
- Embryonated Egg:Historical production method with declining commercial relevance due to allergy profiles and manufacturing complexity.
- Neural Tissue:Obsolete technology retained only in limited geographies with restricted regulatory oversight.
- Inactivated:General classification referring to viral inactivation methodology rather than substrate specificity.
Purified Vero Cell retains volume leadership; Recombinant holds the steepest expansion curve.
Dosing Schedule:
Clinical urgency tiers separate emergency response protocols from preventive occupational health programs, creating divergent pricing power and procurement cadences.
- Post-Exposure Prophylaxis:Multi-dose intramuscular or intradermal regimens administered following suspected rabies virus exposure generate the majority of revenue pools. Acute care decision-making in Brazilian public hospitals and Indian district medical centers limits price negotiation leverage during encephalitis risk windows.
- Pre-Exposure Prophylaxis:Three-dose priming schedules for veterinary workers, laboratory personnel, and travelers to endemic regions present underpenetrated demand. Military Health Agencies in Nigeria and professional veterinary associations across Brazil are expanding procurement volumes as occupational safety regulations tighten.
- Single Dose:Investigational schedule compression enabled by intradermal delivery technologies and adjuvant advances.
- Multiple Dose:Standard Essen or Zagreb regimens requiring four to five clinic visits.
- Booster Dose:Maintenance immunization for persistently exposed occupational cohorts with documented antibody decay.
Post-Exposure Prophylaxis commands procurement priority; Pre-Exposure Prophylaxis is expanding most quickly as occupational coverage mandates proliferate.
End User:
Institutional buyer types exhibit divergent technical specifications, budget cycles, and evidence requirements that fragment supplier engagement models.
- Public Health Departments:Central medical stores and national immunization programs in India, Nigeria, and Brazil aggregate volume through tender mechanisms. Total cost of immunization metrics are displacing per-dose pricing as procurement criteria as real-world evidence requirements from national immunization technical advisory groups harden.
- Veterinary Services:Rural clinic networks and veterinary public health divisions represent the fastest-growing demand segment. Post-exposure prophylaxis programs scaling through veterinary channels in Nigeria and India's Maharashtra state are reconfiguring last-mile distribution requirements.
- Travel Clinics:Private pre-exposure services for international travelers with premium pricing tolerance.
- Research Laboratories:BSL-3 facility workers requiring documented seroconversion and occupational health compliance.
- Military Health Agencies:Standardized force protection protocols with centralized procurement and stockpiling mandates.
Public Health Departments retain volume leadership; Veterinary Services holds the steepest expansion curve.
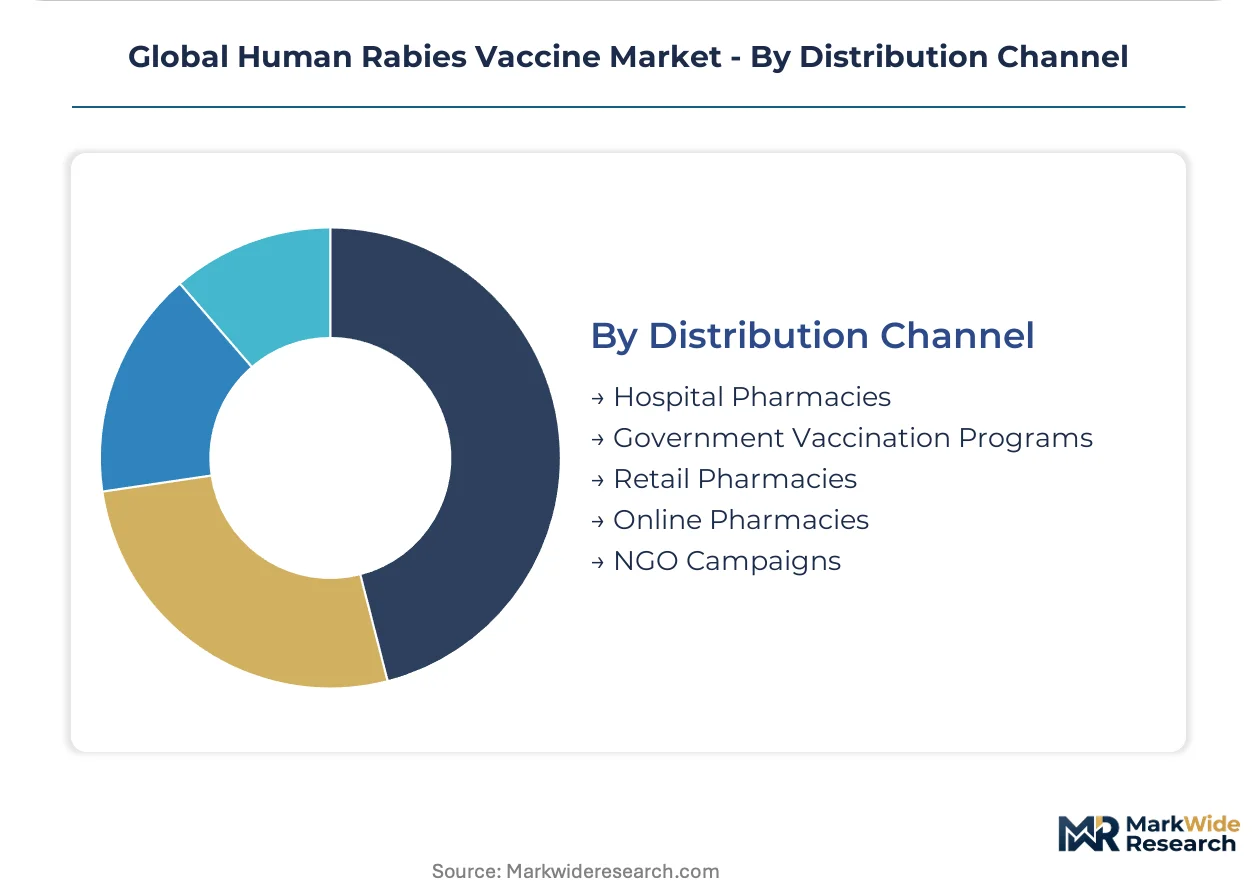
Distribution Channel:
Channel structure determines cold-chain integrity exposure and procurement concentration, with government consolidation displacing fragmented retail and NGO intermediation.
- Government Vaccination Programs:National central medical stores and regional vaccine security mechanisms in West Africa and Southeast Asia are consolidating procurement authority. Bulk purchasing consortia across Nigerian health systems now precede manufacturing scheduling with multi-year volume commitments.
- Hospital Pharmacies:Acute care settings in Brazilian tertiary hospitals and Indian district medical centers maintain emergency stockpiles. Post-exposure urgency limits substitution risk and sustains premium positioning for WHO-prequalified suppliers.
- NGO Campaigns:Gavi-funded initiatives and bilateral health programs with targeted endemic region coverage.
- Retail Pharmacies:Limited private market access for travel and occupational health segments in urban centers.
- Online Pharmacies:Emerging channel with cold-chain verification challenges restricting vaccine categories.
Government Vaccination Programs retain volume leadership; Hospital Pharmacies hold the steepest expansion curve as emergency procurement protocols formalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-exposure prophylaxis programs in India, Brazil, and Nigeria are scaling procurement volumes through government immunization channels. WHO prequalification standards and China's NMPA pathway reforms are tightening manufacturing compliance across export-bound production lines.
India
District medical centers in Maharashtra and Uttar Pradesh are expanding cold-chain storage for emergency rabies vaccination stockpiles. CDSCO manufacturing licensing requirements are forcing purification technology upgrades among domestic suppliers. The Pune-Ahmedabad pharmaceutical corridor anchors Vero cell vaccine production for government tender participation.
Brazil
ANVISA is accelerating regulatory approval timelines for recombinant platform candidates in public hospital procurement. Occupational safety mandates for veterinary workers in São Paulo and Minas Gerais are expanding pre-exposure prophylaxis coverage. The São Paulo metropolitan health system is consolidating emergency vaccine purchasing through centralized medical stores.
Nigeria
Rural veterinary clinics in Kano and Lagos states are becoming primary distribution nodes for post-exposure programs. The national central medical store is displacing fragmented clinic-level ordering through bulk purchasing consortia. Northern Nigeria's vaccine security mechanisms are formalizing multi-year volume commitments with prequalified suppliers.
China
NMPA pathway harmonization with WHO standards is eliminating redundant stability testing for export-bound rabies vaccine production. Domestic manufacturers are gaining accelerated access to African tender markets previously requiring separate dossier submissions. The Yangtze River Delta biopharmaceutical cluster is scaling recombinant platform investments for next-generation prequalification.
United States
FDA lot-release protocols are shaping potency benchmarks for travel clinic and occupational health procurement. Military Health Agencies are standardizing force protection protocols with centralized stockpiling mandates for laboratory personnel. The Boston-Washington corridor's BSL-3 research facilities are driving documented seroconversion requirements for captive supply agreements.
Global Human Rabies Vaccine Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with established WHO prequalification and cold-chain infrastructure. Purified Vero cell production anchors current volume leadership while recombinant platform investments define competitive differentiation. Three archetypes dominate: multinational biopharmaceuticals with integrated global distribution, Indian cost-competitive purified cell manufacturers, and recombinant platform specialists targeting next-generation regulatory pathways. Capacity expansion and strategic partnerships with government immunization programs represent the dominant competitive moves.
Within the multinational tier, Sanofi and GlaxoSmithKline plc exemplify established cold-chain operators sustaining tender participation across African and Southeast Asian markets. Among Indian manufacturers, Serum Institute of India Pvt. Ltd and Bharat Biotech International Limited occupy positions as cost-competitive suppliers for government programs, with the latter representing recombinant platform investment archetypes. These named entities anchor industry-level commentary on manufacturing compliance and procurement channel access without implying specific strategic actions or market positions beyond their archetype representation.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Serum Institute of India Pvt. Ltd |
| Bharat Biotech International Limited |
| Novartis AG |
| Cadila Pharmaceuticals |
| Boehringer Ingelheim International GmbH |
| Zoetis Inc. |
| Others |
Supply & Pricing Matrix
Single-source dependency on Indian Vero cell substrate suppliers compresses margin buffers across WHO-prequalified manufacturers while simultaneously widening spreads between emergency procurement premiums and tender contract rates. This concentration dynamic forces buyers into multi-year volume commitments that lock in supply security against spot market volatility.
Pricing Analysis
Certification level (WHO-prequalified versus domestic-only) creates the primary spread between emergency hospital procurement and government tender pricing. Three-tier pricing structure across premium cold-chain-guaranteed, standard temperature-monitored, and economy bulk-contract tiers reflects divergent potency assurance investments. Pricing pressure stems from CDSCO licensing upgrades forcing chromatography purification retrofits among second-tier domestic suppliers. Veterinary services in rural Nigeria exhibit highest price sensitivity due to fragmented clinic budgets, while Brazilian tertiary hospitals maintain lowest sensitivity given acute encephalitis risk windows.
Supply Chain Analysis
Tariff exposure between China and African tender markets dominates supply chain risk calculations for export-bound manufacturers. Production gravity centers on India, China, and Brazil, with Vero cell substrate and chromatography resin dependencies drawing from specialized biopharmaceutical chemical suppliers. Single-source vulnerability in BSL-3 facility certification creates chokepoints for new capacity activation. Distribution runs through national central medical stores consolidating procurement authority away from clinic-level spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through West African bulk purchasing consortia and Indian state-level tender consolidation, fragmenting supplier negotiation leverage across fragmented rural clinic networks previously accessible through distributor intermediation.
For Market Incumbents: Harden cold-chain infrastructure ownership against emerging recombinant platform entrants by securing captive Vero cell substrate supply through backward integration into bioreactor media production. Accelerate WHO prequalification maintenance investments to defend tender participation slots as NMPA-registered Chinese manufacturers gain African market access. For New Entrants and Emerging Players: Northern Nigeria's veterinary clinic network presents underpenetrated distribution capacity for intradermal delivery technologies promising schedule compression. Target occupational pre-exposure prophylaxis in Brazilian agricultural regions where ANVISA fast-track pathways favor recombinant platform submissions over legacy inactivated virus dossiers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors recombinant platform specialists with CDSCO or NMPA registration momentum over purified Vero cell incumbents facing purification upgrade capex cycles. Long-term viability rests on pharmacoeconomic evidence generation capabilities for national immunization technical advisory group engagement. Monitor WHO prequalification inspection backlog resolution as inflection signal for recombinant platform revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Maintenance | Sustains tender eligibility across African and Southeast Asian government immunization programs. |
| Recombinant Platform Scale-Up | Positions manufacturers for ANVISA and CDSCO fast-track pathways eliminating neural tissue risks. |
| Cold-Chain Infrastructure Expansion | Secures last-mile potency assurance for rural veterinary clinic networks in Nigeria and India. |
| Intradermal Delivery Technology Licensing | Enables single-dose regimen development reducing programmatic costs for government buyers. |
| Bulk Purchasing Consortium Participation | Locks multi-year volume commitments from West African national central medical stores. |
Research Methodology
Operator-level perspectives from regulatory affairs leads at CDSCO and ANVISA, hospital procurement managers at Brazilian tertiary facilities, and veterinary public health directors in Nigerian state ministries anchored the qualitative base. These primary engagements combined with secondary validation from WHO prequalification dossier databases, FDA lot-release protocols, and Gavi procurement disclosure records. Bottom-up manufacturing capacity assessments and top-down government immunization program budget allocations were triangulated to establish volume baselines.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated pre-exposure prophylaxis penetration assumptions over the projection horizon. Segmentation dimensions modeled include vaccine type technology platform, dosing schedule urgency tier, end-user institutional category, and regional regulatory cluster. CAGRs were derived from compound growth trajectory analysis incorporating procurement volume commitments, prequalification timeline probabilities, and cold-chain infrastructure deployment rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by NMPA-registered Chinese manufacturers or recombinant platform specialists would shift outcomes through accelerated tender market share capture. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Immunosuppressive Drugs Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Minocycline Hydrochloride Market