
 Sinus Therapeutic Drugs Market | 2026-2036
Sinus Therapeutic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Sinus Therapeutic Drugs Market Analytics
Hospital procurement is rotating toward outpatient and homecare channels as payors push for reduced readmission costs. Pfizer Inc. leverages its manufacturing scale to supply broad-spectrum antibiotic portfolios across institutional and retail channels. Novartis AG anchors its position through specialized delivery formats in nasal corticosteroids. Sun Pharmaceutical Industries Ltd. competes on cost-optimized oral tablet formulations for emerging markets.
Sinus therapeutic drugs comprise pharmaceutical agents formulated to reduce mucosal inflammation, restore nasal patency, or eradicate bacterial infection in the paranasal sinuses, typically administered via nasal spray, oral tablet, or inhalation routes with bioavailability parameters tailored to local or systemic action. These products serve to alleviate symptomatic burden in rhinosinusitis and allergic rhinitis while preventing progression to chronic or complicated disease states. Nasal corticosteroids dominate value generation due to superior efficacy in mucosal control and extended prescription cycles. Antihistamines occupy a mature volume position in allergic rhinitis management with thinning margin pools from generic saturation. Homecare delivery through patient-directed nasal spray administration represents the fastest-expanding channel as reimbursement shifts favor site-of-care migration.
The FDA governs NDA and ANDA approvals for intranasal formulations with bioequivalence standards that shape generic entry timelines, while the EPA regulates chlorofluorocarbon propellant phase-out in metered-dose inhalation devices. EMA's MDR and REACH frameworks in Europe impose additional toxicity and environmental compliance burdens on excipient selection and device materials. Stakeholders must monitor evolving bioequivalence guidance for complex nasal products and calibrate portfolio investments between innovator delivery platforms and commodity oral generics.
Market Dynamics
The FDA's streamlined ANDA pathway for complex nasal generics is compressing exclusivity windows for innovator delivery platforms while accelerating competitive entry timelines.
Growth Catalysts
- Site-of-care migration:Payers in the United States are redirecting reimbursement toward homecare settings, expanding patient-directed nasal spray administration and reducing institutional overhead.
- REACH compliance differentiation:European manufacturers investing in excipient toxicity screening and sustainable propellant alternatives capture preferential formulary positioning under ECHA frameworks.
- Chronic sinusitis prevalence:Diagnostic expansion in tertiary care networks drives sustained prescription cycling for maintenance corticosteroid regimens.
Market Restraints
- API supply concentration:Fluticasone propionate and mometasone furoate active pharmaceutical ingredients concentrate among Indian and Chinese contract manufacturers, exposing formulators to tariff and logistics volatility.
- Bioequivalence complexity:The FDA's evolving guidance on nasal spray deposition patterns and particle size distribution prolongs ANDA approval timelines for complex generics, delaying cost-driven substitution.
- Oral antibiotic substitution:Primary care prescribers in cost-constrained markets default to amoxicillin-clavulanate tablets for acute bacterial rhinosinusitis, bypassing topical delivery premiums.
Strategic Opportunities
- Underpenetrated Indian outpatient channels:CDSCO's accelerated approval pathways for locally manufactured nasal corticosteroids enable first-mover positioning in tier-two and tier-three cities.
- Digital pharmacy integration:Direct-to-patient subscription models for chronic rhinitis maintenance therapy bypass traditional wholesale distribution markups.
- Propellant technology convergence:Hydrofluoroalkane-free dry powder inhalation platforms align with EPA phase-out mandates while offering patent-protected differentiation.
Industry Challenges
- Device engineering talent scarcity:Nasal spray pump mechanism design and plume geometry optimization require specialized competencies concentrated among European and North American contract development organizations.
- Legacy ERP integration friction:Serialization and track-and-trace mandates under the Drug Supply Chain Security Act force mid-tier manufacturers to reconfigure warehouse management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sinus Therapeutic Drugs Market |
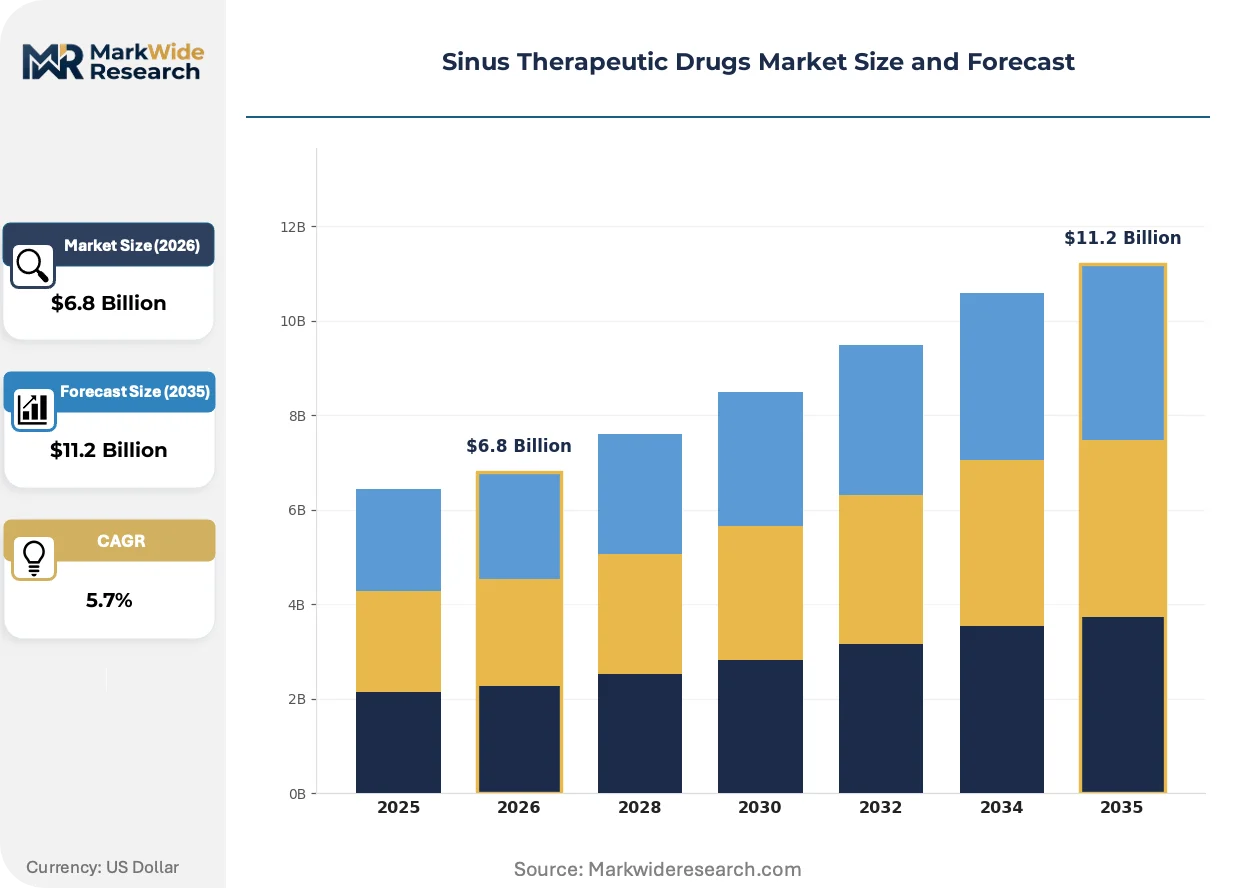
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decongestants, Antihistamines, Nasal Corticosteroids, Antibiotics Delivery Mode: Nasal Spray, Oral Tablet, Liquid, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Allergic Rhinitis, Acute Sinusitis, Chronic Sinusitis, Non-allergic Rhinitis |
| Companies Covered | Novartis AG, Pfizer Inc., Sanofi, GlaxoSmithKline plc, AstraZeneca plc, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Dr. Reddy’s Laboratories Ltd., Janssen Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sinus Therapeutic Drugs Market Evolving Landscape
Delivery platform innovation and regulatory stringency are restructuring competitive advantage around bioequivalence demonstration and environmental compliance rather than molecule exclusivity alone.
Novel nanosuspension formulations with enhanced mucosal retention properties are displacing conventional aqueous nasal sprays in severe chronic rhinosinusitis cases. Academic medical centers and specialty ENT clinics in Germany and the United States are piloting these platforms for post-surgical maintenance. The technology is displacing standard corticosteroid suspensions in refractory patient segments where mucosal penetration limits therapeutic response.
EMA's Medical Device Regulation (MDR) reclassification of certain drug-device combination nasal products is forcing manufacturers to submit clinical evidence on pump reproducibility and patient handling errors. European notified bodies are extending review timelines for legacy products lacking human factors validation. Smaller portfolio holders are withdrawing marginal SKUs rather than absorbing MDR compliance costs, concentrating shelf presence among scaled operators.
Hospital procurement committees are unbundling device selection from pharmaceutical contracting, enabling materials management departments to negotiate pump mechanisms independently of drug substance agreements. This fragmentation is disrupting traditional single-source bundling strategies employed by integrated manufacturers. The pattern is most pronounced in United States integrated delivery networks where GPO leverage extends to device standardization across affiliated ambulatory surgery centers.
Sinus Therapeutic Drugs Market Segmentation
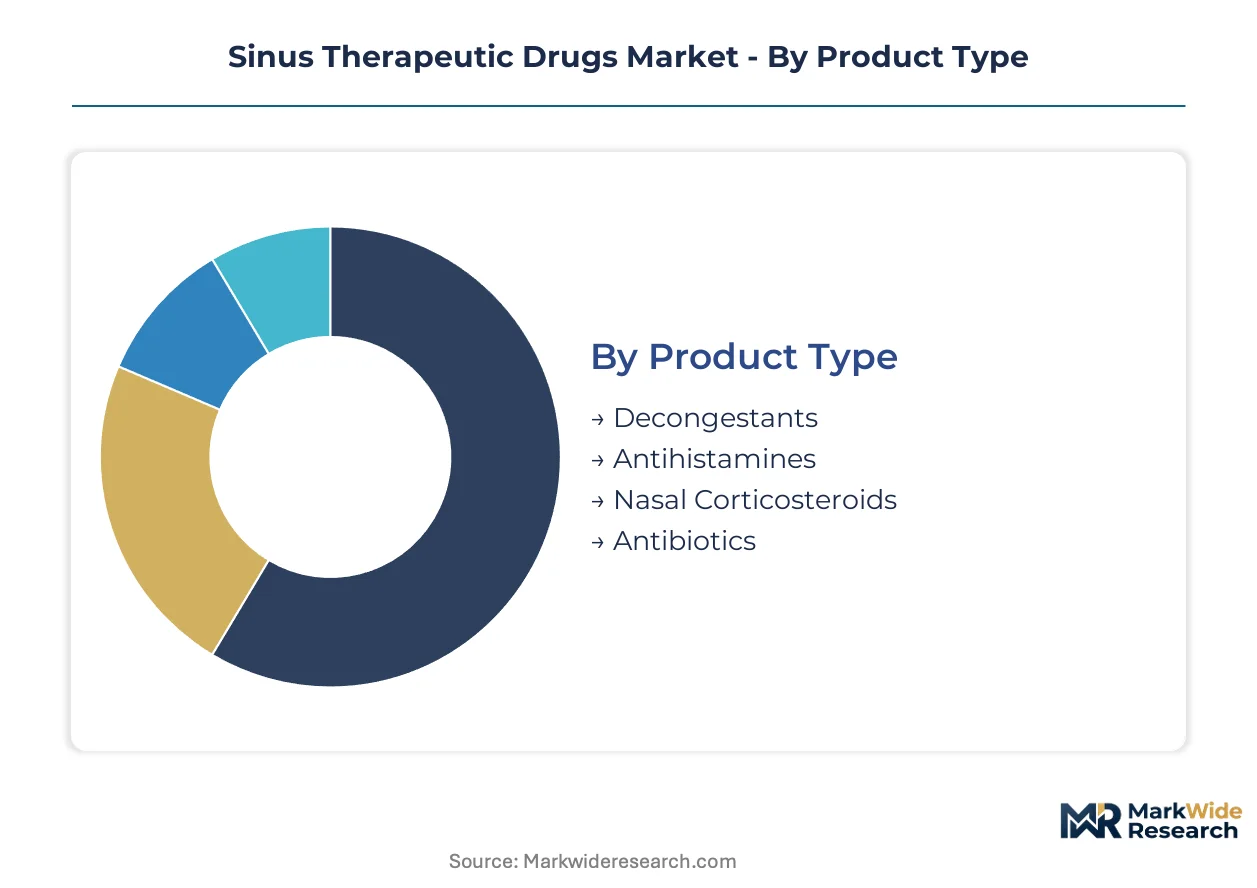
Segmentation in sinus therapeutics reveals where formulation complexity protects margins and where commodity pressures erode returns. Understanding these fault lines guides portfolio allocation between defendable delivery platforms and volume oral generics.
Product Type:
Substitution pressure varies sharply across this category, with oral generics facing the steepest commoditization while intranasal platforms retain pricing power through bioequivalence barriers.
- Nasal Corticosteroids:Synthetic glucocorticoid suspensions delivered via metered-dose pumps achieve direct mucosal deposition with minimal systemic absorption. Demand concentrates in United States integrated delivery networks where maintenance prescribing for chronic rhinosinusitis supports extended prescription cycles and formulary premium positioning.
- Antibiotics:Topical and systemic formulations target acute bacterial rhinosinusitis, with amoxicillin-clavulanate tablets dominating primary care prescribing. Indian and Chinese API manufacturers supply concentrated active pharmaceutical ingredient volumes, exposing finished dose formulators to tariff volatility and logistics disruption.
- Antihistamines:H1-receptor antagonists in oral and intranasal forms manage allergic rhinitis symptoms through competitive histamine blockade.
- Decongestants:Alpha-adrenergic agonists provide short-term nasal patency restoration through vasoconstriction of nasal mucosal vasculature.
Nasal Corticosteroids anchor the volume base while antibiotics gain share at the steepest rate through acute infection management protocols.
Delivery Mode:
Cost tier stratification separates premium device-dependent formats from commodity oral administration, with reimbursement differentials widening between institutional and homecare channels.
- Nasal Spray:Pump-actuated aqueous or suspension formulations deliver precise particle size distributions for optimal turbinate deposition. United States payor migration toward site-of-care reduction accelerates patient-directed administration, expanding retail pharmacy fulfillment and subscription-based replenishment models.
- Oral Tablet:Compressed solid dosage forms offer systemic bioavailability for antibiotics and antihistamines with established pharmacokinetic profiles. Emerging market procurement favors these formats for cost-optimized national essential medicine lists, compressing margin pools through competitive tendering.
- Liquid:Pediatric and geriatric formulations provide dose flexibility for patients with swallowing difficulties or weight-based titration requirements.
- Inhalation:Dry powder and metered-dose platforms extend delivery to posterior nasal and paranasal spaces through patient-controlled inspiratory flow.
Oral tablets anchor the volume base through universal prescribing familiarity while nasal spray platforms climb the fastest on homecare reimbursement tailwinds.
End User:
Customer type determines procurement leverage, with consolidated hospital systems extracting volume discounts while fragmented homecare channels sustain premium pricing.
- Homecare:Patient-directed administration of maintenance nasal corticosteroid regimens eliminates institutional overhead and reduces readmission exposure. United States Medicare Advantage plans increasingly mandate step-down to home-based therapy after acute episode stabilization, redirecting pharmaceutical spend toward retail and mail-order channels.
- Hospitals:Inpatient and emergency department settings manage acute bacterial rhinosinusitis with intravenous antibiotics and surgical intervention for complicated cases. Group purchasing organization consolidation enables device standardization across affiliated ambulatory surgery centers, fragmenting traditional single-source bundling arrangements.
- Clinics:Outpatient ENT and allergy specialist practices bridge acute intervention and chronic maintenance prescribing.
- Pharmacies:Community and digital dispensing nodes fulfill patient-initiated and prescriber-directed therapy with varying formulary tier placement.
Hospitals anchor the volume base through acute episode management while homecare segments expand most quickly on site-of-care migration incentives.
Therapy Area:
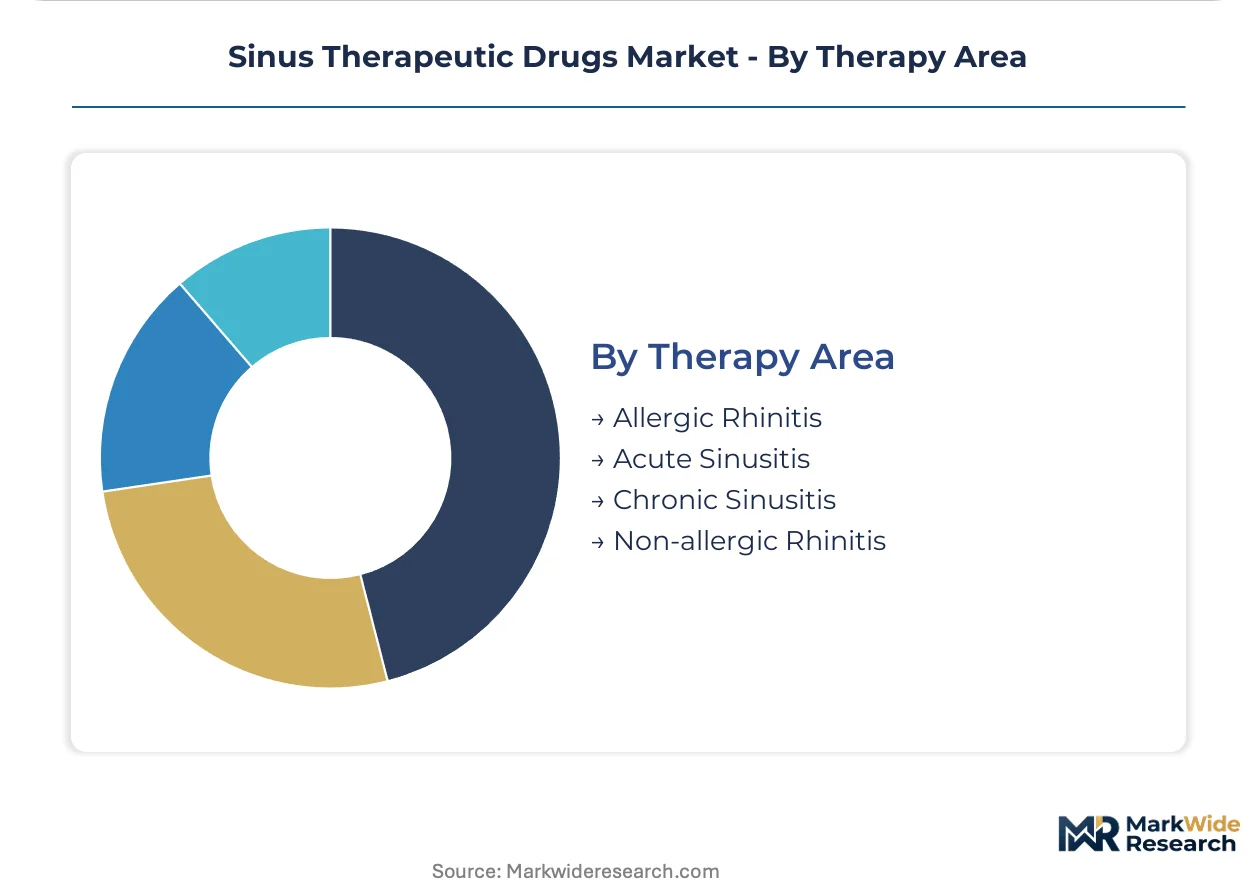
Maturity gradients separate well-established allergic indications from underdiagnosed chronic conditions, with diagnostic expansion driving prescription cycling in latter segments.
- Chronic Sinusitis:Persistent mucosal inflammation exceeding twelve weeks requires maintenance corticosteroid therapy and intermittent antibiotic courses. Tertiary care network diagnostic expansion in Germany and United States academic medical centers sustains prescription cycling for refractory cases requiring specialist referral.
- Allergic Rhinitis:IgE-mediated nasal mucosal response to environmental allergens represents the most prevalent indication with established treatment algorithms. Seasonal and perennial forms drive predictable demand patterns with generic saturation compressing antihistamine margins.
- Acute Sinusitis:Viral or bacterial infection of paranasal sinuses with duration under four weeks dominates primary care prescribing volumes.
- Non-allergic Rhinitis:Vasomotor, gustatory, and occupational triggers generate symptoms without IgE sensitization, often misdiagnosed or undertreated.
Allergic rhinitis anchors the volume base through population prevalence while chronic sinusitis gains share fastest on diagnostic coding expansion and maintenance therapy protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical distribution infrastructure anchors European supply chain resilience for nasal corticosteroid distribution, while direct rail links from Indian API manufacturing clusters to Mumbai's air cargo terminals compress export lead times for contract manufacturers.
United States
Medicare Advantage step-down protocols redirect chronic sinusitis maintenance therapy toward patient-directed homecare administration, expanding retail pharmacy fulfillment volumes. FDA's streamlined ANDA pathway for complex nasal generics accelerates competitive entry timelines for fluticasone propionate formulations. The Philadelphia-Camden pharmaceutical corridor concentrates metered-dose pump engineering talent among specialized contract development organizations serving innovator delivery platforms.
Germany
Academic medical center diagnostic coding expansion for chronic rhinosinusitis sustains prescription cycling for maintenance corticosteroid regimens in tertiary care networks. EMA's MDR reclassification of drug-device combination nasal products extends review timelines for legacy pump mechanisms lacking human factors validation. The Rhine-Main biotechnology cluster around Frankfurt hosts specialized excipient toxicity screening laboratories supporting REACH compliance differentiation.
India
Tier-two and tier-three city outpatient channel expansion creates first-mover positioning opportunities for locally manufactured nasal corticosteroids under CDSCO accelerated approval pathways. DGFT export incentive schemes for pharmaceutical finished dosage forms reduce logistics cost burdens on API-to-formulation integrated manufacturers. The Hyderabad-Visakhapatnam corridor concentrates fluticasone propionate and mometasone furoate active pharmaceutical ingredient production among contract manufacturers supplying global formulators.
China
NMPA priority review pathways for innovative nasal delivery platforms attract multinational licensing agreements for locally developed dry powder inhalation technologies. Dual carbon goals accelerate hydrofluoroalkane propellant phase-out timelines, forcing device engineering investments in sustainable alternatives. The Yangtze River Delta pharmaceutical manufacturing belt around Shanghai hosts concentrated nasal spray pump assembly operations serving both domestic and export markets.
Japan
PMDA's stringent bioequivalence standards for nasal spray deposition patterns prolong generic substitution timelines, protecting innovator pricing power in maintenance therapy segments. METI's pharmaceutical industry revitalization subsidies support domestic manufacturing retention for complex drug-device combinations. The Kansai region around Osaka maintains specialized plastics molding capabilities for precision nasal spray pump mechanism production.
Sinus Therapeutic Drugs Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and delivery platform sophistication. The vendor base stratifies into three tiers: integrated multinationals with device-drug bundling capabilities, mid-cap generic houses with API backward integration, and specialized contract manufacturers with pump engineering competencies. Strategic moves concentrate on M&A for device technology access and capacity expansion in Indian API manufacturing corridors.
Within the integrated multinational tier, Novartis AG and Pfizer Inc. occupy positions exemplifying divergent competitive approaches to delivery platform protection versus manufacturing scale leverage. Sun Pharmaceutical Industries Ltd. anchors the mid-cap generic archetype with concentrated API supply relationships. These three entities collectively illustrate the market's structural tension between innovator delivery differentiation and cost-optimized volume competition.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Sanofi |
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Janssen Pharmaceuticals Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Indian API manufacturers and multinational formulators lock in fluticasone propionate supply access while anchoring price visibility against tariff volatility. These contracts concentrate procurement leverage among scaled operators with backward-integrated manufacturing footprints.
Pricing Analysis
Volume-discount tiering structures separate hospital GPO procurement from retail pharmacy fulfillment. Three-tier pricing stratifies across innovator nasal corticosteroids, authorized generics, and commodity oral antibiotics. Price differentiation hinges on bioequivalence certification complexity and pump mechanism patent protection. Cost compression in oral generic tiers intensifies as Indian manufacturers expand amoxicillin-clavulanate capacity. Retail pharmacy channels exhibit highest price sensitivity due to direct patient co-pay exposure.
Supply Chain Analysis
Strategic stockpiling of mometasone furoate API prevails among European formulators buffering against Indian monsoon logistics disruptions. Active pharmaceutical ingredient production concentrates in India, China, and Italy. Finished dose manufacturing draws from hydrofluoroalkane propellants, precision pump mechanisms, and excipient toxicity screening services. Single-source vulnerability concentrates in nasal spray pump engineering talent pools. Distribution runs through Rotterdam's pharmaceutical hub for European markets and Mumbai's air cargo terminals for Asian export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device-drug combination platforms are restructuring competitive advantage around interoperability with digital pharmacy infrastructure and patient adherence monitoring systems.
For Market Incumbents: Consolidate pump engineering capabilities through captive supply agreements with European contract development organizations. Deepen backward integration into fluticasone propionate API production within Indian manufacturing corridors. FDA's evolving bioequivalence guidance on nasal spray deposition patterns threatens innovator exclusivity windows. For New Entrants and Emerging Players: Lead with digital pharmacy subscription models for chronic rhinitis maintenance therapy in United States Medicare Advantage networks. Target tier-two Indian outpatient channels where CDSCO accelerated approval pathways reduce entry timelines. Pursue white-space positioning in dry powder inhalation platforms aligned with EPA hydrofluoroalkane phase-out mandates. For Investors and Strategic Acquirers: Specialized contract manufacturers with MDR-compliant pump mechanism portfolios represent the highest-conviction acquisition archetype. Long-term viability frames around five-to-ten year regulatory compliance differentiation rather than molecule exclusivity alone. Monitor EMA notified body review timeline extensions for legacy drug-device combinations as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Accelerated Approval Pathway | Compresses entry timelines for locally manufactured nasal corticosteroids in Indian tier-two cities. |
| REACH Compliance Differentiation | Captures preferential formulary positioning under ECHA frameworks for sustainable propellant alternatives. |
| Digital Pharmacy Integration | Bypasses traditional wholesale distribution markups through direct-to-patient subscription models. |
| MDR Human Factors Validation | Extends review timelines for legacy pump mechanisms, concentrating shelf presence among scaled operators. |
| API Backward Integration | Reduces tariff exposure from concentrated Indian and Chinese contract manufacturing dependencies. |
Research Methodology
Cross-validation between formulary database audits and FDA ANDA filing records anchors the qualitative findings on competitive entry timelines. Primary interviews with regulatory affairs leads, hospital procurement managers, ENT specialists, and payer access specialists combine with secondary analysis of EMA MDR submissions, ClinicalTrials.gov records, CMS Medicare reimbursement data, and Indian DGFT export statistics. Bottom-up prescription volume modeling triangulates against top-down pharmaceutical spending forecasts.
Sensitivity analysis across bioequivalence approval scenario variants and API tariff rate assumptions tests forecast robustness. The analytical framework segments by product type, delivery mode, end user, and therapy area across the projection horizon. CAGRs derive from patient population epidemiology, prescription cycling rates, and reimbursement policy trajectory. Modeled inputs include chronic sinusitis diagnostic coding expansion rates and site-of-care migration incentives.
The analysis sits within stated boundaries; outcomes outside FDA guidance stability or sustained Indian API export flow would require recalibration. Forecasts reflect assumptions on reimbursement policy continuity and propellant phase-out adherence timelines. Revision becomes warranted when MDR compliance cost thresholds trigger portfolio withdrawals among mid-tier manufacturers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Latin America Generic Injectables Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Omega 3 Prescription Drugs Market