
 Peptic Ulcer Market | 2026-2036
Peptic Ulcer Market Size, Share, and Industry Trends Forecast 2026-2036
Peptic Ulcer Market Intelligence
Patient adherence and monitoring programs are broadening the scope of therapeutic offerings beyond the pill. AstraZeneca leverages its extensive clinical data and established brand presence in the proton pump inhibitor class. Takeda Pharmaceutical differentiates through its development of novel compounds for specific gastrointestinal conditions. Pfizer sustains its market share through a diverse portfolio of antibiotics used in eradication therapies.
Peptic ulcer disease involves the formation of open sores on the inner lining of the stomach and the upper portion of the small intestine. These lesions primarily result from infection with Helicobacter pylori bacteria or the long-term use of nonsteroidal anti-inflammatory drugs. Proton Pump Inhibitors command the largest share of the product landscape due to their efficacy in reducing stomach acid. Treatment strategies within the therapy area segment are tailored specifically for either gastric ulcers or the more common duodenal ulcers.
Drug approval pathways are governed by stringent clinical trial requirements set by bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA). In Japan, the Pharmaceuticals and Medical Devices Agency (PMDA) sets standards for new drug applications, influencing market entry. Future treatment success depends on developing therapies that can overcome increasing antibiotic resistance in H. pylori infections.
Market Dynamics
The increasing prevalence of antibiotic-resistant Helicobacter pylori strains is the central structural force shaping the peptic ulcer market. This challenge compels a shift from established eradication therapies toward novel combination treatments and advanced diagnostics to improve patient outcomes.
Growth Catalysts
- Hospital Treatment Protocols:Standardized hospital guidelines increasingly mandate combination therapies, particularly for H. pylori eradication, which expands the use of multiple drug classes per patient and supports market growth.
- Aging Demographics in Japan:Japan's rapidly aging population, with higher long-term use of NSAIDs and significant H. pylori prevalence, creates a concentrated source of demand for advanced ulcer treatments and preventative care.
- Advanced Diagnostic Tools:The development of more accurate and non-invasive diagnostic tests, such as urea breath tests and stool antigen tests, facilitates earlier detection, leading to increased treatment initiation rates.
Market Restraints
- Generic Drug Erosion:The patent expiration of blockbuster Proton Pump Inhibitors (PPIs) has led to widespread generic competition, constraining revenue growth for branded drug manufacturers and shifting market value.
- Limited Novel Antibiotic Pipeline:The scientific and economic hurdles in developing new antibiotics effective against multi-drug resistant H. pylori strains limit the introduction of breakthrough therapies to address the most pressing clinical need.
- Stringent Regulatory Pathways:The high cost and long duration of clinical trials required by the FDA, EMA, and PMDA for new gastrointestinal drugs create significant barriers to market entry for smaller innovators.
Strategic Opportunities
- Emerging Asian Markets:Untapped markets in Southeast Asia with high H. pylori prevalence and rising healthcare expenditure present significant expansion opportunities for established therapies and diagnostic services.
- Microbiome-Modulating Therapies:Research into gut microbiome health opens avenues for developing probiotics or other modulators as adjuncts or alternatives to traditional antibiotic-based ulcer treatments, creating a new product category.
- Digital Adherence Programs:Developing digital health platforms to monitor patient adherence to complex H. pylori eradication regimens offers a new value-added service beyond the drug itself, improving treatment efficacy.
Industry Challenges
- Patient Treatment Compliance:Ensuring patient adherence to multi-drug, multi-day eradication therapies remains a significant operational hurdle, directly impacting treatment success rates and contributing to the spread of resistance.
- Diagnostic Lag in Primary Care:The logistical complexity of implementing susceptibility testing for H. pylori in routine clinical practice creates a delay between diagnosis and the prescription of effective, targeted antibiotics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptic Ulcer Market |
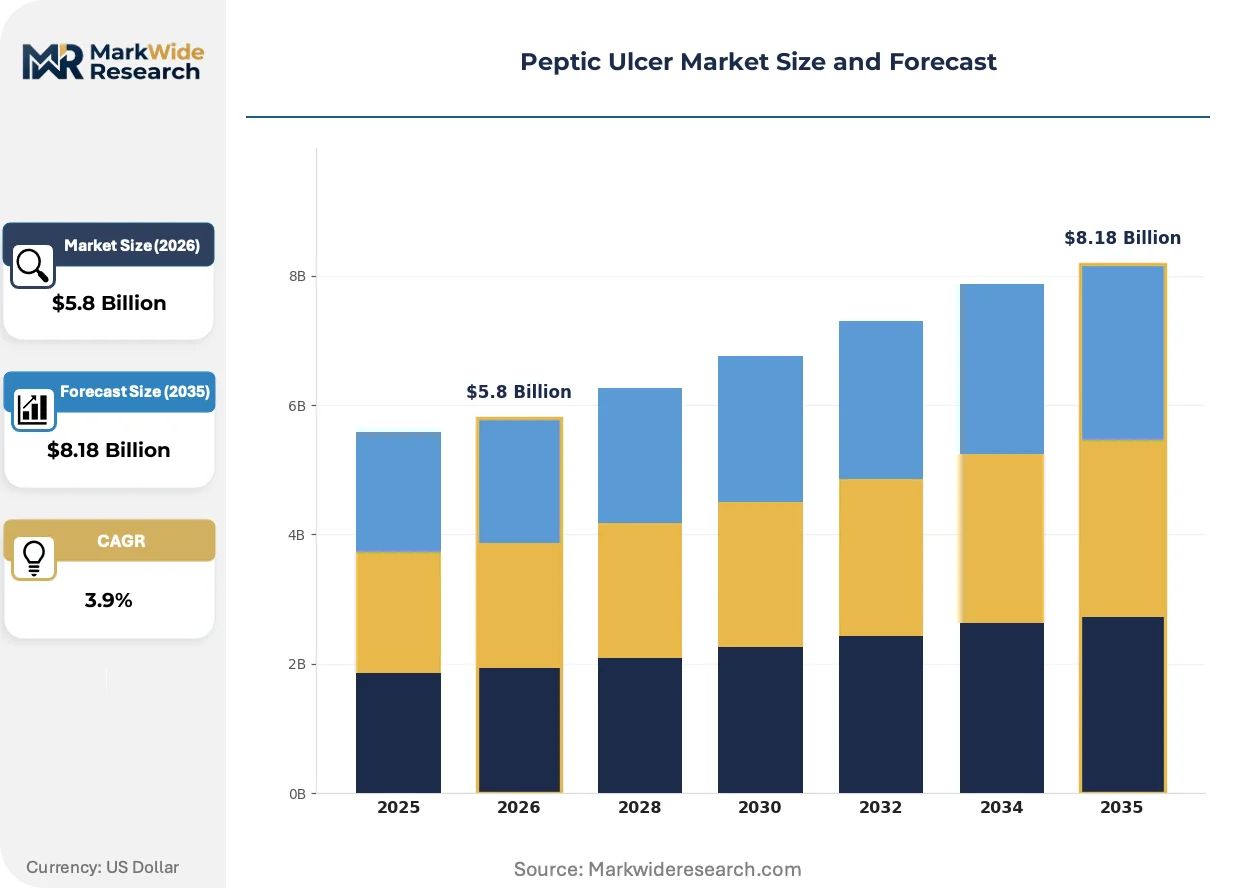
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antacids, H2 Receptor Antagonists, Proton Pump Inhibitors, Antibiotics, Cytoprotective Agents Therapy Area: Gastric Ulcer, Duodenal Ulcer, Stress Ulcer, NSAID-induced Ulcer, Zollinger-Ellison Syndrome End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Community Healthcare Centers Delivery Mode: Oral, Intravenous, Intramuscular, Transdermal, Sublingual |
| Companies Covered | AstraZeneca, Pfizer, Takeda Pharmaceutical, Abbott Laboratories, Novartis AG, Sanofi, Boehringer Ingelheim, Eisai Co., Ltd., Daewoong Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptic Ulcer Market Strategic Shifts & Innovations
The therapeutic landscape for peptic ulcers is shifting from broad-spectrum approaches to more personalized treatment modalities. This evolution is driven by the need to overcome antibiotic resistance and improve long-term patient outcomes through more targeted interventions.
Potassium-Competitive Acid Blockers (P-CABs) represent a new class of acid suppressants offering faster and more potent action than traditional PPIs. Gastroenterology specialists are leading the adoption of P-CABs, particularly for refractory conditions and as a core component of H. pylori eradication. This technology is integrating digital monitoring tools to track patient response, creating a more comprehensive care package for complex cases.
Regulatory incentives, such as the US Food and Drug Administration's Qualified Infectious Disease Product (QIDP) designation, provide benefits like extended market exclusivity. This pathway is designed to de-risk and accelerate the development pipeline for drugs targeting critical pathogens like resistant H. pylori. Biopharmaceutical companies focused on anti-infectives are most affected, as the designation makes investment in this area more commercially viable.
A notable shift in patient priorities involves a greater preference for therapies with fewer side effects and shorter treatment durations. This preference is disrupting the dominance of older, complex 14-day triple-therapy regimens in favor of newer, more streamlined quadruple therapies or sequential treatments. The trend is most visible in developed markets like the United States and Western Europe, where patient information access influences prescribing decisions.
Peptic Ulcer Market Segmentation
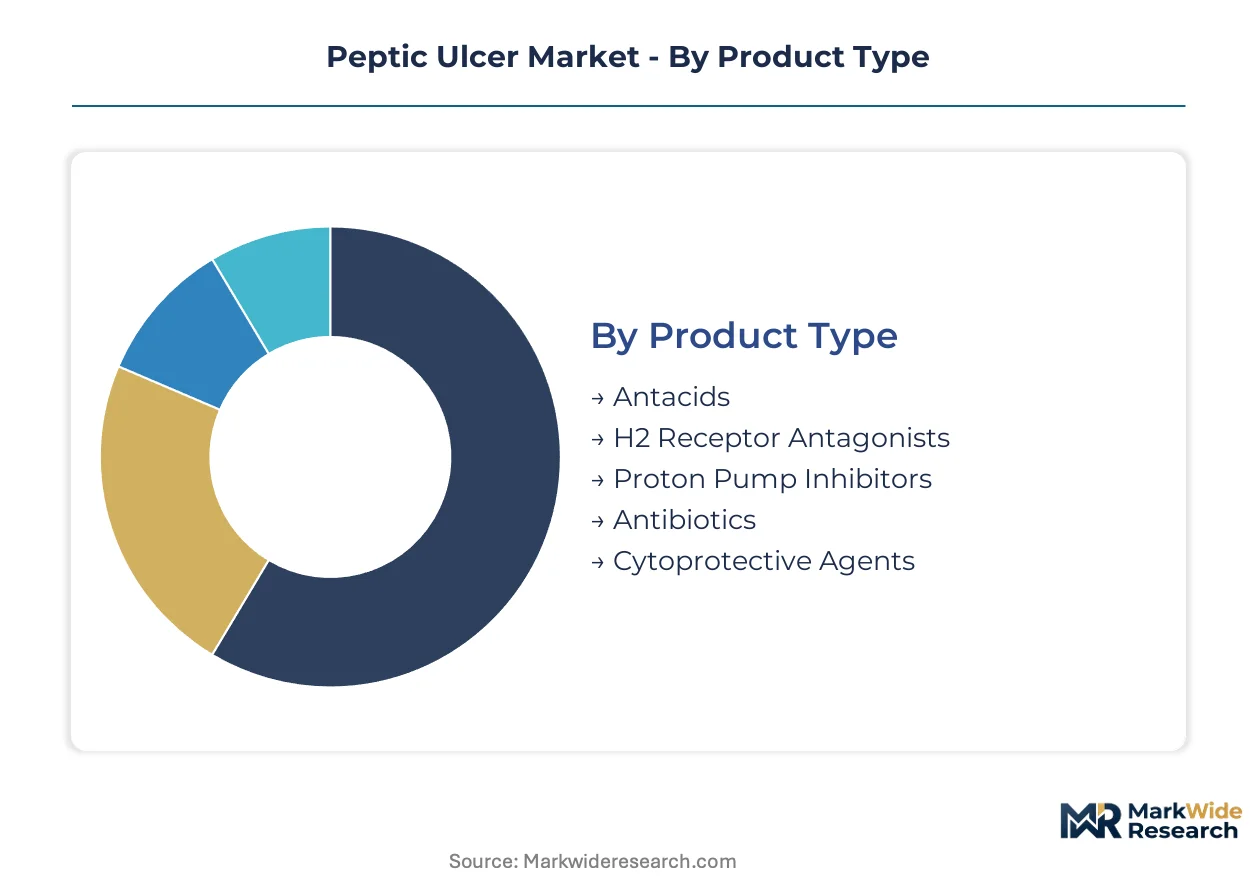
The peptic ulcer market segmentation provides a granular understanding of treatment modalities and patient needs, reflecting diverse therapeutic approaches and delivery systems. Dissecting these segments reveals specific areas of innovation and established market dominance. This detailed view assists stakeholders in identifying opportunities for targeted intervention and strategic resource allocation.
Product Type:
The product type landscape balances high-volume generic treatments with premium, novel compounds addressing specific clinical challenges.
- Proton Pump Inhibitors:These agents effectively reduce stomach acid production, forming the cornerstone of peptic ulcer treatment due to their high efficacy and established safety profiles. Demand concentrates in developed markets, particularly the United States, driven by chronic acid-related conditions.
- Antibiotics:Crucial for eradicating Helicobacter pylori infections, these drugs are often used in combination therapies to overcome bacterial resistance. The increasing prevalence of antibiotic-resistant strains in regions like Japan necessitates continuous research and development for novel compounds.
- Antacids:These over-the-counter medications provide rapid, symptomatic relief by neutralizing stomach acid, appealing to patients seeking immediate comfort.
- H2 Receptor Antagonists:These drugs reduce acid secretion by blocking histamine receptors, offering an alternative to PPIs for some patients.
- Cytoprotective Agents:These medications protect the stomach lining from acid and promote healing, often used as adjuncts in complex cases.
Today's leader: Proton Pump Inhibitors. Tomorrow's challenger: Antibiotics.
Therapy Area:
Treatment strategies for peptic ulcers are highly specific, tailored to the ulcer's location and underlying cause within the gastrointestinal tract.
- Duodenal Ulcer:These ulcers, occurring in the first part of the small intestine, are the most common type and frequently associated with H. pylori infection. Treatment protocols in Europe emphasize eradication therapies for these prevalent cases.
- Gastric Ulcer:Forming on the stomach lining, these ulcers can be caused by H. pylori or NSAID use, often requiring a multifaceted treatment approach. Hospital treatment protocols in the United States increasingly mandate combination therapies for gastric ulcer management.
- NSAID-induced Ulcer:These ulcers result from the long-term use of nonsteroidal anti-inflammatory drugs, particularly in aging populations.
- Stress Ulcer:Occurring in critically ill patients, these ulcers are often prevented and treated in hospital intensive care units.
- Zollinger-Ellison Syndrome:This rare condition involves excessive acid production, necessitating potent acid-suppressing medications for management.
Targeted interventions for NSAID-induced Ulcer are expanding most quickly, while Gastric Ulcer remains a consistent focus.
End User:
The distribution of peptic ulcer treatments is largely dictated by the severity of the condition and the complexity of the required therapeutic regimen.
- Hospitals:These institutions serve as primary centers for diagnosing and treating severe or complicated peptic ulcer cases, often involving intravenous medications and advanced diagnostics. Hospital treatment protocols frequently incorporate combination therapies for H. pylori eradication.
- Specialty Clinics:Gastroenterology clinics provide specialized care for chronic or refractory peptic ulcers, offering expert consultation and long-term management plans. Patient adherence and monitoring programs are broadening the scope of therapeutic offerings within these settings.
- Ambulatory Surgical Centers:These facilities handle diagnostic procedures like endoscopy and minor interventions for peptic ulcer complications.
- Community Healthcare Centers:These centers provide initial diagnosis and management for uncomplicated peptic ulcer cases, often prescribing oral medications.
The shift towards Specialty Clinics is driven by the need for personalized care, while Hospitals maintain their established role in acute management.
Delivery Mode:
The method of drug administration for peptic ulcer treatments is chosen based on factors such as drug properties, patient compliance, and the desired speed of action.
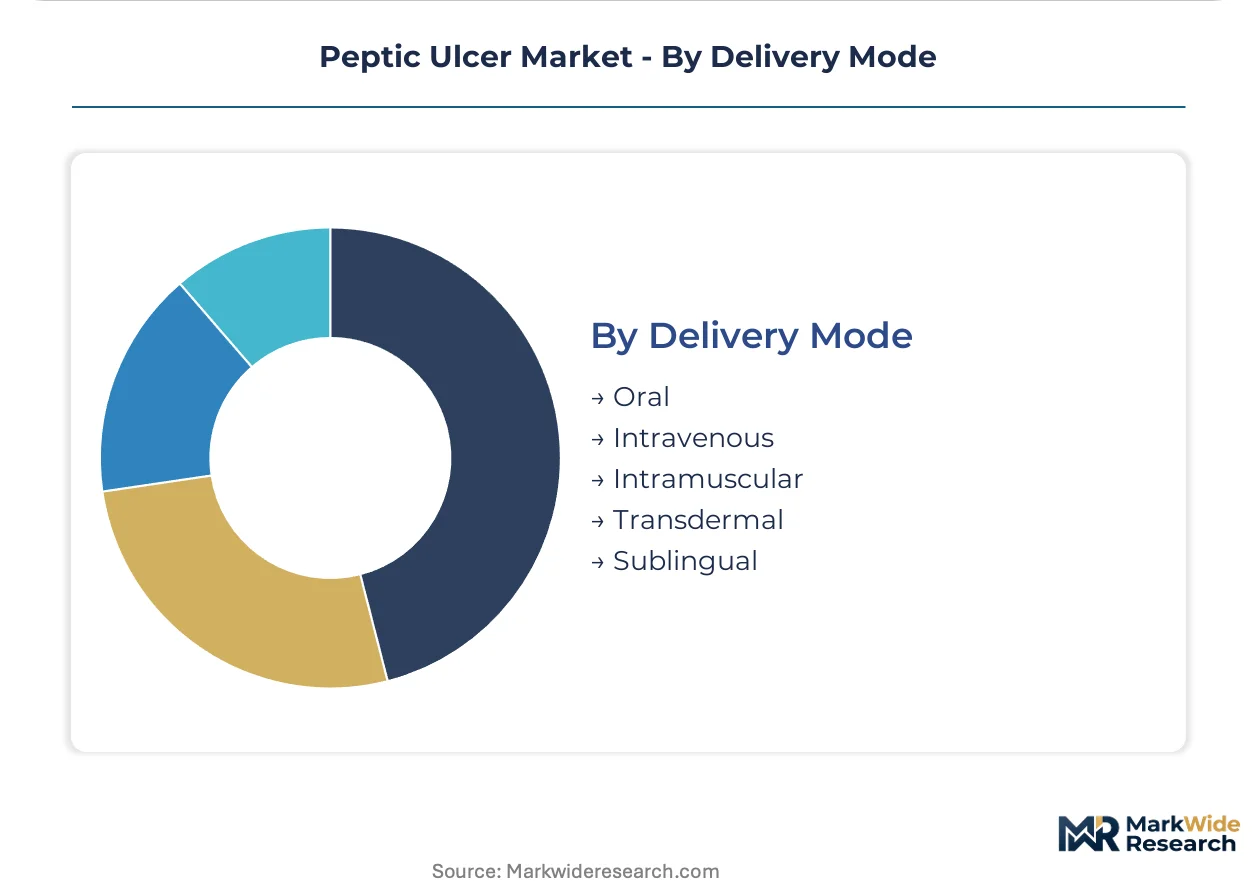
- Oral:This is the most common and convenient delivery method for most peptic ulcer medications, including PPIs and antibiotics, suitable for long-term home use. Patient preference for therapies with shorter treatment durations influences the development of new oral regimens.
- Intravenous:Used for severe cases, hospitalized patients, or when rapid drug action is required, intravenous administration ensures high bioavailability. This mode is crucial in managing acute gastrointestinal bleeding or refractory conditions.
- Transdermal:This non-invasive method allows for continuous drug delivery through the skin, potentially improving patient compliance for certain medications.
- Intramuscular:This route is less common for peptic ulcer treatment but may be used for specific short-term or emergency applications.
- Sublingual:This method allows for rapid absorption directly into the bloodstream, bypassing the digestive system, though rarely used for typical ulcer treatments.
Innovation in Oral delivery aims to improve patient adherence, complementing the established utility of Intravenous administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The peptic ulcer market demonstrates significant regional variations. Demand for advanced treatments is particularly strong in the United States, while Japan's aging demographics create a distinct demand profile for preventative care. These divergent needs shape pharmaceutical development and market access strategies across global territories.
United States
Demand for advanced treatments and combination therapies drives market expansion in the United States. The US Food and Drug Administration (FDA) sets stringent clinical trial requirements for new gastrointestinal drugs. Biopharmaceutical research hubs in Boston and San Francisco focus on novel compounds for resistant H. pylori strains.
Japan
Japan's aging population and high H. pylori prevalence generate consistent demand for advanced ulcer treatments. The Pharmaceuticals and Medical Devices Agency (PMDA) influences market entry for new drug applications. Pharmaceutical clusters in Osaka actively develop therapies addressing NSAID-induced ulcers.
Germany
Germany exhibits stable demand for peptic ulcer therapies, supported by comprehensive healthcare infrastructure. The European Medicines Agency (EMA) governs drug approval pathways across the European Union. Research institutions in Munich are investigating microbiome-modulating therapies for gastric health.
India
India experiences rising demand for peptic ulcer treatments due to increasing H. pylori infections and NSAID use. The Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical product approvals. Major pharmaceutical manufacturing centers in Hyderabad focus on producing affordable generic PPIs.
China
China's large patient population and expanding healthcare access fuel demand for both established and novel peptic ulcer medications. The National Medical Products Administration (NMPA) oversees drug registration and clinical trials. Research parks in Shanghai are becoming centers for gastrointestinal drug innovation.
Peptic Ulcer Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the peptic ulcer market. The market structure exhibits a tiered consolidation, with large pharmaceutical companies dominating the branded drug landscape. Strategic archetypes include established pharmaceutical giants focused on comprehensive portfolios, specialized gastrointestinal drug developers, and generic manufacturers. Portfolio diversification into novel compounds and strategic partnerships for H. pylori eradication therapies represent dominant competitive moves among these players.
Among the established pharmaceutical giants, AstraZeneca and Pfizer exemplify companies with broad portfolios. AstraZeneca maintains a strong position in the proton pump inhibitor class, leveraging its extensive clinical data and established brand presence. Pfizer sustains its market share through its diverse portfolio of antibiotics essential for H. pylori eradication therapies. Takeda Pharmaceutical, a Japan-based company, occupies a specialized position by focusing on the development of novel compounds tailored for specific gastrointestinal conditions. These players collectively anchor different facets of the peptic ulcer treatment landscape, from potent acid suppression to complex H. pylori eradication strategies.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer |
| Takeda Pharmaceutical |
| Abbott Laboratories |
| Novartis AG |
| Sanofi |
| Boehringer Ingelheim |
| Eisai Co., Ltd. |
| Daewoong Pharmaceutical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
A clear divergence between branded novel compounds and generic acid suppressants shapes both pricing strategies and supply chain resilience in the peptic ulcer market. This bifurcation influences how pharmaceutical companies invest in R&D and manage their global manufacturing footprints.
Pricing Analysis
Capacity additions in India are reshaping price floors for generic active pharmaceutical ingredients, impacting the overall cost structure. The dominant pricing model remains contract-based for institutional purchases and transactional for retail sales, often stratified by brand and formulation. Clinical efficacy and regulatory approval by bodies like the FDA or EMA serve as primary price differentiation drivers. Pricing softness stems from widespread generic competition following patent expirations. Payers and patients seeking cost-effective solutions are most price-sensitive, while hospitals prioritize novel therapies for complex cases.
Supply Chain Analysis
Reverse logistics for expired or recalled medications present a complex challenge within the pharmaceutical supply chain, demanding stringent regulatory compliance. Geographic supply concentration for key Active Pharmaceutical Ingredients (APIs) centers on India and China. Raw material dependencies include specialized chemical intermediates and pharmaceutical-grade excipients. A structural risk involves potential logistics chokepoints and geopolitical instability affecting API sourcing. Distribution runs through established networks of hospital pharmacies, specialty clinics, and retail pharmacies globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peptic ulcer market operates as a stable compounder, driven by the persistent global prevalence of Helicobacter pylori infections.
For Market Incumbents: Extend existing brand leadership by investing in advanced diagnostic tools for H. pylori susceptibility testing. Diversify portfolios beyond traditional proton pump inhibitors to mitigate generic drug erosion. Strategic partnerships with biotech firms developing novel antibiotics can address the growing threat of antimicrobial resistance. Focus R&D on combination therapies with improved patient adherence profiles.
For New Entrants and Emerging Players: Underserved patient populations in emerging Asian markets represent a significant white space for novel treatment approaches. Target the development of microbiome-modulating therapies or digital adherence programs as value-added services. A go-to-market angle focusing on patient education and simplified treatment regimens can penetrate markets where compliance is a major hurdle.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized R&D capabilities for resistant H. pylori strains are scarce. The market exhibits consistent demand over the long term, driven by chronic disease prevalence. Acquisition targets should include specialized gastrointestinal drug developers or companies with innovative diagnostic platforms. Success rates of novel H. pylori eradication regimens in late-stage trials is a specific signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Diversification into P-CABs | Expands therapeutic offerings beyond PPIs, addressing refractory acid-related conditions. |
| Investment in H. pylori Diagnostics | Improves treatment targeting for antibiotic-resistant strains, enhancing patient outcomes. |
| Digital Adherence Program Development | Enhances patient compliance with complex regimens, reducing treatment failures. |
| Strategic Partnerships for Novel Antibiotics | Accelerates development of therapies against multi-drug resistant H. pylori. |
| Geographic Expansion in Southeast Asia | Captures demand in high-prevalence regions with rising healthcare expenditure. |
Research Approach
Coverage spans the United States, Japan, Germany, India, and China, with primary inputs from each region's key stakeholders. This analysis combines insights from in-depth primary interviews with gastroenterology specialists, pharmaceutical R&D executives, regulatory affairs leads, and hospital procurement managers. Secondary validation draws from sources including FDA filings, EMA submissions, PMDA guidelines, and clinical trial databases. Both bottom-up and top-down triangulation methods ensure data accuracy.
Rate-of-change decomposition frames the analytical framework, assessing market shifts across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user, delivery mode, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) derive from a comprehensive evaluation of historical trends and projected future demand. Key industry-specific forecast inputs include H. pylori resistance rates and nonsteroidal anti-inflammatory drug (NSAID) usage patterns.
Underlying measurement precision varies by segment; Proton Pump Inhibitors and Antibiotics carry tighter precision than others due to established sales data. Forecasts reflect assumptions regarding regulatory changes and technological advancements. Emergence of new H. pylori strains and unexpected shifts in treatment guidelines are specific risk factors. Practitioners should monitor H. pylori resistance trends and regulatory incentives for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Gallstone Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
Chile Gastric Cancer Treatment Market
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Diverticular Disease Therapeutics Market