
 Drug Delivery Market | 2026-2036
Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Delivery Market Intelligence
Biodegradable polymers are consolidating as the dominant material class in implantable and injectable systems, displacing conventional metal stents and non-degradable reservoirs. Pfizer Inc. leverages vertical integration across polymer synthesis and finished dosage manufacturing to protect margin pools in controlled-release injectables. Novartis AG anchors its portfolio in liposomal and nanotechnology platforms, sustaining R&D intensity above industry norms for oncology applications. Johnson & Johnson Services, Inc. competes through geographic dominance in microneedle patch development, with manufacturing scale concentrated in North American and European facilities.
Drug delivery encompasses the engineered transport of pharmaceutical compounds to targeted physiological sites using controlled-release kinetics, biocompatible carrier materials, and route-specific administration devices, with functional parameters including dissolution profiles, bioavailability ratios, and tissue permeability coefficients designed to optimize therapeutic indices. Injectable platforms lead current revenue generation due to their dominance in biologics administration, while microneedle technology represents the fastest-expanding segment as patient preference shifts toward minimally invasive alternatives. Polymer-based systems occupy the deepest margin pools because formulation patents and material exclusivity create durable pricing power against generic competition.
The FDA enforces Current Good Manufacturing Practice standards for combination products, while the EMA's Medical Device Regulation imposes clinical evidence requirements that reshape development costs for European market access. ISO 13485 quality management standards and the EU AI Act's emerging provisions for algorithm-driven dosing systems are forcing manufacturers to restructure compliance departments and documentation protocols. Stakeholders must monitor regulatory divergence between the FDA's risk-based classification approach and the EMA's stricter clinical endpoint requirements when prioritizing geographic launch sequences.
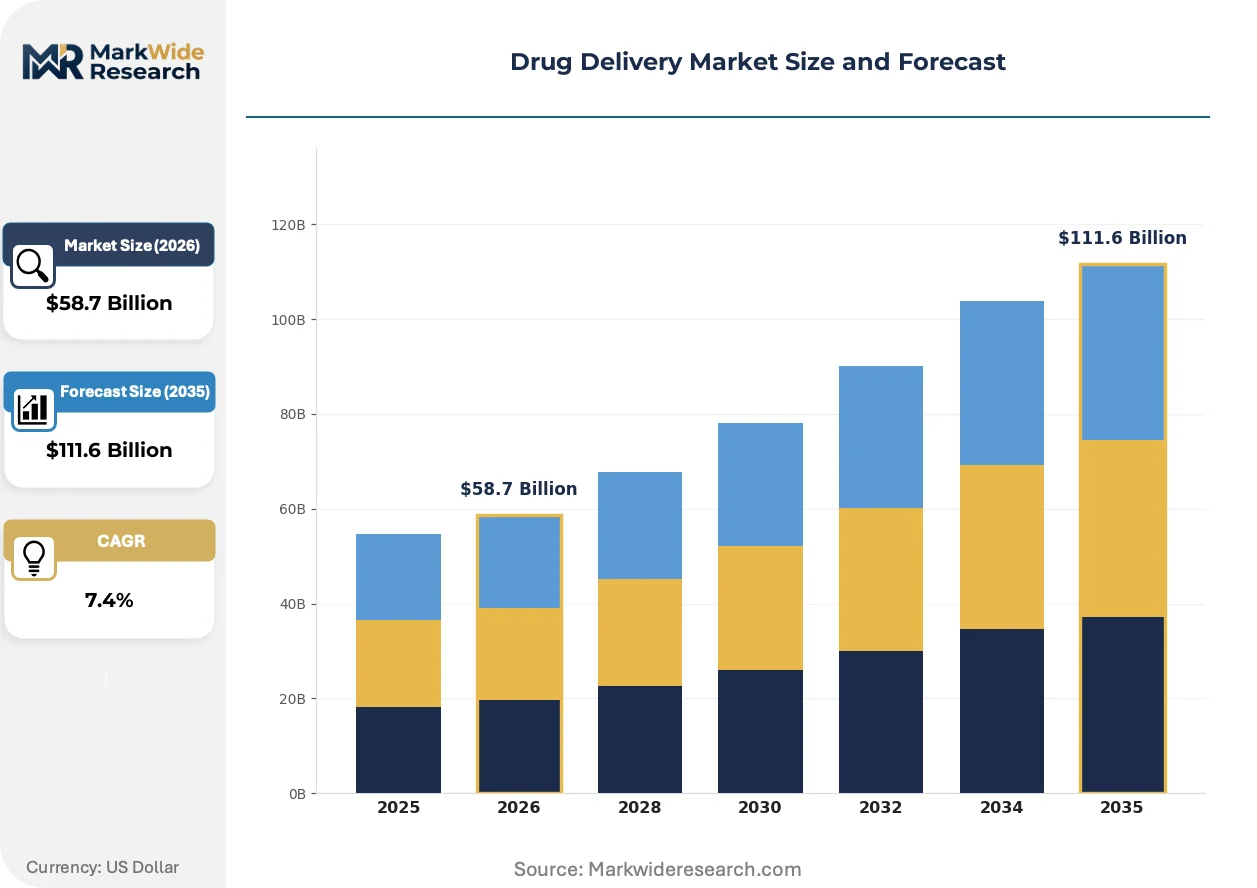
Market Dynamics
Biodegradable polymer synthesis is concentrating among three specialized chemical suppliers, creating upstream bottlenecks that reshape downstream formulation economics and patent licensing terms for implantable device manufacturers.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's breakthrough device designation compresses clinical trial timelines for drug-device combinations, pulling forward commercialization revenue for oncology-focused delivery platforms.
- Japan's Biologics Infrastructure:METI-funded manufacturing clusters in Kansai and Kanto regions expand fill-finish capacity for controlled-release injectables, anchoring regional supply security.
- Microneedle Patch Technology:Transdermal delivery systems bypass first-pass metabolism and cold-chain requirements, opening self-administration pathways for chronic disease management.
Market Restraints
- Specialized Polymer Feedstock Concentration:Medical-grade PLGA and PCL production clusters in Germany and Switzerland, exposing formulators to single-source risk and euro-denominated input volatility.
- EMA MDR Clinical Evidence Burden:The EU Medical Device Regulation mandates extended follow-up periods for implantable combination products, inflating European market entry costs relative to FDA pathways.
- Metal Stent Substitution Ceiling:Non-degradable cardiovascular stents retain cost advantages in price-sensitive hospital procurement, slowing full displacement despite polymer biocompatibility benefits.
Strategic Opportunities
- Brazil's ANVISA Streamlining:Brazil's regulator implemented priority review tracks for nanotechnology-based oncology formulations, creating first-mover windows for liposomal platform holders.
- AI-Enabled Dosing Algorithms:The EU AI Act's risk classification framework for algorithm-driven infusion pumps is converging with ISO 13485 quality mandates, opening compliance-as-a-service revenue streams.
- Home Infusion Channel Expansion:Specialty pharmacy networks in the United States are building cold-chain infrastructure for biologic self-administration, displacing hospital outpatient settings for maintenance therapy.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemistry expertise in biodegradable material degradation kinetics concentrates among aging cohorts at legacy pharmaceutical manufacturers.
- ISO 13485 Documentation Burden:Design history file requirements for combination products force mid-scale device firms to restructure quality departments or outsource regulatory affairs.
- Legacy ERP Integration Friction:Electronic batch record systems for continuous manufacturing lines conflict with validated legacy infrastructure at established dosage form facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Delivery Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $111.6 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Transdermal Patch, Oral, Inhalation, Nasal Spray, Implantable Technology: Nanotechnology, Liposomal, Microneedle, Polymer-Based, Carrier-Mediated, Targeted Release Therapy Area: Oncology, Cardiovascular, Neurology, Diabetes, Infectious Diseases, Respiratory End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Medical Device Manufacturers |
| Companies Covered | Johnson & Johnson Services, Inc., Pfizer Inc., Novartis AG, F. Hoffmann-La Roche Ltd., Becton, Dickinson and Company, Medtronic, Baxter International Inc., West Pharmaceutical Services Inc., GlaxoSmithKline plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Delivery Market Strategic Shifts & Innovations
Active pharmaceutical ingredient complexity is outpacing conventional formulation capacity, forcing convergence between materials science and digital manufacturing control systems across contract development organizations.
Electrospun nanofiber scaffolds for localized drug release are converging with 3D printing platforms to enable patient-specific implant geometries. Orthopedic and wound care device manufacturers in Germany and Massachusetts are piloting these systems for antibiotic-loaded bone grafts. The technology is converging with real-time dissolution monitoring to compress formulation development cycles from years to months.
The EU AI Act's high-risk system classification for algorithm-controlled infusion pumps is forcing manufacturers to restructure clinical validation protocols. European notified bodies now demand algorithmic transparency documentation alongside traditional biocompatibility studies. Oncology and diabetes device segments are responding by segregating European and United States product variants to manage divergent evidentiary burdens.
Hospital procurement committees are unbundling device acquisition from drug supply contracts, reversing decade-long bundled pricing structures. This pattern concentrates negotiating leverage among United States health system purchasing organizations and German hospital networks. Generic injectable manufacturers are capturing margin previously retained by branded combination product holders through separate device sourcing strategies.
Drug Delivery Market Segmentation
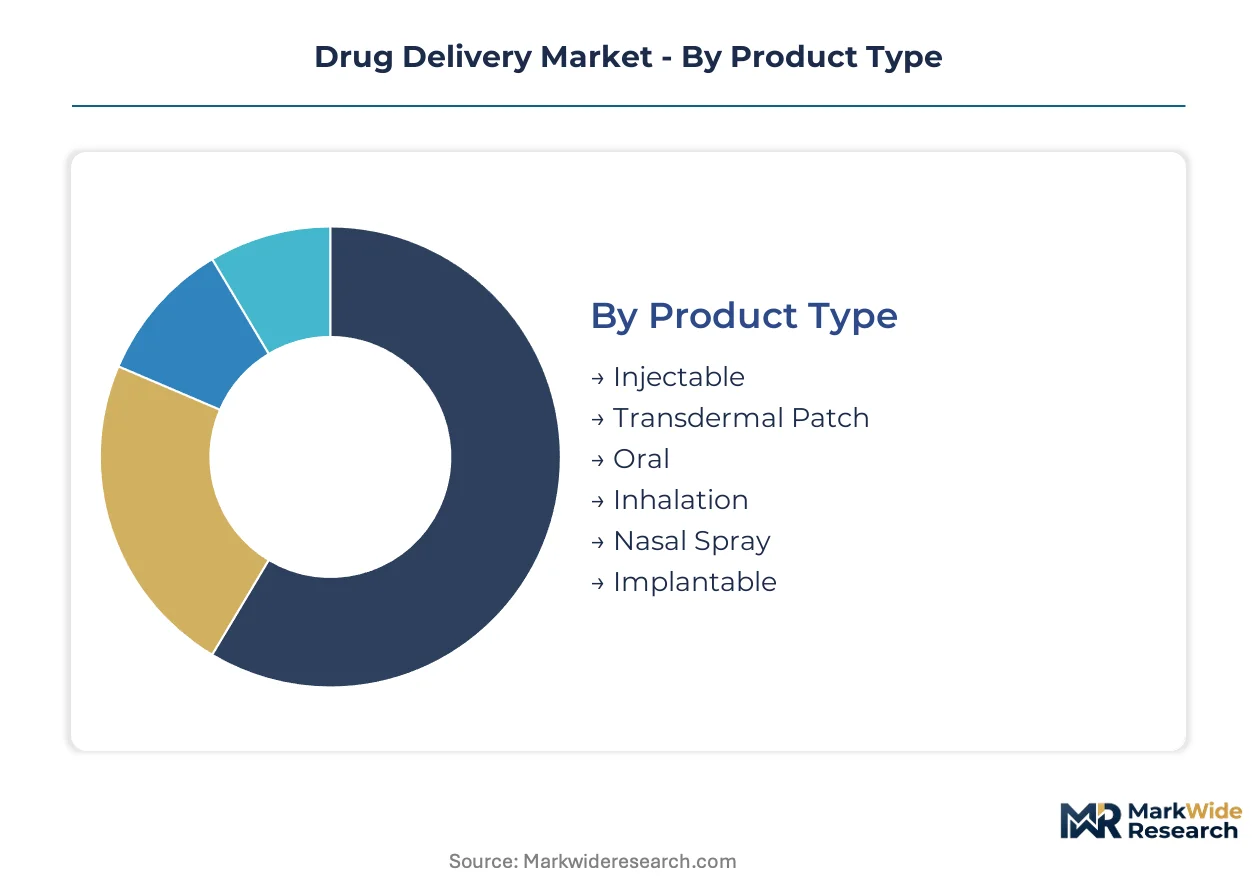
Drug delivery segmentation reveals divergent regulatory pathways and margin architectures across administration routes and carrier technologies. Each category carries distinct FDA, EMA, and ISO 13485 certification burdens that reshape development timelines and geographic launch priorities.
Product Type:
FDA breakthrough device designation and EMA MDR clinical evidence requirements vary sharply across administration routes, with implantable systems facing the steepest regulatory burden and oral platforms the lightest.
- Injectable:Dominates biologics administration through prefilled syringes and autoinjectors. Demand concentrates in United States oncology clinics and German hospital networks where cold-chain infrastructure supports temperature-sensitive monoclonal antibodies. The segment absorbs the deepest R&D investment due to viscosity challenges and needle-free alternatives.
- Transdermal Patch:Bypasses first-pass metabolism through adhesive matrix or reservoir systems. Patient preference in Japan and United States home-care settings drives adoption for chronic pain and hormone replacement, though skin permeability limits applicable drug classes.
- Oral:Retains cost advantages through established tableting infrastructure and patient familiarity. Bioavailability enhancement technologies address absorption limitations for poorly soluble compounds.
- Inhalation:Targets respiratory and systemic delivery via nebulizers, dry powder inhalers, and metered-dose devices. Lung deposition efficiency determines therapeutic equivalence.
- Nasal Spray:Enables rapid systemic absorption and direct-to-brain delivery for selected compounds. Device consistency challenges require specialized actuation testing.
- Implantable:Requires extended biocompatibility studies and degradation kinetic validation. Long-acting depot formulations in oncology and contraception justify development costs.
Injectable sits at the top of the volume ranking, with transdermal patch climbing the fastest.
Technology:
Patent thickets and material exclusivity create tiered margin structures, with polymer-based and liposomal platforms commanding premium pricing against commoditized carrier systems.
- Nanotechnology:Particle engineering below 100 nanometers enhances solubility and targeting precision. Brazil's ANVISA priority review tracks accelerate oncology formulation approvals for qualified platforms.
- Liposomal:Phospholipid bilayer encapsulation improves drug stability and reduces toxicity profiles. Manufacturing complexity limits production to specialized facilities in Switzerland and Massachusetts.
- Microneedle:Dissolving or hydrogel-forming arrays enable painless transdermal delivery. Johnson & Johnson's North American and European manufacturing scale anchors competitive positioning in diabetes and vaccine applications.
- Polymer-Based:PLGA and PCL degradation kinetics enable tunable release profiles from weeks to months. Three German and Swiss chemical suppliers concentrate medical-grade feedstock production.
- Carrier-Mediated:Ligand-targeted or antibody-directed transport improves tissue specificity. Receptor binding validation extends preclinical timelines.
- Targeted Release:pH-sensitive or enzyme-triggered mechanisms confine drug activity to disease sites. Formulation patents create durable pricing power against generic competition.
Polymer-based systems capture the widest revenue share, with microneedle technology gaining share fastest.
Therapy Area:
Clinical trial infrastructure and reimbursable pricing determine geographic concentration, with oncology and diabetes anchoring investment in United States, Germany, and Japan.
- Oncology:Cytotoxic payloads demand precise targeting to minimize off-tissue toxicity. Liposomal doxorubicin and antibody-drug conjugates concentrate development in Novartis AG's nanotechnology platforms.
- Cardiovascular:Biodegradable stents and anticoagulant depots compete against cost-optimized metal alternatives. German hospital procurement committees unbundle device from drug contracts.
- Neurology:Blood-brain barrier penetration challenges limit applicable technologies. Intrathecal pumps and nasal-to-brain pathways attract specialized development.
- Diabetes:Continuous glucose monitoring integration drives smart insulin delivery. United States specialty pharmacy networks expand home infusion infrastructure.
- Infectious Diseases:Long-acting injectables improve adherence in tuberculosis and HIV management. Cold-chain requirements constrain distribution in emerging markets.
- Respiratory:Inhalation devices dominate asthma and COPD maintenance. Lung deposition modeling guides generic bioequivalence studies.
Oncology leads therapeutic investment intensity, with neurology showing steepest expansion trajectory.
End User:
Customer capability profiles determine service bundling preferences, with pharmaceutical companies integrating formulation development and biotechnology firms outsourcing to contract manufacturing organizations.
- Pharmaceutical Companies:Pfizer Inc.'s vertical integration across polymer synthesis and finished dosage manufacturing protects margin pools in controlled-release injectables.
- Biotechnology Firms:R&D-stage companies prioritize platform flexibility over manufacturing scale. Partnership structures with specialized contract development organizations predominate.
- Research Laboratories:Academic and government institutions drive early-stage materials science innovation. Technology transfer agreements bridge discovery and commercialization.
- Medical Device Manufacturers:Combination product expertise in ISO 13485 quality systems determines regulatory submission success. Design history file capabilities separate qualified from marginal suppliers.
Pharmaceutical companies dominate procurement volume, with biotechnology firms expanding contract manufacturing engagement most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kansai and Kanto manufacturing clusters anchor Japan's biologics fill-finish capacity, while United States clinical trial infrastructure and German chemical feedstock production shape competitive positioning across controlled-release platforms.
United States
Oncology clinics and specialty pharmacy networks drive demand for prefilled syringes and autoinjector systems. The FDA's breakthrough device designation compresses commercialization timelines for drug-device combinations. Greater Boston and Research Triangle Park host concentrated contract manufacturing organizations serving biotechnology firms.
Germany
Hospital procurement committees unbundle device acquisition from drug supply contracts, shifting negotiating leverage toward purchasing organizations. The EMA's Medical Device Regulation imposes extended follow-up requirements for implantable combination products. Baden-Württemberg and North Rhine-Westphalia concentrate medical-grade PLGA and PCL polymer synthesis among specialized chemical suppliers.
Japan
METI-funded manufacturing clusters expand controlled-release injectable capacity for domestic and export markets. The PMDA aligns with FDA accelerated approval frameworks for nanotechnology-based oncology formulations. Kansai and Kanto regions anchor regional supply security for biologic drug products.
Switzerland
Liposomal manufacturing complexity limits production to specialized facilities serving high-value oncology applications. Swissmedic maintains alignment with EMA quality standards while offering streamlined review for innovative carrier technologies. Basel and Zurich concentrate formulation expertise in phospholipid bilayer encapsulation systems.
Brazil
ANVISA's priority review tracks for nanotechnology-based oncology formulations create first-mover windows for platform holders. The regulator's streamlining efforts attract liposomal and polymer-based system developers seeking Latin American market access. São Paulo's clinical research infrastructure supports regional trial execution for novel delivery mechanisms.
Drug Delivery Market Key Industry Players
Global majors compete with regional champions across polymer synthesis, finished dosage manufacturing, and microneedle patch development. Market structure consolidates around three strategic tiers: vertically integrated pharmaceutical conglomerates controlling upstream material supply, specialized nanotechnology platform holders, and geographic-focused device manufacturers. Competitive moves center on backward integration into polymer feedstock production and strategic partnerships with contract development organizations to secure formulation capacity.
Among vertically integrated conglomerates, Pfizer Inc. and Johnson & Johnson Services, Inc. occupy positions spanning polymer synthesis through finished dosage manufacturing. Novartis AG sits within the specialized platform tier, anchoring nanotechnology and liposomal capabilities. These three entities exemplify distinct competitive archetypes: captive supply chain control, geographic manufacturing scale concentration, and R&D-intensive platform specialization.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Becton, Dickinson and Company |
| Medtronic |
| Baxter International Inc. |
| West Pharmaceutical Services Inc. |
| GlaxoSmithKline plc. |
| Others |
Cost & Logistics Intelligence
Formulation chemistry expertise in biodegradable material degradation kinetics concentrates among aging cohorts in Massachusetts and Basel, with labor-cost differentials between these legacy pharmaceutical hubs and emerging CRO clusters in India widening pricing-tier spreads across polymer-based and liposomal platforms.
Pricing Analysis
Input-cost pass-through from medical-grade PLGA and PCL feedstock volatility in Germany and Switzerland compresses margins for mid-scale device manufacturers lacking backward integration into polymer synthesis. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated platforms from CE-marked equivalents and unbundled generic injectables. Cost compression in the economy tier is intensifying because hospital procurement committees now source devices and drugs separately. Biotechnology firms with outsourced manufacturing exhibit the highest price sensitivity, while vertically integrated pharmaceutical conglomerates retain pricing power through captive material supply.
Supply Chain Analysis
Dual-sourcing requirements from ISO 13485-certified device manufacturers mandate multi-supplier qualification for medical-grade PLGA and PCL, yet production clusters in Germany, Switzerland, and Japan still dominate feedstock supply. Raw material dependencies center on phospholipid bilayers for liposomal systems, electrospun nanofiber precursors, and cold-chain packaging components. Single-source vulnerability persists for specialized polymer synthesis expertise concentrated in Baden-Württemberg. Distribution runs through United States specialty pharmacy networks and German hospital procurement organizations with direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drug delivery market reads as a late-cycle quality story, with demand shifting toward premium specifications as oncology clinics prioritize targeted release platforms with validated degradation kinetics over commoditized alternatives.
For Market Incumbents: Anchor competitive position through backward integration into medical-grade polymer feedstock production in Germany or Switzerland, securing supply security against emerging CRO competition. Defend margin pools by acquiring specialized contract development organizations with ISO 13485 design history file capabilities, as regulatory documentation burdens now separate qualified from marginal suppliers. Prioritize FDA breakthrough device designation for oncology-focused platforms to compress commercialization timelines relative to EMA MDR pathways.
For New Entrants and Emerging Players: AI-enabled dosing algorithms for algorithm-controlled infusion pumps present a technology-first wedge, as the EU AI Act's high-risk system classification forces incumbents to restructure clinical validation protocols. Target Brazil's ANVISA priority review tracks for nanotechnology-based oncology formulations, where streamlining efforts create first-mover windows absent entrenched competition. Pursue partnership structures with METI-funded manufacturing clusters in Japan's Kansai region to access fill-finish capacity without capital-intensive facility builds.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale device firms struggling with ISO 13485 documentation burdens and legacy ERP integration friction, as quality department restructuring costs depress near-term earnings. Long-term viability hinges on exposure to microneedle patch technology and home infusion channel expansion, segments where patient preference shifts toward self-administration sustain durable demand. Watch for inflection signals in hospital procurement committee unbundling patterns, as separate device sourcing strategies redistribute margin from branded combination product holders to generic injectable manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough device designation compresses oncology platform commercialization timelines against EMA MDR alternatives. |
| Backward Integration | Captive polymer synthesis in Germany or Switzerland insulates margin pools from euro-denominated feedstock volatility. |
| Manufacturing Scale-Up | METI-funded Kansai clusters expand controlled-release injectable capacity for biologics export markets. |
| Strategic Partnership | Collaboration with Brazilian CROs accelerates ANVISA priority review for nanotechnology oncology formulations. |
| Software Companion Development | AI-enabled dosing algorithms for infusion pumps open compliance-as-a-service revenue under EU AI Act mandates. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at combination product manufacturers, formulary directors at United States oncology clinics, procurement managers at German hospital networks, and biomedical engineers at contract development organizations with secondary validation against FDA filings, EMA Medical Device Regulation submissions, ClinicalTrials.gov records, and ISO 13485 certification databases. Bottom-up patient population modeling and top-down pharmaceutical R&D expenditure analysis provided cross-verification.
Comparable-period anchoring established baseline growth trajectories from historical regulatory approval timelines and commercialization patterns across the projection horizon. Segmentation dimensions modeled include administration route, carrier technology, therapy area, and regional regulatory cluster. CAGRs were derived from patent expiration schedules, biosimilar entry assumptions, and reimbursement pathway evolution. Forecast inputs incorporated cold-chain infrastructure buildout rates and microneedle patch manufacturing scale expansion.
The model holds under stable FDA-EMA regulatory alignment and continued biologics pipeline investment; deviation in polymer feedstock trade restrictions or accelerated generic substitution would shift volume trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Postmenopausal Vaginal Atrophy Drugs Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Sympathoimemetic Agents Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Antithrombin Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market