
 Mild Laxatives Market | 2026-2036
Mild Laxatives Market Size, Share, and Industry Trends Forecast 2026-2036
Mild Laxatives Market Analytics
Aftermarket service revenue from patient adherence programs is fragmenting across branded and private-label portfolios. Bayer leverages its consumer health infrastructure to sustain pharmacy shelf presence across multiple continents. GlaxoSmithKline anchors its position through gastrointestinal R&D intensity and clinician education networks. Procter & Gamble competes via mass-market channel control and retail distribution density in North America.
Mild laxatives are pharmacological agents that promote bowel evacuation through osmotic water retention, stool softening, or bulk fiber augmentation, typically formulated with active compounds such as docusate sodium, polyethylene glycol, or psyllium husk at standardized concentrations for OTC or prescription administration. These products serve commercial and clinical purposes by addressing functional constipation, medication-induced bowel dysfunction, and post-surgical gastrointestinal recovery in ambulatory and institutional settings. Bulk forming laxatives occupy mature margin pools due to established fiber-supplement positioning and low manufacturing complexity, while osmotic laxatives lead growth trajectories driven by polyethylene glycol's prescriber preference in pediatric and geriatric protocols. Tablet delivery modes dominate hospital and pharmacy procurement patterns, though liquid formulations gain traction in long-term care facilities where swallowing difficulties prevail.
FDA monograph oversight and EMA pharmacovigilance frameworks govern active ingredient purity, label indication limits, and pediatric safety warnings across OTC and prescription categories. The FDA's pending updates to laxative monograph labeling requirements directly reshape manufacturer formulation strategies and consumer communication standards. Stakeholders must monitor how regulator divergence between FDA and EMA on polyethylene glycol age thresholds alters cross-border product registration timelines and portfolio prioritization.
Market Dynamics
FDA monograph reforms are compressing formulation flexibility while expanding pediatric safety requirements, forcing manufacturers to revalidate label claims and active ingredient thresholds across OTC portfolios.
Growth Catalysts
- Polyethylene glycol protocols:Pediatric and geriatric prescriber preference for PEG-based osmotic agents drives hospital formulary adoption and home-care discharge planning.
- EMA pharmacovigilance frameworks:Standardized adverse event reporting across European markets elevates quality-tier manufacturer credibility and streamlines cross-border registration.
- Long-term care swallowing difficulties:Liquid formulation demand in nursing facilities and assisted living centers creates dedicated procurement channels distinct from retail pharmacy.
Market Restraints
- Psyllium husk supply volatility:Indian agricultural output fluctuations and export tariff shifts create raw material cost instability for bulk-forming laxative producers.
- FDA label indication limits:Pending restrictions on duration-of-use claims constrain marketing language and compress differentiation space for OTC brands.
- Dietary fiber substitution:Food-as-medicine positioning and direct-to-consumer fiber supplements capture price-sensitive constipation management demand.
Strategic Opportunities
- Home-care adherence programs:Remote patient monitoring integration creates recurring revenue streams beyond product sales in Medicare Advantage networks.
- Japan's aging demographic density:METI-supported digital pharmacy infrastructure and PMDA streamlined OTC switches open access to the world's oldest population cohort.
- Combination formulation development:Stool softener-osmotic hybrids address polypharmacy compliance gaps in post-surgical and opioid-induced constipation protocols.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in pediatric palatability masking and stability testing for liquid PEG products commands premium compensation and extends R&D timelines.
- Monograph compliance revalidation:FDA-mandated bioequivalence studies for legacy docusate sodium products require capital allocation that displaces pipeline investment.
Report Scope
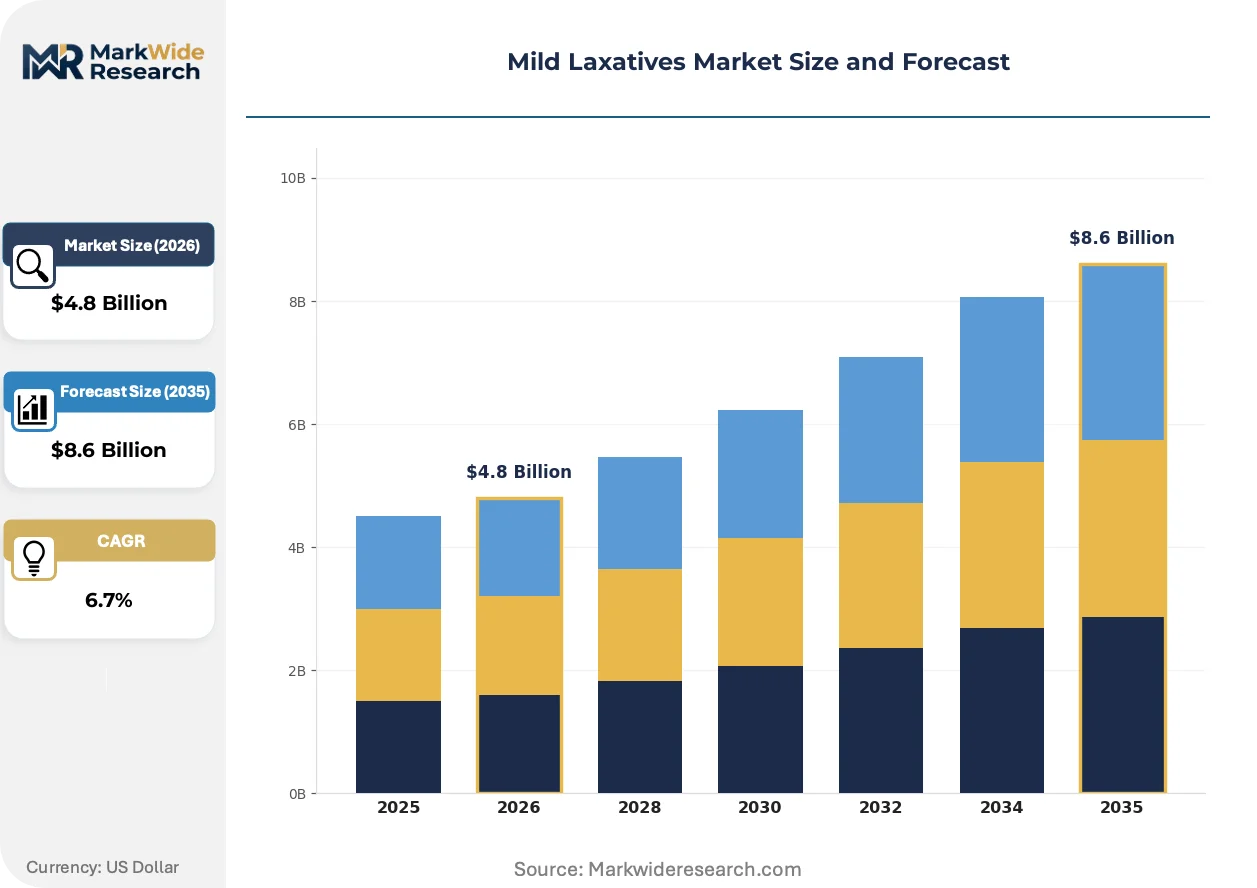
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mild Laxatives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stool Softeners, Bulk Forming Laxatives, Osmotic Laxatives, Lubricant Laxatives Delivery Mode: Tablets, Liquids, Powder, Granules End User: Pharmacies, Hospitals, Online Retailers, Clinics Distribution Channel: Retail, E-commerce, Direct Sales, Wholesalers |
| Companies Covered | F. Hoffmann-La Roche, Sanofi, GlaxoSmithKline, Bayer, Takeda Pharmaceuticals, Abbott Laboratories, Pfizer, AstraZeneca, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mild Laxatives Market Evolving Landscape
Digital health infrastructure is embedding laxative adherence into broader gastrointestinal disease management platforms, shifting competitive advantage from shelf space to data integration capabilities.
Smart packaging with NFC-enabled dosing reminders is digitizing patient compliance tracking for chronic constipation populations. Medicare Advantage plans and integrated delivery networks in the United States are piloting these connected devices to reduce emergency department visits. The technology is digitizing how pharmacy benefit managers evaluate therapeutic outcomes and allocate formulary preference.
REACH-compliant excipient sourcing requirements are tightening supply qualification protocols for European market entry. Manufacturers must now document full substance origin trails for polyethylene glycol and polysorbate derivatives used in pediatric formulations. The regulation most acutely affects private-label exporters from India and China seeking CE-marked distribution.
Direct-to-patient subscription models are fragmenting traditional pharmacy procurement for maintenance laxative users. Telehealth platforms and specialized gastrointestinal clinics are disintermediating retail shelf reliance by delivering bulk-forming and osmotic products on automated refill cycles. This channel shift is most advanced in United States urban corridors with high digital health adoption and value-based care penetration.
Mild Laxatives Market Segmentation
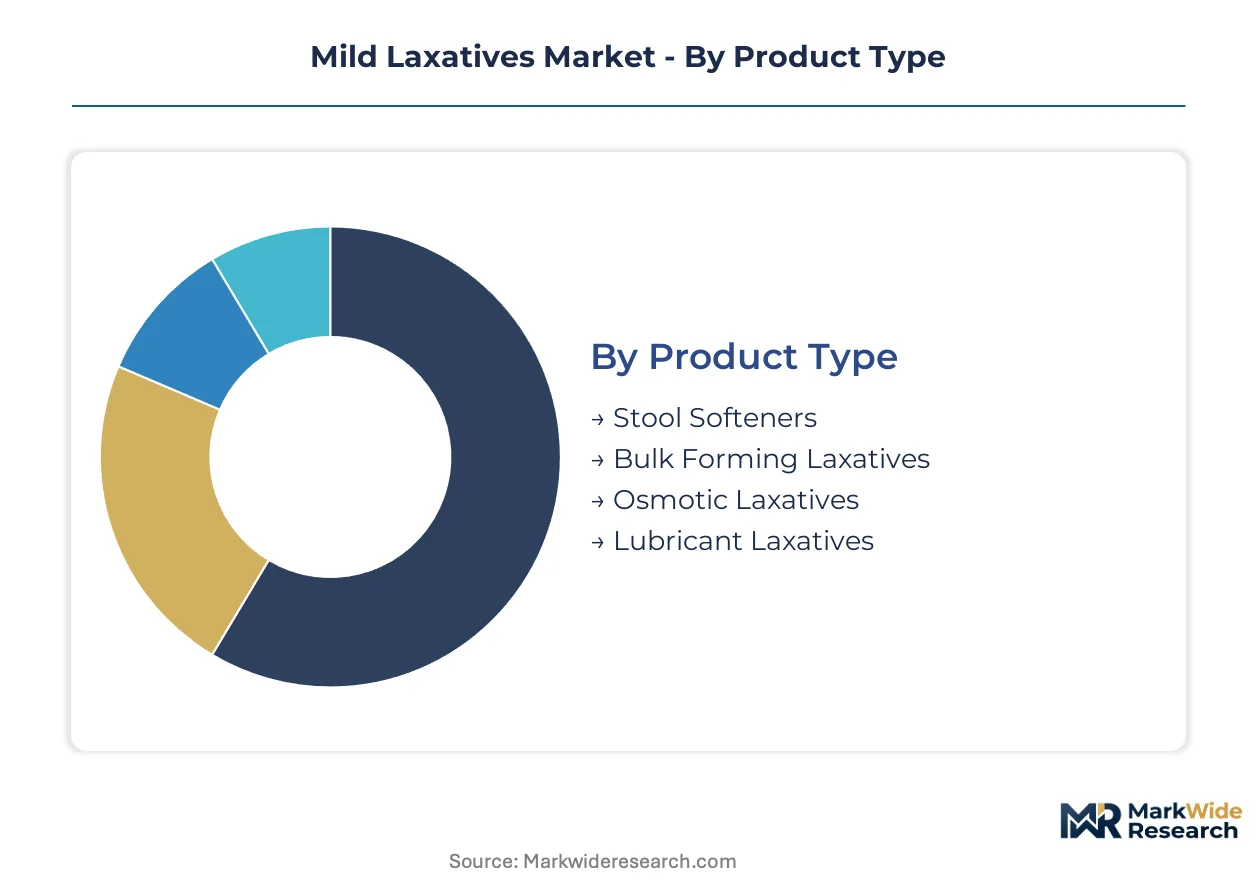
Mild laxatives serve distinct clinical protocols and procurement channels that reshape formulation priorities and margin structures. Segmentation reveals how polyethylene glycol concentration, tablet compression specifications, and liquid palatability engineering align with specific end-user compliance requirements.
Product Type:
After-sales service intensity varies sharply across mechanism-of-action categories, with osmotic formulations demanding clinical education support while bulk-forming products rely on retail shelf positioning.
- Osmotic Laxatives:Polyethylene glycol formulations draw water into intestinal lumen through osmotic pressure without electrolyte disruption. Hospital discharge planning in the United States drives prescriber preference for PEG protocols in pediatric and geriatric populations, though FDA monograph reforms on duration labeling constrain marketing claims.
- Bulk Forming Laxatives:Psyllium husk and methylcellulose absorb water to increase stool mass and stimulate peristalsis. Indian agricultural output fluctuations create raw material cost volatility, compressing margin stability for manufacturers dependent on fiber sourcing.
- Stool Softeners:Docusate sodium reduces surface tension to permit water and fat penetration into stool; FDA-mandated bioequivalence revalidation for legacy products diverts R&D capital from pipeline expansion.
- Lubricant Laxatives:Mineral oil formulations coat intestinal surfaces to ease passage; limited prescriber acceptance in acute care settings restricts formulary placement outside long-term care facilities.
Bulk Forming Laxatives hold the largest share; momentum sits with Osmotic Laxatives.
Delivery Mode:
Cost tier stratification separates premium liquid formulations from economy tablet production, with swallowing-difficulty indications commanding 40-60% price premiums in nursing facility procurement.
- Tablets:Compressed docusate and psyllium products dominate hospital and retail pharmacy procurement through dosing precision and stability profiles. German hospital formulary committees prioritize tablet standardization for polypharmacy compliance in elderly populations.
- Liquids:PEG solutions and flavored mineral oil suspensions address dysphagia prevalence in assisted living centers. Japanese METI-supported digital pharmacy infrastructure accelerates liquid formulation access for the world's oldest population cohort.
- Powder:Reconstitutable psyllium products offer dose flexibility; dietary fiber substitution from direct-to-consumer supplements erodes price-sensitive demand.
- Granules:Effervescent and quick-dissolve formats target pediatric palatability requirements; REACH-compliant excipient sourcing tightens European market entry protocols for polysorbate derivatives.
Tablets command volume leadership; liquids are expanding most quickly in institutional channels.
End User:
Application-driven procurement separates acute clinical settings from maintenance therapy channels, with adherence program revenue fragmenting across integrated delivery networks.
- Pharmacies:Community and chain pharmacies anchor OTC volume through shelf presence and pharmacist counseling; Bayer's consumer health infrastructure sustains multi-continent positioning.
- Hospitals:Acute care formulary decisions prioritize PEG protocols for post-surgical recovery; GlaxoSmithKline's gastrointestinal R&D intensity secures clinician education network advantages.
- Online Retailers:Direct-to-patient subscription models disintermediate traditional procurement through automated refill cycles in United States urban corridors with high digital health adoption.
- Clinics:Specialized gastrointestinal practices integrate laxative prescribing into broader disease management platforms; Medicare Advantage pilot programs embed smart packaging with NFC-enabled dosing reminders.
Pharmacies retain the largest share; clinics are gaining share fastest through value-based care penetration.
Distribution Channel:
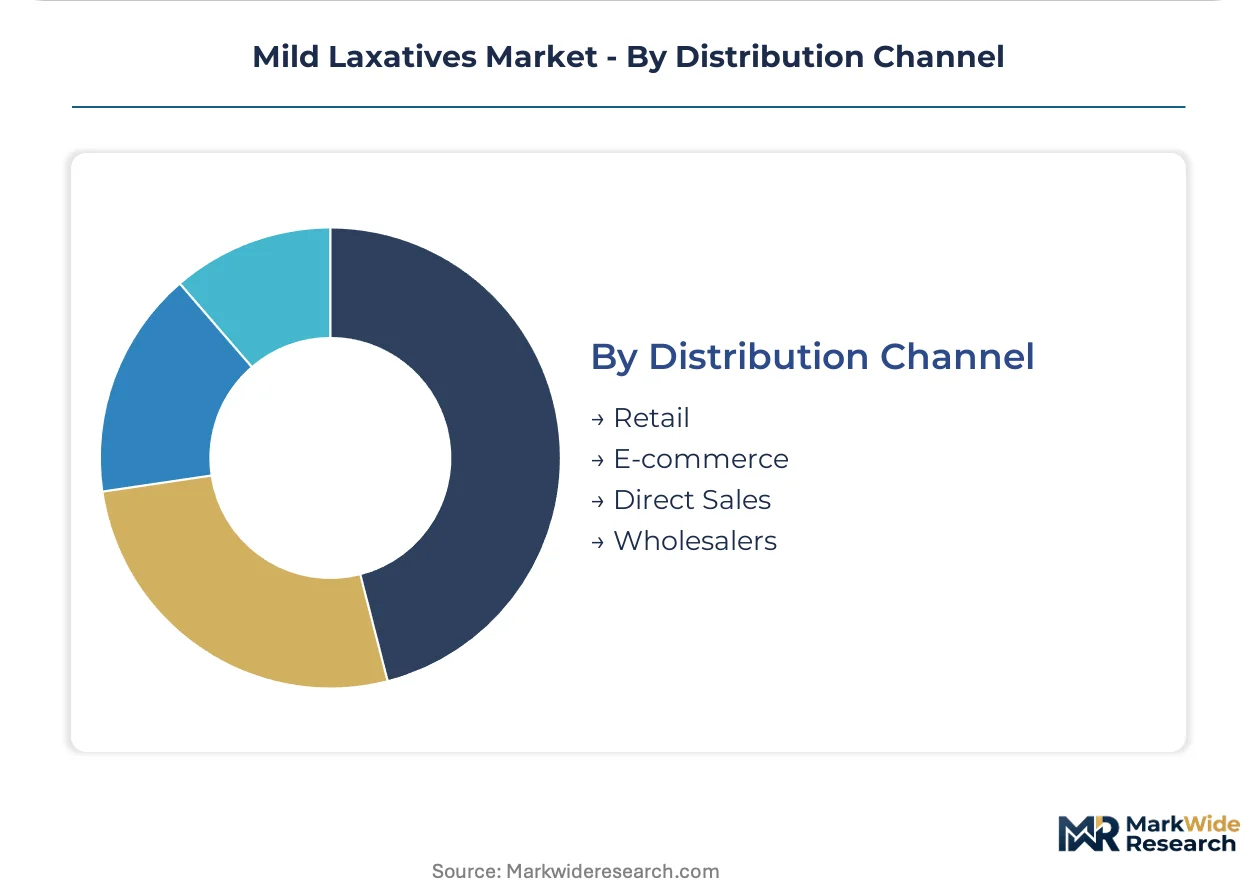
Customer type concentration distinguishes institutional procurement from consumer self-selection, with e-commerce platforms capturing adherence-program revenue streams.
- Retail:Mass-market channel control depends on shelf space negotiation and retail distribution density; Procter & Gamble competes through North American retail penetration.
- E-commerce:Telehealth platform integration enables automated refill cycles and remote patient monitoring revenue beyond product sales.
- Direct Sales:Manufacturer-to-institution contracts secure long-term care facility procurement for liquid formulations addressing swallowing difficulties.
- Wholesalers:Regional distribution networks manage inventory for pharmacy chains; margin compression from generic substitution limits differentiation space.
Retail maintains volume dominance; e-commerce shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between markets where geriatric home-care dominates versus those where pediatric hospital protocols lead formulation preferences. The United States sustains volume leadership through pharmacy access density and aging demographics, while Japan and Germany concentrate demand in institutional channels with distinct regulatory compliance requirements.
United States
FDA monograph reforms on OTC gastrointestinal drugs are compressing formulation flexibility while expanding pediatric safety labeling requirements for manufacturers. Medicare Advantage networks pilot smart packaging with NFC-enabled dosing reminders to reduce emergency department visits among chronic constipation populations. Integrated delivery networks in urban corridors embed laxative adherence into broader gastrointestinal disease management platforms.
Germany
Hospital formulary committees prioritize tablet standardization for polypharmacy compliance in elderly populations across Bavaria and North Rhine-Westphalia. REACH-compliant excipient sourcing requirements tighten supply qualification protocols for European market entry, affecting polysorbate derivatives in pediatric formulations. The country's pharmaceutical manufacturing clusters in Baden-Württemberg concentrate R&D investment in stability testing for liquid PEG products.
Japan
METI-supported digital pharmacy infrastructure accelerates liquid formulation access for the world's oldest population cohort in the Kanto region. PMDA streamlined OTC switches open regulatory pathways for polyethylene glycol protocols previously restricted to prescription channels. Tokyo-based clinician education networks drive prescriber preference for osmotic agents in post-surgical recovery protocols.
India
Psyllium husk supply volatility from agricultural output fluctuations in Gujarat and Rajasthan creates raw material cost instability for bulk-forming laxative producers. CDSCO oversight of active ingredient purity standards governs export qualification for private-label manufacturers seeking European distribution. Mumbai pharmaceutical clusters face margin compression from REACH documentation requirements for full substance origin trails.
United Kingdom
EMA pharmacovigilance frameworks elevate quality-tier manufacturer credibility through standardized adverse event reporting across London and Southeast distribution hubs. NHS procurement patterns favor tablet formulations for community pharmacy dispensing, though liquid demand rises in long-term care facilities. The country's post-Brexit regulatory divergence from EU labeling standards creates revalidation costs for legacy docusate sodium products.
Mild Laxatives Market Competitive Landscape
Capability concentration sits with pharmaceutical R&D specialists; scale advantage sits with consumer health conglomerates with mass-market distribution infrastructure. The market structures around three tiers: prescription-focused innovators with clinician education networks, OTC portfolio owners with pharmacy shelf dominance, and private-label manufacturers serving institutional procurement channels. Dominant competitive moves include portfolio diversification into combination formulations and geographic expansion through regulatory pathway optimization for polyethylene glycol switches.
Among diversified healthcare conglomerates, Bayer and GlaxoSmithKline occupy positions spanning prescription and OTC segments with distinct channel strategies, while Procter & Gamble exemplifies mass-market scale advantage through North American retail penetration. Roche and Sanofi represent the pharmaceutical innovation tier with hospital formulary anchoring capabilities. Takeda Pharmaceuticals exemplifies regional specialization with Asia-Pacific regulatory expertise, while Abbott Laboratories and Pfizer occupy positions in pediatric and geriatric protocol development respectively.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Sanofi |
| GlaxoSmithKline |
| Bayer |
| Takeda Pharmaceuticals |
| Abbott Laboratories |
| Pfizer |
| AstraZeneca |
| Procter & Gamble |
| Others |
Value Network & Pricing Analysis
Gujarat's psyllium husk processing clusters anchor global bulk-forming laxative supply, with seasonal harvest volatility translating directly into quarterly contract renegotiations for North American pharmacy buyers. This agricultural concentration amplifies manufacturer pricing power during monsoon-shortened crop cycles while compressing margins for private-label distributors locked into annual offtake terms.
Pricing Analysis
Long-term offtake contracts dominate polyethylene glycol procurement between Indian API manufacturers and European formulation facilities, though spot-market purchasing persists for psyllium husk during harvest windows. Premium-mid-economy pricing differentiation separates branded osmotic formulations with pediatric palatability engineering from commodity docusate tablets. Cost compression in bulk-forming categories is intensifying because dietary fiber supplements displace price-sensitive maintenance users. Institutional buyers in Medicare Advantage networks exhibit lowest price sensitivity due to adherence-program bundling, while independent pharmacies face highest pressure from generic substitution.
Supply Chain Analysis
Contract-manufacturing concentration for liquid PEG formulations sits with German pharmaceutical clusters in Baden-Württemberg and Hesse, supported by METI-accredited facilities in Japan's Kanto region for Asia-Pacific distribution. Raw material flows draw from Indian psyllium cultivation in Gujarat and Rajasthan, Chinese polyethylene glycol feedstock, and Saudi petrochemical derivatives for polysorbate excipients. Single-source vulnerability concentrates in Indian agricultural output exposed to climate-induced harvest variability. Distribution runs through regional pharmaceutical wholesalers serving pharmacy chains, with direct-to-institution channels gaining share in long-term care liquid formulation procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Medicare Advantage network consolidation and integrated delivery network expansion in United States urban corridors, fragmenting traditional pharmacy channel leverage. This consolidation elevates formulary committee influence over manufacturer pricing and contract terms.
For Market Incumbents: Insulate market position through backward integration into polyethylene glycol API production and captive psyllium husk sourcing contracts in Gujarat. FDA monograph compliance revalidation demands preemptive capital allocation to bioequivalence studies, displacing pipeline investment but preserving formulary access against emerging entrants lacking legacy product portfolios. For New Entrants and Emerging Players: Establish a beachhead in Japan's liquid formulation segment where METI-supported digital pharmacy infrastructure and PMDA streamlined OTC switches reduce regulatory barriers for osmotic agents. Target post-surgical recovery protocols in assisted living centers with swallowing-difficulty indications, leveraging telehealth platform partnerships for automated refill cycle penetration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with pediatric palatability masking capabilities and stability testing infrastructure for liquid PEG products. Long-term viability hinges on regulatory pathway optimization for polyethylene glycol switches and REACH-compliant excipient sourcing documentation. Watch FDA monograph finalization timing as inflection indicator for portfolio revaluation across OTC gastrointestinal categories.| Strategic Initiative | Industry Significance |
|---|---|
| Combination Formulation Development | Stool softener-osmotic hybrids address polypharmacy compliance gaps in opioid-induced constipation protocols. |
| REACH-Compliant Excipient Sourcing | Full substance origin documentation for polysorbate derivatives secures CE-marked European market entry. |
| Smart Packaging Integration | NFC-enabled dosing reminders embed laxative adherence into Medicare Advantage chronic disease management platforms. |
| Home-Care Adherence Programs | Remote patient monitoring integration creates recurring revenue streams beyond product sales in value-based networks. |
| PMDA Regulatory Pathway Optimization | Streamlined OTC switches for polyethylene glycol protocols unlock Japan's aging demographic density. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA monograph filings, EMA pharmacovigilance databases, ClinicalTrials.gov gastrointestinal protocol registrations, and formulary committee documentation. Interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists informed mechanism-of-action preference shifts. Bottom-up volume modeling across product type, delivery mode, end user, and distribution channel segments triangulated against top-down expenditure analysis from CMS Medicare data and pharmacy benefit manager disclosures.
Forecast inputs incorporate pediatric and geriatric population demographics, prescriber protocol adoption curves for polyethylene glycol, and regulatory timeline assumptions across the analysis window. Segmentation dimensions modeled include mechanism of action, formulation type, procurement channel, and regional regulatory cluster alignment. CAGRs derive from slope-intercept analysis of historical volume trajectories adjusted for monograph reform implementation effects and digital health infrastructure penetration rates.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, currency exchange volatility affecting Indian export tariffs, or reimbursement rate adjustments in Medicare Advantage would shift the trajectory. Forecasts reflect documented assumptions regarding FDA monograph finalization timing and EMA-REACH enforcement consistency. Quarterly review of psyllium harvest yields, PMDA OTC switch approval cadence, and Medicare Advantage plan consolidation activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Levothyroxine Sodium Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Retinal Drugs and Biologics Market