
 Pemphigus Vulgaris (PV) Treatment Market | 2026-2036
Pemphigus Vulgaris (PV) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pemphigus Vulgaris (PV) Treatment Market Analysis
Patient referral networks is decoupling from general dermatology practices into dedicated autoimmune blistering centers across major health systems. F. Hoffmann-La Roche Ltd leverages its oncology infrastructure to cross-sell rituximab into dermatology channels. Novartis anchors its position through sustained investment in B-cell targeting platforms. Argenx SE differentiates with its anti-FcRn pipeline, occupying a narrow but high-value mechanistic niche.
Pemphigus Vulgaris treatment encompasses pharmacological interventions targeting autoantibody-mediated acantholysis, primarily deploying corticosteroids, immunosuppressants, and biologics to suppress pathogenic IgG production against desmoglein adhesion proteins. The therapeutic objective centers on achieving rapid disease control while minimizing corticosteroid exposure to prevent infection and metabolic complications. Monoclonal antibodies represent the fastest-expanding segment, capturing disproportionate investment as rituximab biosimilars and novel anti-FcRn agents reshape the standard of care. Intravenous immunoglobulin maintains a stable position in refractory rescue protocols, though its high cost and supply constraints limit broader utilization.
FDA orphan drug incentives and EMA's PRIME designation accelerate development timelines for novel PV therapeutics, compressing the gap between proof-of-concept and commercial availability. The FDA's evolving guidance on steroid-sparing endpoints is forcing sponsors to redesign Phase III protocols around durable remission metrics rather than short-term lesion counts. Stakeholders must monitor how anti-FcRn agents reshape payer formularies and whether biosimilar rituximab entry fragments the biologic segment.
Market Dynamics
The FDA's orphan drug incentives and evolving steroid-sparing endpoint guidance are compressing clinical trial timelines while forcing sponsors to redesign protocols around durable remission metrics rather than short-term lesion clearance.
Growth Catalysts
- EMA PRIME Designation:The European Medicines Agency's priority medicines scheme accelerates assessment timelines for novel PV therapeutics, compressing the gap between proof-of-concept and commercial availability across EU member states.
- Rituximab Biosimilar Entry:Multiple biosimilar manufacturers are expanding manufacturing capacity for anti-CD20 therapies, broadening patient access through price competition in previously supply-constrained markets.
- Anti-FcRn Mechanism Validation:The emergence of neonatal Fc receptor blockade as a validated therapeutic approach is attracting pipeline investment from biologics specialists seeking steroid-sparing alternatives.
Market Restraints
- IVIG Supply Concentration:Intravenous immunoglobulin production depends on plasma fractionation facilities concentrated in the United States and Germany, creating vulnerability to donor pool fluctuations and export restrictions.
- Corticosteroid Dependency:First-line prednisone protocols remain entrenched in community dermatology practices despite biologic availability, slowing mechanistic diversification of treatment algorithms.
- Reimbursement Heterogeneity:Payer coverage for off-label rituximab varies across national health systems, fragmenting access patterns between insured and publicly funded patient populations.
Strategic Opportunities
- Subcutaneous Formulation Development:Route-of-administration innovation targeting self-injection delivery is expanding addressable patient populations beyond infusion center-dependent cohorts.
- Biomarker-Guided Patient Selection:Desmoglein antibody titer stratification is enabling precision enrollment in clinical trials, improving response rates and regulatory submission quality.
- Autoimmune Blistering Center Networks:Dedicated referral hubs within major US health systems are consolidating severe case management, creating concentrated prescriber bases for novel therapy launches.
Industry Challenges
- Specialized Immunopathology Workforce:Diagnostic confirmation requires direct immunofluorescence expertise concentrated in academic medical centers, creating geographic access barriers and diagnostic delays.
- Longitudinal Outcome Data Collection:Relapse tracking across steroid-tapering protocols demands registry infrastructure that most community practices lack, complicating real-world evidence generation.
- Cross-Border Trial Harmonization:Divergent FDA and EMA requirements for steroid-sparing primary endpoints force sponsors to maintain parallel protocol designs, inflating development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pemphigus Vulgaris (PV) Treatment Market |
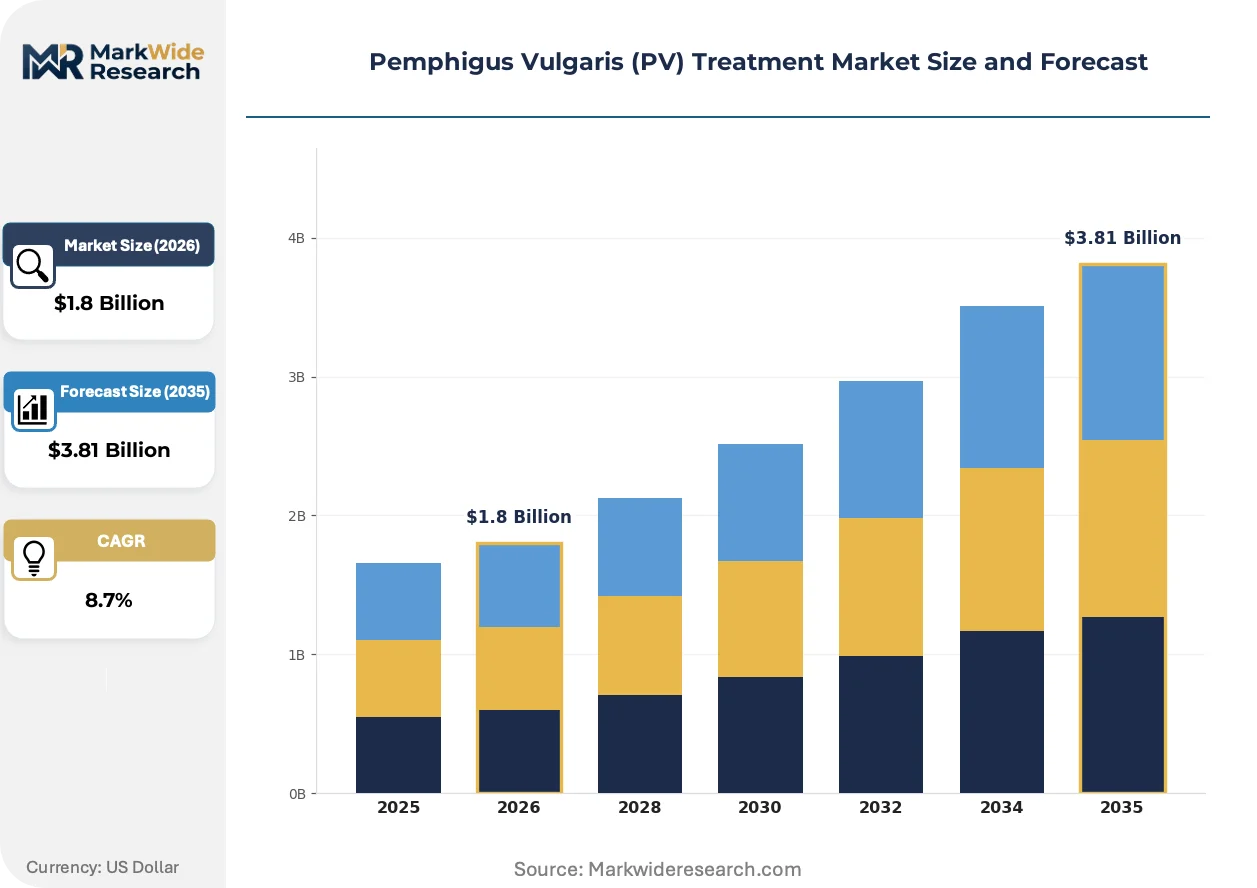
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Monoclonal Antibodies, Intravenous Immunoglobulin Route of Administration: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Specialty Clinics, Homecare, Research Institutes Distribution Channel: Direct Sales, Retail Pharmacies, Online Pharmacies, Wholesale |
| Companies Covered | F. Hoffmann-La Roche Ltd, Novartis AG, Sanofi, Amgen Inc., GlaxoSmithKline plc, Pfizer Inc., AstraZeneca, AbbVie Inc., Argenx SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pemphigus Vulgaris (PV) Treatment Market Emerging Trajectories
Biologic mechanism diversification and regulatory pathway optimization are converging to reshape competitive positioning in autoimmune blistering disorders, with particular acceleration in B-cell depletion and IgG modulation platforms.
Anti-FcRn monoclonal antibodies are rewriting the therapeutic algorithm for refractory PV by accelerating pathogenic IgG clearance without broad immunosuppression. Academic medical centers in the United States are adopting these agents ahead of formal label expansion, driven by steroid-sparing imperatives in metabolically vulnerable patients. The mechanism is compressing the window between diagnosis and biologic initiation, displacing prolonged corticosteroid bridging protocols.
REACH registration requirements in the European Union are tightening traceability standards for plasma-derived products, forcing IVIG manufacturers to reconfigure supply chain documentation systems. The industrial consequence is accelerated investment in recombinant alternatives that bypass human plasma sourcing entirely. Germany and France are most affected, with hospital pharmacy committees now requiring enhanced provenance certification for immunoglobulin procurement.
Patient advocacy networks are consolidating demand-side influence through disease-specific foundations that directly shape payer prior authorization criteria. These organizations are disrupting traditional prescriber-payer negotiations by supplying standardized outcome documentation templates. The shift is most visible in the United States, where the International Pemphigus and Pemphigoid Foundation has established formal collaboration protocols with major commercial insurers.
Pemphigus Vulgaris (PV) Treatment Market Segmentation
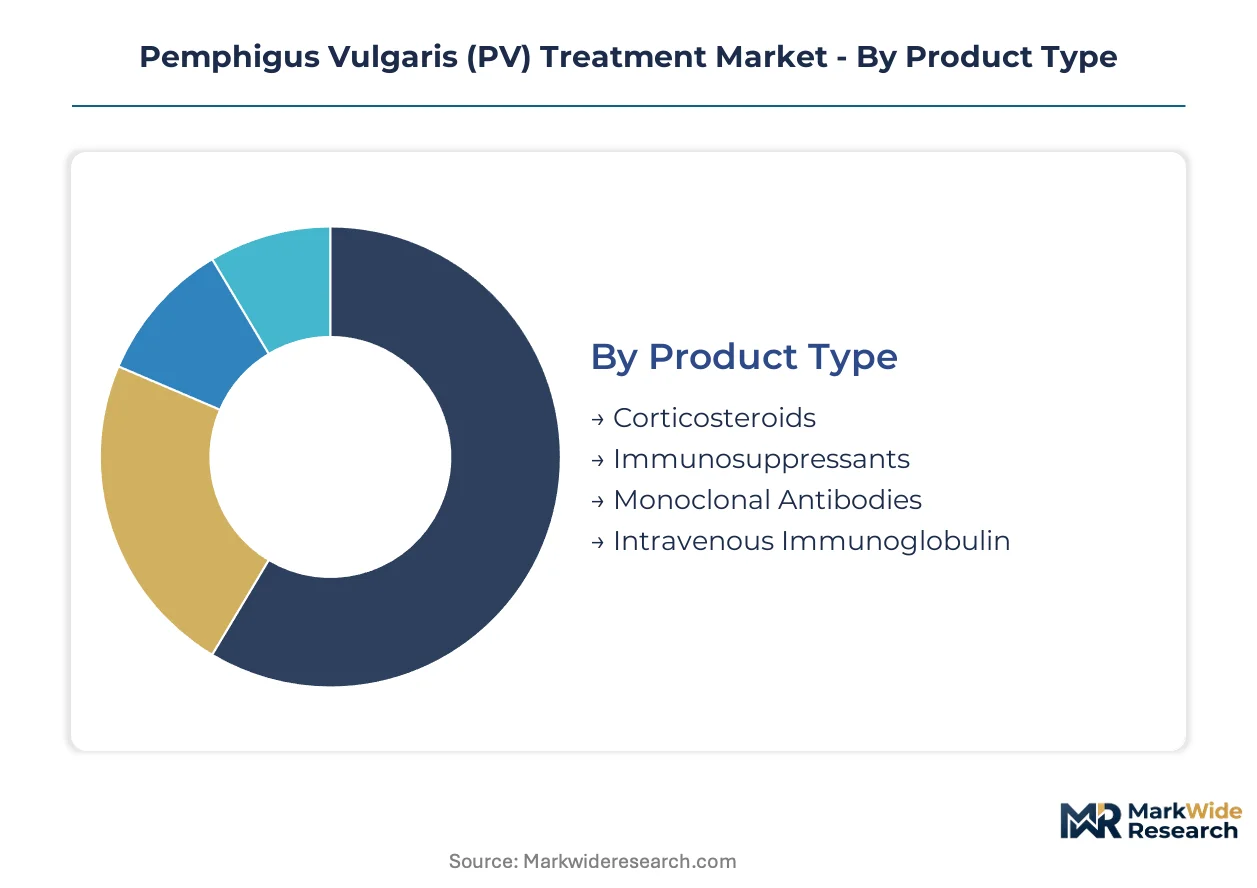
Treatment algorithms for Pemphigus Vulgaris stratify sharply between acute induction protocols and chronic maintenance regimens. Segment boundaries reflect payer reimbursement tiers, infusion center capacity, and prescriber specialty rather than purely clinical indication.
Product Type:
Volume concentration clusters in first-line systemic agents, while premium capture concentrates in biologic mechanisms that enable steroid tapering.
- Corticosteroids:Prednisone and methylprednisolone remain the universal induction backbone across community dermatology and emergency departments. Demand concentrates in the United States and Germany, where high-dose protocols persist despite biologic availability due to formulary inertia and prescriber familiarity.
- Monoclonal Antibodies:Rituximab and emerging anti-FcRn agents command disproportionate revenue per treated patient through infusion-based delivery and specialty pharmacy networks. Academic medical centers in Boston and San Francisco are adopting these agents fastest, driven by steroid-sparing imperatives in metabolically vulnerable patients.
- Immunosuppressants:Azathioprine and mycoprednisolone serve as bridge therapy in resource-constrained settings and steroid-dependent maintenance protocols.
- Intravenous Immunoglobulin:Plasma-derived rescue therapy for rituximab-refractory cases, constrained by donor pool availability and fractionation capacity.
Mature deployment sits with corticosteroids. Newer deployment is concentrated in monoclonal antibodies.
Route of Administration:
Infusion center dependency shapes patient selection and geographic access patterns more than pharmacokinetic optimization.
- Intravenous:Rituximab and IVIG require supervised infusion infrastructure, concentrating utilization in urban hospital systems with dedicated autoimmune infusion suites. The FDA's REMS requirements for biologic monitoring reinforce hospital-based delivery.
- Subcutaneous:Emerging anti-FcRn formulations and biosimilar rituximab variants are expanding addressable populations beyond infusion center catchment areas. Germany's outpatient specialty pharmacy networks are piloting home-based subcutaneous administration for stable maintenance patients.
- Oral:Prednisone, azathioprine, and mycophenolate mofetil dominate community prescribing through retail pharmacy channels.
- Topical:Adjunctive corticosteroid and calcineurin inhibitor preparations for limited mucosal disease, rarely sufficient as monotherapy.
Institutional capacity limits intravenous expansion. Patient convenience is accelerating subcutaneous migration.
End User:
Case complexity and reimbursement intensity determine where novel therapies achieve first adoption versus sustained volume.
- Specialty Clinics:Dedicated autoimmune blistering centers within US academic health systems concentrate biologic prescribing and clinical trial enrollment. The University of Pennsylvania and Stanford Health Care have established formal referral networks that bypass general dermatology for severe cases.
- Hospitals:Emergency departments and inpatient services manage acute flares, sepsis complications, and rituximab induction protocols requiring monitoring.
- Homecare:Subcutaneous formulation availability is expanding skilled nursing and self-injection protocols for maintenance patients with stable disease.
- Research Institutes:Phase II and III trial sites at NIH-funded centers generate protocol-driven demand that precedes commercial availability.
Complex case management concentrates in specialty clinics. Community access depends on hospital infrastructure.
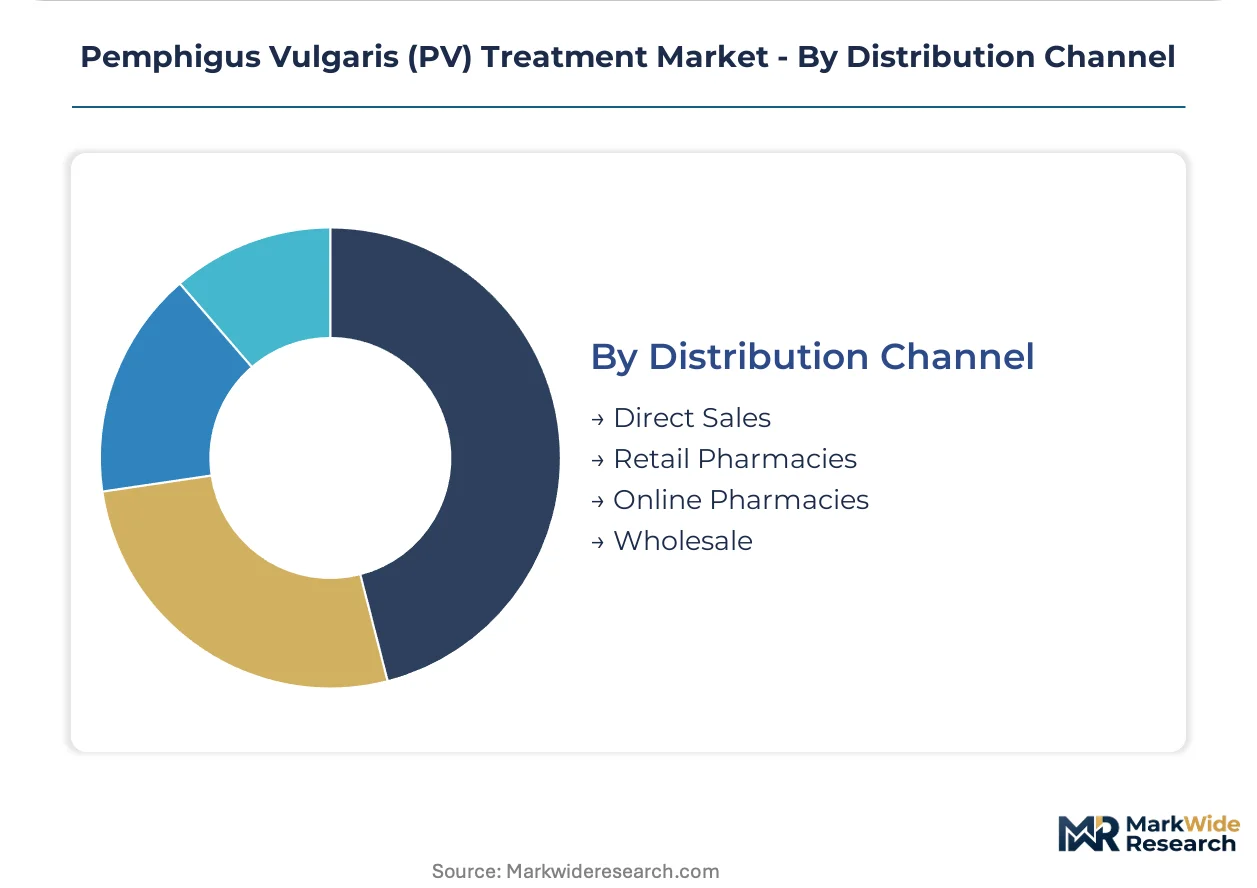
Distribution Channel:
Biologic cold chain requirements and prior authorization complexity fragment channel economics across temperature-controlled logistics and specialty pharmacy networks.
- Direct Sales:Manufacturer-to-hospital contracting dominates rituximab and IVIG procurement through 340B and group purchasing organization arrangements. The Cleveland Clinic and Mayo Clinic systems negotiate directly for biologic supply security.
- Retail Pharmacies:Oral generic immunosuppressants and corticosteroids flow through Walgreens and CVS networks with standard inventory turns.
- Online Pharmacies:Limited to oral maintenance medications in markets with established e-prescription infrastructure.
- Wholesale:McKesson and Cardinal Health distribute plasma-derived products under enhanced traceability protocols mandated by REACH in the European Union.
Biologic procurement centralizes through direct sales. Oral generics fragment across retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologic prescribing for Pemphigus Vulgaris concentrates in health systems with dedicated autoimmune blistering centers and favorable payer coverage for rituximab and emerging anti-FcRn therapies. Regulatory pathway design and plasma fractionation capacity shape regional access patterns.
United States
Academic medical centers in Boston, Philadelphia, and San Francisco drive adoption of steroid-sparing biologics through formal referral networks that bypass general dermatology. The FDA's accelerated approval pathways for orphan indications compress development timelines for novel anti-FcRn agents. The Cleveland Clinic and Mayo Clinic systems negotiate directly with manufacturers for biologic supply security through 340B arrangements.
Germany
Hospital pharmacy committees in Berlin and Munich now require enhanced provenance certification for IVIG procurement under REACH traceability mandates. Outpatient specialty pharmacy networks pilot home-based subcutaneous rituximab administration for stable maintenance patients. The country's plasma fractionation infrastructure anchors European immunoglobulin supply, though donor pool fluctuations create periodic constraints.
Japan
PMDA consultation programs for rare disease therapeutics attract sponsors seeking parallel development with FDA and EMA pathways. Tokyo and Osaka academic centers concentrate direct immunofluorescence diagnostic expertise, creating geographic access barriers for rural patients. Reimbursement negotiations for biologics occur through Chuikyo price assessment processes that reference EU and US pricing benchmarks.
United Kingdom
NICE technology appraisals for rituximab in autoimmune blistering disorders influence prescribing across NHS England specialist dermatology networks. London teaching hospitals and the Manchester Royal Infirmary anchor clinical trial enrollment for emerging B-cell targeting platforms. Post-Brexit divergence from EMA centralized procedures requires sponsors to maintain separate UK regulatory submissions.
France
ANSM oversight of plasma-derived product distribution reinforces hospital-based IVIG utilization rather than community infusion. The Assistance Publique-Hôpitaux de Paris network consolidates severe case management, creating concentrated prescriber bases for novel therapy launches. HAS evaluation of steroid-sparing endpoints shapes reimbursement decisions for biologics in pemphigus indications.
Pemphigus Vulgaris (PV) Treatment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue mechanistic differentiation through neonatal Fc receptor blockade and subcutaneous formulation innovation. The competitive structure stratifies across oncology-crossover players with existing anti-CD20 infrastructure, dedicated autoimmune biologic specialists, and plasma fractionation incumbents with IVIG portfolios. Three archetypes dominate: large-cap diversified pharmaceutical companies with dermatology sales forces, mid-cap biologics specialists with single-mechanism depth, and biosimilar manufacturers expanding manufacturing capacity for rituximab variants. Competitive intensity centers on M&A activity targeting B-cell platform assets and strategic partnerships for subcutaneous delivery technology.
Within the large-cap diversified tier, F. Hoffmann-La Roche Ltd and Novartis AG exemplify oncology infrastructure crossover into dermatology channels. Roche leverages existing rituximab manufacturing and infusion center relationships to maintain position in community and academic settings alike. Novartis anchors its presence through sustained investment in B-cell targeting platforms beyond the anti-CD20 mechanism. Among mechanistic specialists, Argenx SE occupies a narrow but high-value niche with anti-FcRn pipeline assets that address steroid-sparing imperatives in metabolically vulnerable patient populations.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Sanofi |
| Amgen Inc. |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| AstraZeneca |
| AbbVie Inc. |
| Argenx SE |
| Others |
Supply Flow & Price Mechanics
Plasma fractionation capacity in the United States and Germany feeds directly into tiered pricing for immunoglobulin therapies, with donor pool constraints propagating cost premiums downstream to hospital pharmacy committees and specialty infusion centers managing refractory PV cases.
Pricing Analysis
Volume capture clusters in generic corticosteroids and oral immunosuppressants, while margin concentration sits with biologic mechanisms enabling steroid tapering. Three-tier pricing structure across premium monoclonal antibodies, standard maintenance immunosuppressants, and economy corticosteroid protocols reflects reimbursement tier alignment rather than manufacturing cost. Pricing pressure stems from biosimilar rituximab entry compressing anti-CD20 premiums. Community dermatology practices exhibit highest price sensitivity; academic medical centers with 340B status demonstrate lowest sensitivity due to federal pricing advantages.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor cold-chain logistics for plasma-derived products and monoclonal antibodies. Manufacturing draws from concentrated plasma collection networks in the United States and fractionation facilities in Germany and France. Single-source vulnerability characterizes IVIG supply, with donor pool fluctuations in North America creating periodic allocation constraints. Distribution runs through hospital-based specialty pharmacy networks and direct manufacturer contracting with major health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma collection capacity constraints prop pricing power for immunoglobulin manufacturers, while biologic cold-chain infrastructure limits rapid supply expansion in response to demand surges.
For Market Incumbents: Hedge rituximab revenue exposure by accelerating anti-FcRn pipeline investment before biosimilar price erosion penetrates academic medical center formularies. Secure backward integration into plasma collection networks to reduce IVIG supply vulnerability. Prioritize subcutaneous formulation development to expand addressable populations beyond infusion center catchment areas. For New Entrants and Emerging Players: Telemedicine-enabled specialty consultation platforms offer the lowest-barrier entry point for reaching underserved geographic markets lacking direct immunofluorescence diagnostic expertise. Target community dermatology practices in secondary US cities and rural Japan where referral networks to academic centers remain underdeveloped. Pursue strategic partnerships with existing autoimmune blistering foundations to streamline prior authorization documentation. For Investors and Strategic Acquirers: FDA accelerated approval for novel anti-FcRn mechanisms is the leading indicator that steroid-sparing endpoints have achieved regulatory validation sufficient to support premium pricing. Long-term viability hinges on B-cell platform durability rather than single-asset exposure. Monitor EMA PRIME designation patterns as early signals of EU reimbursement trajectory for emerging mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Route innovation expands patient access beyond infusion center infrastructure constraints. |
| Plasma Collection Network Expansion | Upstream capacity secures IVIG supply stability against donor pool volatility. |
| Biomarker-Guided Trial Design | Desmoglein antibody stratification improves regulatory submission quality and response rates. |
| Autoimmune Blistering Center Partnerships | Formal referral protocols concentrate prescriber access for novel therapy launches. |
| Biosimilar Manufacturing Scale-Up | Anti-CD20 capacity expansion broadens patient access through price competition. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with formulary directors, hospital procurement managers, payer access specialists, and clinical trial investigators. FDA submissions, EMA assessment reports, ClinicalTrials.gov entries, and hospital procurement databases provided validation anchors. Bottom-up patient-flow modeling and top-down revenue triangulation converged on segment estimates.
Data-stream reconciliation across epidemiological prevalence estimates, treatment algorithm adoption curves, and biologic penetration rates generated volume and value outputs across the projection horizon. Segmentation dimensions encompassed treatment line, route of administration, end-user facility type, and regional regulatory cluster. CAGRs derived from fitted adoption curves incorporating payer coverage expansion scenarios and biosimilar entry timing assumptions.
The model holds under stable plasma collection rates and continued payer coverage for biologic therapies; deviation in donor pool availability or reimbursement policy shifts would revise immunoglobulin and anti-CD20 forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Ulcerative Colitis Market