
 Global Acquired Aplastic Anemia Market | 2026-2036
Global Acquired Aplastic Anemia Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acquired Aplastic Anemia Market Foresight
Aftermarket patient monitoring and long-term immunosuppressive management is rewriting how pharmaceutical margins accumulate across the treatment lifecycle. Novartis AG leverages its transplant medicine portfolio to sustain presence in high-complexity care settings. Amgen Inc. anchors its position through hematopoietic growth factor specialization, while Pfizer Inc. competes via broad immunology manufacturing scale.
Acquired aplastic anemia denotes a hematologic condition characterized by immune-mediated destruction of hematopoietic stem cells in bone marrow, resulting in pancytopenia and requiring intervention through immunosuppression or stem cell replacement to restore blood cell production. The condition demands sustained therapeutic management to prevent hemorrhage, infection, and organ failure in affected patients. Among therapy areas, severe aplastic anemia commands the dominant share due to urgent intervention requirements and higher per-patient treatment intensity, while very severe aplastic anemia represents the fastest-growing subsegment driven by expanded diagnostic screening and earlier detection protocols. Immunosuppressants retain the largest product type position, though bone marrow transplantation carries premium pricing and concentrated margin pools tied to specialized center accreditation.
FDA orphan drug designations and EMA priority medicine pathways shape development incentives and accelerate market access for novel therapies targeting rare hematologic indications. REACH compliance and WHO Good Manufacturing Practice standards govern raw material sourcing and biologic production consistency across international supply chains. Stakeholders must monitor evolving reimbursement criteria for combination immunosuppressive regimens and transplant procedures across national health systems.
Market Dynamics
The transition from institutional transplant volume toward outpatient immunosuppressive maintenance is compressing revenue recognition timelines and forcing manufacturers to restructure field medical deployment around chronic care sites rather than acute centers.
Growth Catalysts
- EMA Priority Medicine Pathways:Accelerated assessment procedures for severe aplastic anemia therapies reduce development-to-approval intervals, incentivizing biologics investment across European hematology networks.
- Expanded Diagnostic Screening:Earlier detection protocols in Japanese metropolitan health systems are converting subclinical cases into treatable patient populations before progression to very severe classification.
- Specialized Center Accreditation:Concentration of bone marrow transplant procedures in German university hospitals generates referral network effects that sustain procedure volume and associated pharmaceutical offtake.
Market Restraints
- Biologic Input Concentration:Recombinant protein production depends on Chinese hamster ovary cell line supply chains concentrated in single-source contract manufacturing organizations.
- Transplant Cost Barriers:Allogeneic stem cell replacement requires sustained hospitalization and graft-versus-host prophylaxis that exhausts lifetime insurance caps in United States commercial coverage structures.
- Regulatory Divergence:FDA's risk evaluation and mitigation strategy requirements for immunosuppressants create protocol complexity that delays trial initiation relative to EMA adaptive pathway designs.
Strategic Opportunities
- Brazilian Public Health Expansion:ANVISA's rare disease framework and Ministry of Health reimbursement inclusion for aplastic anemia creates accessible volume in Latin America's largest single-payer system.
- Digital Therapeutic Adjuncts:Remote patient monitoring platforms for neutropenic fever surveillance are converging with existing pharmaceutical regimens to enable home-based care transitions.
- Companion Diagnostic Integration:HLA typing automation and next-generation sequencing cost reductions allow pre-emptive donor identification that accelerates transplant eligibility determination.
Industry Challenges
- Hematopoietic Stem Cell Processing:Cord blood banking standardization delays and cryopreservation protocol variability create graft quality uncertainty that complicates transplant scheduling.
- Specialized Nursing Shortage:Apheresis and stem cell collection certification programs produce insufficient trained personnel relative to expanding transplant center capacity in United States and German markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acquired Aplastic Anemia Market |
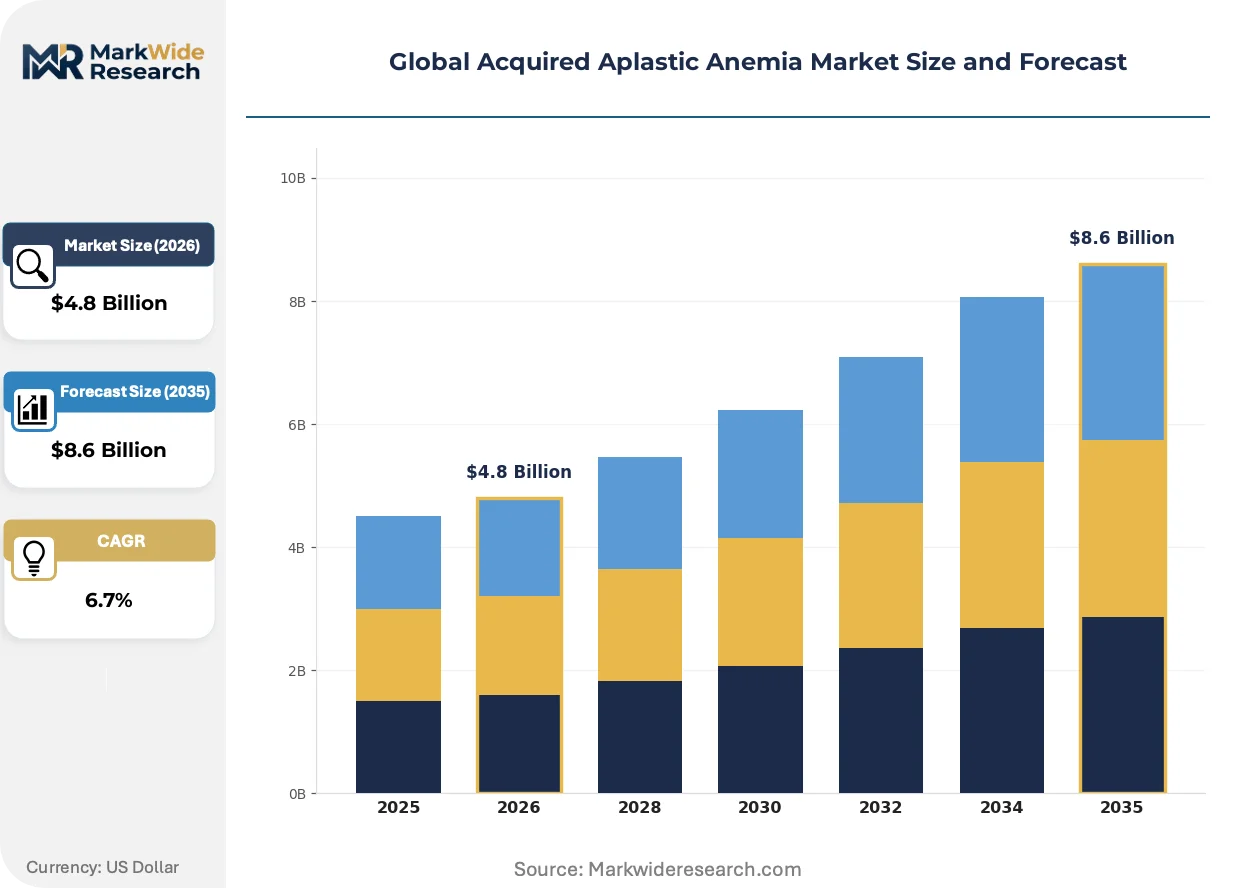
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Hematopoietic Growth Factors, Blood Transfusion Products, Bone Marrow Transplantation, Others Therapy Area: Severe Aplastic Anemia, Non-Severe Aplastic Anemia, Very Severe Aplastic Anemia, Chronic Aplastic Anemia End User: Hematology Clinics, Transplant Centers, Specialty Hospitals, Blood Banks, Diagnostic Laboratories Delivery Mode: Oral Tablets, Intravenous Infusion, Subcutaneous Injection, Transfusion, Surgical Procedure |
| Companies Covered | Teva Pharmaceuticals, Kyowa Kirin Co., Ltd., Novartis AG, Baxter, Pfizer Inc., GSK, Amgen Inc., Partner Therapeutics, Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acquired Aplastic Anemia Market Shifts & Advancements
Virtual care infrastructure and real-time biomarker monitoring are dissolving the historical boundary between acute transplant intervention and chronic immunosuppressive management.
Next-generation sequencing-based minimal residual disease assessment is virtualizing the traditional bone marrow biopsy workflow for treatment response evaluation. Academic medical centers in the United States and Japan are adopting circulating cell-free DNA platforms to reduce invasive monitoring frequency. This shift is virtualizing the physical site-of-care requirement for disease surveillance, enabling decentralized patient management.
REACH compliance extensions for pharmaceutical intermediates are tightening solvent residue specifications in immunosuppressive active pharmaceutical ingredient synthesis. European contract manufacturers face reformulation costs to meet updated substance of very high concern thresholds. Synthetic chemistry suppliers serving the aplastic anemia pipeline are responding by relocating production to facilities with dedicated containment infrastructure.
Consolidation among United States specialty pharmacy distributors is compressing patient access channel options for oral immunosuppressive therapies. Payer-owned pharmacy benefit managers are mandating exclusive dispensing relationships that displace independent hemophilia and oncology pharmacy networks. This concentration is most visible in Medicare Part D coverage determinations where limited distribution networks restrict patient choice of infusion site.
Global Acquired Aplastic Anemia Market Segmentation
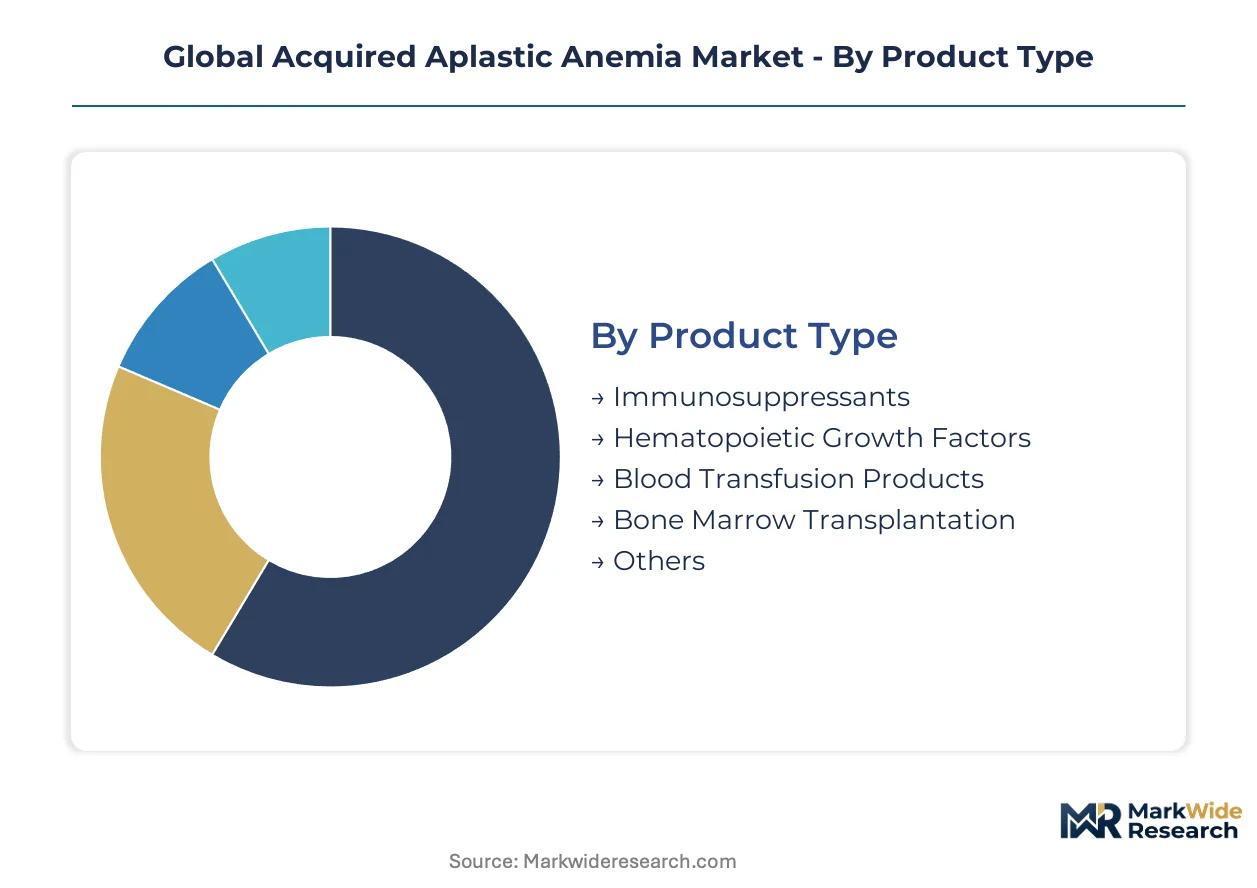
Segmentation in the acquired aplastic anemia market reveals distinct margin profiles tied to intervention intensity and site-of-care requirements. Each dimension shapes procurement patterns, reimbursement negotiation leverage, and manufacturer field deployment priorities across the treatment continuum.
Product Type:
Cost tier stratification separates chronic maintenance therapies from acute intervention modalities with divergent pricing power and reimbursement durability.
- Immunosuppressants:Cyclosporine and anti-thymocyte globulin regimens form the pharmacologic backbone of first-line non-transplant management. Demand concentrates in United States outpatient hematology clinics where Medicare Part B infusion reimbursement sustains margin pools, though payer-owned pharmacy benefit managers are compressing dispensing channel options through exclusive network mandates.
- Bone Marrow Transplantation:Allogeneic stem cell replacement commands premium pricing tied to specialized center accreditation and graft-versus-host prophylaxis protocols. German university hospitals generate concentrated procedure volume through referral network effects that sustain associated pharmaceutical offtake for conditioning regimens and post-transplant maintenance.
- Hematopoietic Growth Factors:Recombinant protein stimulants address neutropenia and thrombocytopenia in supportive care protocols.
- Blood Transfusion Products:Irradiated cellular components manage hemorrhage and anemia complications pending definitive therapy.
- Others:Androgen derivatives and experimental modalities occupy niche salvage indications.
Immunosuppressants command the established base. The steepest expansion runs through bone marrow transplantation as diagnostic screening protocols convert subclinical cases earlier in disease progression.
Therapy Area:
Disease severity classification determines intervention urgency, per-patient treatment intensity, and site-of-care requirements across the clinical spectrum.
- Severe Aplastic Anemia:Bone marrow cellularity below 25% with severe neutropenia triggers immediate immunosuppression or transplant evaluation. United States transplant centers are expanding treatment capacity as the primary adoption channel, with FDA orphan drug designations accelerating development timelines for novel therapies targeting this indication.
- Very Severe Aplastic Anemia:Absolute neutrophil counts below 200 per microliter demand emergent intervention with the highest per-patient resource consumption. Japanese metropolitan health systems are driving case volume growth through expanded diagnostic screening that captures patients before progression to this classification.
- Non-Severe Aplastic Anemia:Moderate cytopenias permit observation or delayed intervention in select patients.
- Chronic Aplastic Anemia:Persistent disease requiring long-term transfusion dependence or maintenance immunosuppression.
Severe aplastic anemia anchors current revenue concentration. Very severe aplastic anemia is climbing the fastest as earlier detection protocols reshape addressable patient populations.
End User:
Site-of-care configuration dictates procurement authority, reimbursement pathway complexity, and pharmaceutical manufacturer account management resource allocation.
- Transplant Centers:Accredited programs concentrate high-complexity procedures and associated pharmaceutical consumption in academic medical center settings. German and United States facilities are expanding capacity to meet referral demand, with specialized nursing shortages emerging as a binding constraint on volume growth.
- Hematology Clinics:Community and hospital-based practices manage chronic immunosuppressive maintenance and transfusion protocols. The transition from institutional transplant volume toward outpatient maintenance is compressing revenue recognition timelines and forcing restructuring of field medical deployment around chronic care sites.
- Specialty Hospitals:Dedicated oncology and blood disorder institutions with focused infrastructure.
- Blood Banks:Cellular product suppliers supporting transfusion-dependent patient management.
- Diagnostic Laboratories:Testing facilities enabling disease classification and treatment monitoring.
Transplant centers retain the premium intervention base. Hematology clinics are gaining share fastest as care models shift toward decentralized chronic management.
Delivery Mode:
Administration route shapes patient compliance requirements, healthcare professional training demands, and site-of-care flexibility across treatment phases.
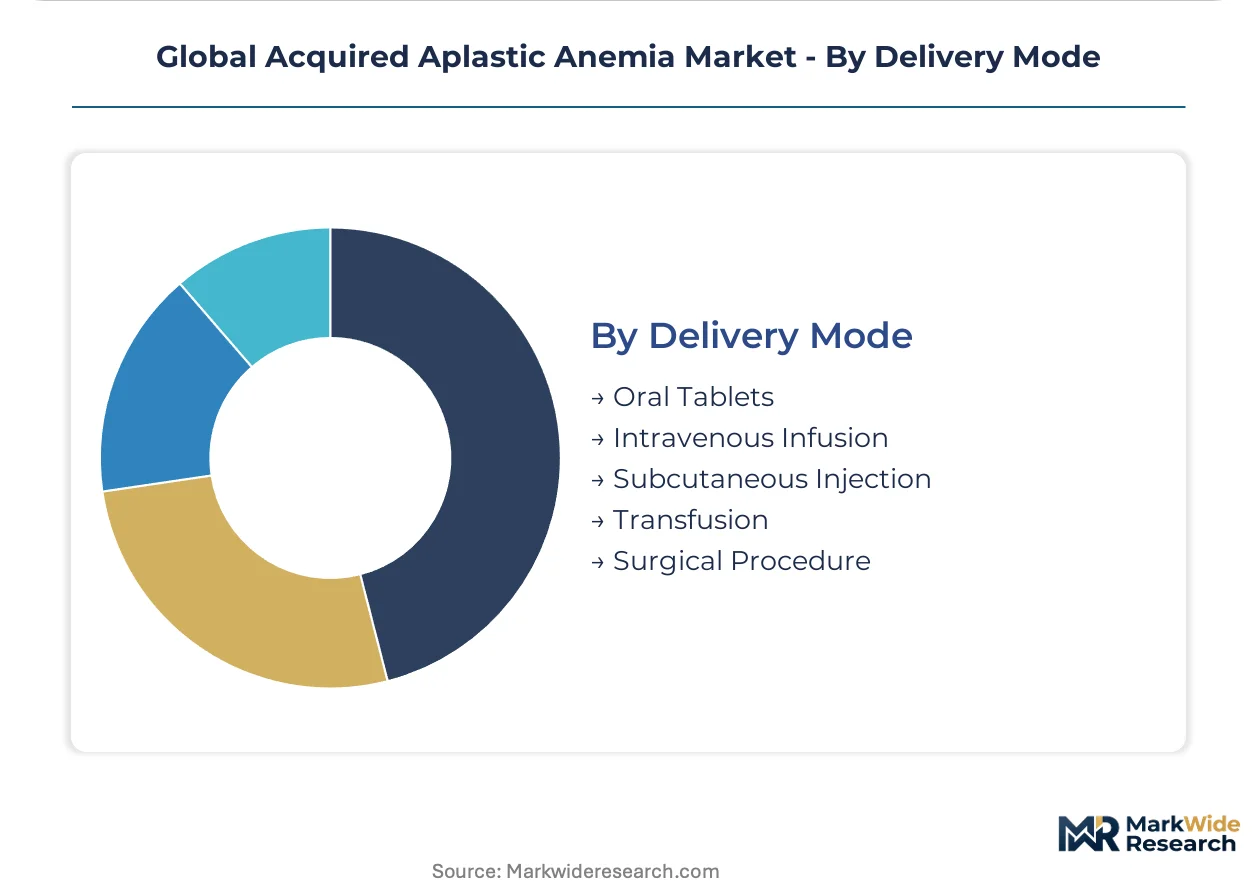
- Intravenous Infusion:Hospital or infusion center administration for immunosuppressive induction and blood product delivery. REACH compliance extensions for pharmaceutical intermediates are tightening solvent residue specifications in active pharmaceutical ingredient synthesis, with European contract manufacturers facing reformulation costs.
- Oral Tablets:Cyclosporine and tacrolimus maintenance enable home-based chronic management. Consolidation among United States specialty pharmacy distributors is compressing patient access channel options, with payer-owned pharmacy benefit managers mandating exclusive dispensing relationships.
- Subcutaneous Injection:Growth factor self-administration in neutropenic fever prophylaxis protocols.
- Transfusion:Cellular product delivery requiring irradiated component availability.
- Surgical Procedure:Bone marrow harvest and stem cell infusion interventions.
Intravenous infusion anchors acute intervention revenue. Oral tablets are expanding most quickly as virtual care infrastructure dissolves boundaries between acute and chronic management phases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate lowest price elasticity due to comprehensive public reimbursement frameworks, while United States commercial coverage structures expose patients to transplant cost barriers that compress demand. Price sensitivity concentrates where insurance caps exhaust and out-of-pocket obligations accumulate.
United States
FDA orphan drug designations and expanded transplant center capacity drive pharmaceutical investment toward severe aplastic anemia indications. Medicare Part B infusion reimbursement sustains outpatient immunosuppressive margins, though payer-owned pharmacy benefit managers are compressing oral therapy dispensing channels through exclusive network mandates. Boston and New York academic medical centers anchor specialized hematology infrastructure that generates referral concentration.
Germany
EMA priority medicine pathways accelerate biologics development timelines across European hematology networks. University hospitals in Munich and Heidelberg concentrate bone marrow transplant volume through specialized center accreditation that sustains procedure referral networks. REACH compliance extensions for pharmaceutical intermediates are tightening solvent residue specifications in active pharmaceutical ingredient synthesis.
Japan
Metropolitan health systems in Tokyo and Osaka deploy expanded diagnostic screening protocols that convert subclinical cases into treatable populations before progression to very severe classification. PMDA regulatory frameworks align with international standards while maintaining distinct post-market surveillance requirements. Japanese transplant centers are expanding apheresis and stem cell collection capacity to address trained personnel shortages.
Brazil
ANVISA's rare disease framework and Ministry of Health reimbursement inclusion for aplastic anemia creates accessible volume in Latin America's largest single-payer system. São Paulo and Rio de Janeiro concentrate specialized hematology infrastructure that supports immunosuppressive therapy distribution. Public health expansion programs are converting previously untreated patient populations into addressable demand.
United Kingdom
NHS England specialized commissioning frameworks concentrate severe aplastic anemia care in designated supra-regional centers. London and Manchester anchor transplant networks that manage complex cases through centralized referral pathways. MHRA regulatory alignment with EMA standards facilitates parallel market access for novel immunosuppressive therapies.
Global Acquired Aplastic Anemia Market Competitive Landscape
Capability concentration sits with specialized hematology and transplant medicine portfolios; scale advantage sits with broad immunology manufacturing infrastructure. The market structure separates into two functional tiers: integrated biopharmaceutical conglomerates with cross-therapeutic manufacturing scale, and focused hematology specialists with deep clinical development expertise in rare blood disorders. Three archetypes dominate competitive positioning: transplant medicine platform builders, hematopoietic growth factor specialists, and immunosuppressive therapy generalists. Dominant competitive moves include strategic partnerships with academic medical centers for real-world evidence generation, and geographic licensing arrangements to access emerging market reimbursement frameworks.
Within the integrated biopharmaceutical tier, Novartis AG and Pfizer Inc. occupy positions shaped by transplant medicine portfolio breadth and immunology manufacturing scale respectively. Amgen Inc. represents the hematopoietic growth factor specialist archetype with recombinant protein production capabilities. These three companies exemplify how competitive positioning in acquired aplastic anemia derives from upstream control over biologic manufacturing infrastructure and downstream relationships with specialized transplant center networks.
| Leading Market Players |
|---|
| Teva Pharmaceuticals |
| Kyowa Kirin Co., Ltd. |
| Novartis AG |
| Baxter |
| Pfizer Inc. |
| GSK |
| Amgen Inc. |
| Partner Therapeutics, Inc. |
| Sanofi |
| Others |
Supply & Pricing Matrix
Chinese hamster ovary cell line production clusters in Suzhou and Shanghai anchor recombinant protein supply for hematopoietic growth factors, with capacity constraints translating directly into pricing power for contract manufacturers serving immunosuppressive therapy developers.
Pricing Analysis
Aftermarket patient monitoring and long-term immunosuppressive management drives lifetime value accumulation across the treatment lifecycle. Three-tier pricing structure across premium transplant center bundles, standard outpatient clinic protocols, and economy transfusion-dependent maintenance tiers separates intervention intensity levels. Cost compression in oral maintenance therapies intensifies as payer-owned pharmacy benefit managers mandate exclusive dispensing networks. Uninsured and underinsured patient segments exhibit highest price sensitivity, while German and Japanese public reimbursement frameworks insulate transplant-eligible populations from out-of-pocket exposure.
Supply Chain Analysis
Export-control restrictions on gene-editing technologies and CRISPR-related reagents limit flows of advanced therapeutic inputs between United States and Chinese research institutions. Active pharmaceutical ingredient synthesis concentrates in India and China, with European contract manufacturing serving high-containment immunosuppressive production. Recombinant protein production rests on Chinese hamster ovary cell lines, synthetic chemistry intermediates, and cryopreservation media. Single-source contract manufacturing organization vulnerability creates graft-quality uncertainty that complicates transplant scheduling. Distribution runs through specialty pharmacy networks and hospital-based infusion centers with limited distribution network mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term immunosuppressive maintenance and remote patient monitoring services expand faster than acute transplant hardware, creating durable recurring revenue layers that reshape pharmaceutical margin profiles across the treatment continuum.
For Market Incumbents: Entrench position through backward integration into recombinant protein production capacity and captive supply of Chinese hamster ovary cell line infrastructure. Novartis AG and Amgen Inc. should consolidate relationships with German university hospital referral networks to defend against emerging biosimilar pressure. FDA risk evaluation and mitigation strategy complexity creates regulatory moats that favor established players with dedicated compliance infrastructure. For New Entrants and Emerging Players: Brazilian public health expansion under ANVISA's rare disease framework represents the most penetrable entry point for immunosuppressive therapy manufacturers seeking volume access in single-payer systems. Digital therapeutic adjuncts for neutropenic fever surveillance in Japanese metropolitan health systems offer a second white-space target with lower regulatory barriers than core pharmaceutical development. Partner with academic medical centers for real-world evidence generation to accelerate reimbursement inclusion. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hematopoietic growth factor specialists with recombinant protein manufacturing scale and transplant medicine platform builders with deep academic medical center relationships. Long-term viability hinges on chronic care model transition durability rather than acute intervention volume. Acquisition targets should demonstrate established limited distribution network access and payer contracting leverage. Watch for inflection signals in Medicare Part D coverage determination shifts for oral immunosuppressive therapies.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA orphan drug designations accelerate development timelines for severe aplastic anemia indications. |
| Manufacturing Scale-Up | Chinese hamster ovary cell line capacity expansion reduces single-source dependency for growth factor supply. |
| Regulatory Approval Pathway | EMA priority medicine pathways reduce European hematology network access intervals for novel biologics. |
| Licensing Agreement | Geographic licensing arrangements unlock Brazilian Ministry of Health reimbursement inclusion. |
| Pipeline Diversification | Next-generation sequencing companion diagnostics enable pre-emptive donor identification acceleration. |
Research Methodology
The analysis maps immunosuppressant regimens, bone marrow transplantation protocols, hematopoietic growth factor applications, and blood transfusion product categories, each validated through hematology clinic directors, transplant center administrators, payer formulary directors, and pharmaceutical regulatory affairs leads. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases enable bottom-up and top-down triangulation across the acquired aplastic anemia treatment continuum.
Assumptions held fixed include current regulatory pathway structures and reimbursement framework stability, while patient population growth and diagnostic screening expansion rates varied across modeling scenarios. Segmentation dimensions encompass therapy area severity classification, product type intervention modality, end-user site-of-care configuration, and regional regulatory cluster. CAGRs derive from patient volume projections tied to expanded diagnostic protocols and per-patient treatment intensity assumptions, with transplant center capacity expansion and specialty nursing shortage constraints incorporated as industry-specific forecast inputs.
Practitioners should monitor EMA adaptive pathway design evolution, FDA risk evaluation and mitigation strategy modifications, and Brazilian ANVISA rare disease framework implementation pace for early signals of forecast revision necessity. Forecasts reflect documented assumptions regarding immunosuppressive therapy reimbursement durability and transplant center accreditation concentration. Material shifts in Medicare Part B infusion reimbursement policy or REACH compliance extension stringency for pharmaceutical intermediates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Gastritis Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market