
 Necrotizing Fasciitis Market | 2026-2036
Necrotizing Fasciitis Market Size, Share, and Industry Trends Forecast 2026-2036
Necrotizing Fasciitis Market Foresight
Next-generation rapid molecular diagnostics is rewriting how clinicians identify necrotizing fasciitis pathogens before tissue destruction escalates. Pfizer Inc. leverages its broad-spectrum antibiotic portfolio to anchor hospital formulary positioning. Merck & Co., Inc. sustains competitive presence through carbapenem-class leadership in severe polymicrobial infections. Gilead Sciences Inc. differentiates via antiviral and antifungal adjacencies that address atypical pathogen presentations.
Necrotizing fasciitis constitutes a rapidly progressive soft-tissue infection characterized by widespread fascial necrosis, typically triggered by polymicrobial invasion through compromised skin barriers, with mortality exceeding 25% without prompt surgical debridement and targeted antimicrobial therapy. The condition demands immediate operative intervention combined with broad-spectrum intravenous antibiotics to halt fascial spread and sepsis progression. Among therapy area segments, critical care commands the deepest margin pools due to prolonged ICU stays and multi-modal intervention requirements. Surgical equipment within product type segments occupies the fastest-expanding niche as minimally invasive debridement technologies gain traction in tertiary centers.
The FDA's Qualified Infectious Disease Product designation shapes development incentives by granting priority review and extended market exclusivity for novel antibiotics targeting resistant pathogens. EMA's infectious disease guidance and WHO's Essential Medicines List criteria further constrain formulary access and reimbursement thresholds across regulated markets. Stakeholders must monitor how regulatory pathways for combination diagnostic-therapeutic protocols reshape competitive entry barriers and clinical trial design requirements.
Market Dynamics
The FDA's Qualified Infectious Disease Product program is compressing development timelines for novel antibiotics while trauma centers expand combination antibiotic protocols, creating a dual pressure on manufacturers to accelerate innovation while maintaining surgical precision.
Growth Catalysts
- QIDP Acceleration:The FDA's priority review pathway grants extended market exclusivity for resistant-pathogen antibiotics, incentivizing R&D investment in gram-positive and polymicrobial coverage agents.
- Critical Care Infrastructure:United States trauma center density supports aggressive surgical intervention protocols, concentrating demand for rapid molecular diagnostics and broad-spectrum IV formulations.
- Next-Generation Sequencing:Rapid pathogen identification technologies enable targeted antimicrobial selection within hours rather than days, reducing empiric therapy duration and improving patient outcomes.
Market Restraints
- Antibiotic Stewardship Constraints:Hospital formulary restrictions and CDC stewardship mandates limit broad-spectrum prescribing, compressing utilization rates for newer agents regardless of clinical efficacy.
- Specialized Surgical Capacity:Tertiary center concentration in urban corridors creates geographic access barriers, delaying debridement in rural and underserved catchment areas.
- Reimbursement Compression:Medicare severity-adjusted DRG classifications inadequately capture the resource intensity of prolonged ICU stays and repeated operative interventions.
Strategic Opportunities
- Diagnostic-Therapeutic Bundling:FDA breakthrough device designation pathways enable simultaneous approval of rapid molecular tests with companion antibiotic protocols, creating integrated product positioning.
- Minimally Invasive Debridement:Hydro-surgical and ultrasonic tissue removal systems address unmet need in extremity-sparing surgery, opening premium equipment segments in academic medical centers.
- Tele-ICU Integration:Remote critical care consultation networks extend specialist oversight to community hospitals, expanding addressable patient volume beyond traditional referral patterns.
Industry Challenges
- Infectious Disease Specialist Shortage:Fellowship-trained clinicians concentrate in coastal academic institutions, creating diagnostic and therapeutic expertise gaps in secondary markets.
- Clinical Trial Enrollment:Rare disease incidence and emergency presentation windows complicate randomized controlled study design for novel agents targeting necrotizing fasciitis specifically.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Necrotizing Fasciitis Market |
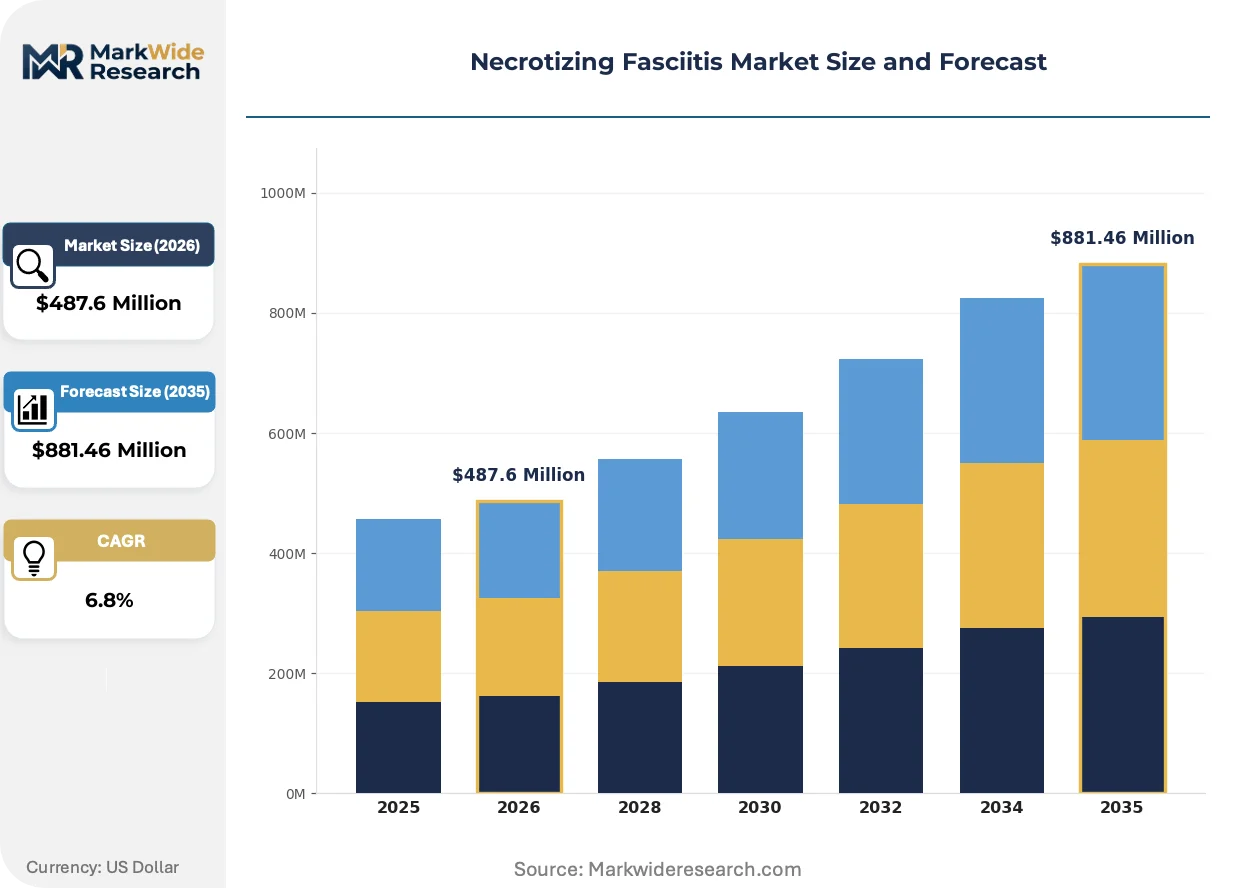
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Surgical Equipment, Dressings, Pain Management Therapy Area: Infectious Diseases, Critical Care, Wound Management, Emergency Medicine End User: Hospitals, Specialty Clinics, Outpatient Centers, Home Healthcare Delivery Mode: Intravenous, Oral, Topical, Surgical Intervention |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Gilead Sciences Inc., Astellas Pharma Inc., Basilea Pharmaceutica Ltd., Takeda Pharmaceutical Co., CSL Behring, Grifols S.A., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Necrotizing Fasciitis Market Shifts & Advancements
Digital pathology platforms and AI-assisted tissue analysis are compressing diagnostic decision timelines while regulatory frameworks evolve to accommodate combination product submissions.
Next-generation rapid molecular diagnostics is digitizing specimen-to-result workflows through automated nucleic acid extraction and cloud-connected pathogen identification algorithms. Emergency departments and surgical intensive care units in United States health systems are adopting these platforms within eighteen-month procurement cycles. This capability is digitizing how clinicians triage suspected cases before irreversible fascial destruction progresses.
The European Medicines Agency's infectious disease guidance on multidrug-resistant pathogens is tightening formulary access thresholds for novel antibiotics across EU member states. Manufacturers must now demonstrate superiority against established carbapenem regimens rather than non-inferiority, elevating clinical trial design complexity. German and French hospital procurement consortiums are responding by consolidating purchasing power and demanding outcome-based utilization guarantees.
Point-of-care lactate and procalcitonin testing is compressing sepsis recognition timelines in pre-hospital and emergency settings, triggering earlier surgical consultation patterns. Air medical transport services and regional trauma networks are integrating these biomarkers into triage protocols, replacing traditional clinical scoring systems. This behavioral shift is most visible in southeastern United States states where rural hospital closures have centralized definitive care responsibility.
Necrotizing Fasciitis Market Segmentation
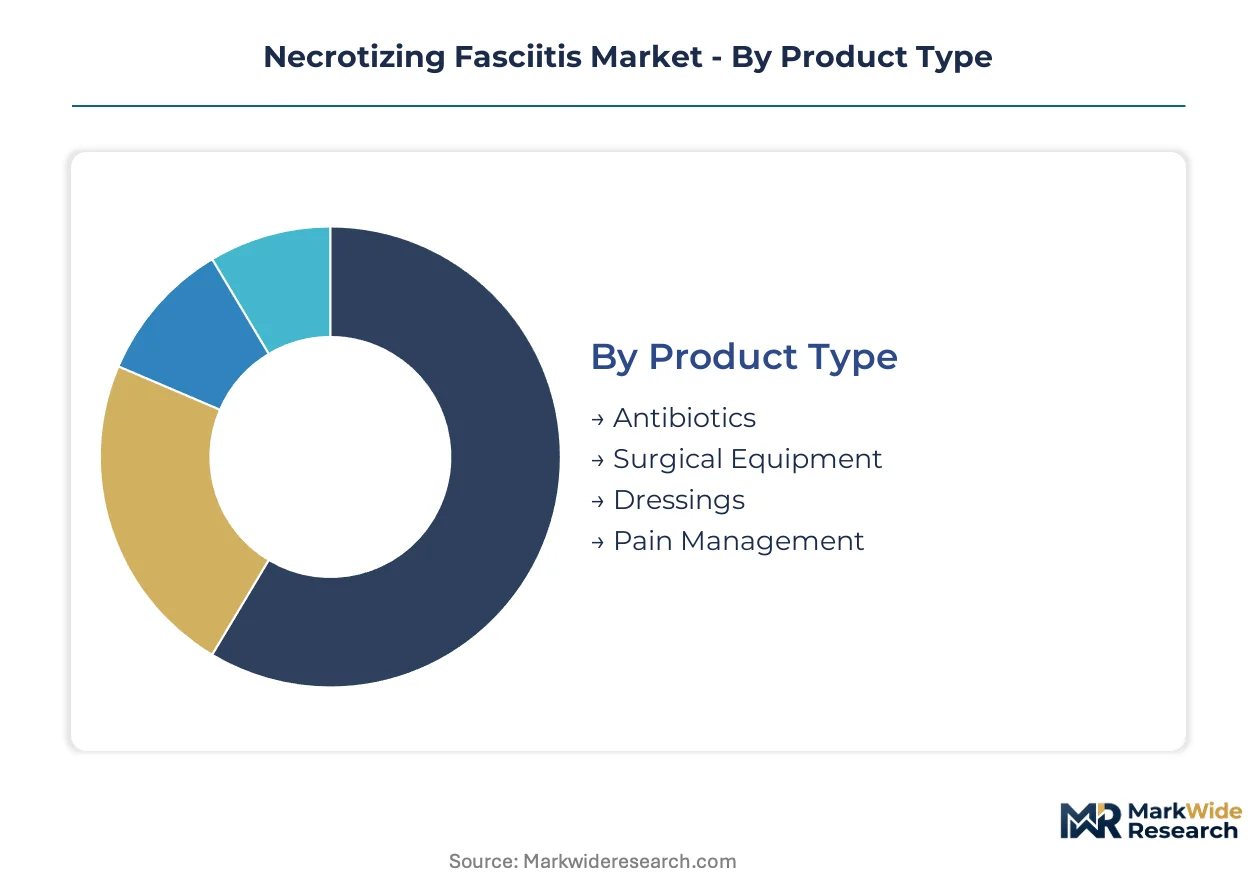
Necrotizing fasciitis management requires coordinated deployment across acute intervention, post-operative stabilization, and long-term recovery phases. Segmentation reveals how resource intensity concentrates in critical care infrastructure while surgical innovation and outpatient transition create secondary value pools.
Product Type:
Product selection tracks the clinical timeline from emergency debridement through wound closure and rehabilitation.
- Antibiotics:Broad-spectrum IV formulations including carbapenems, lipopeptides, and combination beta-lactamase inhibitors target polymicrobial gram-positive, gram-negative, and anaerobic coverage. United States trauma centers drive formulary placement through FDA QIDP-designated agents, though CDC stewardship mandates constrain empiric utilization rates.
- Surgical Equipment:Hydro-surgical and ultrasonic debridement systems enable fascial plane dissection with reduced collateral tissue damage. Academic medical centers in Germany and the United States are standardizing these platforms for extremity-sparing protocols.
- Dressings:Negative-pressure wound therapy and antimicrobial-impregnated matrices support post-debridement granulation.
- Pain Management:Regional anesthesia catheters and multimodal opioid-sparing protocols facilitate early mobilization.
Established volume favors antibiotics; emerging adoption favors surgical equipment.
Therapy Area:
Resource allocation intensity varies sharply across the care continuum from initial resuscitation through rehabilitation.
- Critical Care:Prolonged ICU stays requiring mechanical ventilation, vasopressor support, and continuous renal replacement therapy generate the deepest margin pools. United States health systems capture this value through severity-adjusted DRG billing, though Medicare reimbursement inadequately reflects operative repetition.
- Infectious Diseases:Fellowship-trained specialists direct empiric-to-targeted therapy transitions and source control timing. Coastal academic concentration creates expertise gaps in secondary United States markets and rural European catchments.
- Wound Management:Plastic surgery and wound care nursing coordinate delayed primary closure and grafting decisions.
- Emergency Medicine:Rapid recognition protocols using LRINEC scoring and point-of-care lactate testing compress time-to-operating room.
Critical care commands the steepest expansion trajectory; infectious diseases faces specialist supply constraints.
End User:
Site-of-care migration potential depends on surgical complexity and monitoring intensity requirements.
- Hospitals:Tertiary centers with dedicated surgical ICU capacity, on-call plastic surgery, and hyperbaric oxygen availability manage definitive care. Urban corridor concentration in the United States, Germany, and Japan creates geographic access barriers for rural populations.
- Specialty Clinics:Wound care and infectious disease outpatient facilities manage post-acute dressing changes and IV antibiotic completion.
- Outpatient Centers:Ambulatory surgical centers handle limited debridement for early-presenting, localized infections.
- Home Healthcare:Infusion nursing and negative-pressure wound therapy devices enable early discharge for stable patients.
Hospital infrastructure anchors current revenue; home healthcare represents the fastest-climbing alternative setting.
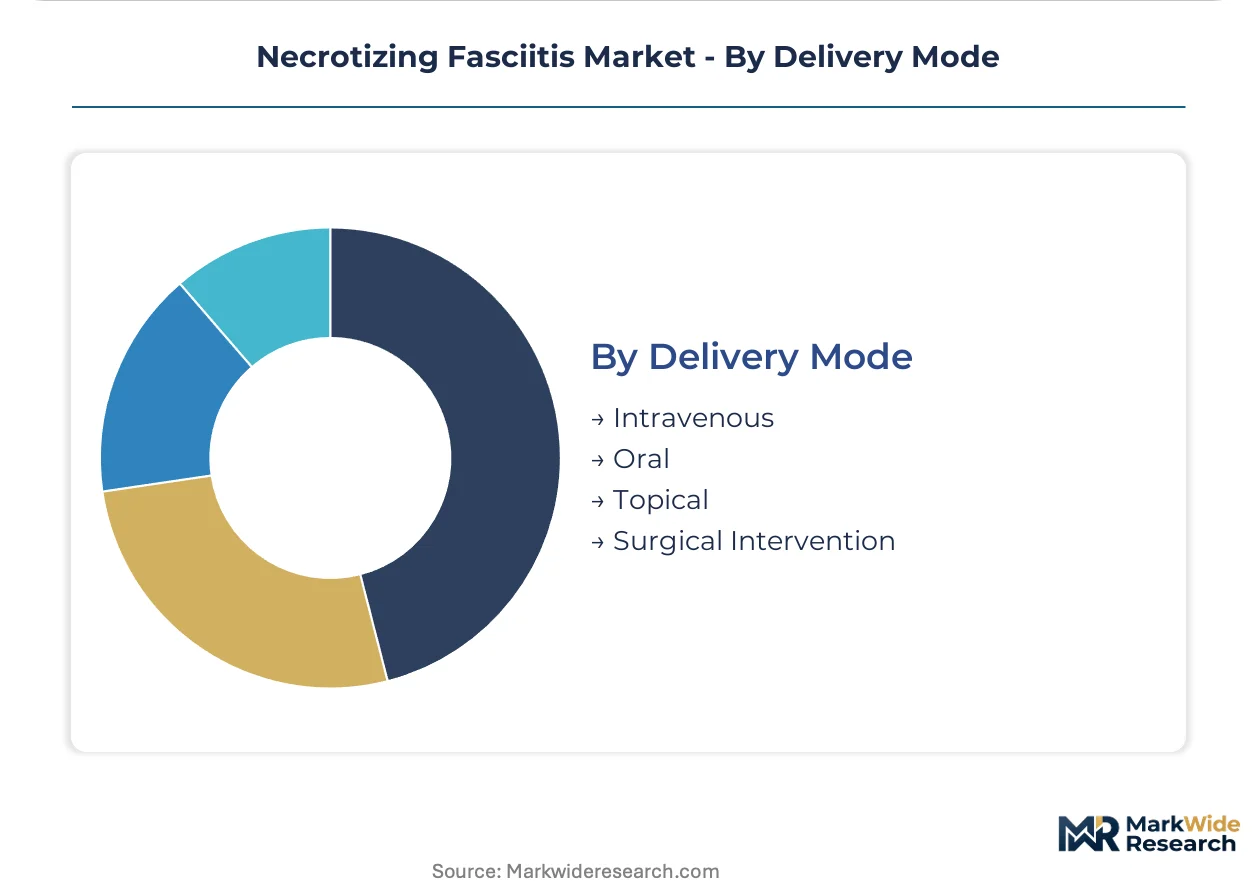
Delivery Mode:
Route selection follows disease severity progression and tissue penetration requirements.
- Intravenous:Continuous infusion of broad-spectrum agents achieves reliable tissue concentrations above MIC thresholds during active fascial spread. United States hospitals favor extended-infusion piperacillin-tazobactam and carbapenem protocols per IDSA guidance.
- Surgical Intervention:Repeated operative debridement at 24-48 hour intervals until viable tissue margins remain the non-negotiable standard of care. Minimally invasive technologies are gaining share fastest in extremity presentations.
- Oral:Step-down fluoroquinolone or amoxicillin-clavulanate regimens complete polymicrobial coverage after clinical stabilization.
- Topical:Antiseptic instillation and antimicrobial dressings supplement systemic therapy at wound surfaces.
Surgical intervention remains non-substitutable; IV delivery dominates pharmaceutical revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States trauma centers export clinical protocols and surgical training to tertiary hospitals in Germany, Japan, and Australia. German academic medical centers reciprocate with advanced wound care technologies and minimally invasive debridement platforms. This bilateral knowledge transfer concentrates high-complexity case management in urban corridor clusters across both continents.
United States
FDA's Qualified Infectious Disease Product program drives antibiotic development through priority review and extended exclusivity. Trauma center density in southeastern states supports aggressive surgical intervention protocols. The Texas Medical Center in Houston anchors extremity-sparing surgery innovation through hydro-surgical platform adoption.
Germany
EMA infectious disease guidance mandates superiority demonstrations against carbapenem regimens for novel antibiotic approval. Hospital procurement consortiums in Baden-Württemberg and Bavaria consolidate purchasing power for outcome-based contracts. The Berlin-Brandenburg medical cluster specializes in post-debridement negative-pressure wound therapy standardization.
Japan
PMDA accelerated approval pathways compress timelines for resistant-pathogen antibiotics targeting polymicrobial infections. METI funding supports rapid molecular diagnostic platform deployment in tertiary centers. The Kansai region around Osaka concentrates hyperbaric oxygen therapy capacity for fascial infection complications.
Australia
TGA priority review designation aligns with FDA QIDP incentives for gram-positive and anaerobic coverage agents. Rural hospital closure patterns in Queensland and Western Australia delay definitive surgical care. The Sydney-Greater New South Wales corridor maintains the highest density of plastic surgery on-call capacity for limb-salvage procedures.
United Kingdom
NICE technology appraisals constrain reimbursement for premium-priced antibiotics without mortality benefit demonstration. NHS England's specialized commissioning framework centralizes necrotizing fasciitis care in major trauma centers. The London-Southeast cluster leads tele-ICU integration to extend specialist oversight to community hospitals.
Necrotizing Fasciitis Market Competitive Landscape
On the supply side, the industry is consolidated around diversified pharmaceutical conglomerates with critical care antibiotic portfolios, supplemented by specialized plasma fractionators and regional generics manufacturers. Three archetypes dominate: broad-spectrum antibiotic developers leveraging FDA QIDP designations, surgical equipment innovators commercializing minimally invasive debridement platforms, and plasma-derived therapy suppliers addressing toxin-mediated complications. Competitive moves concentrate on diagnostic-therapeutic bundling partnerships and geographic expansion of trauma center training networks.
Among diversified pharmaceutical developers, Pfizer Inc., Merck & Co., Inc., and Gilead Sciences Inc. occupy positions that exemplify contrasting portfolio strategies. Pfizer anchors hospital formulary placement through carbapenem and lipopeptide class leadership. Merck sustains competitive presence in polymicrobial severe infection management. Gilead differentiates via antiviral and antifungal adjacencies that address atypical pathogen presentations in immunocompromised patient subsets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Gilead Sciences Inc. |
| Astellas Pharma Inc. |
| Basilea Pharmaceutica Ltd. |
| Takeda Pharmaceutical Co. |
| CSL Behring |
| Grifols S.A. |
| GlaxoSmithKline plc |
| Others |
Supply & Pricing Matrix
Overcapacity in carbapenem-class antibiotic fermentation capacity across India and China compresses spot pricing for generic broad-spectrum agents while simultaneously incentivizing contract manufacturers to pursue higher-margin QIDP-designated novel therapies. This utilization asymmetry concentrates pricing power with FDA-certified sterile injectable facilities in the United States and Germany, forcing procurement consortiums to accept outcome-based utilization guarantees for differentiated coverage agents.
Pricing Analysis
Next-generation rapid molecular diagnostic platforms command 40-60% premiums over conventional culture-based identification systems, while prior-generation empiric antibiotic protocols face sustained deflation from CDC stewardship mandates. The dominant model is tiered pricing separating premium QIDP-designated agents from standard carbapenem generics and economy-oriented oral step-down formulations. Price differentiation rests on FDA exclusivity status and clinical mortality benefit data, with German hospital procurement consortiums exhibiting highest sensitivity to per-dose acquisition costs and United States academic medical centers least sensitive due to severity-adjusted DRG reimbursement buffers. Pricing pressure intensifies in the standard tier as Indian API manufacturers expand piperacillin-tazobactam output.
Supply Chain Analysis
Upstream fermentation feedstock for lipopeptide and carbapenem antibiotics concentrates in China, India, and Italy, with sterile fill-finish capacity clustering in the United States, Germany, and Japan. Active pharmaceutical ingredient production draws from corn-derived dextrose broths, specialized boron-containing intermediates, and palladium catalysts for hydrogenation steps. Single-source vulnerability pervades the boron intermediate segment, where two Chinese manufacturers supply 70% of global input for daptomycin-class agents. Distribution runs through hospital GPO contracts in the United States, regional procurement consortiums in Germany, and centralized NHS supply frameworks in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The necrotizing fasciitis market functions as a service-attach opportunity where diagnostic-therapeutic protocol subscriptions and remote ICU consultation networks expand faster than hardware revenues from surgical equipment sales.
For Market Incumbents: Entrench formulary positioning by embedding rapid molecular diagnostic platforms within hospital system IDN contracts, creating switching costs that delay generic antibiotic commoditization. Deepen backward integration into sterile injectable manufacturing through captive capacity additions in North Carolina and Bavaria to insulate margin pools from Indian API price volatility. The priority defensive lever is certification investment in FDA QIDP extensions that reset exclusivity clocks.
For New Entrants and Emerging Players: Pursue white-space capture in tele-ICU integration services for community hospitals in rural United States corridors and Australian states experiencing specialist shortage. The most penetrable segment is outpatient wound care transition management, where home healthcare agencies seek bundled negative-pressure wound therapy and infusion nursing packages. The specific go-to-market angle is outcome-based contracting that shares sepsis readmission risk with hospital partners.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plasma fractionators with immunoglobulin adjuvant therapies for toxin-mediated fascial infections, where multi-year hospital supply agreements generate predictable cash flows. Long-term viability over the projection horizon favors acquisition targets with diagnostic-therapeutic bundling capabilities and established trauma center training networks. The specific signal to watch is FDA breakthrough device designation velocity for companion diagnostic platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Bundling Partnerships | FDA breakthrough device pathways enable simultaneous approval of rapid molecular tests with companion antibiotic protocols. |
| Minimally Invasive Surgical Platform Launch | Hydro-surgical and ultrasonic debridement systems address unmet need in extremity-sparing surgery at academic medical centers. |
| Tele-ICU Network Expansion | Remote critical care consultation extends specialist oversight to community hospitals beyond traditional referral patterns. |
| QIDP Regulatory Approval Pathway | FDA priority review and extended exclusivity incentivizes R&D investment in gram-positive and polymicrobial coverage agents. |
| Plasma-Derived Therapy Manufacturing Scale-Up | Immunoglobulin adjuvant therapies for toxin-mediated complications deepen margin pools through multi-year hospital contracts. |
Research Methodology
Cross-validation between infectious disease specialist interviews and hospital procurement database analysis anchors the qualitative findings on formulary placement dynamics and pricing negotiation patterns. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers were combined with secondary validation from FDA QIDP filings, EMA submissions, ClinicalTrials.gov entries, and CMS Medicare severity-adjusted DRG classifications. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation were reconciled across the analysis window.
Calibration against historical antibiotic adoption curves and surgical intervention episode counts shaped the analytical framework across therapy area segments, product type categories, and regional regulatory clusters. Segmentation dimensions modeled include administration route, care setting intensity, pathogen coverage spectrum, and regional reimbursement infrastructure. CAGRs were derived from logarithmic trend fitting to adjusted baseline values, incorporating FDA approval velocity for novel agents and trauma center capacity expansion rates as industry-specific forecast inputs.
Sensitivities concentrate around FDA QIDP designation velocity, CDC stewardship mandate enforcement intensity, and rural hospital closure patterns that delay definitive surgical care. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement adequacy. Cross-checking against hospital procurement consortium contract disclosure patterns and GPO pricing benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market