
 Azathioprine API Market | 2026-2036
Azathioprine API Market Size, Share, and Industry Trends Forecast 2026-2036
Azathioprine API Market Insights
Synthetic route optimization toward biocatalytic processes is recalibrating cost structures across azathioprine API production. Teva Pharmaceutical Industries leverages vertical integration across formulation and active ingredient supply to sustain margin resilience. Aarti Industries anchors its position through specialized thiopurine chemistry capabilities and captive intermediates. Cheng Yi Pharmaceutical competes on manufacturing scale within Asia-Pacific supply corridors.
Azathioprine API is a purine antimetabolite synthesized through condensation of 6-mercaptopurine with imidazole derivatives, typically meeting USP or EP specifications of 98.0-102.0% assay purity for pharmaceutical use. It functions primarily as an immunosuppressive agent inhibiting purine metabolism in lymphocytes, with applications spanning organ transplantation maintenance and autoimmune disease management. Tablet formulations dominate current volume flows given established oral dosing regimens and stability profiles, while injection formats capture premium positioning in acute transplant settings where bioavailability precision matters. Distribution through specialty pharmacies concentrates margin pools due to cold-chain requirements and patient monitoring protocols.
FDA current Good Manufacturing Practice enforcement and EMA's revised Active Substance Master File guidelines are tightening impurity profiling thresholds for immunosuppressive APIs, directly shaping batch release timelines and facility audit frequencies. India's CDSCO and China's NMPA are aligning domestic API export certifications with ICH Q7 standards, compressing market access timelines for qualified manufacturers. Stakeholders must monitor evolving pharmacovigilance requirements for thiopurine S-methyltransferase genotyping as personalized dosing protocols reshape prescription volumes and formulation specifications.
Market Dynamics
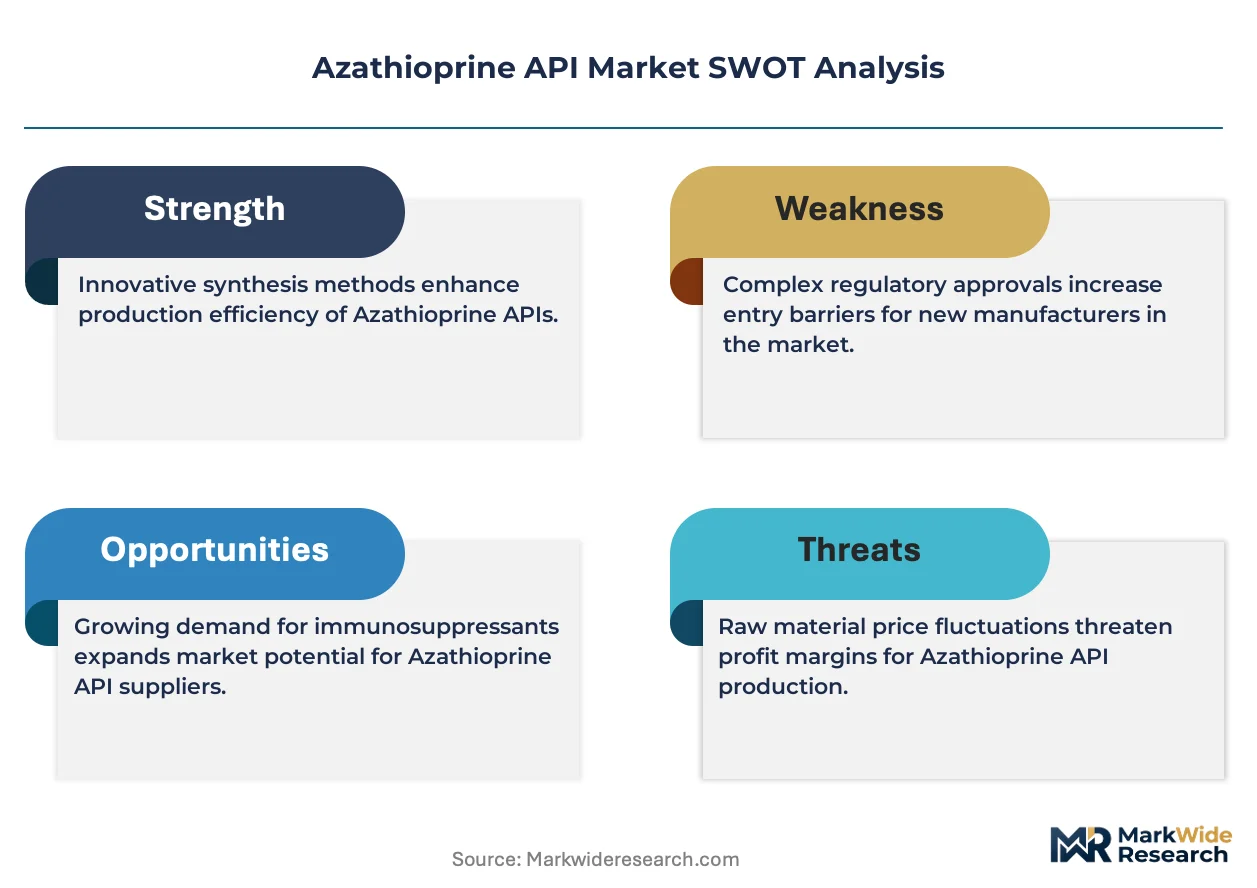
Biocatalytic process adoption is compressing production costs for azathioprine API manufacturers while simultaneously raising the technical barrier to entry. This synthetic route transition is redistributing competitive advantage toward firms with enzymatic chemistry capabilities and away from legacy nitro reduction methods.
Growth Catalysts
- Organ transplantation protocols:Rising solid organ transplant volumes in India and China are expanding the addressable patient base for maintenance immunosuppression. Hospital formulary expansion in these markets is accelerating API consumption.
- EMA Active Substance Master File alignment:Revised impurity profiling guidelines are streamlining batch release timelines for qualified European suppliers. This regulatory clarity is shortening market access cycles.
- Thiopurine S-methyltransferase genotyping:Personalized dosing protocols are extending treatment durations and reducing discontinuation rates. Pharmacogenomic integration is reshaping prescription volumes.
Market Restraints
- 6-mercaptopurine feedstock volatility:Concentrated supply of this key intermediate creates input cost instability. Three specialized chemical manufacturers control the majority of merchant supply.
- FDA current Good Manufacturing Practice enforcement:Elevated facility audit frequencies are extending compliance timelines. Batch release delays are compressing working capital efficiency.
- Mycophenolate mofetil substitution:Alternative immunosuppressants are capturing share in de novo transplant protocols. Formulary preference shifts are constraining volume growth in select accounts.
Strategic Opportunities
- CDSCO export certification alignment:Indian manufacturers achieving ICH Q7 equivalence are accessing accelerated EU and US registration pathways. This regulatory convergence is compressing time-to-market.
- Biocatalytic-thiopurine chemistry convergence:Enzymatic process integration is enabling cost structures previously unattainable at commercial scale. Technology licensing partnerships are emerging.
- Specialty pharmacy channel expansion:Cold-chain distribution networks are capturing margin pools through patient monitoring bundling. This channel is displacing traditional wholesale in premium segments.
Industry Challenges
- Enzymatic process engineering talent scarcity:Biocatalysis expertise resides in limited geographic clusters. Recruitment competition is elevating compensation costs.
- USP and EP specification harmonization:Divergent assay purity thresholds between pharmacopeias are complicating multi-market registration strategies. Dual certification requirements are extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Azathioprine API Market |
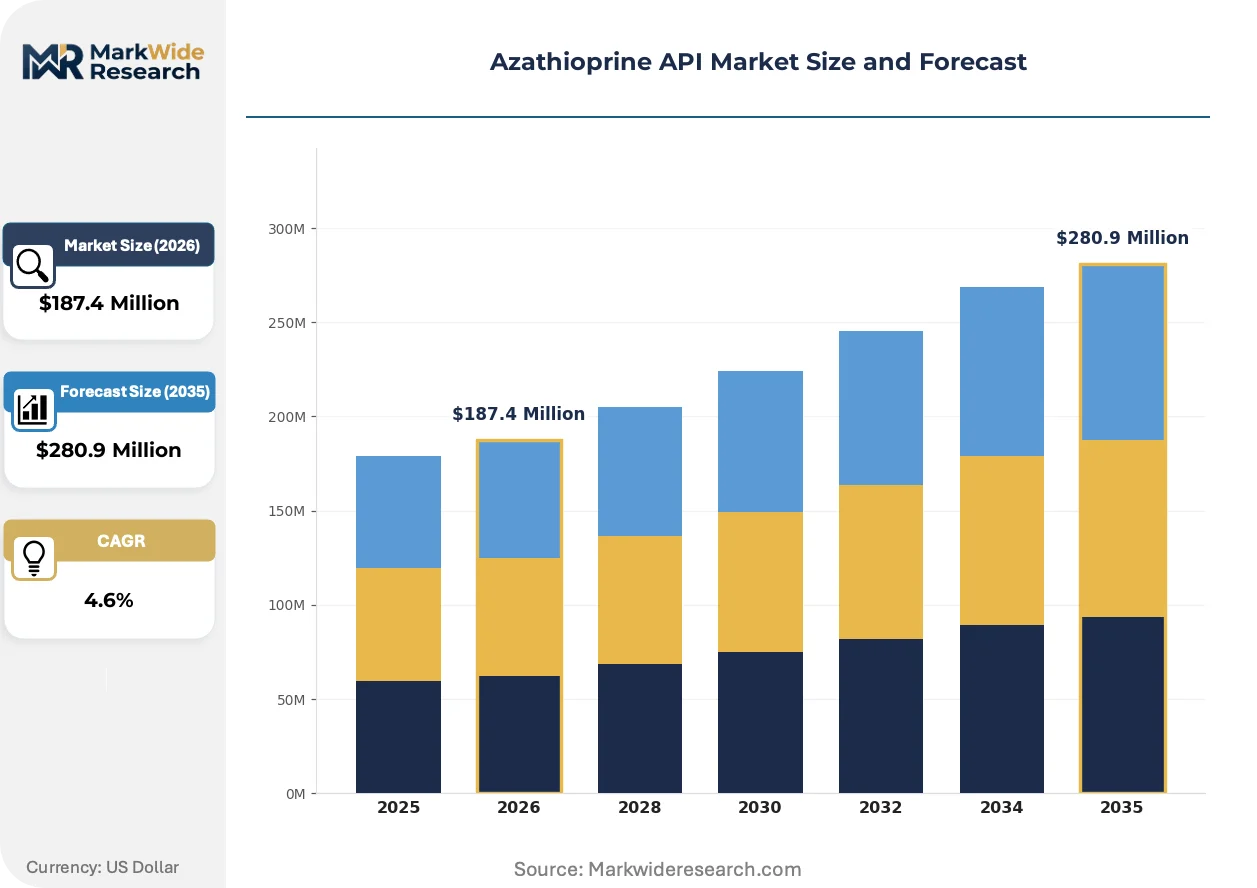
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Injection, Oral Solution, Powder End User: Hospitals, Clinics, Pharmacies, Homecare Application: Autoimmune Diseases, Organ Transplantation, Cancer Therapy, Inflammatory Conditions Distribution Channel: Direct Sales, Wholesale, Online Retail, Specialty Pharmacies |
| Companies Covered | Index Pharmaceutical, GlaxoSmithKline, Aspen API, Mylan N.V., Cheng Yi Pharmaceutical, Fermion, Rakshit Pharmaceuticals, Teva Pharmaceutical Industries, Aarti Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Azathioprine API Market Trends and Innovations
Continuous processing technologies are displacing batch manufacturing in azathioprine API synthesis, enabled by advances in flow chemistry and real-time analytical control. This operational shift is compressing cycle times and reducing solvent waste profiles.
Biocatalytic reduction of nitro intermediates is expanding into commercial-scale azathioprine production, replacing traditional chemical hydrogenation. Contract manufacturers in India and China are retrofitting existing assets to accommodate enzymatic conversion steps. This technology is expanding into cost-sensitive supply corridors previously dominated by conventional synthetic routes.
EMA's revised Active Substance Master File guidelines are mandating enhanced impurity profiling for immunosuppressive APIs, including specified identification thresholds for process-related substances. European manufacturers are investing in high-resolution mass spectrometry capabilities to meet documentation requirements. Tablet formulation specialists are most affected, as solid dosage forms face heightened scrutiny relative to injection formats.
Hospital procurement consolidation is concentrating purchasing power among integrated delivery networks and group purchasing organizations. Specialty pharmacies are capturing direct distribution relationships with transplant centers, displacing traditional wholesale intermediaries. This channel restructuring is most visible in the United States, where vertical integration between pharmacy benefit managers and specialty pharmacies is reshaping margin distribution.
Azathioprine API Market Segmentation
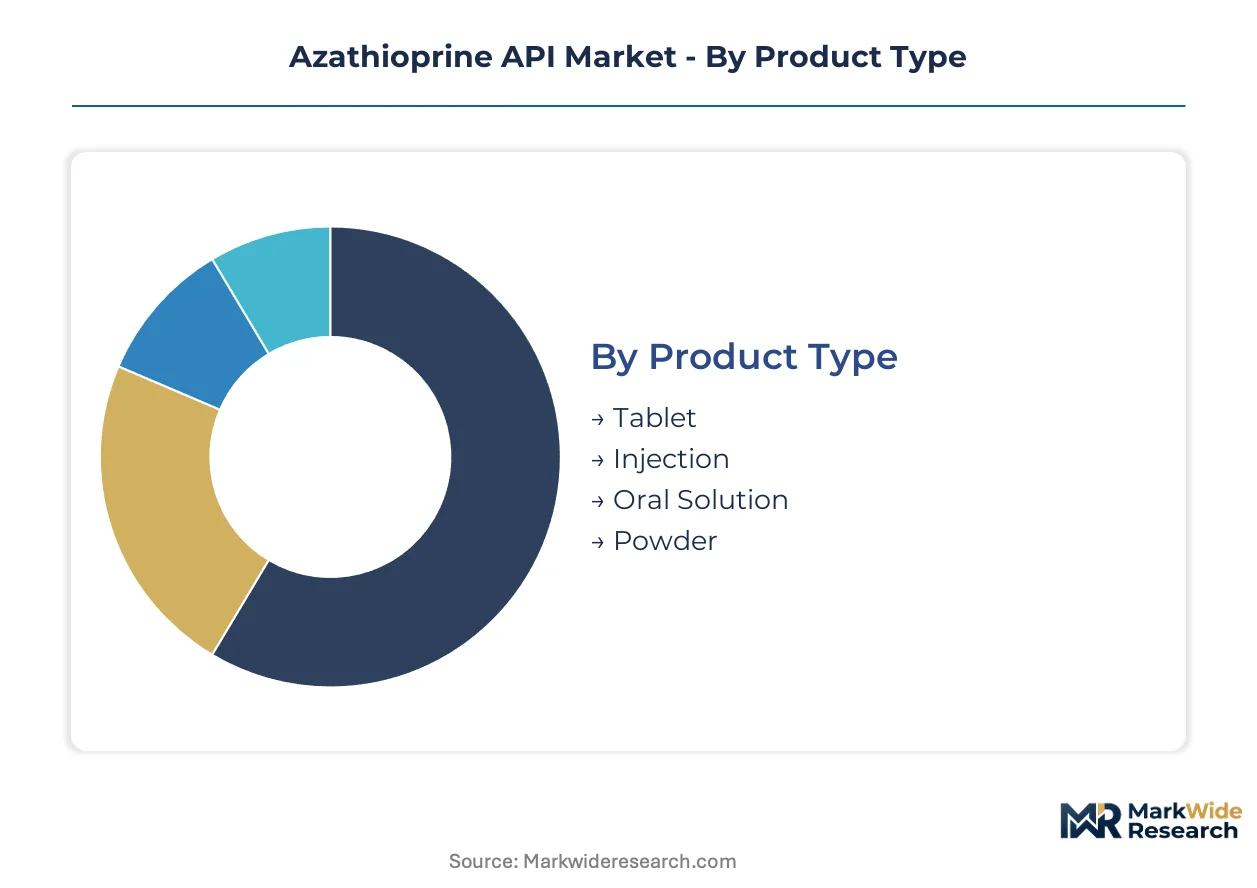
Azathioprine API demand fragments across formulation types, care settings, and distribution channels with divergent margin profiles. Each segment carries distinct regulatory burdens and technical specifications that reshape competitive positioning.
Product Type:
Tablet formulations dominate volume flows while injection formats command premium positioning through bioavailability precision requirements.
- Tablet:Oral solid dosage forms meeting USP or EP assay specifications of 98.0-102.0% purity anchor maintenance immunosuppression protocols. Hospital formulary expansion in India and China concentrates tablet demand as transplant volumes scale in these markets.
- Injection:Parenteral formats capture acute transplant settings where precise dosing and rapid bioavailability override cost considerations. Cold-chain requirements and sterility validation elevate manufacturing complexity and margin capture.
- Oral Solution:Liquid formulations serve pediatric populations and patients with swallowing difficulties, requiring stability testing for shelf-life validation.
- Powder:Bulk API powder supplies compounding pharmacies and institutional preparation facilities with flexibility for customized dosing.
Mature deployment sits with Tablet. Newer deployment is concentrated in Injection as precision dosing protocols expand.
End User:
Care setting determines reimbursement pathways and monitoring intensity, with hospital-based administration retaining the highest compliance oversight.
- Hospitals:Integrated transplant centers manage induction and maintenance protocols with embedded pharmacogenomic testing for thiopurine S-methyltransferase variants. FDA current Good Manufacturing Practice enforcement elevates documentation requirements for hospital-supplying manufacturers.
- Clinics:Outpatient rheumatology and gastroenterology practices prescribe for autoimmune indications with lower monitoring frequency than transplant protocols.
- Pharmacies:Retail dispensing captures stable maintenance prescriptions with established oral dosing regimens and patient counseling requirements.
- Homecare:Self-administered maintenance therapy expands through specialty pharmacy channels with remote monitoring capabilities.
Volume concentration rests with Hospitals. Margin expansion is accelerating in Homecare through specialty pharmacy integration.
Application:
Therapeutic indication shapes dosing duration, monitoring intensity, and competitive substitution risk across patient populations.
- Autoimmune Diseases:Chronic maintenance therapy for Crohn's disease, ulcerative colitis, and systemic lupus erythematosus generates recurring prescription volumes. EMA's revised Active Substance Master File guidelines elevate impurity profiling requirements for long-duration therapies.
- Organ Transplantation:Solid organ maintenance protocols require lifelong immunosuppression with narrow therapeutic windows. Rising transplant volumes in India and China expand the addressable patient base most rapidly.
- Cancer Therapy:Oncology applications leverage azathioprine's antimetabolite mechanism in combination regimens with distinct procurement pathways.
- Inflammatory Conditions:Dermatologic and rheumatologic indications compete with biologic alternatives in formulary positioning.
Established utilization centers on Autoimmune Diseases. Steepest expansion trajectory is visible in Organ Transplantation as emerging markets scale surgical capacity.
Distribution Channel:
Channel structure determines margin distribution and patient access controls with cold-chain and monitoring requirements favoring specialized intermediaries.
- Direct Sales:Manufacturer-to-institution contracts serve large transplant centers with volume commitments and integrated service bundling.
- Wholesale:Traditional distributors handle standard oral formulations with established logistics networks and compressed margins.
- Online Retail:Digital pharmacies expand access for maintenance prescriptions with regulatory compliance varying by jurisdiction.
- Specialty Pharmacies:Cold-chain distribution networks with embedded patient monitoring capture premium segments and displace wholesale in transplant maintenance.
Wholesale retains volume leadership. Specialty Pharmacies are gaining share fastest through vertical integration with pharmacy benefit managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for azathioprine API concentrates in transplant-heavy medical systems with established immunosuppression protocols. Regulatory alignment with ICH Q7 standards is compressing export timelines for qualified manufacturers in key supply corridors.
United States
Solid organ transplant volumes at centers like Mayo Clinic and Cleveland Clinic sustain maintenance immunosuppression demand. FDA current Good Manufacturing Practice enforcement elevates facility audit frequencies and documentation requirements. New Jersey and Pennsylvania host API manufacturing clusters where contract manufacturers retrofit assets for biocatalytic conversion steps.
Germany
EMA Active Substance Master File alignment streamlines batch release for European suppliers serving transplant centers in Berlin and Munich. REACH compliance adds layer of chemical safety documentation for thiopurine intermediates. Bavaria anchors pharmaceutical chemistry capabilities with specialized enzymatic process engineering talent pools.
India
Rising transplant volumes at All India Institute of Medical Sciences and private hospital chains expand addressable patient base for maintenance therapy. CDSCO export certification alignment with ICH Q7 accelerates EU and US registration pathways. Gujarat and Maharashtra concentrate API manufacturing capacity with backward integration into 6-mercaptopurine feedstock supply.
China
NMPA alignment with international GMP standards compresses market access timelines for qualified immunosuppressive API exporters. Yangtze River Delta manufacturing clusters scale biocatalytic production capacity for thiopurine chemistry. Cheng Yi Pharmaceutical anchors regional supply through manufacturing scale within Asia-Pacific corridors.
United Kingdom
NHS transplant protocols maintain steady demand for azathioprine in maintenance regimens post-kidney and liver transplantation. MHRA post-Brexit regulatory autonomy preserves EMA-equivalent impurity profiling standards for API imports. Southeast England concentrates specialty pharmacy distribution networks with cold-chain capabilities for parenteral formats.
Azathioprine API Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration conferring margin resilience in tablet formulations while pure-play API suppliers compete on biocatalytic process efficiency. The vendor base organizes around three archetypes: integrated pharmaceutical conglomerates with captive demand, specialized thiopurine chemistry houses, and emerging-scale Asian manufacturers. Consolidation pressure operates through technology licensing partnerships rather than asset-heavy M&A, as enzymatic process capabilities prove difficult to acquire.
Among integrated pharmaceutical conglomerates, Teva Pharmaceutical Industries exemplifies backward integration across formulation and active ingredient supply. Aarti Industries occupies a position within specialized thiopurine chemistry, leveraging captive intermediates for cost structure control. Cheng Yi Pharmaceutical sits within the scale-driven Asian manufacturer tier, competing on production volume within regional export corridors.
| Leading Market Players |
|---|
| Index Pharmaceutical |
| GlaxoSmithKline |
| Aspen API |
| Mylan N.V. |
| Cheng Yi Pharmaceutical |
| Fermion |
| Rakshit Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Aarti Industries |
| Others |
Pricing and Supply Chain Analysis
Hospital formulary consolidation across India and China is compressing procurement timelines for azathioprine API while elevating technical qualification thresholds, forcing suppliers to absorb compliance investments that reshape margin structures across tablet and injection tiers.
Pricing Analysis
Tablet formulations anchor volume flows at compressed margins while injection formats command premium positioning through sterility validation and cold-chain requirements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified batches from EP-compliant intermediates and regional-grade supplies. Pricing pressure stems from mycophenolate mofetil substitution in de novo transplant protocols, eroding share in acute settings. Hospital procurement groups exhibit highest price sensitivity, whereas specialty pharmacies tolerating premium capture for patient monitoring bundling.
Supply Chain Analysis
Dual-sourcing requirements mandated by integrated delivery networks in the United States and European transplant centers are fragmenting order books across qualified manufacturers. Supply concentrates in India, China, and Germany, with Gujarat and Maharashtra anchoring 6-mercaptopurine feedstock production. Biocatalytic enzyme supply and imidazole derivative precursors constitute critical input dependencies. Single-source vulnerability in specialized enzymatic catalyst production elevates disruption risk. Distribution runs through specialty pharmacy networks displacing wholesale intermediaries in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic process engineering talent scarcity constitutes the binding capacity constraint, propping pricing power for qualified biocatalytic manufacturers while excluding marginal competitors from premium supply tiers.
For Market Incumbents: Lock in biocatalytic process advantages through captive enzyme supply partnerships before technology licensing dilutes differentiation. Defend hospital formulary positions against mycophenolate mofetil substitution by embedding pharmacogenomic testing services. Prioritize CDSCO and NMPA export certification alignment to capture emerging market procurement consolidation. For New Entrants and Emerging Players: Begin with oral solution and powder formats serving compounding pharmacies and pediatric populations, segments where regulatory barriers sit lower than injection sterility requirements. Target homecare distribution through specialty pharmacy partnerships as the most penetrable channel. Pursue technology licensing from established enzymatic chemistry houses rather than greenfield process development. For Investors and Strategic Acquirers: Re-rating potential sits with specialized thiopurine chemistry houses given EMA Active Substance Master File alignment compressing European market access timelines. Long-term viability favors manufacturers with backward integration into 6-mercaptopurine intermediates and demonstrated biocatalytic scale. Monitor thiopurine S-methyltransferase genotyping adoption rates as the signal indicating prescription volume durability and formulation specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Biocatalytic Process Scale-Up | Enzymatic conversion retrofits compress production costs for qualified thiopurine manufacturers. |
| CDSCO Export Certification Alignment | ICH Q7 equivalence accelerates EU and US registration pathways for Indian suppliers. |
| Specialty Pharmacy Channel Partnership | Cold-chain distribution with patient monitoring captures premium transplant maintenance volumes. |
| 6-Mercaptopurine Backward Integration | Captive intermediate supply insulates against feedstock volatility from concentrated merchant sources. |
| Pharmacogenomic Testing Service Bundling | Embedded thiopurine S-methyltransferase screening defends formulary position against substitute immunosuppressants. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with customs records and formulary databases. Primary interviews with regulatory affairs leads, hospital procurement managers, and API manufacturing executives provided qualitative grounding. Bottom-up volume estimates by formulation type and application triangulated against top-down market sizing across the analysis window.
Historical trendline analysis of transplant volumes and immunosuppression protocols established baseline demand trajectories. The modeling framework segmented by product type, end user, application, and distribution channel, with regional regulatory clusters as an overlay dimension. CAGRs were derived from slope analysis of normalized growth curves, incorporating biocatalytic adoption rates and pharmacogenomic integration timelines as industry-specific inputs.
Underlying measurement precision varies by segment; tablet formulations carry tighter precision than injection formats due to standardized assay specifications. Forecasts reflect assumptions regarding EMA guideline implementation pacing and CDSCO-NMPA alignment trajectories. Deviation in enzymatic process engineering talent availability or mycophenolate mofetil substitution rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Global Heparin Sodium Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
Fusion Inhibitors Market