
 Stress Urinary Incontinence Market | 2026-2036
Stress Urinary Incontinence Market Size, Share, and Industry Trends Forecast 2026-2036
Stress Urinary Incontinence Market Analytics
Pay-per-procedure leasing and asset-light service models is fragmenting competitive dynamics in the Stress Urinary Incontinence Market, lowering capital barriers for mid-sized clinics and ambulatory surgical centers. Coloplast A/S anchors its position through deep specialization in continence care and direct urology channel relationships. Medtronic leverages its broad surgical portfolio to cross-sell pelvic floor solutions alongside existing laparoscopic accounts. Boston Scientific Corporation competes through sustained R&D intensity in minimally invasive sling systems and sacral neuromodulation platforms.
Stress urinary incontinence refers to the involuntary leakage of urine during physical exertion, defined urodynamically by a vesical pressure exceeding urethral pressure without detrusor contraction, with severity graded by pad-test volume and validated symptom questionnaires. The condition's primary commercial purpose lies in restoring continence through mechanical support of the urethrovesical junction or neuromodulation of pelvic afferent pathways. Among treatment types, surgery and physical therapy represent the most structurally divergent margin pools, with sling procedures commanding higher reimbursement while conservative management expands volume through lower-cost pharmacy and clinic channels. Within product categories, implants and devices concentrate value capture due to recurring revenue from neuromodulation systems and synthetic mesh kits, whereas pads operate as a mature, price-sensitive consumable segment with thinner margins.
The FDA's 510(k) clearance pathway and ongoing post-market surveillance requirements for surgical mesh products shape product development timelines and litigation exposure for manufacturers active in the United States. The EU MDR's strengthened clinical evidence demands and unique device identification mandates are forcing redesign of technical documentation and quality management systems for market access in Europe. Stakeholders must monitor evolving FDA guidance on biologic versus synthetic sling materials and corresponding payer coverage determinations that will reshape product mix decisions across hospital and ambulatory settings.
Market Dynamics
The EU Medical Device Regulation's strengthened clinical evidence requirements are forcing manufacturers to rebuild technical documentation and quality management systems, compressing product development timelines while elevating barriers for new entrants.
Growth Catalysts
- Aging Demographics:Rising prevalence of pelvic floor disorders among women over 50 in the United States is expanding the addressable patient pool for sling procedures and neuromodulation systems.
- MDR Implementation:The EU MDR's unique device identification mandates are accelerating digital traceability investments that improve post-market surveillance and reduce litigation exposure for compliant manufacturers.
- Minimally Invasive Techniques:Laparoscopic and single-incision sling placement methods are shortening hospital stays and shifting procedural volumes toward ambulatory surgical centers.
Market Restraints
- Polypropylene Mesh Litigation:Historical product liability claims against synthetic mid-urethral slings have created enduring reputational damage and constrained payer coverage for mesh-based devices.
- Supply Concentration:Specialized biologic graft suppliers in Switzerland and Ireland control limited processing capacity for autologous and xenogenic sling materials.
- Reimbursement Compression:CMS physician fee schedule adjustments for outpatient urogynecology procedures are squeezing margins for hospital outpatient departments.
Strategic Opportunities
- Underpenetrated Markets:Germany and France exhibit lower sling procedure rates per capita than the United States, presenting expansion potential for established device portfolios.
- Remote Patient Monitoring:Bluetooth-enabled neuromodulation programmers are enabling post-implant titration without clinic visits, creating subscription revenue streams.
- Bioresorbable Materials:Convergence of polymer science and tissue engineering is opening pathways for temporary mechanical support that eliminates permanent foreign body complications.
Industry Challenges
- Specialized Surgical Training:Shortage of urogynecologists fellowship-trained in advanced sling placement and complication management limits procedural capacity in community hospitals.
- Legacy System Integration:Sacral neuromodulation devices from earlier generations lack interoperability with contemporary electronic health record platforms, complicating patient data workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stress Urinary Incontinence Market |
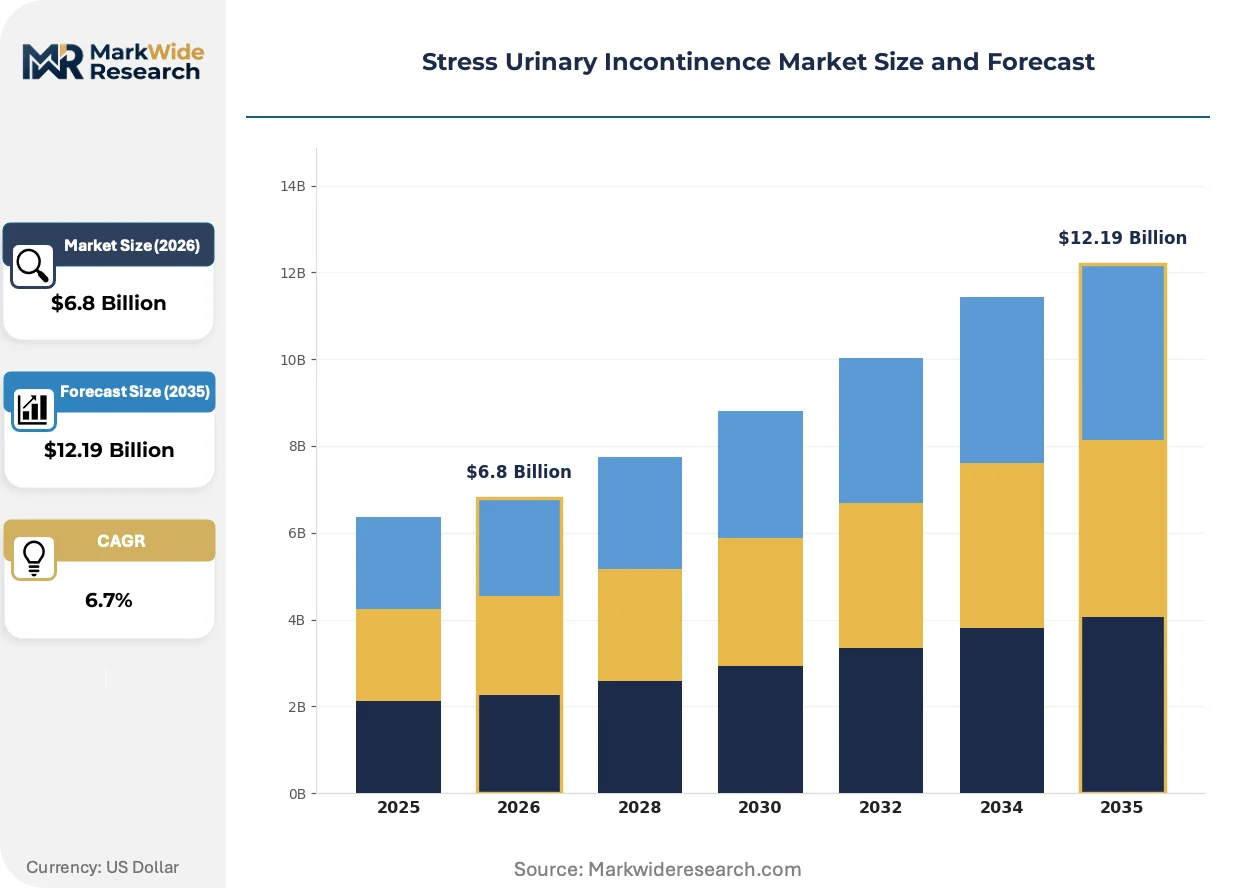
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Medications, Physical Therapy, Lifestyle Changes Product Category: Implants, Devices, Pads, Surgical Instruments Patient Type: Elderly Women, Postpartum Women, Surgical Candidates, Non-Surgical Candidates Distribution Channel: Hospitals, Pharmacies, Online Retail, Clinics |
| Companies Covered | Coloplast A/S, Boston Scientific Corporation, Johnson & Johnson Services, BD, Laborie, CooperSurgical, Teleflex Incorporated, Medtronic, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stress Urinary Incontinence Market Evolving Landscape
Product development in stress urinary incontinence is pivoting toward biologic and resorbable alternatives as regulatory pressure on permanent synthetic mesh intensifies, while service models fragment toward asset-light configurations.
Single-incision mini-slings utilizing ultra-high molecular weight polyethylene are rendering obsolete traditional transobturator and retropubic multi-incision approaches. Ambulatory surgical centers in the United States are adopting these systems at accelerating rates, compressing average procedure time from 45 minutes to under 20 minutes and enabling same-day discharge protocols that reshape facility economics.
The EU MDR's post-market clinical follow-up requirements are mandating systematic long-term safety data collection for all Class III implantable devices. Manufacturers must now fund prospective registries or randomized trials as conditions of continued market authorization, disproportionately burdening smaller competitors with limited clinical affairs infrastructure while favoring organizations with established European epidemiological networks.
Leasing arrangements for neuromodulation generators and capital equipment are displacing outright purchase in mid-sized urology practices. Pay-per-procedure contracts align vendor revenue with clinical utilization, transferring obsolescence risk from physician buyers to device suppliers and concentrating negotiating leverage among multi-site practice management organizations in Texas and Florida.
Stress Urinary Incontinence Market Segmentation
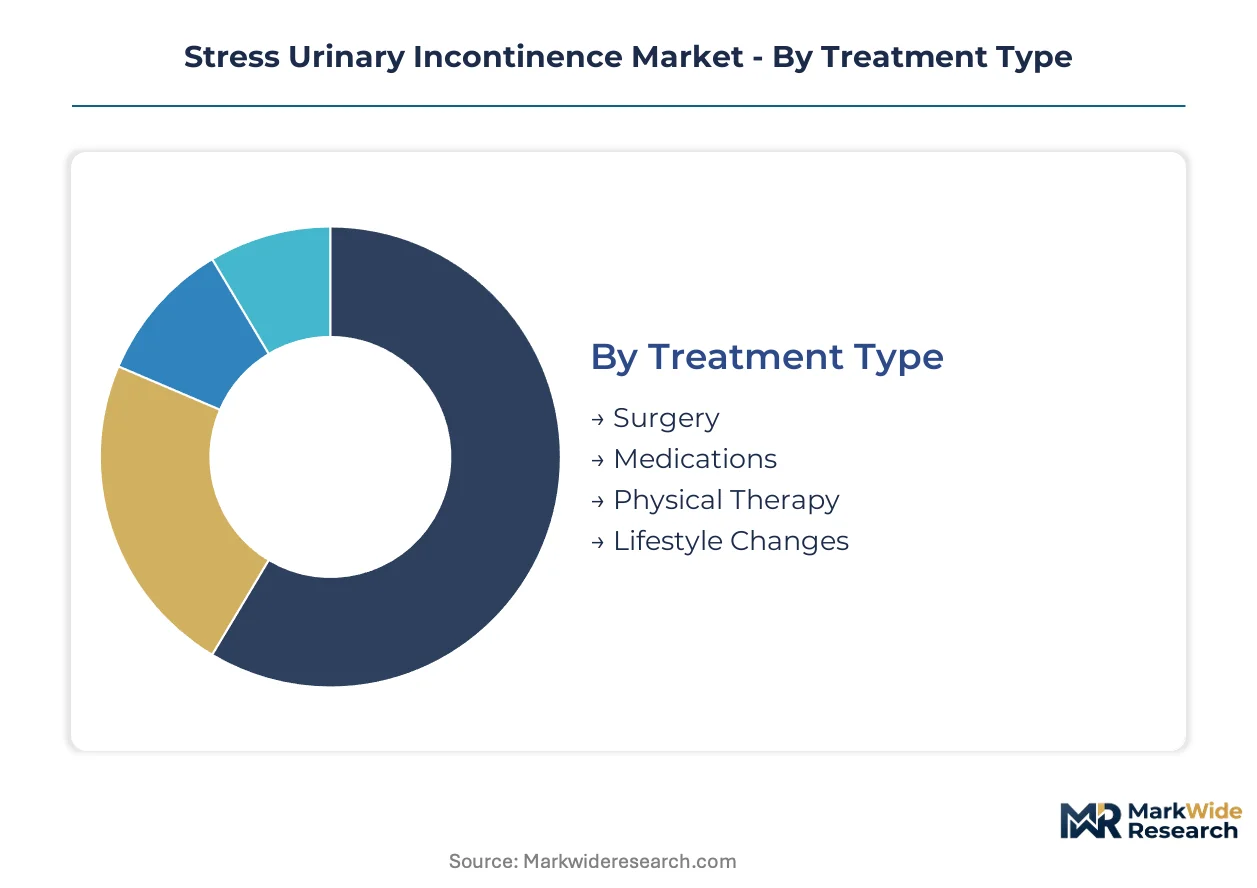
Segmentation in stress urinary incontinence reveals divergent margin architectures across mechanical, pharmacological, and behavioral interventions. Surgical and implantable categories concentrate value capture through recurring neuromodulation revenue and mesh kit replacements, while conservative management segments expand volume through lower-acuity channels with compressed pricing power.
Treatment Type:
Surgery turns over capital equipment on 5-7 year cycles, while lifestyle modifications refresh continuously through consumer repurchase; medications and physical therapy occupy intermediate replacement rhythms tied to prescription renewals and session packages.
- Surgery:Mid-urethral sling placement and sacral neuromodulation implantation deliver mechanical urethral support or pelvic afferent nerve modulation. Demand concentrates in United States hospital outpatient departments and ambulatory surgical centers where CMS reimbursement pathways and aging demographics sustain procedural volumes, though polypropylene mesh litigation constrains synthetic sling adoption.
- Physical Therapy:Pelvic floor muscle training and biofeedback protocols strengthen urethral sphincter competence through supervised exercise regimens. Concentration is rising in Germany and France where conservative management protocols precede surgical referral, driven by urogynecology guideline evolution and lower complication risk profiles.
- Medications:Alpha-adrenergic agonists and topical estrogen formulations target urethral mucosal tone and sphincter contractility.
- Lifestyle Changes:Weight reduction, fluid management, and bladder training protocols reduce intra-abdominal pressure on the urethrovesical junction.
Surgery anchors the volume base while physical therapy gains share at the steepest rate as European reimbursement frameworks prioritize step-care protocols.
Product Category:
Cost tiers stratify sharply: implants and devices command premium pricing through regulatory complexity and surgical placement requirements, while pads compete as price-sensitive consumables with minimal differentiation.
- Implants:Synthetic polypropylene mesh kits and biologic xenograft slings provide permanent or resorbable mechanical support at the urethrovesical junction. Demand clusters in United States academic medical centers where fellowship-trained urogynecologists manage complex cases, constrained by FDA post-market surveillance mandates and biologic graft supply limitations from Swiss and Irish processing facilities.
- Devices:Sacral neuromodulation systems and single-incision mini-sling delivery instruments enable minimally invasive procedural execution. Bluetooth-enabled programmer adoption is expanding fastest in Texas and Florida multi-site urology practices where pay-per-procedure leasing aligns vendor revenue with clinical utilization.
- Pads:Absorbent continence products manage leakage episodes through disposable or reusable garment systems.
- Surgical Instruments:Trocars, needle passers, and fixation devices facilitate sling placement and neuromodulation lead insertion.
Pads anchor the volume base while devices expand most quickly through ambulatory surgical center adoption and remote patient monitoring integration.
Patient Type:
Application urgency varies: postpartum women present acute onset with potential spontaneous resolution, while elderly women manifest chronic progressive conditions requiring escalating intervention intensity.
- Elderly Women:Age-related pelvic floor denervation and urethral mucosal atrophy produce chronic stress incontinence requiring durable mechanical or neuromodulatory solutions. United States Medicare beneficiaries dominate procedural volumes as established coverage pathways and urogynecology workforce concentration enable access.
- Postpartum Women:Parturition-induced pelvic floor trauma and urethral hypermobility generate de novo incontinence often amenable to conservative management. Physical therapy demand is climbing fastest in France and Germany where postpartum pelvic floor rehabilitation is standard of care.
- Surgical Candidates:Patients failing conservative management with anatomical prolapse or intrinsic sphincter deficiency meet criteria for sling or neuromodulation implantation.
- Non-Surgical Candidates:Comorbidity burden, anticoagulation requirements, or patient preference directs toward pharmacological or behavioral management pathways.
Elderly women anchor the volume base while postpartum women represent the fastest-climbing trajectory as European postnatal care protocols expand pelvic floor service access.
Distribution Channel:
Customer type fragmentation drives channel strategy: hospitals capture high-acuity surgical cases, pharmacies manage prescription renewals, and online retail serves stigma-sensitive consumable purchasers.
- Hospitals:Operating rooms and outpatient surgical suites deliver implantable devices and procedural services through employed or affiliated urogynecologists. United States hospital outpatient departments concentrate neuromodulation generator placements and complex revision surgeries where specialized complication management capabilities reside.
- Clinics:Urology and urogynecology offices provide physical therapy, medication management, and device programming services. Independent practice adoption of single-incision mini-sling systems is accelerating in Texas and Florida where pay-per-procedure leasing reduces capital barriers.
- Pharmacies:Retail and specialty pharmacy networks dispense alpha-adrenergic agents and topical estrogen formulations.
- Online Retail:E-commerce platforms deliver absorbent pads and pelvic floor training devices with privacy-preserving direct-to-consumer logistics.
Hospitals anchor the volume base while clinics gain share at the steepest rate through ambulatory surgical center migration and asset-light service model proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in continence care devices favor net-importing developed markets, with manufacturing concentration in Switzerland and Ireland for biologic graft materials creating supply dependencies for major consuming regions. The United States absorbs the largest absolute volume of implantable neuromodulation systems and synthetic sling kits, while European markets exhibit stronger conservative management penetration that moderates surgical device import intensity.
United States
Medicare beneficiary expansion and established CPT reimbursement codes for sacral neuromodulation sustain procedural volume leadership. FDA post-market surveillance mandates for surgical mesh products shape manufacturer compliance investments and litigation risk management. The Texas and Florida multi-site urology practice clusters are accelerating pay-per-procedure leasing adoption for mini-sling systems.
Germany
Step-care reimbursement protocols prioritize pelvic floor physical therapy before surgical authorization, compressing immediate device demand while extending treatment pathways. The EU MDR's strengthened clinical evidence requirements are forcing technical documentation redesign for market access maintenance. The Baden-Württemberg medical technology corridor hosts specialized biologic graft processing facilities serving continental European demand.
France
Postpartum pelvic floor rehabilitation standardization is expanding conservative management service capacity and delaying surgical referral timelines. ANSM oversight of implantable urogynecological devices aligns with EU MDR transitional provisions for Class III device recertification. The Île-de-France academic medical centers concentrate fellowship-trained urogynecologists managing complex revision cases.
United Kingdom
NICE guideline evolution toward conservative-first management is shifting commissioning priorities away from primary surgical intervention. MHRA post-Brexit regulatory divergence from EU MDR is creating parallel conformity assessment requirements for device manufacturers. The Greater Manchester and London hospital networks are piloting remote neuromodulation programming services to reduce outpatient clinic burden.
Switzerland
Specialized xenogenic and autologous tissue processing capacity controls upstream supply for European biologic sling manufacturers. Swissmedic medical device authorization requirements maintain alignment with EU MDR standards despite non-member status. The Basel-Zurich corridor concentrates contract manufacturing organizations serving global orthopedic and urogynecological implant demand.
Stress Urinary Incontinence Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and single-use instrumentation. The vendor base organizes around three strategic archetypes: diversified surgical conglomerates cross-selling pelvic floor solutions, focused continence care specialists with deep urology channel relationships, and contract manufacturers supplying biologic graft materials to branded device marketers. Competitive maneuvering concentrates on M&A for neuromodulation platform access and strategic partnerships for bioresorbable material development pipelines.
Among the diversified surgical portfolio holders, Medtronic and Boston Scientific Corporation occupy positions spanning sacral neuromodulation systems and minimally invasive sling platforms, while Coloplast A/S exemplifies the focused continence specialist archetype with dedicated urogynecological channel infrastructure. These three entities represent distinct competitive postures: the cross-selling conglomerate, the R&D-intensive interventional platform provider, and the disease-state specialist, respectively.
| Leading Market Players |
|---|
| Coloplast A/S |
| Boston Scientific Corporation |
| Johnson & Johnson Services |
| BD |
| Laborie |
| CooperSurgical |
| Teleflex Incorporated |
| Medtronic |
| Cook Medical |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Swiss and Irish biologic graft processing facilities determines both three-tier pricing structure across premium, standard, and economy levels and supply chain vulnerability to EU MDR compliance disruptions. Polypropylene mesh litigation exposure compresses synthetic sling margins while elevating biologic premium tiers, forcing manufacturers to absorb certification costs or pass through to hospital buyers.
Pricing Analysis
Hospital outpatient departments anchor device pricing through CMS reimbursement pathways that stratify by procedure complexity and implant material class. Premium-mid-economy pricing differentiation separates biologic xenografts from synthetic polypropylene kits and basic absorbable alternatives, with certification tier—FDA 510(k) versus PMA pathway—adding further spread. Cost compression in the synthetic mesh tier intensifies because payer coverage restrictions and litigation reserves erode vendor margins. Ambulatory surgical centers exhibit highest price sensitivity due to pay-per-procedure leasing structures, while academic medical centers absorb premium biologic costs through bundled episode payments.
Supply Chain Analysis
Tariff exposure between Switzerland and continental EU member states dominates biologic sling material flows, with specialized tissue processing capacity concentrated in Basel-Zurich and Cork-Dublin corridors. Raw material dependencies center on porcine dermal matrices, cadaveric fascia, and ultra-high molecular weight polyethylene monofilaments. Single-source vulnerability pervades the xenograft supply tier where two processors control European autologous tissue preparation. Distribution runs through GPO-negotiated hospital contracts in the United States and direct tender relationships with German and French regional health authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled neuromodulation programmer ecosystems are redefining competitive moats around data interoperability and remote titration subscriptions, shifting value capture from hardware placement to recurring software services.
For Market Incumbents: Insulate sacral neuromodulation generator positions through backward integration into lead manufacturing and captive biologic graft processing in Switzerland. Deepen FDA 510(k) pipeline reserves against emerging bioresorbable competitors while locking multi-site urology practice clusters into exclusive pay-per-procedure arrangements in Texas and Florida. For New Entrants and Emerging Players: Establish a beachhead in postpartum pelvic floor rehabilitation services across Germany and France where conservative management protocols create device-agnostic entry points. Target independent ambulatory surgical centers with single-incision mini-sling systems under asset-light leasing terms, bypassing capital-intensive hospital sales cycles. For Investors and Strategic Acquirers: EU MDR recertification deadlines reshape the acquisition landscape toward clinical affairs infrastructure and European epidemiological network assets. Five-to-ten year viability hinges on post-market surveillance capability scale rather than product portfolio breadth alone. Watch FDA guidance evolution on biologic versus synthetic sling materials as the definitive signal for portfolio reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Redesign | Preserves market access for Class III implantable devices across German and French hospital networks. |
| Bluetooth-Enabled Remote Programming Development | Enables subscription revenue capture from Texas and Florida multi-site urology practices. |
| Bioresorbable Polymer Pipeline Investment | Addresses permanent foreign body complication risks driving synthetic mesh litigation exposure. |
| Pay-Per-Procedure Leasing Expansion | Aligns vendor revenue with ambulatory surgical center utilization rates and transfers obsolescence risk. |
| Hospital System Partnership for GPO Contract Access | Secures preferred vendor status within CMS reimbursement pathways for outpatient urogynecology. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, CMS Medicare claims data, EU MDR notified body documentation, and hospital procurement databases. Interviews with urogynecologists, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers informed demand-side validation. Bottom-up procedural volume estimates triangulate against top-down market sizing from trade flow analysis and import statistics.
Forecast inputs span treatment type evolution, product category replacement cycles, patient demographic shifts, and distribution channel migration patterns across the analysis window. Segmentation dimensions modeled include surgical versus conservative management pathways, implant material classes, neuromodulation system generations, and ambulatory versus inpatient site-of-care trajectories. CAGRs derive from logistic diffusion curves fitted to historical adoption rates and adjusted for reimbursement policy inflections.
Sensitivities concentrate around FDA post-market surveillance mandate enforcement intensity, EU MDR transition timeline extensions, and polypropylene mesh litigation settlement patterns. Forecasts reflect documented assumptions on procedural volume elasticity to reimbursement rate changes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market