
 Global Pemphigus Vulgaris Market | 2026-2036
Global Pemphigus Vulgaris Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pemphigus Vulgaris Market Foresight
Combination therapy bundling is restructuring treatment protocols for pemphigus vulgaris, with clinicians increasingly pairing rituximab regimens with corticosteroid taper protocols to reduce relapse rates. F. Hoffmann-La Roche Ltd leverages its oncology manufacturing infrastructure to sustain rituximab supply for off-label autoimmune use. Pfizer Inc. anchors its position through JAK inhibitor research pipelines targeting B-cell signaling pathways. Argenx SE differentiates with its FcRn antagonist technology, competing directly against legacy immunosuppressive standards.
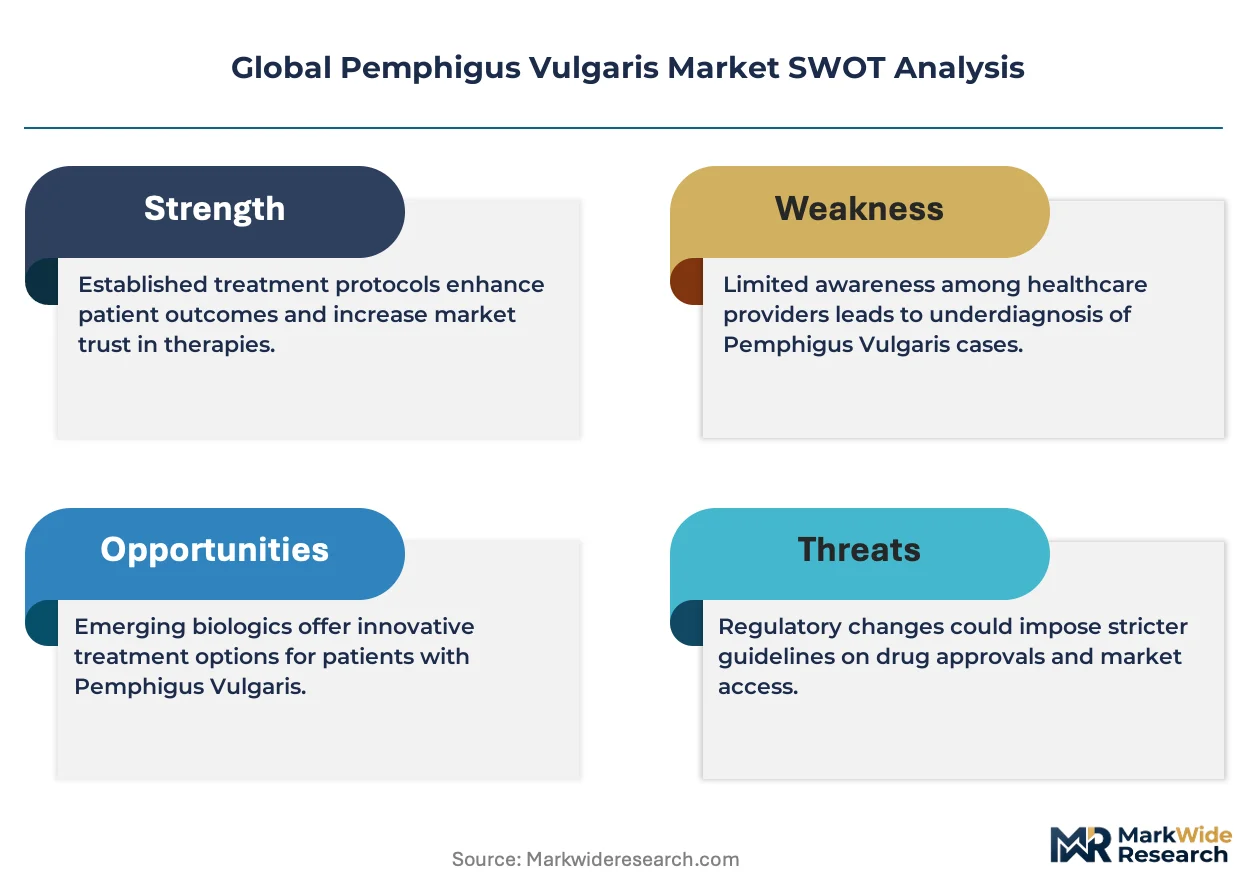
Pemphigus vulgaris constitutes a life-threatening autoimmune mucocutaneous disorder characterized by IgG autoantibodies against desmoglein 1 and desmoglein 3 adhesion proteins, causing acantholysis and flaccid blister formation across epidermal layers. The condition demands sustained immunomodulatory intervention to prevent sepsis and mortality from extensive skin denudation. Biologics command the fastest-expanding product category as anti-CD20 and FcRn-targeted therapies displace chronic corticosteroid dependence. Injectable delivery modes capture premium positioning due to hospital-based infusion requirements, while oral corticosteroids retain volume leadership in emerging markets where infusion infrastructure remains limited.
The FDA orphan drug program shapes development economics through tax credits and market exclusivity incentives for novel pemphigus therapies. EMA's PRIME designation and Japan's PMDA sakigake framework create parallel accelerated pathways that fragment regulatory strategy across development programs. The EU AI Act introduces compliance complexity for diagnostic algorithms used in blistering disease differentiation. Stakeholders must monitor evolving biosimilar competition against reference rituximab and the clinical readouts from next-generation B-cell depleting agents.
Market Dynamics
Biologic therapy protocols are consolidating around FcRn antagonist and anti-CD20 mechanisms, compressing the therapeutic window for chronic corticosteroid maintenance and forcing infrastructure investments in hospital-based infusion capacity.
Growth Catalysts
- FDA Orphan Drug Tax Credits:The incentive framework reduces development costs for novel monoclonal antibodies targeting rare autoimmune indications, accelerating pipeline progression for B-cell depleting agents.
- Specialty Clinic Expansion:Dermatology centers in the United States are adding dedicated infusion suites to administer rituximab and emerging biologics, extending treatment access beyond academic medical centers.
- Desmoglein ELISA Diagnostic Standardization:Quantitative autoantibody testing is unifying diagnosis protocols across tertiary care networks, reducing misclassification of pemphigus subtypes and expediting appropriate therapy initiation.
Market Restraints
- Cold Chain Biologics Distribution:Temperature-controlled logistics for intravenous immunoglobulin and monoclonal antibodies impose infrastructure requirements that limit rural and emerging market access.
- Reimbursement Fragmentation:Payer policies in Germany and France impose step-therapy requirements that delay biologic access until corticosteroid failure, extending time to disease control.
- Plasma-Derived Input Volatility:Immunoglobulin manufacturing depends on fractionated plasma supply concentrated in United States collection centers, exposing production to donor availability swings.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered delivery mechanisms for FcRn antagonists would displace hospital-based infusion requirements, unlocking home care channels and reducing per-dose facility costs.
- Japan's PMDA Sakigake Pathway:The early approval framework offers reduced review timelines for innovative autoimmune therapies, creating first-mover positioning in Asia-Pacific's highest-value rare disease market.
- Teledermatology Triage Networks:Remote blister assessment protocols are penetrating underserved United States regions, accelerating specialist referral and compressing diagnostic delay intervals.
Industry Challenges
- Biosimilar Manufacturing Scale-Up:Reference rituximab biosimilar production requires cell line development expertise concentrated at contract manufacturing organizations in Switzerland and Singapore, creating capacity bottlenecks.
- Cross-Border Regulatory Divergence:EMA's PRIME designation criteria differ from FDA breakthrough therapy standards, forcing parallel dossier preparation that extends development timelines and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pemphigus Vulgaris Market |
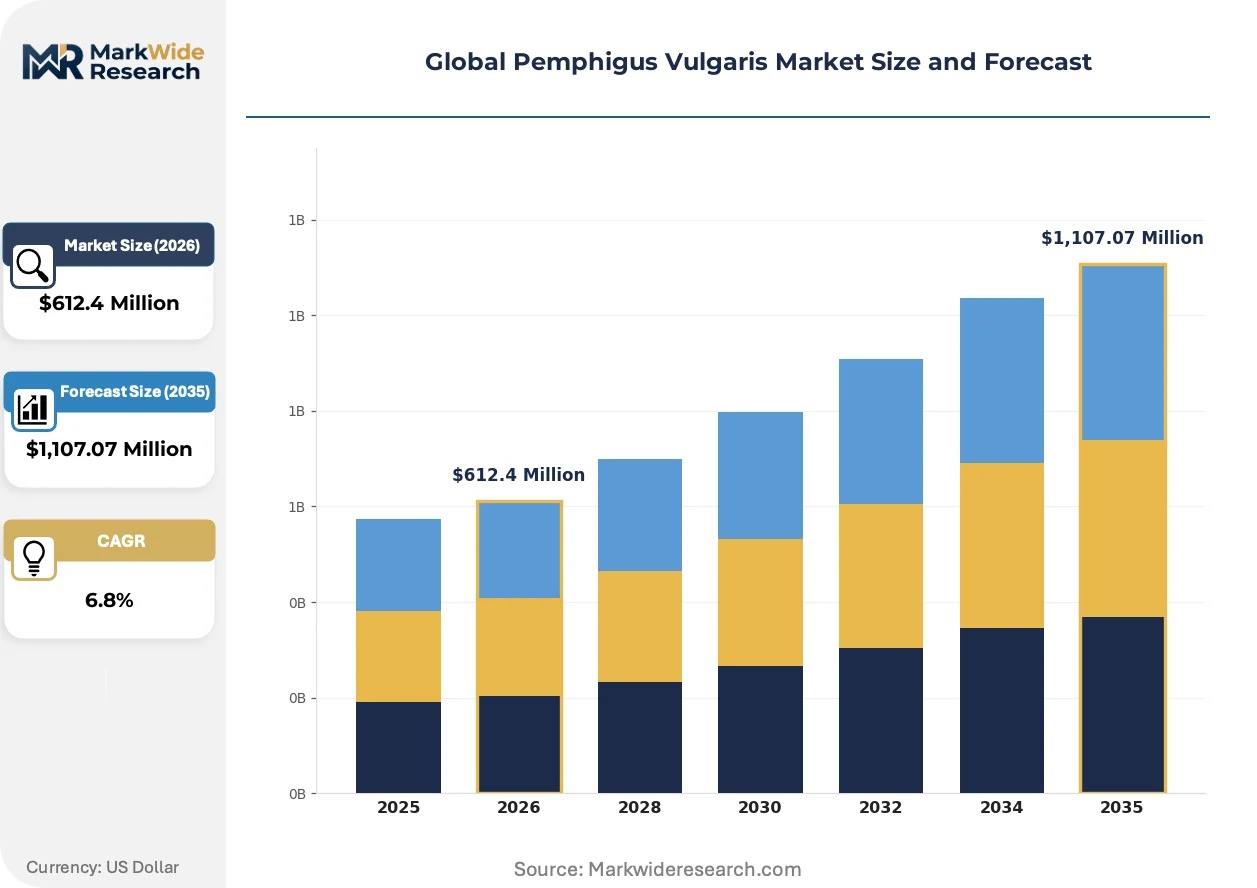
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Systemic Corticosteroids, Immunosuppressants, Biologics, Topical Treatments Therapy Area: Autoimmune Disorders, Dermatological Conditions, Rare Diseases, Chronic Skin Disorders End User: Specialty Clinics, Dermatology Centers, Academic Research Institutes, Outpatient Facilities Delivery Mode: Oral, Injectable, Topical, Intravenous |
| Companies Covered | F. Hoffmann-La Roche Ltd, Pfizer Inc., Novartis AG, AbbVie Inc., Amgen Inc., Sanofi, Argenx SE, CSL Behring GmbH, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pemphigus Vulgaris Market Shifts & Advancements
Mechanism-of-action diversification is fragmenting the therapeutic algorithm, with novel targets emerging alongside established B-cell depletion and FcRn blockade approaches.
Next-generation B-cell modulators are unifying precision dosing with reduced immunogenicity profiles. Academic medical centers in the United States and Germany are piloting these agents in rituximab-refractory cohorts. The convergence is compressing relapse intervals and enabling corticosteroid-free maintenance protocols that were previously unattainable.
EMA's MDR classification rules for companion diagnostics are reshaping blister disease differentiation algorithms. In-vitro diagnostic manufacturers must now submit clinical evidence packages for desmoglein antibody quantification platforms. Dermatology laboratories in France and the Netherlands are consolidating around CE-marked ELISA systems to preempt compliance gaps.
Patient advocacy networks are demanding value-based access agreements that tie reimbursement to sustained remission endpoints. Payers in the United Kingdom and Australia are piloting outcomes-linked contracts for biologic therapies in autoimmune dermatology. The shift is forcing manufacturers to assemble real-world evidence infrastructure that tracks long-term disease control beyond clinical trial horizons.
Global Pemphigus Vulgaris Market Segmentation
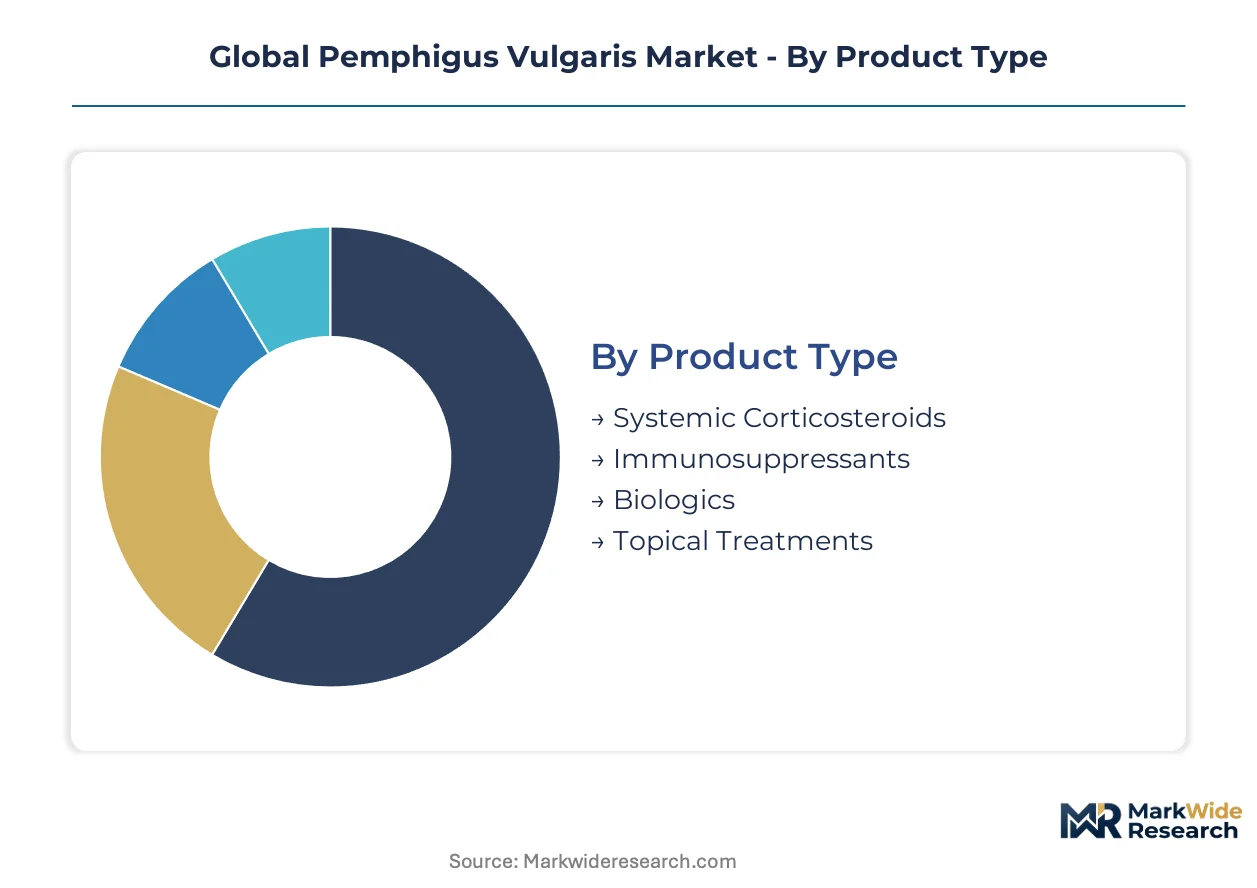
Therapeutic modality selection in pemphigus vulgaris hinges on disease severity, comorbidity profiles, and infusion infrastructure availability. Segmentation reveals how biologic penetration varies sharply across delivery capabilities and prescriber settings.
Product Type:
Cost tier and clinical risk tolerance stratify prescribing patterns across immunomodulatory options.
- Systemic Corticosteroids:First-line intervention utilizing prednisone and methylprednisolone protocols. Demand concentrates in India and Brazil where reimbursement constraints limit biologic access; long-term adrenal suppression drives taper urgency.
- Biologics:Engineered monoclonal antibodies targeting CD20 surface markers and neonatal Fc receptor pathways. United States academic medical centers anchor adoption; rituximab infusion suites expand into community dermatology practices.
- Immunosuppressants:Azathioprine and mycophenolate mofetil serve as steroid-sparing bridge therapies. European step-therapy mandates in Germany and France sustain volume despite slower onset.
- Topical Treatments:Corticosteroid creams and wound care formulations manage localized lesions. Outpatient facilities in Spain and Italy utilize these for maintenance between systemic flares.
Volume sits with systemic corticosteroids; growth tilts toward biologics.
Therapy Area:
Regulatory designation status determines development economics and payer access pathways.
- Rare Diseases:Orphan drug frameworks in the United States and European Union accelerate monoclonal antibody approval timelines. FDA tax credits reduce effective development costs for novel FcRn antagonists.
- Autoimmune Disorders:Shared mechanistic pathways with rheumatoid arthritis and lupus enable indication expansion. Academic research institutes in the United Kingdom repurpose B-cell depletion protocols across dermatology and rheumatology divisions.
- Dermatological Conditions:Blistering disease specialization drives tertiary referral concentration. Dermatology centers in France and the Netherlands consolidate desmoglein antibody testing expertise.
- Chronic Skin Disorders:Longitudinal management requirements differentiate from acute infectious presentations. Outpatient facilities in Australia structure relapse prevention programs around patient education.
Regulatory momentum clusters in rare diseases; clinical volume spreads across autoimmune disorders.
End User:
Prescriber infrastructure depth dictates biologic administration feasibility.
- Specialty Clinics:Dedicated infusion capacity and nursing staff trained in hypersensitivity monitoring. United States metropolitan markets see rapid suite expansion; rural penetration remains uneven.
- Academic Research Institutes:Clinical trial access and refractory case concentration attract novel mechanism investigation. German university hospitals anchor European investigator-initiated studies.
- Dermatology Centers:General dermatology practices with limited infusion capability rely on corticosteroid and immunosuppressant prescribing. Spain's public hospital networks embed these within regional dermatology departments.
- Outpatient Facilities:Ambulatory settings managing stable maintenance patients. India's tier-2 cities utilize these for oral medication dispensing and wound care follow-up.
Complex case concentration favors academic research institutes; patient volume flows through specialty clinics.
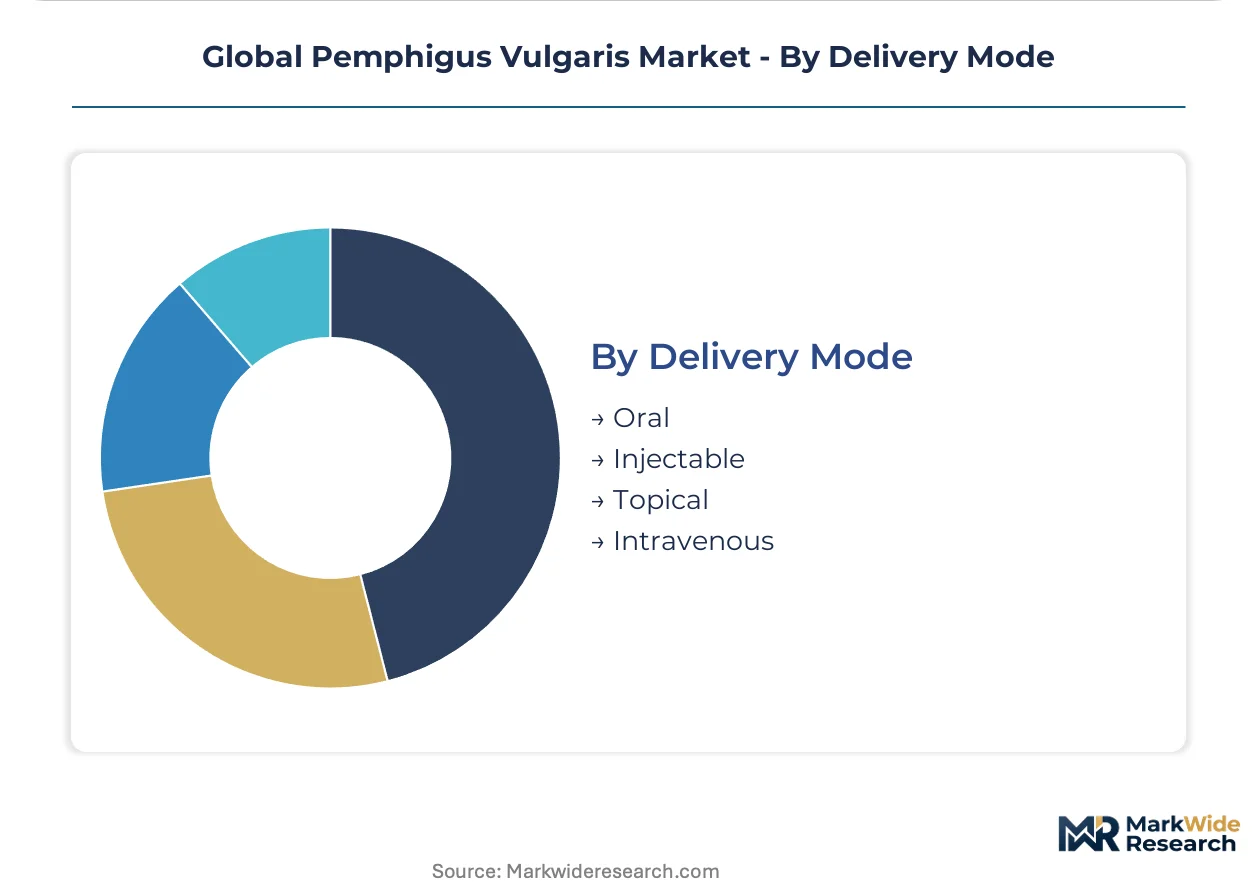
Delivery Mode:
Administration setting requirements shape geographic and economic access patterns.
- Intravenous:Hospital-based infusion mandates for rituximab and intravenous immunoglobulin. Cold chain logistics and nursing supervision limit deployment to tertiary centers in Brazil and Mexico.
- Injectable:Subcutaneous FcRn antagonist development targets home administration. Japan's PMDA sakigake pathway prioritizes reduced facility burden for innovative delivery formats.
- Oral:Prednisone and mycophenolate mofetil enable community-based initiation. Emerging markets in Southeast Asia rely on this mode where infusion infrastructure is nascent.
- Topical:Patient-directed application for lesion management. Australian primary care networks integrate these into teledermatology follow-up protocols.
Facility dependence anchors intravenous volume; patient convenience drives injectable development priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Orphan Drug Tax Credit zone concentrates pemphigus vulgaris biologic development, with FDA incentives drawing monoclonal antibody investment toward Boston-Cambridge and San Francisco Bay Area clusters.
United States
Academic medical centers in Boston and New York anchor rituximab infusion expansion into community dermatology practices. FDA orphan drug designation accelerates novel FcRn antagonist timelines through tax credit offsets. The Mayo Clinic Rochester network standardizes desmoglein ELISA protocols across Midwest tertiary referrals.
Germany
University hospitals in Berlin and Munich pilot next-generation B-cell modulators for refractory cohorts. EMA PRIME designation criteria shape parallel dossier preparation alongside FDA submissions. The Heidelberg dermatology cluster consolidates investigator-initiated studies across European investigator networks.
Japan
Tokyo and Osaka dermatology centers drive subcutaneous formulation trials through PMDA sakigake accelerated review pathways. METI rare disease funding supports domestic biologic manufacturing scale-up. The Kobe biomedical cluster houses specialized infusion capacity for autoimmune blistering cases.
France
Paris and Lyon tertiary networks enforce step-therapy mandates that delay biologic access until corticosteroid failure. ANSM pharmacovigilance requirements shape post-market surveillance for anti-CD20 therapies. The Strasbourg dermatology institute advances desmoglein antibody quantification platform validation.
Australia
Sydney and Melbourne outpatient facilities structure relapse prevention programs around patient education protocols. TGA reimbursement pilots tie biologic access to sustained remission endpoints. The Brisbane teledermatology network compresses diagnostic delay intervals for regional blister assessment.
Global Pemphigus Vulgaris Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the pemphigus vulgaris therapeutic space. The market structure consolidates around three tiers: oncology-derived biologic manufacturers repurposing infrastructure, rare disease specialists advancing novel mechanisms, and plasma fractionators securing immunoglobulin supply. Dominant competitive moves include strategic partnerships for diagnostic companion development and geographic licensing agreements for subcutaneous formulation distribution.
Within the diversified pharmaceutical tier, F. Hoffmann-La Roche Ltd and Pfizer Inc. occupy positions leveraging existing manufacturing infrastructure for autoimmune indications. Argenx SE exemplifies the focused rare disease specialist archetype, with its Belgium-based structure anchoring FcRn antagonist development. These three entities represent contrasting strategic postures: legacy biologic repurposing against novel mechanism investment.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Novartis AG |
| AbbVie Inc. |
| Amgen Inc. |
| Sanofi |
| Argenx SE |
| CSL Behring GmbH |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Cold chain sustainability mandates for biologics distribution gate qualified supply access and premium-tier pricing power, as FDA and EMA validation requirements for temperature-controlled logistics separate certified manufacturers from commodity corticosteroid suppliers. Buyers in United States academic medical centers absorb facility-dependent infusion premiums, while emerging market procurement in India and Brazil gravitates toward oral formulations where cold chain infrastructure remains undeveloped.
Pricing Analysis
Margin tightening in biologic tiers reflects plasma-derived input volatility and fractionation capacity constraints concentrated at United States collection centers. Three-tier pricing structure across FcRn antagonist premium, rituximab standard, and corticosteroid economy levels stratifies by mechanism novelty and infusion infrastructure requirements. Cost-down pressure on intravenous immunoglobulin accelerates because donor availability swings disrupt fractionated supply. Payers in Germany and France exhibit highest price sensitivity due to step-therapy mandates, while United States orphan drug reimbursement sustains premium capture.
Supply Chain Analysis
EMA MDR certification and FDA biologics license requirements gate qualified manufacturing capacity for monoclonal antibodies and plasma-derived therapies. Supply concentrates in United States plasma collection networks, Swiss contract manufacturing organizations, and Singapore cell line development facilities. Raw material dependencies span fractionated human plasma, recombinant cell substrates, and single-use bioreactor components. Single-source vulnerability concentrates at United States plasma collection centers, exposing immunoglobulin production to donor availability disruption. Distribution runs through hospital-based infusion suites and specialty pharmacy channels with cold chain custody requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into plasma collection and fractionation infrastructure anchors competitive positioning, as control over immunoglobulin supply inputs separates sustainable biologic manufacturers from formulation-dependent competitors.
For Market Incumbents: Cement supply security through backward integration into plasma collection infrastructure or captive fractionation agreements with United States collection networks. Biosimilar rituximab manufacturing scale-up at Swiss and Singapore contract organizations threatens reference product margins; defend through FcRn antagonist pipeline advancement and subcutaneous formulation development that reduces facility dependence. For New Entrants and Emerging Players: The price-point gap between premium biologics and economy corticosteroids in India and Brazil offers white-space entry for oral JAK inhibitor development targeting steroid-refractory patients. Teledermatology triage networks in underserved United States regions present the most penetrable channel for diagnostic algorithm partnerships. Pursue licensing agreements with academic medical centers for desmoglein ELISA companion diagnostic co-development. For Investors and Strategic Acquirers: PMDA sakigake pathway approvals for subcutaneous FcRn antagonists are the leading indicator that home administration formats will displace hospital-based infusion requirements across Asia-Pacific markets. Target acquisition profiles center on rare disease specialists with validated FcRn platforms and subcutaneous delivery expertise. Monitor EMA PRIME designation grants as inflection signals for accelerated European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Self-administered delivery displaces hospital infusion requirements and unlocks home care channels. |
| Plasma Collection Integration | Backward control over fractionated supply inputs secures immunoglobulin manufacturing continuity. |
| Companion Diagnostic Partnership | Desmoglein ELISA co-development with Mayo Clinic standardizes tertiary referral protocols. |
| PMDA Sakigake Pathway Engagement | Accelerated Japanese review reduces time-to-market for innovative autoimmune mechanisms. |
| Real-World Evidence Infrastructure | Outcomes-linked contracts with United Kingdom and Australian payers tie reimbursement to remission endpoints. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads at FDA and EMA, formulary directors at United States academic medical centers, and payer access specialists underwrites the qualitative findings. Secondary validation draws from FDA orphan drug filings, EMA PRIME designation databases, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up patient population estimates and top-down biologic revenue triangulation anchor market size construction.
Rate-of-change decomposition across therapeutic modality, delivery mode, and regional regulatory cluster segments isolates growth contribution by mechanism. CAGRs derive from patient incidence modeling, treatment penetration assumptions, and pricing trajectory analysis across the projection horizon. Forecast inputs incorporate rituximab biosimilar erosion curves, FcRn antagonist launch sequencing, and corticosteroid taper protocol adoption in academic versus community settings.
Inputs from clinical trial registries and payer policy documents were available through the study window; gaps in real-world treatment persistence data introduce uncertainty bands around long-term biologic adherence assumptions. Forecasts reflect documented assumptions regarding regulatory approval timelines and reimbursement negotiation outcomes. A model refresh is warranted upon material change in FDA orphan drug tax credit policy or EMA MDR enforcement posture for companion diagnostics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Dry Eye Syndrome Market