
 Calcineurin Inhibitor Drugs Market | 2026-2036
Calcineurin Inhibitor Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Calcineurin Inhibitor Drugs Market Outlook
Buyer concentration among hospital systems and specialized transplant centers is rebalancing as ambulatory infusion clinics and homecare settings gain reimbursement traction for oral tacrolimus monitoring. Novartis AG sustains its historical franchise in transplant immunosuppression through established nephrology channel relationships. Astellas Pharma Inc. dominates the tacrolimus segment with manufacturing scale that anchors supply contracts across major academic medical centers. Roche differentiates through diagnostic companion offerings that pair therapeutic drug monitoring with calcineurin inhibitor dosing protocols.
Calcineurin inhibitor drugs are a class of immunosuppressive agents that block the phosphatase activity of calcineurin, a calcium-calmodulin-dependent serine-threonine phosphatase, thereby preventing nuclear translocation of NFAT transcription factors and subsequent IL-2 gene expression in T-lymphocytes. These compounds, whether macrolide lactones like tacrolimus or cyclic peptides like ciclosporin, serve primarily to prevent allograft rejection in solid organ transplantation and to modulate pathologic immune responses in autoimmune disorders. The therapy area segmentation reveals transplant rejection as the mature revenue base while dermatological conditions represent the fastest-growing application as topical pimecrolimus expands into atopic dermatitis management. Oral delivery mode commands the volume share due to chronic maintenance dosing requirements, though intravenous formulations retain premium positioning in perioperative induction protocols.
FDA bioequivalence requirements for narrow therapeutic index immunosuppressants create regulatory barriers that protect innovator formulations and constrain rapid generic substitution in the United States. The EMA's MDR and pharmacovigilance frameworks in Europe impose post-market surveillance obligations that elevate compliance costs for manufacturers serving transplant populations. China's NMPA has implemented accelerated review pathways for locally produced calcineurin inhibitors, reshaping competitive access in the world's second-largest transplant market. Stakeholders must monitor evolving therapeutic drug monitoring guidelines and biosimilar equivalence standards that will determine substitution eligibility and margin preservation across major markets.
Market Dynamics
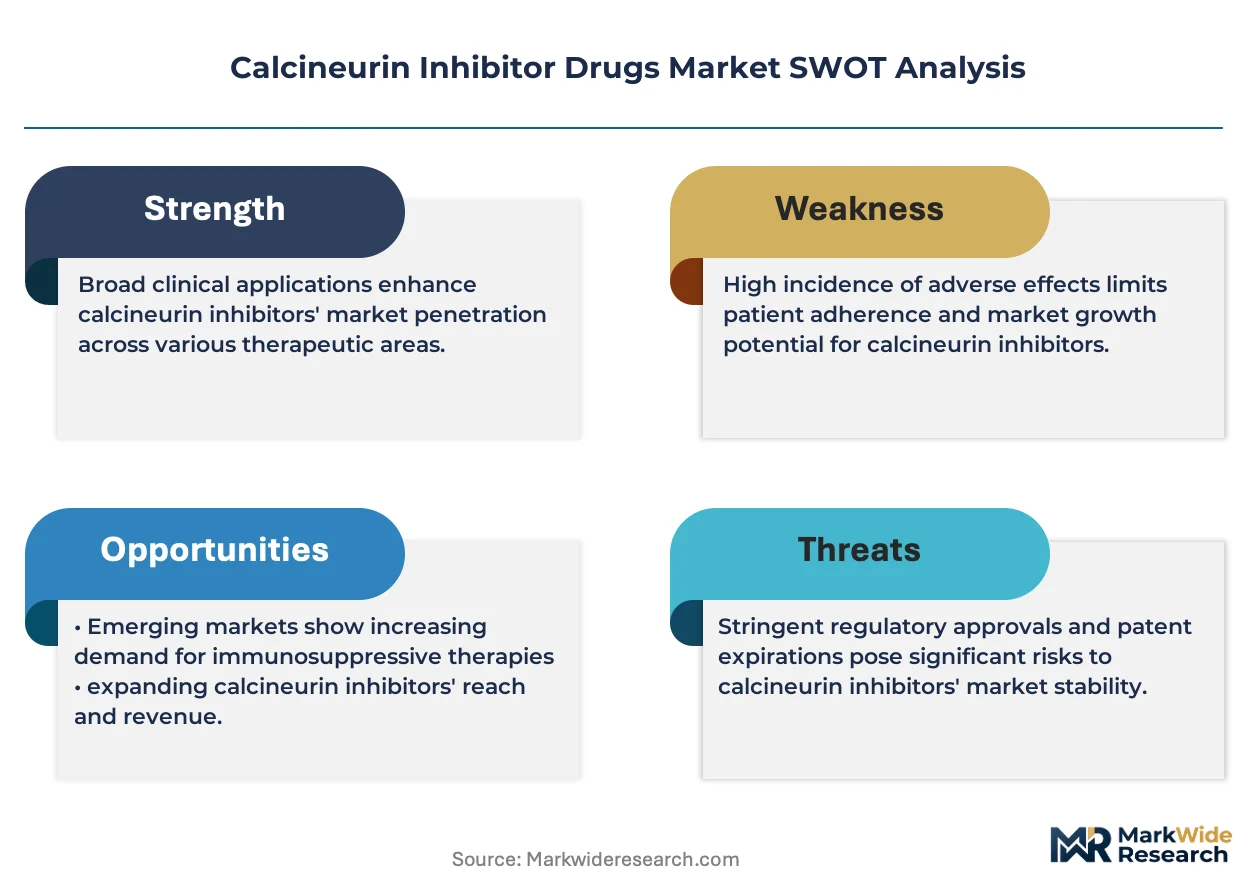
Generic substitution barriers around tacrolimus bioequivalence are concentrating margin in innovator formulations while China's NMPA accelerates domestic manufacturing approvals, creating divergent competitive dynamics across transplant markets.
Growth Catalysts
- Accelerated NMPA pathways:China's National Medical Products Administration has compressed review timelines for locally produced calcineurin inhibitors, expanding domestic manufacturing capacity for organ transplantation programs.
- Topical pimecrolimus expansion:Dermatology clinics are adopting topical calcineurin inhibitors for atopic dermatitis management, creating new prescription volume outside transplant centers.
- Therapeutic drug monitoring integration:Diagnostic protocols pairing immunoassay platforms with calcineurin inhibitor dosing are standardizing precision medicine approaches in nephrology.
Market Restraints
- Narrow therapeutic index constraints:FDA bioequivalence requirements for tacrolimus create regulatory friction that slows generic substitution and protects incumbent pricing power.
- API supply concentration:Active pharmaceutical ingredient production for macrolide lactones clusters among specialized fermentation facilities in Asia, exposing formulation networks to single-source risk.
- Biologic substitution pressure:Monoclonal antibody induction therapies in perioperative protocols are compressing calcineurin inhibitor utilization in high-risk transplant populations.
Strategic Opportunities
- Home-based oral monitoring:Ambulatory care settings and homecare reimbursement pathways for tacrolimus blood level testing are opening distribution channels beyond hospital pharmacies.
- Companion diagnostic bundling:Integration of pharmacogenomic testing with calcineurin inhibitor selection protocols offers value-based positioning for precision dosing services.
- EMA MDR compliance services:Post-market surveillance obligations under Europe's Medical Device Regulation create service revenue streams for therapeutic drug monitoring platform vendors.
Industry Challenges
- Bioanalytical talent scarcity:Clinical pharmacology laboratories face recruitment gaps for mass spectrometry specialists capable of validating immunosuppressant assays under CAP accreditation standards.
- Cold chain integrity costs:Intravenous cyclosporine formulations require temperature-controlled distribution infrastructure that elevates logistics expenditure for regional hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcineurin Inhibitor Drugs Market |
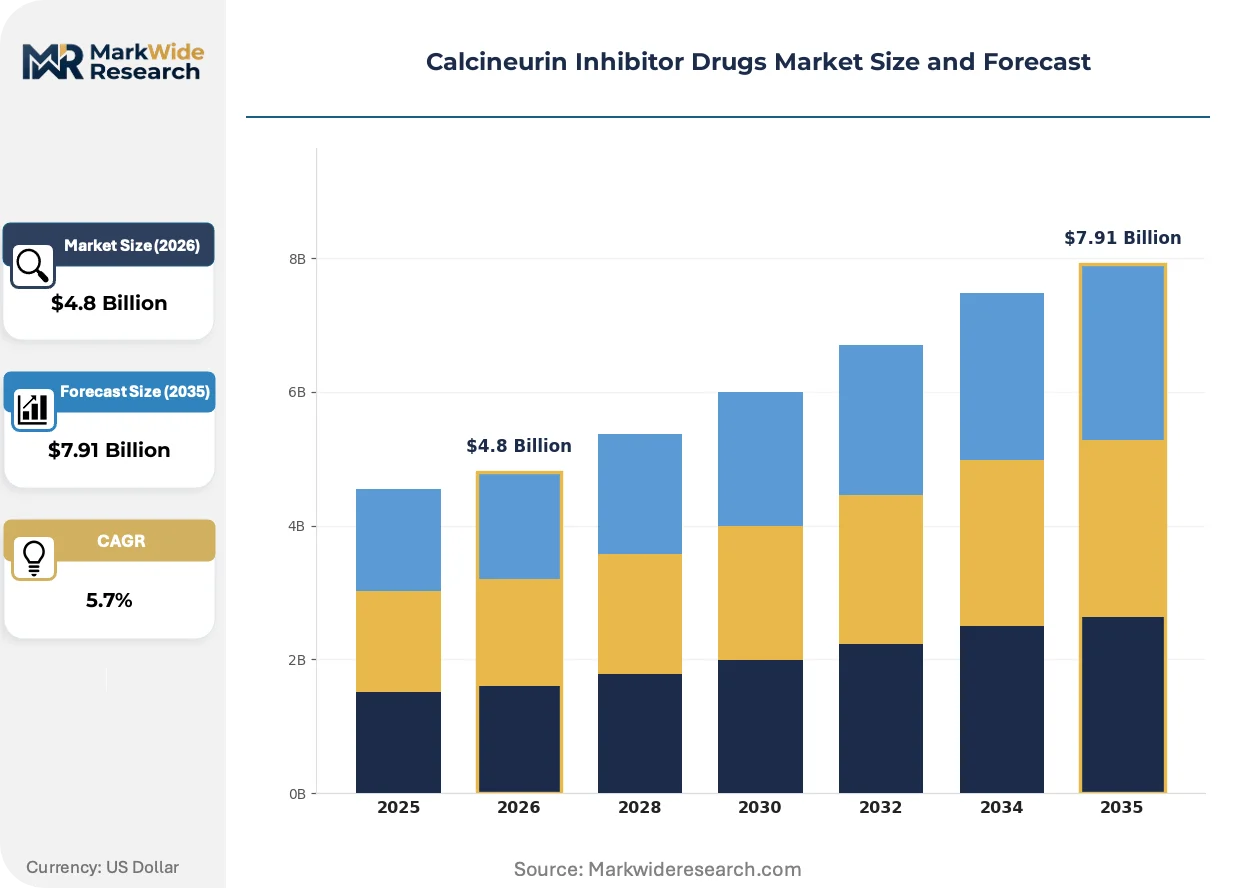
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ciclosporin, Tacrolimus, Pimecrolimus, Others Therapy Area: Transplant Rejection, Autoimmune Disorders, Dermatological Conditions, Inflammatory Diseases Delivery Mode: Oral, Topical, Injectable, Intravenous End User: Hospitals, Clinics, Homecare Settings, Research Laboratories |
| Companies Covered | Otsuka Pharmaceuticals, Roche, Novartis AG, Biocon, Viatris Inc., Astellas Pharma Inc., AbbVie, Dr. Reddy’s Laboratories Ltd., Aurinia Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcineurin Inhibitor Drugs Market Strategic Shifts
Digital biomarker integration and point-of-care testing platforms are compressing the feedback loop between drug administration and dose adjustment, reshaping how transplant centers manage immunosuppression protocols.
Microsampling devices for capillary blood collection are converging with smartphone-connected readers to enable patient-administered tacrolimus monitoring outside clinical settings. Home dialysis providers and rural transplant follow-up clinics are piloting these systems to reduce travel burden for stable graft recipients. This distributed testing architecture is converging with centralized laboratory information systems, creating hybrid care models that split testing volume between sites.
Europe's Medical Device Regulation and pharmacovigilance frameworks now mandate systematic post-authorization safety studies for narrow therapeutic index drugs used in transplant populations. Manufacturers serving EU markets must maintain active registries tracking long-term graft outcomes and adverse event profiles. These surveillance obligations fall most heavily on generic sponsors seeking MDR compliance for tacrolimus formulations, elevating entry costs relative to historical standards.
Hospital procurement committees are consolidating immunosuppressant purchasing through specialty pharmacy carve-outs and 340B program optimization. Academic medical centers increasingly contract with limited distribution pharmacies for oral tacrolimus fulfillment, displacing traditional wholesaler relationships. This channel concentration is most advanced in United States transplant networks, where integrated delivery systems capture pharmacy margin through captive specialty dispensaries.
Calcineurin Inhibitor Drugs Market Segmentation
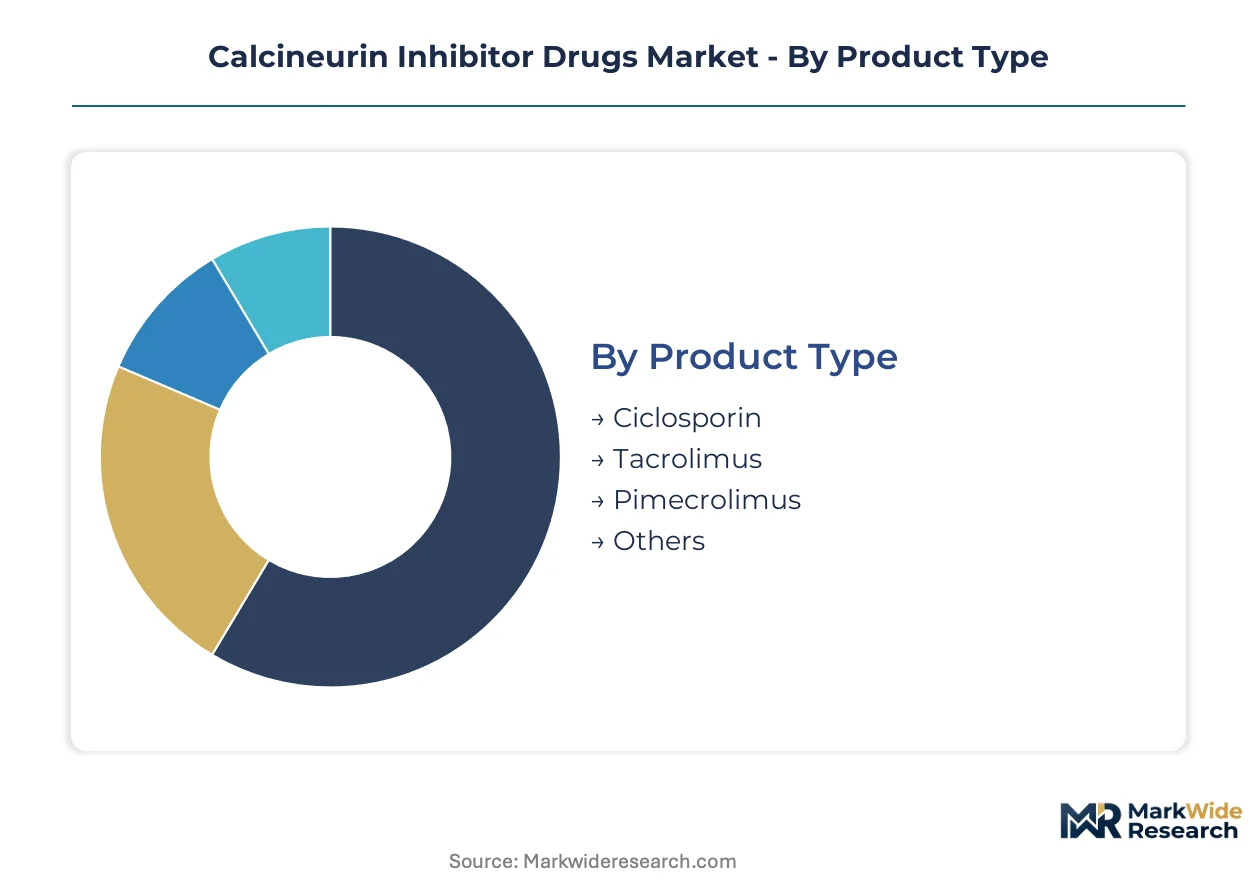
Calcineurin inhibitor portfolios require granular segmentation to capture divergent clinical applications and distribution economics. Product chemistry, therapy setting, delivery route, and care location each reshape procurement patterns and margin structures for manufacturers and channel intermediaries.
Product Type:
Integration depth varies sharply across this category, with macrolide lactones embedding into chronic maintenance protocols while cyclic peptides retain standalone perioperative positioning.
- Tacrolimus:Macrolide lactone derived from Streptomyces tsukubaensis with 50-100 times the potency of ciclosporin. Demand concentrates in United States academic medical centers where FDA bioequivalence standards protect innovator formulations from rapid generic displacement.
- Ciclosporin:Cyclic undecapeptide isolated from Tolypocladium inflatum that revolutionized transplant survival rates. Volume placements cluster in China where NMPA accelerated domestic manufacturing approvals reduced import dependency for kidney transplantation programs.
- Pimecrolimus:Ascomycin derivative engineered for topical immunosuppression with reduced systemic absorption. Dermatology clinics in Germany and France are expanding prescriptions for atopic dermatitis beyond pediatric populations.
- Others:Includes voclosporin and experimental analogs in development pipelines, plus veterinary formulations with limited human crossover.
Volume placements concentrate in tacrolimus; the faster expansion belongs to pimecrolimus.
Therapy Area:
Cost tier stratification separates mature transplant maintenance from emerging autoimmune and dermatological applications with distinct pricing power.
- Transplant Rejection:Prophylaxis against solid organ allograft rejection in kidney, liver, heart, and lung transplantation. Nephrology centers in Japan and South Korea anchor procurement volumes through government-funded organ allocation systems.
- Dermatological Conditions:Atopic dermatitis, psoriasis, and vitiligo management using topical formulations. Pediatric dermatology practices in Spain and Italy are driving prescription growth as steroid-sparing alternatives gain regulatory endorsement.
- Autoimmune Disorders:Systemic lupus erythematosus, rheumatoid arthritis, and inflammatory bowel disease modulation. Rheumatology clinics in the United Kingdom face reimbursement constraints that limit off-label expansion.
- Inflammatory Diseases:Nephrotic syndrome, uveitis, and severe asthma with calcineurin-dependent pathophysiology. Specialist networks in Australia and Canada maintain restricted access protocols.
Revenue weight sits with transplant rejection; dermatological conditions are climbing the fastest.
Delivery Mode:
Customer type mapping reveals hospital pharmacy dominance in intravenous induction versus homecare penetration for oral maintenance.
- Oral:Capsule and tablet formulations for chronic outpatient immunosuppression. Medicare Part D and commercial insurers in the United States have expanded mail-order pharmacy networks that displace hospital dispensary volume.
- Intravenous:Perioperative induction and rescue therapy for graft dysfunction. Cold chain requirements and compounding pharmacy regulations elevate logistics costs for regional hospital networks in Brazil and Mexico.
- Topical:Cream and ointment vehicles for localized dermatological application. Retail pharmacy chains in France and Germany capture margin through direct-to-consumer dispensing.
- Injectable:Subcutaneous depot formulations in limited commercial availability. Research protocols at academic centers in Switzerland and the Netherlands are evaluating sustained-release alternatives.
Volume concentrates in oral delivery; intravenous retains premium positioning.
End User:
Supply concentration patterns favor integrated hospital systems while ambulatory channels fragment purchasing authority.
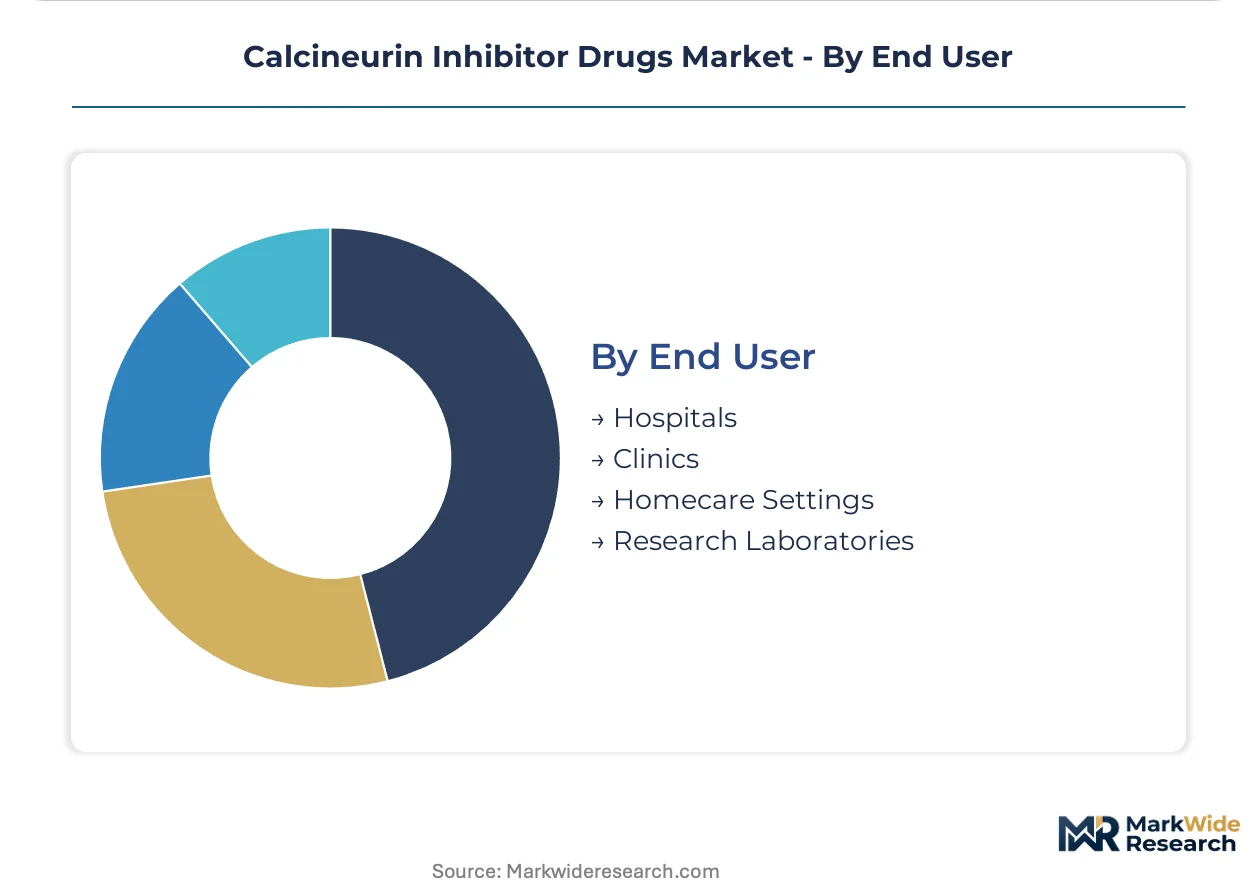
- Hospitals:Transplant centers and nephrology units with captive specialty pharmacies. United States 340B program optimization has concentrated procurement through academic medical center networks.
- Homecare Settings:Patient-administered oral tacrolimus with remote therapeutic drug monitoring. Dialysis providers in Sweden and Denmark are piloting microsampling devices for rural graft recipient follow-up.
- Clinics:Dermatology and rheumatology outpatient facilities with limited formulary control. Private practice networks in India face price pressure from government tender systems.
- Research Laboratories:Clinical trial supply and pharmacokinetic study materials. CRO partnerships in Singapore and South Korea support bioequivalence validation for generic sponsors.
Procurement authority concentrates in hospitals; homecare settings are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transplant center density and regulatory stringency concentrate demand across five national markets with divergent approval pathways and reimbursement structures.
United States
Academic medical centers in Boston, Houston, and San Francisco anchor procurement volumes through integrated specialty pharmacy networks. FDA bioequivalence standards for narrow therapeutic index immunosuppressants protect innovator tacrolimus formulations from rapid generic displacement. The 340B program optimization concentrates purchasing authority through captive hospital dispensaries.
China
Government-funded organ transplantation programs in Beijing, Shanghai, and Guangzhou drive volume requirements for kidney and liver allograft protocols. NMPA accelerated review pathways compress approval timelines for locally manufactured calcineurin inhibitors. Domestic fermentation capacity expansion in Jiangsu and Zhejiang provinces reduces import dependency.
Germany
EMA pharmacovigilance frameworks and MDR post-market surveillance obligations elevate compliance costs for generic sponsors seeking tacrolimus equivalence. Dermatology clinics in Munich and Hamburg expand topical pimecrolimus prescriptions for atopic dermatitis beyond pediatric populations. Hospital procurement committees consolidate immunosuppressant purchasing through specialty pharmacy carve-outs.
Japan
PMDA maintains stringent bioequivalence requirements that parallel FDA standards for narrow therapeutic index drugs. Government-funded organ allocation systems in Tokyo, Osaka, and Nagoya anchor nephrology center procurement volumes. Domestic transplant networks favor established innovator relationships over generic substitution.
India
CDSCO regulatory pathways and government tender systems create price pressure for oral tacrolimus formulations. Private transplant centers in Delhi, Mumbai, and Chennai drive demand alongside expanding public hospital nephrology units. Local API fermentation capacity supports cost-competitive generic manufacturing.
Calcineurin Inhibitor Drugs Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biosimilar equivalence and companion diagnostic bundling. The market structures around three concentration nodes: macrolide lactone manufacturing scale, cyclic peptide legacy franchises, and precision dosing service platforms. Two strategic archetypes dominate—vertically integrated API-to-formulation operators and diagnostic-therapeutic bundlers. Capacity expansion in Asian fermentation facilities and M&A targeting therapeutic drug monitoring platforms represent the prevailing competitive moves.
Among Swiss-based pharmaceutical conglomerates, Novartis AG and Roche exemplify divergent positioning archetypes—one anchoring legacy transplant immunosuppression through nephrology channel relationships, the other pairing diagnostic platforms with calcineurin inhibitor dosing protocols. Japanese specialty pharmaceutical operators, represented by Astellas Pharma Inc. and Otsuka Pharmaceuticals, occupy positions shaped by domestic regulatory stringency and Asia-Pacific manufacturing scale. Indian generic manufacturers, including Dr. Reddy's Laboratories Ltd. and Biocon, sit within the cost-optimized supply tier serving price-sensitive transplant markets.
| Leading Market Players |
|---|
| Otsuka Pharmaceuticals |
| Roche |
| Novartis AG |
| Biocon |
| Viatris Inc. |
| Astellas Pharma Inc. |
| AbbVie |
| Dr. Reddy's Laboratories Ltd. |
| Aurinia Pharmaceuticals Inc. |
| Others |
Value Chain & Pricing Dynamics
Fermentation-based API production scaling in Jiangsu and Zhejiang provinces is compressing manufacturing costs for macrolide lactones while simultaneously concentrating supply leverage among Asian fermentation specialists. This technological transition rewards operators with captive fermentation capacity and squeezes margin for formulation-only competitors dependent on spot API markets.
Pricing Analysis
Volume placements concentrate in oral tacrolimus generics where cost-per-dose competition intensifies, while intravenous cyclosporine and innovator-brand tacrolimus retain premium positioning through cold-chain logistics bundling and FDA bioequivalence barriers. Price differentiation separates innovator formulations protected by narrow therapeutic index regulations from commodity generics facing tender pressure in India and China. Pricing pressure stems from NMPA-accelerated domestic manufacturing approvals in China, which expand low-cost supply. Hospital systems exhibit lowest price sensitivity due to 340B program capture and therapeutic drug monitoring integration, while private clinics in emerging markets face acute cost pressure.
Supply Chain Analysis
Regional distribution centers in Shanghai, Mumbai, and Rotterdam anchor hub-and-spoke patterns for temperature-sensitive formulations, with last-mile delivery to transplant centers requiring validated cold-chain custody. API production clusters in China, India, and South Korea, with fermentation-derived tacrolimus precursors drawing from specialized Streptomyces cultivation facilities. Supply chain risk centers on single-source vulnerability for macrolide lactone fermentation capacity, where facility contamination or regulatory enforcement could disrupt global tacrolimus availability. Distribution runs through hospital specialty pharmacies in the United States, government tender channels in China, and retail pharmacy networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcineurin inhibitor market is becoming a vertical-integration race, with API-to-formulation control and diagnostic bundling as the decisive levers for margin preservation.
For Market Incumbents: Anchor formulation market share through backward integration into fermentation capacity in Zhejiang or Jiangsu provinces, securing tacrolimus API supply against generic sponsor encroachment. Deepen nephrology channel relationships by bundling therapeutic drug monitoring platforms with dosing protocols, creating switching costs that protect against biologic substitution pressure from monoclonal antibody induction therapies. For New Entrants and Emerging Players: Capture homecare monitoring white space by pairing microsampling devices with mail-order pharmacy fulfillment for stable graft recipients in rural markets. Target dermatology clinics in Spain and Italy with topical pimecrolimus formulations as steroid-sparing alternatives, leveraging pediatric atopic dermatitis expansion and direct-to-consumer pharmacy channels. For Investors and Strategic Acquirers: Exit pathways concentrate in diagnostic-therapeutic bundling platforms and Asian fermentation assets with FDA or EMA DMF filings. Long-term viability hinges on regulatory moats around narrow therapeutic index bioequivalence standards. Watch NMPA approval velocity for domestic Chinese manufacturers as the inflection signal for generic pricing compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| API Fermentation Capacity Expansion | Captive tacrolimus precursor production in Zhejiang reduces import dependency and secures supply for NMPA submissions. |
| Therapeutic Drug Monitoring Platform Acquisition | Immunoassay platform integration with dosing protocols creates switching costs in United States transplant centers. |
| EMA MDR Compliance Service Development | Post-market surveillance registry offerings address generic sponsor cost barriers in European tacrolimus markets. |
| Microsampling Device Partnership | Smartphone-connected capillary blood collection enables patient-administered monitoring outside nephrology clinics. |
| Topical Pimecrolimus Line Extension | Dermatology channel expansion in Germany and France captures steroid-sparing prescription growth beyond pediatric populations. |
Study Parameters
Multi-period observation of FDA bioequivalence filing patterns, NMPA approval timelines, and transplant center procurement volumes anchored the trend analysis, supplemented by interviews with nephrology formulary directors, hospital pharmacy procurement managers, therapeutic drug monitoring platform engineers, and regulatory affairs leads at generic sponsors. Secondary validation drew from FDA Orange Book listings, EMA EPAR documentation, ClinicalTrials.gov immunosuppression protocol registries, and China NMPA drug approval databases. Bottom-up transplant center demand modeling and top-down API fermentation capacity estimates were triangulated against government organ allocation statistics.
The input-output matrix framed volume projections across product chemistry, therapy area, delivery mode, and care location dimensions, with CAGRs derived from regression against historical transplant procedure growth and regulatory approval velocity. Modeling incorporated pharmacokinetic study completion rates, DMF filing-to-approval intervals, and reimbursement pathway expansion for homecare monitoring services throughout the forecast period.
The model holds under stable regulatory bioequivalence standards and continued government organ transplantation program funding; deviation in FDA generic substitution policy or NMPA domestic manufacturing incentives would shift competitive dynamics and volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Opioids Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Tuberculosis Therapeutics Market