
 Cachexia Treatment Market | 2026-2036
Cachexia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cachexia Treatment Market Outlook
North American pharmaceutical manufacturing is consolidating around specialized biologics capacity for cachexia therapeutics. Pfizer Inc. leverages its established oncology infrastructure to sustain commercial reach across hospital networks. Helsinn Group anchors its position through focused R&D in supportive cancer care, while Bristol-Myers Squibb Company competes via immunotherapy adjacency and broad institutional access.
Cachexia treatment encompasses pharmacological and nutritional interventions targeting pathological muscle wasting and metabolic dysfunction, typically involving progestational agents, corticosteroids, or selective androgen receptor modulators administered to restore lean body mass and functional capacity. Appetite stimulants dominate current prescription volumes due to established reimbursement and oral convenience, though anti-inflammatory drugs capture expanding investigator interest as mechanistic understanding of tumor-derived inflammatory signaling deepens. Injectable delivery modes command premium positioning in acute hospital settings where bioavailability and dosing precision prove critical, while homecare settings increasingly absorb oral and transdermal formats as palliative care infrastructure matures.
The FDA's orphan drug designation framework and the EMA's conditional marketing authorization pathway both shape development economics and patient access timelines for novel cachexia agents. ISO 14155 clinical investigation standards and ICH-GCP guidelines further constrain trial execution and data integrity requirements across jurisdictions. Stakeholders must monitor evolving biomarker qualification pathways and payer evidence thresholds as regulators and health technology assessment bodies tighten alignment between surrogate endpoints and demonstrated functional outcomes.
Market Dynamics
The cachexia treatment market pivots on the FDA's accelerated approval pathways for rare disease therapeutics, which compress development timelines and reshape how sponsors design registrational trials for wasting syndrome interventions.
Growth Catalysts
- Orphan drug incentives:The FDA's orphan designation framework delivers tax credits and market exclusivity, drawing capital toward cachexia drug development previously deemed commercially marginal.
- Oncology center expansion:US hospital networks are embedding multidisciplinary cachexia protocols within cancer care pathways, institutionalizing pharmacological intervention earlier in disease progression.
- Geriatric research mandates:Japan's METI-backed initiatives channel public funding into anabolic and anti-inflammatory candidates targeting aging-related muscle wasting.
Market Restraints
- Surrogate endpoint validation:EMA and FDA divergence on acceptable biomarkers for cachexia trials forces sponsors to run parallel development tracks, inflating study costs.
- Active pharmaceutical ingredient concentration:Synthetic progestational agent manufacturing clusters in India and China, exposing supply chains to geopolitical friction and quality enforcement variability.
- Functional outcome measurement:The absence of standardized lean body mass assessment protocols across sites generates data heterogeneity that regulators reject.
Strategic Opportunities
- Homecare channel maturation:Oral and transdermal delivery formats are penetrating palliative care infrastructure outside hospital settings, opening reimbursement negotiations with Medicare Advantage plans.
- Selective androgen receptor modulator convergence:SARM technology is crossing from muscle atrophy indications into oncology supportive care, leveraging existing toxicology packages.
- Conditional marketing authorization:The EMA's pathway allows earlier revenue recognition in Europe for drugs demonstrating meaningful weight stabilization, ahead of full survival data.
Industry Challenges
- Clinical trial execution:ISO 14155 and ICH-GCP compliance demands specialized site networks for cachexia studies, and qualified investigator scarcity limits enrollment velocity.
- Biomarker qualification timelines:FDA's evolving evidentiary standards for inflammatory cytokine surrogates force sponsors to retrofit ongoing trials with additional mechanistic endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cachexia Treatment Market |
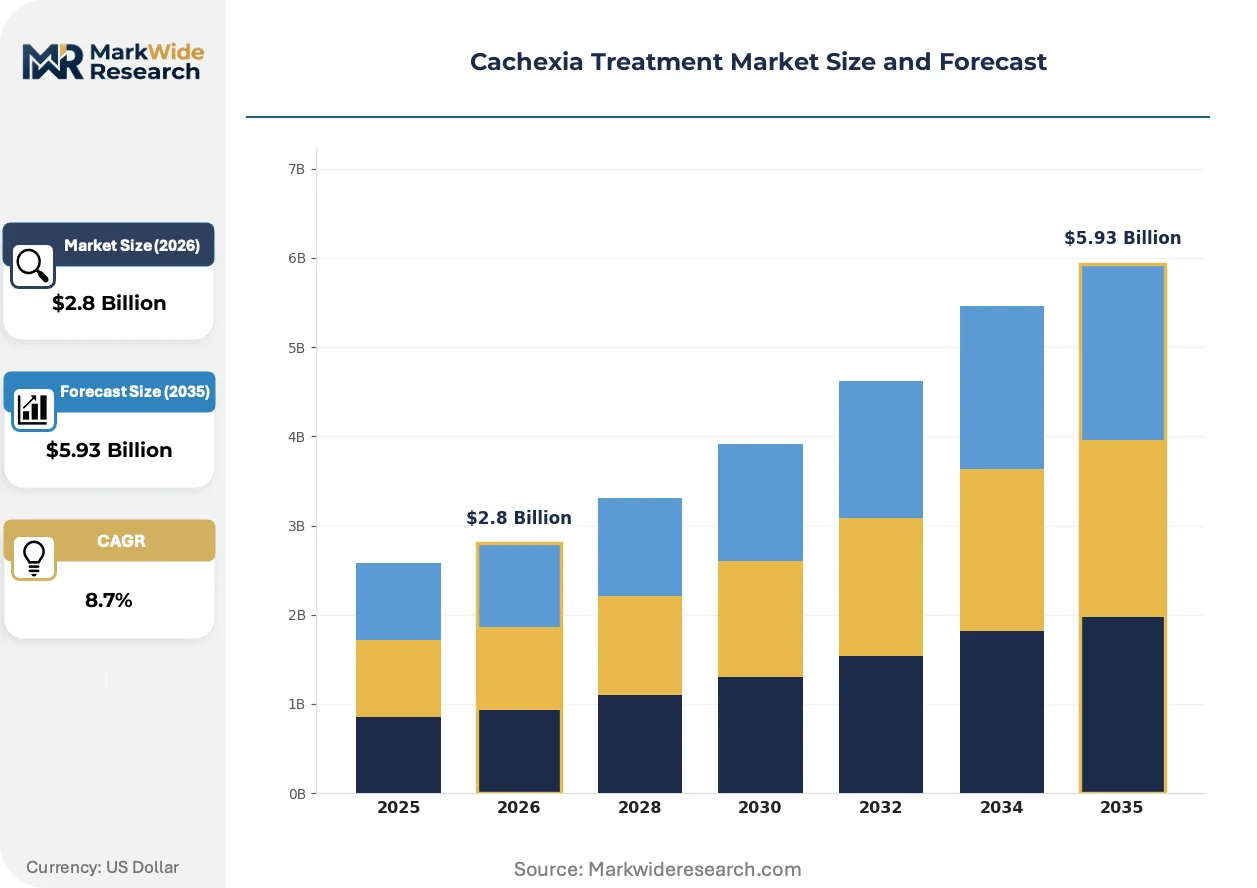
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Appetite Stimulants, Anabolic Agents, Nutritional Supplements, Anti-inflammatory Drugs Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Homecare Settings, Specialty Clinics, Research Institutions Application: Cancer, Chronic Obstructive Pulmonary Disease, HIV/AIDS, Heart Failure |
| Companies Covered | Pfizer Inc., Helsinn Group, Bristol-Myers Squibb Company, Merck & Co., Inc., Novartis AG, AbbVie Inc., Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., AVEO Oncology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cachexia Treatment Market Strategic Shifts
Cachexia therapeutics are absorbing precision medicine methodologies that segment patient populations by tumor-derived inflammatory profiles, redirecting R&D investment toward mechanism-targeted rather than symptom-masking interventions.
Anti-inflammatory drug platforms are absorbing capital previously allocated to appetite stimulants as mechanistic understanding of IL-6 and TNF-alpha signaling deepens. Oncology centers in Germany and the United States are adopting these candidates for patient subgroups with elevated C-reactive protein, compressing the addressable market for progestational agents while expanding the total treatable population through biomarker stratification.
EMA's conditional marketing authorization pathway is compressing commercialization timelines for novel cachexia agents by permitting approval based on intermediate endpoints like lean body mass change. Sponsors are responding by front-loading European regulatory submissions and negotiating early access schemes with national health technology assessment bodies in France and Italy, where hospital pharmacy budgets absorb innovative supportive care drugs.
Palliative care procurement is consolidating purchasing decisions within integrated health networks, displacing fragmented physician prescribing. Oncology centers in Japan and the United States are centralizing formulary control, forcing manufacturers to contract with pharmacy benefit managers rather than individual clinicians. This channel compression is most visible in Medicare Advantage penetration regions, where capitated payments incentivize network standardization over drug variety.
Cachexia Treatment Market Segmentation
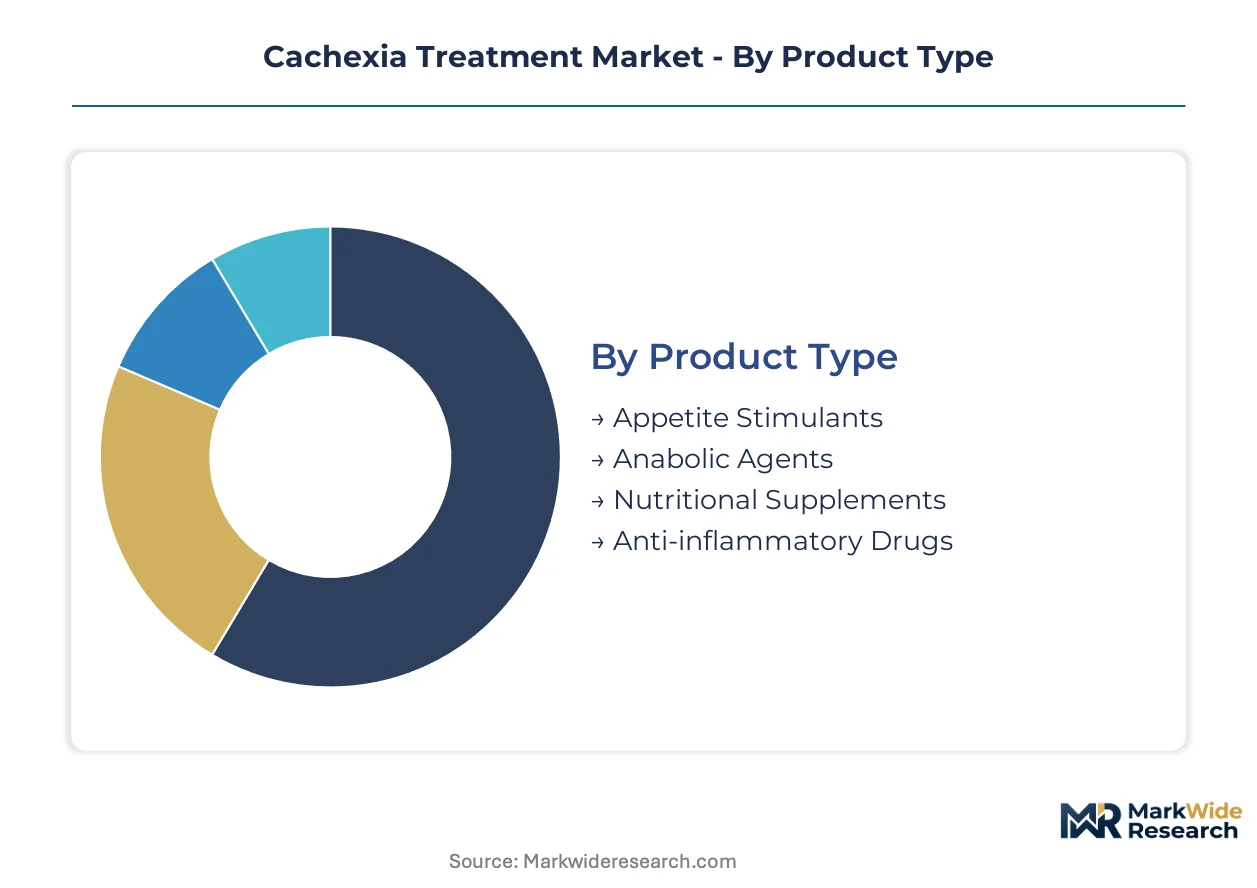
Segmentation in cachexia therapeutics reveals how supply chain configuration, reimbursement pathways, and clinical settings fragment commercial opportunity. Manufacturers must align formulation choices with institutional procurement patterns and patient mobility constraints.
Product Type:
Supply concentration for active pharmaceutical ingredients varies sharply across mechanism classes, with synthetic progestational agents clustering in South Asian manufacturing hubs while biologic anti-inflammatory platforms remain captive to North American and European CMO networks.
- Appetite Stimulants:Megestrol acetate and medroxyprogesterone formulations dominate prescription volumes through established oral dosing and Medicare Part D reimbursement. Hospital formularies in the United States and Japan retain these agents as first-line interventions for cancer-related wasting, though payer pressure on progestational class labeling constrains pricing power.
- Anabolic Agents:Selective androgen receptor modulators and growth hormone secretagogues target lean body mass preservation through distinct metabolic pathways. Germany's oncology centers and Japan's geriatric hospitals absorb the majority of investigational shipments as these agents advance through registrational trials.
- Nutritional Supplements:Medical food formulations concentrate in homecare channels where palliative care nurses manage compliance.
- Anti-inflammatory Drugs:IL-6 and TNF-alpha inhibitors command premium positioning in academic medical centers with biomarker stratification capabilities.
Appetite stimulants absorb the bulk of installed capacity; anti-inflammatory drugs are expanding most quickly.
Delivery Mode:
Cost tier differentiation separates acute hospital administration from ambulatory and home-based care, with reimbursement codes and nursing labor intensity determining channel economics.
- Oral:Tablet and liquid formulations dominate outpatient prescribing through pharmacy benefit manager coverage and patient self-administration convenience. Medicare Advantage plans in the United States increasingly require oral step therapy before authorizing injectable alternatives.
- Injectable:Subcutaneous and intramuscular depot formulations command hospital pharmacy budgets where bioavailability assurance outweighs administration cost. Japan's cancer centers and Germany's university hospitals maintain the densest site networks for injectable protocol enrollment.
- Transdermal:Patch delivery penetrates hospice settings where swallowing dysfunction limits oral options.
- Intravenous:Infusion-dependent biologics remain restricted to infusion center networks with specialist oversight.
Oral formats capture the highest prescription volumes; injectable platforms command the steepest expansion trajectory as biologic agents advance.
End User:
Customer type fragmentation reflects divergent procurement authority, with integrated health networks centralizing purchasing decisions while research institutions operate through grant-funded acquisition channels.
- Hospitals:Inpatient oncology and palliative care units drive concentrated demand for acute intervention protocols. IDN formulary committees in the United States and Japan's National Hospital Organization facilities exercise gatekeeping authority over high-cost supportive care agents.
- Homecare Settings:Hospice agencies and visiting nurse associations manage chronic wasting outside institutional walls. Germany's ambulatory palliative care infrastructure and Japan's community-based long-term care insurance programs channel reimbursement toward home-administered formats.
- Specialty Clinics:Outpatient cancer centers handle stable patients between hospitalization episodes.
- Research Institutions:Academic medical centers with NIH or AMED funding source investigational agents for mechanistic studies.
Hospitals retain the dominant share of pharmaceutical procurement; homecare settings are climbing the fastest as palliative care infrastructure matures.
Application:
Volume concentration tracks disease prevalence and regulatory precedent, with oncology indications offering the clearest pathway to approval and reimbursement while non-malignant wasting syndromes present evidentiary gaps.
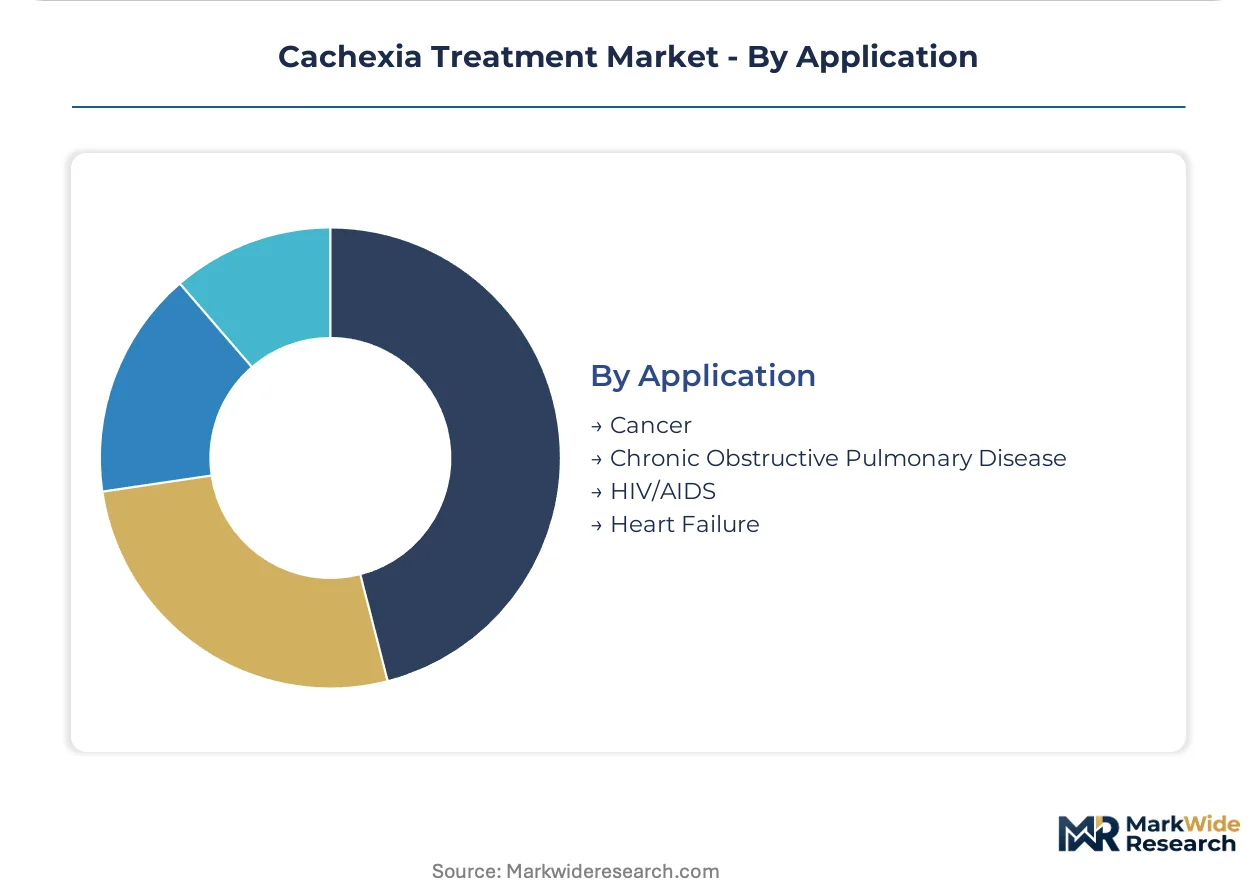
- Cancer:Tumor-related cachexia represents the primary addressable population with established diagnostic criteria and regulatory precedent for lean body mass endpoints. FDA's historical approvals for progestational agents in this indication create reference pricing for subsequent entrants.
- Chronic Obstructive Pulmonary Disease:Respiratory wasting syndromes attract growing investigator interest as inflammatory mechanisms overlap with oncology pathways. The United Kingdom's NHS and Japan's J-PORTAL registry generate real-world evidence for COPD-specific intervention protocols.
- HIV/AIDS:Wasting syndrome in immunocompromised patients retains orphan designation incentives in US markets.
- Heart Failure:Cardiac cachexia remains underdiagnosed with limited therapeutic development.
Cancer applications command the preponderance of clinical development investment; COPD is gaining share fastest as mechanistic overlap with tumor biology accelerates trial design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic progestational agent manufacturing anchors the supply geography in India and China, while clinical development and commercialization concentrate in North American and European pharmaceutical corridors. Demand fragmentation reflects divergent regulatory pathways and palliative care infrastructure maturity.
United States
Oncology centers across the United States are embedding multidisciplinary cachexia protocols within cancer care pathways, institutionalizing pharmacological intervention earlier in disease progression. The FDA's accelerated approval pathways for rare disease therapeutics compress development timelines and reshape registrational trial design. Hospital networks in Boston and the Research Triangle exercise gatekeeping authority over high-cost supportive care agents through integrated delivery network formulary committees.
Germany
University hospitals in Germany maintain dense site networks for injectable protocol enrollment and biomarker-stratified intervention studies. The country's national pharmaceutical regulator aligns with EMA conditional marketing authorization standards, permitting earlier revenue recognition for drugs demonstrating meaningful weight stabilization. Academic medical centers in Munich and Heidelberg channel reimbursement toward home-administered formats through ambulatory palliative care infrastructure expansion.
Japan
METI-backed geriatric research initiatives channel public funding into anabolic and anti-inflammatory candidates targeting aging-related muscle wasting. Japan's National Hospital Organization facilities exercise centralized procurement authority over innovative supportive care drugs. Cancer centers in Tokyo and Osaka absorb the majority of investigational shipments as selective androgen receptor modulators advance through registrational trials.
United Kingdom
The NHS generates real-world evidence for COPD-specific intervention protocols as inflammatory mechanisms overlap with oncology pathways. National health technology assessment bodies tighten alignment between surrogate endpoints and demonstrated functional outcomes. Hospital pharmacy budgets in London and Manchester increasingly absorb innovative supportive care drugs through early access scheme negotiations.
India
Active pharmaceutical ingredient concentration for synthetic progestational agents exposes supply chains to quality enforcement variability and geopolitical friction. The country's national pharmaceutical regulator enforces ISO 14155 clinical investigation standards alongside ICH-GCP guidelines. Manufacturing clusters in Hyderabad and Ahmedabad supply oral megestrol acetate formulations to hospital formularies across Southeast Asia and Africa.
Cachexia Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue mechanism-targeted biologic platforms. The market structure reflects moderate consolidation around oncology-focused pharmaceutical conglomerates with supportive care adjacencies, while specialized biotechnology firms compete on biomarker stratification capabilities. Three archetypes dominate: diversified oncology majors leveraging institutional access, supportive care specialists with focused R&D pipelines, and immunotherapy players exploiting mechanistic overlap. Competitive dynamics center on strategic partnerships for biomarker qualification and geographic expansion through conditional marketing authorization pathways.
Among diversified oncology majors, Pfizer Inc. and Bristol-Myers Squibb Company exemplify the institutional-access archetype, while Helsinn Group occupies a position within the supportive care specialist tier. Pfizer Inc. leverages established hospital network relationships, Bristol-Myers Squibb Company competes via immunotherapy adjacency and broad formulary presence, and Helsinn Group anchors its positioning through focused development in cancer-related wasting syndrome. These three entities represent contrasting strategic postures within a market where commercial reach and mechanistic differentiation determine competitive viability.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Helsinn Group |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Novartis AG |
| AbbVie Inc. |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| AVEO Oncology |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery network formulary consolidation in the United States is forcing manufacturers to bundle clinical education and patient monitoring services with drug shipments, compressing unbundled product margins while elevating total contract values. This procurement shift rewards sponsors with captive manufacturing capacity and penalizes those dependent on contract manufacturing organization networks for fill-finish operations.
Pricing Analysis
Warranty and service bundling separates hospital procurement contracts from homecare channel arrangements, with the former incorporating adherence monitoring and the latter stripping to bare product economics. Three-tier pricing structure across premium, standard, and economy levels reflects biomarker stratification capabilities, FDA approval pathway, and geographic exclusivity terms. Cost compression in the appetite stimulant tier is intensifying because of megestrol acetate commoditization and Indian API oversupply. Medicare Advantage plans exhibit the sharpest price sensitivity, while Japan's National Hospital Organization facilities prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with synthetic progestational agent active pharmaceutical ingredient production, where Hyderabad and Ahmedabad manufacturing clusters feed global oral formulation demand. Biologic anti-inflammatory platforms draw from North American and European contract manufacturing organization networks, with monoclonal antibody cell culture and purification stages resting on single-site stainless steel bioreactor capacity. Tariff exposure on Chinese-sourced excipients and packaging materials generates margin volatility for oral solid dose manufacturers. Distribution runs through integrated health network central pharmacies in the United States, specialty distributors in Germany, and hospital pharmacy cooperatives in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biologics manufacturing capacity for cachexia therapeutics remains physically constrained, with multi-product facility slots booked years forward and single-use bioreactor supply intermittently disrupted. This bottleneck props pricing for sponsors with confirmed manufacturing access.
For Market Incumbents: Anticipate formulary exclusion risk from selective androgen receptor modulator entrants by securing long-term hospital system contracts with embedded lean body mass outcome guarantees. Backward integration into API production for progestational agents reduces exposure to Indian supply chain friction. Prioritize biomarker qualification partnerships with FDA to defend mechanism-based pricing against symptom-masking alternatives. For New Entrants and Emerging Players: Homecare hospice agencies represent an underserved buyer archetype with fragmented purchasing and limited formulary control, offering entry without integrated delivery network gatekeeper negotiations. Japan's community-based long-term care insurance programs and Germany's ambulatory palliative care infrastructure present the most penetrable reimbursement environments. A go-to-market angle emphasizing oral convenience and transdermal alternatives to injectable standards bypasses hospital pharmacy committee barriers. For Investors and Strategic Acquirers: The window for entry favors biotechnology firms with validated IL-6 or TNF-alpha pathway assets and existing toxicology packages transferable to oncology supportive care. Long-term viability hinges on conditional marketing authorization pathway execution in Europe and biomarker-stratified label expansion. The signal to watch as inflection indicator is FDA qualification of inflammatory cytokine surrogates as registrational endpoints, which would re-rate mechanism-targeted platforms against progestational incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Partnership | FDA endorsement of C-reactive protein stratification accelerates mechanistic drug development timelines. |
| Conditional Marketing Authorization Submission | EMA's intermediate endpoint pathway permits European revenue recognition ahead of survival data completion. |
| Integrated Delivery Network Contracting | Long-term hospital system agreements lock out selective androgen receptor modulator competitors. |
| API Manufacturing Backward Integration | Captive synthetic progestational agent production insulates margins from Indian supply chain volatility. |
| Homecare Channel Distribution Buildout | Medicare Advantage oral step therapy requirements favor palliative care infrastructure penetration. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. FDA orphan drug designation databases, EMA conditional marketing authorization decisions, ClinicalTrials.gov protocol registries, and hospital procurement databases provided segmentation benchmarks. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were reconciled through iterative triangulation.
Data-stream reconciliation across patient population estimates, treatment protocol adoption curves, and reimbursement code valuation generated consistent volume and value outputs across the projection horizon. Segmentation dimensions modeled include mechanism class, delivery mode, end-user setting, and regional regulatory cluster. CAGRs were derived from log-linear trend fitting to historical prescription data and forward adjustment for pipeline asset probability-weighted launches. Forecast inputs incorporated biomarker qualification pathway timelines and palliative care infrastructure maturity indices.
Revisions become necessary when FDA evidentiary standards for inflammatory cytokine surrogates shift, EMA conditional marketing authorization requirements tighten, or geopolitical friction disrupts Indian and Chinese API supply channels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Cerebral Vasospasm Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Buruli Ulcer Treatment Market
Specialty Medicine
Global Pemphigus Vulgaris Market