
 Global Addison's Disease Treatment Market | 2026-2036
Global Addison's Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Addison's Disease Treatment Market Foresight
Continuous manufacturing and real-time release testing for oral corticosteroids is reshaping how hydrocortisone tablets are produced and quality-assured across commercial supply chains. Pfizer Inc. leverages its biologics infrastructure to sustain high-purity active pharmaceutical ingredient sourcing for adrenal hormone therapies. Takeda Pharmaceutical Company Limited anchors its position through specialized endocrinology distribution networks across Asia-Pacific markets. Novartis AG differentiates via integrated diagnostics-to-treatment platforms that streamline patient identification and therapeutic monitoring.
Addison's disease treatment encompasses pharmaceutical interventions that replace deficient cortisol and aldosterone in patients with adrenal insufficiency, typically requiring precise milligram-level dosing of synthetic glucocorticoids and mineralocorticoids matched to circadian rhythm patterns. Hydrocortisone remains the cornerstone product type due to its physiological cortisol mimicry, while extended-release capsules represent the fastest-growing delivery mode as patients and clinicians seek reduced dosing frequency and flatter plasma concentration profiles. Among therapy areas, primary adrenal insufficiency commands the largest patient pool, though acute adrenal crisis management commands premium pricing due to the life-threatening nature of presentation and need for immediate parenteral intervention.
FDA orphan drug incentives and EU MDR quality system requirements collectively elevate barriers for new corticosteroid entrants while reinforcing standards for batch consistency and bioequivalence. The WHO's Essential Medicines List inclusion of hydrocortisone shapes procurement priorities in low-resource health systems and influences national formulary decisions. Stakeholders must monitor how real-world evidence requirements from EMA and FDA evolve for long-established hormone therapies, as post-market surveillance obligations will determine competitive positioning for both originators and generic manufacturers.
Market Dynamics
The Addison's disease treatment landscape is fundamentally reshaping around personalized hormone replacement protocols, with specialty clinics and endocrinology centers driving demand for circadian-matched corticosteroid dosing that moves beyond standard twice-daily regimens.
Growth Catalysts
- Orphan Drug Incentives:The FDA's evolving framework for rare disease therapeutics accelerates regulatory pathways for novel corticosteroid formulations, reducing time-to-market for sponsors targeting adrenal insufficiency.
- Continuous Manufacturing:Real-time release testing technologies enable batch-to-batch consistency in hydrocortisone tablet production, cutting quality assurance timelines and reducing supply interruptions.
- Diagnostic Infrastructure Expansion:Germany's network of specialized endocrinology centers and Japan's autoimmune screening programs expand patient identification rates, converting undiagnosed populations into addressable demand.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:High-purity corticosteroid API sourcing concentrates among limited European and North American suppliers, creating vulnerability to geopolitical trade friction or single-site manufacturing disruptions.
- EU MDR Compliance Burden:The Medical Device Regulation's tightened quality system requirements for drug-device combination products elevate documentation and clinical evidence costs for extended-release delivery mechanisms.
- Generic Substitution Pressure:Immediate-release hydrocortisone tablets face commoditization as multiple abbreviated new drug applications achieve bioequivalence, compressing margin structures for originator formulations.
Strategic Opportunities
- Pediatric Formulation Gaps:The United States exhibits underpenetration in weight-based dosing solutions for children with congenital adrenal hyperplasia, presenting white space for age-appropriate delivery technologies.
- Integrated Diagnostics-to-Treatment Platforms:Convergence of automated ACTH stimulation testing with electronic health record integration streamlines referral pathways from primary care to endocrinology specialists.
- Home-Based Crisis Management:Injectable hydrocortisone emergency kits for self-administration during adrenal crisis episodes address unmet needs in rural and remote patient populations across Australia and Canada.
Industry Challenges
- Endocrinology Specialist Scarcity:The limited pipeline of fellowship-trained adrenal disorder specialists creates patient access bottlenecks, particularly in secondary and tertiary care markets outside major metropolitan clusters.
- Real-World Evidence Generation:Long-established hormone therapies lack contemporary post-market surveillance data meeting EMA and FDA evolving standards, forcing costly retrospective cohort studies to maintain competitive positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Addison's Disease Treatment Market |
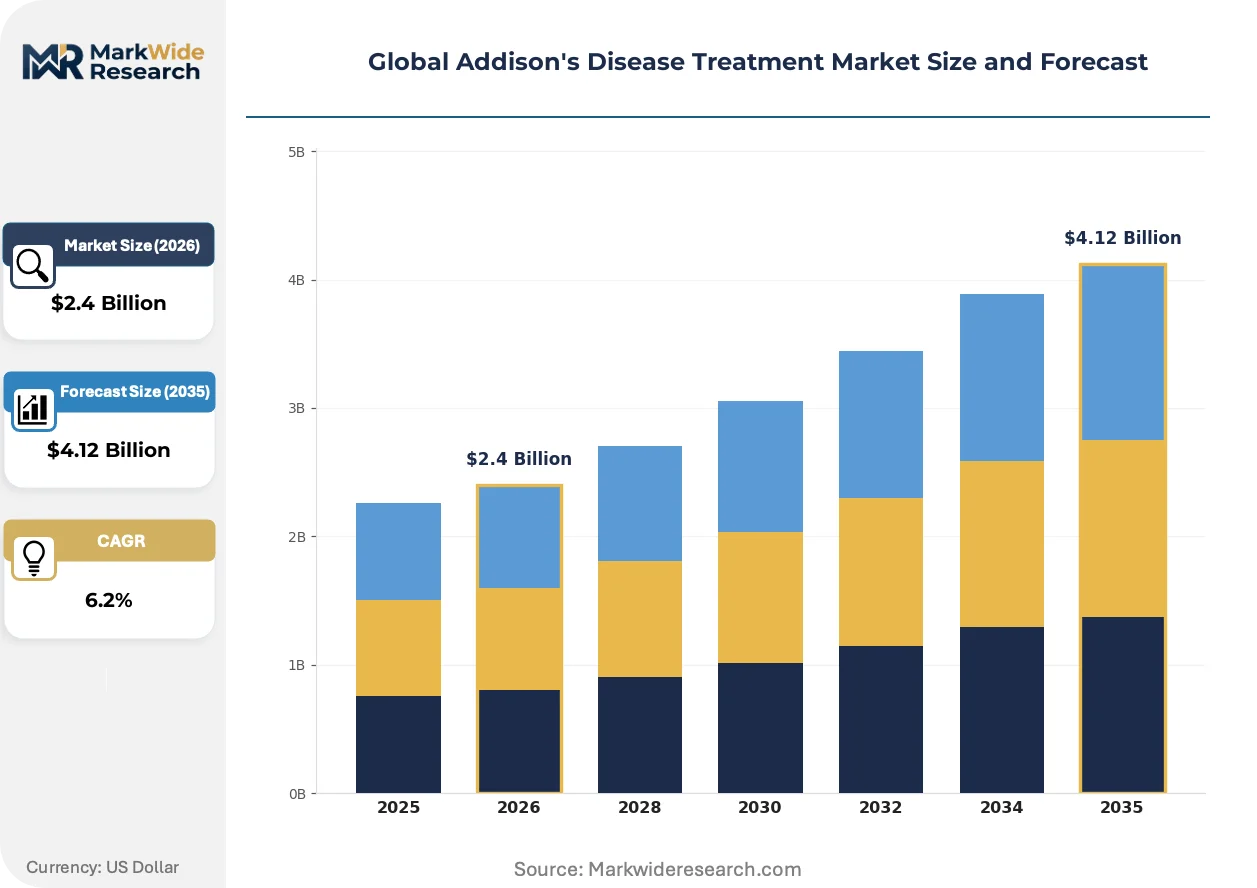
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocortisone, Fludrocortisone, Cortisone Acetate, Prednisone Therapy Area: Primary Adrenal Insufficiency, Secondary Adrenal Deficiency, Acute Adrenal Crisis, Chronic Adrenal Insufficiency End User: Specialty Clinics, Endocrinology Centers, Hospitals, Home Healthcare Services Delivery Mode: Oral Tablets, Injectable Solutions, Extended-Release Capsules, Topical Preparations |
| Companies Covered | Pfizer Inc., Takeda Pharmaceutical Company Limited, Merck & Co., Inc., Bristol-Myers Squibb Company, Novartis AG, GlaxoSmithKline plc, Sanofi S.A., Teva Pharmaceutical Industries Ltd., AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Addison's Disease Treatment Market Shifts & Advancements
Pharmaceutical manufacturing and patient management paradigms are converging toward precision dosing and supply chain resilience, with technology vendors and regulatory bodies simultaneously pushing and pulling market evolution.
Extended-release hydrocortisone capsules with dual-layer coating technology enable flatter plasma concentration curves that mimic physiological cortisol secretion patterns more closely than conventional immediate-release tablets. Specialty pharmacies and academic medical centers are adopting these formulations at accelerating rates for patients with persistent fatigue or metabolic complications on standard therapy. This pharmacokinetic advancement is rendering obsolete the clinical assumption that twice-daily dosing adequately replaces natural circadian rhythm.
The EU MDR's heightened scrutiny of drug-device combination products is forcing manufacturers to generate additional clinical performance data for existing auto-injector and pump delivery systems. This regulatory tightening elevates barriers for new market entrants while reinforcing incumbent positions for firms with established quality management systems. Extended-release capsule categories face the steepest compliance cost increases, with notified body review timelines extending substantially for products crossing the medicinal product-medical device boundary.
Patients and caregivers are increasingly demanding unbundled crisis management training and standalone emergency supply procurement separate from routine prescription fulfillment. Hospital outpatient pharmacies and mail-order distributors are responding with dedicated adrenal insufficiency care programs that combine medication delivery with education and remote monitoring. This behavioral shift is most pronounced in the United States and United Kingdom, where direct-to-patient subscription models for emergency hydrocortisone kits are gaining traction among advocacy organization members.
Global Addison's Disease Treatment Market Segmentation
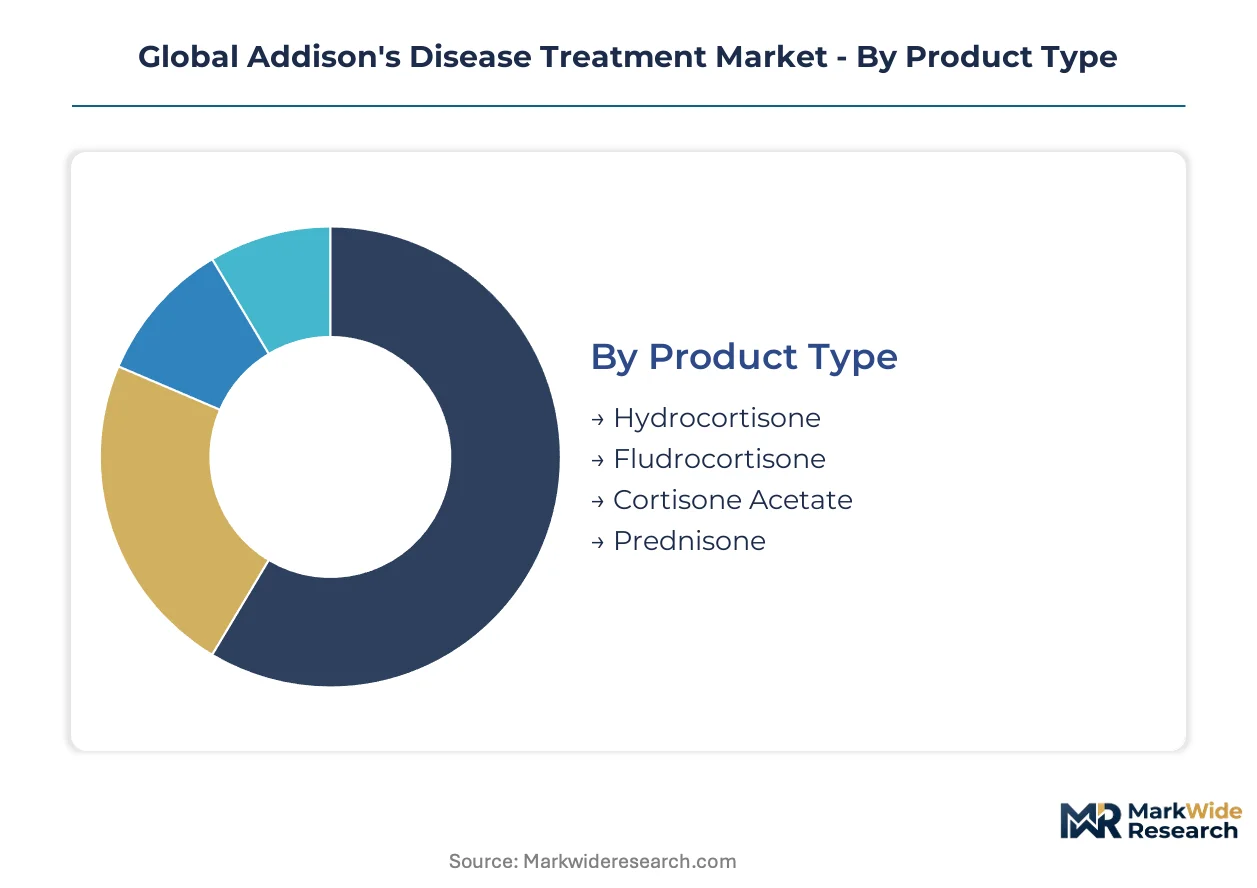
Segmentation in Addison's disease treatment reveals how therapeutic modalities, care settings, and delivery technologies partition value across patient populations with varying severity and access profiles. Understanding these divisions exposes where formulation innovation concentrates versus where commoditization pressures dominate procurement decisions.
Product Type:
The maturity spectrum spans from century-old synthetic corticosteroids to refined mineralocorticoid analogues with narrower therapeutic indices.
- Hydrocortisone:This glucocorticoid mimics endogenous cortisol with 1:1 mineralocorticoid activity, making it the physiological replacement of choice. Demand concentrates in Germany and the United States where endocrinology centers prioritize circadian-matched dosing protocols over cost-minimization.
- Fludrocortisone:A synthetic mineralocorticoid with potent sodium-retaining properties and negligible glucocorticoid effects. Japan's specialized adrenal insufficiency clinics drive premium positioning for this agent in primary aldosterone deficiency management.
- Cortisone Acetate:A prodrug requiring hepatic conversion to hydrocortisone, offering slower onset and extended duration suited to specific metabolic phenotypes.
- Prednisone:A longer-acting synthetic glucocorticoid with minimal mineralocorticoid activity, deployed where once-daily dosing compliance outweighs physiological precision requirements.
Hydrocortisone handles the majority of throughput; extended-release fludrocortisone combinations are gaining share fastest among patients with refractory electrolyte disturbances.
Therapy Area:
Application severity determines whether treatment emphasizes chronic stability or acute life-preservation, with reimbursement pathways diverging accordingly.
- Primary Adrenal Insufficiency:Autoimmune destruction of the adrenal cortex requiring both glucocorticoid and mineralocorticoid replacement lifelong. Specialty clinics in the United Kingdom and Australia prioritize patient education for self-management of this permanent condition.
- Acute Adrenal Crisis:A medical emergency characterized by vascular collapse, hypoglycemia, and hyperkalemia demanding immediate parenteral hydrocortisone. Hospital emergency departments in the United States command premium pricing for crisis intervention protocols and intensive monitoring.
- Secondary Adrenal Deficiency:Hypothalamic-pituitary axis suppression from exogenous steroids or structural lesions, often requiring glucocorticoid replacement without mineralocorticoid supplementation.
- Chronic Adrenal Insufficiency:Stable outpatient management with dose adjustments for intercurrent illness, stress, or surgical procedures.
Primary adrenal insufficiency handles the majority of throughput; acute adrenal crisis management is expanding most quickly on a value basis due to emergency care premiums.
End User:
Customer type stratification reflects the concentration of specialized expertise versus the economies of scale achievable in generalist settings.
- Specialty Clinics:Dedicated endocrinology practices offering personalized hormone replacement with ACTH stimulation testing and circadian rhythm optimization. These facilities in Germany and Switzerland lead adoption of extended-release formulations.
- Endocrinology Centers:Academic medical centers with multidisciplinary adrenal teams managing complex cases including congenital adrenal hyperplasia and concomitant autoimmune polyendocrine syndromes.
- Hospitals:Inpatient and emergency settings handling acute presentations, perioperative management, and crisis stabilization across general medical and surgical services.
- Home Healthcare Services:Providers of nursing support for injection training, emergency kit supply, and remote monitoring in rural and dispersed populations across Canada and Australia.
Specialty clinics handle the majority of throughput; home healthcare services are climbing the fastest as self-administration protocols reduce institutional dependency.
Delivery Mode:
Supply concentration varies from commoditized immediate-release tablets to specialized formulations requiring advanced manufacturing capabilities.
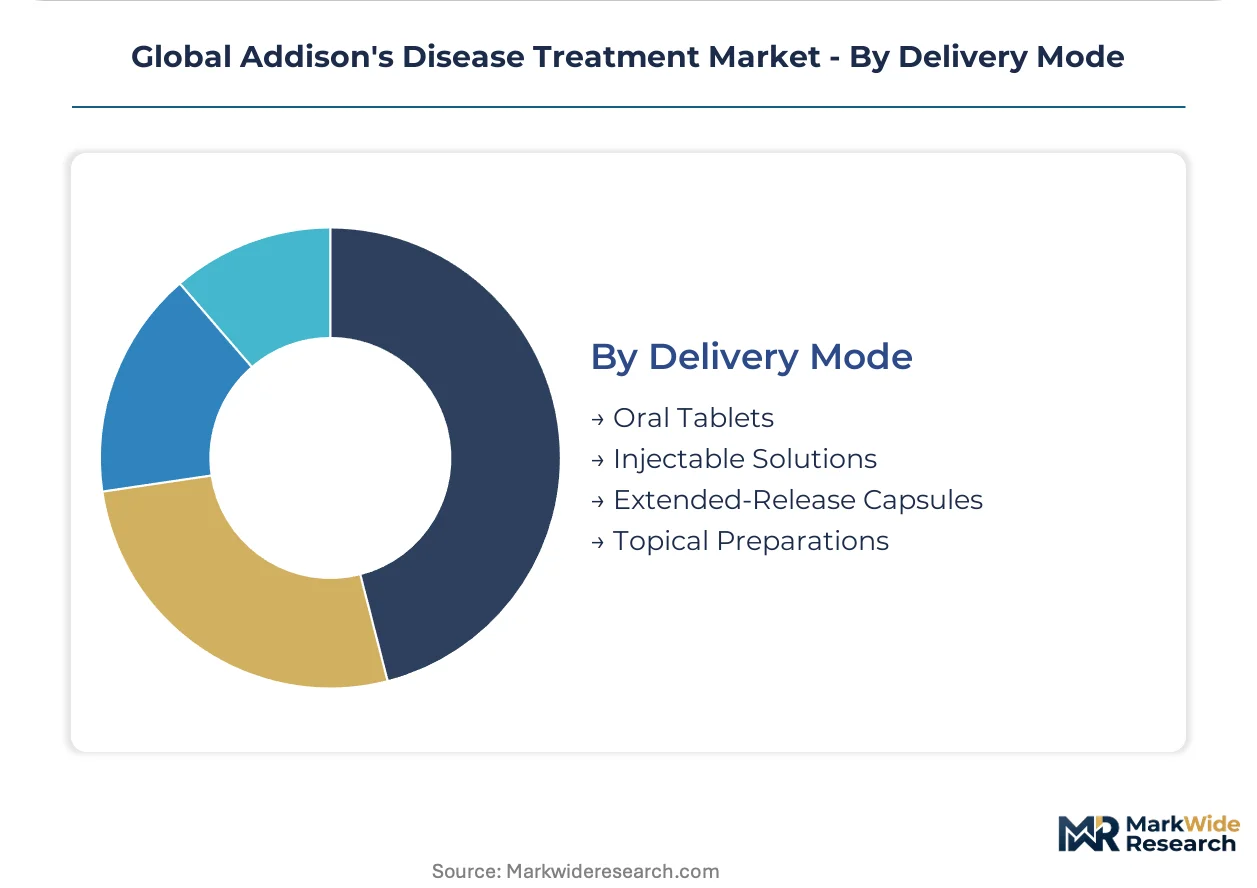
- Extended-Release Capsules:Dual-layer coating technologies enable flatter plasma concentration curves that approximate physiological cortisol secretion. Patients in the United States and United Kingdom increasingly demand these formulations to reduce fatigue and metabolic complications.
- Injectable Solutions:Parenteral hydrocortisone for crisis management, perioperative coverage, and patients with impaired gastrointestinal absorption. Home emergency kits are penetrating rural Australia and remote Canadian territories where hospital access is delayed.
- Oral Tablets:Immediate-release hydrocortisone and fludrocortisone tablets representing the standard of care for stable chronic management.
- Topical Preparations:Transdermal absorption systems under investigation for patients with swallowing difficulties or enteral feeding requirements.
Oral tablets handle the majority of throughput; extended-release capsules show the steepest expansion trajectory as circadian-matched dosing becomes standard of care in leading endocrinology centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized corticosteroid formulations to Japan and Australia, while the United States supplies extended-release technologies to Canadian and Mexican endocrinology networks.
United States
FDA orphan drug incentives and academic medical center concentration drive adoption of circadian-matched dosing protocols. The agency's real-world evidence guidance shapes post-market surveillance obligations for hormone therapies. Boston's endocrinology corridor anchors clinical trial activity for next-generation extended-release capsules.
Germany
Specialized endocrinology centers and statutory health insurance reimbursement pathways expand patient identification for autoimmune adrenal insufficiency. EU MDR quality system requirements tighten documentation standards for drug-device combination products. Munich and Heidelberg clusters lead European adoption of personalized hormone replacement protocols.
Japan
PMDA streamlined review pathways for rare disease therapeutics accelerate market access for novel corticosteroid formulations. METI industrial policy supports domestic active pharmaceutical ingredient production for hormone therapies. Tokyo and Osaka academic medical centers pioneer integrated diagnostics-to-treatment platforms for adrenal disorders.
Australia
TGA inclusion of hydrocortisone on the Australian Register of Therapeutic Goods shapes procurement priorities in public hospital systems. Remote patient monitoring programs address access gaps for rural populations requiring emergency injection training. Melbourne and Sydney endocrinology hubs develop home-based crisis management protocols.
Switzerland
Swissmedic's stringent batch release requirements reinforce quality benchmarks for high-purity corticosteroid imports. Private insurance reimbursement for personalized medicine approaches supports premium positioning of extended-release formulations. Basel and Zurich pharmaceutical clusters concentrate European headquarters functions for multinational hormone therapy sponsors.
Global Addison's Disease Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Large-cap pharmaceutical conglomerates with established endocrinology franchises dominate formulation supply through integrated distribution networks. Mid-scale generic manufacturers capture commoditized immediate-release tablet volumes through price-competitive tenders. Emerging delivery-technology specialists occupy niche positions in extended-release and emergency injection formats. Capacity expansion into continuous manufacturing capabilities and strategic partnerships for diagnostic platform integration represent the dominant competitive moves.
Within the large-cap integrated tier, Pfizer Inc. and Novartis AG exemplify archetypes combining biologics infrastructure with specialized distribution reach. Takeda Pharmaceutical Company Limited occupies a distinct position anchoring Asia-Pacific market development through regional endocrinology network relationships. These three entities represent the spectrum from North American and European headquarters-based global operations to Asia-centric specialized market development.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Novartis AG |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Others |
Supply & Pricing Matrix
The Rotterdam-Frankfurt pharmaceutical freight corridor anchors cost dynamics for high-purity corticosteroid API movement, with its congestion surcharges amplifying price differentiation between originator formulations and commoditized immediate-release tablets while specialty clinics absorb premium logistics costs for circadian-matched delivery systems.
Pricing Analysis
Cost-plus contracts with API price indexation dominate procurement between European formulators and North American buyers. Three-tier pricing structure across extended-release capsules, immediate-release tablets, and generic substitutes separates patient segments by reimbursement tier and clinical complexity. Pricing pressure stems from abbreviated new drug application approvals for bioequivalent hydrocortisone, compressing originator margins. Hospital procurement committees exhibit highest price sensitivity, while academic medical centers prioritize pharmacokinetic performance over per-unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized European facilities in Germany, Switzerland, and the Netherlands holding validated capacity for continuous corticosteroid tablet production. High-purity hydrocortisone API draws from Italian and Spanish chemical synthesis sites, with fludrocortisone precursors sourced through limited North American suppliers. Single-source vulnerability for dual-layer coating excipients creates exposure to notified body approval delays. Distribution runs through specialty pharmacy networks and hospital outpatient pharmacies rather than retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
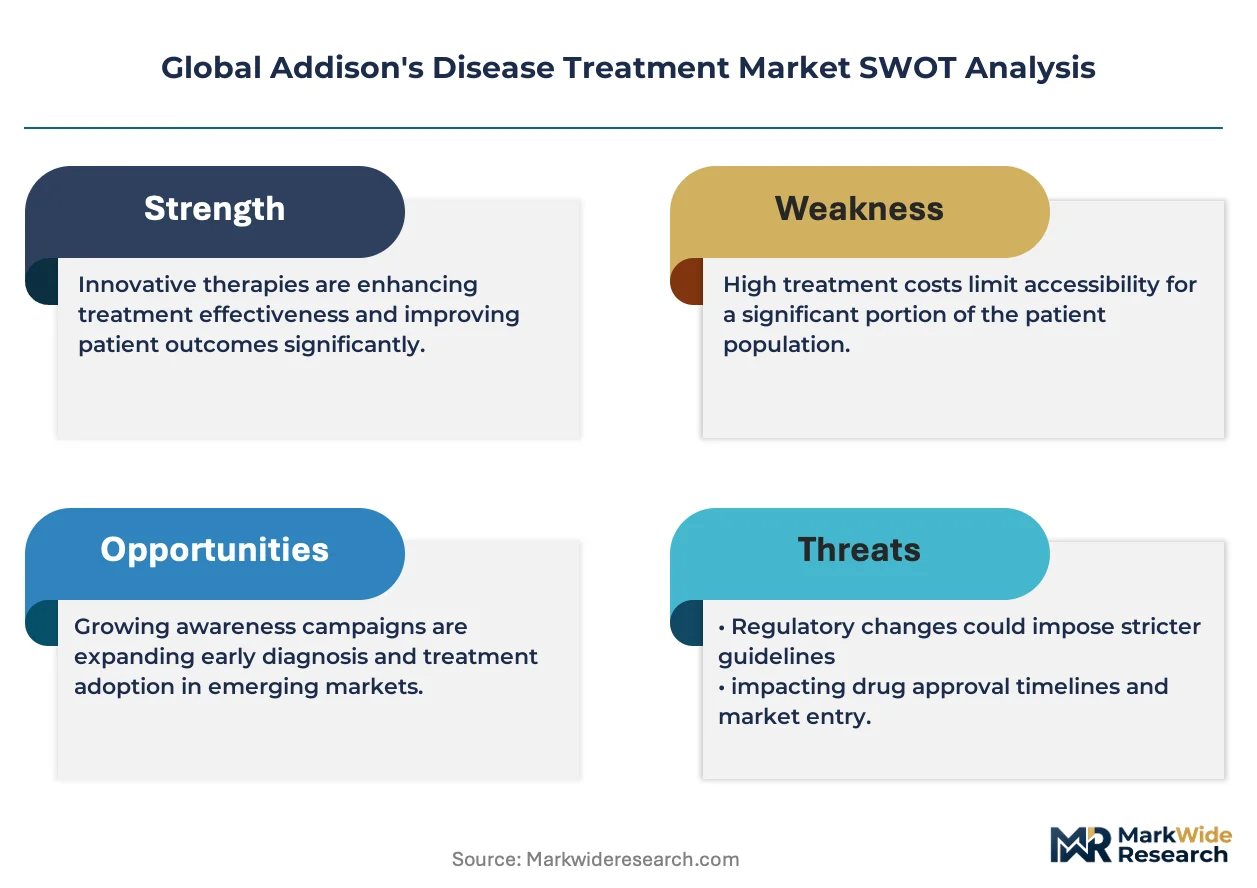
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions. FDA orphan drug designation and EU MDR quality system requirements create switching costs that deter new formulation entrants.
For Market Incumbents: Harden API supply security through backward integration into European corticosteroid synthesis capacity or captive supply agreements with Italian chemical manufacturers. Deepen channel control by embedding continuous manufacturing capabilities within existing quality management systems to outpace generic substitution pressure from abbreviated new drug application filers.
For New Entrants and Emerging Players: Pursue pediatric weight-based dosing formulations in the United States, where regulatory incentives for rare disease therapeutics intersect with underpenetrated congenital adrenal hyperplasia management. Target home healthcare services in Australia and Canada through direct-to-patient subscription models for emergency hydrocortisone injection kits, leveraging remote monitoring partnerships with regional endocrinology hubs.
For Investors and Strategic Acquirers: Delivery-technology specialists with validated extended-release coating capabilities represent the optimal acquisition archetype for portfolio diversification into circadian-matched hormone replacement. Long-term viability hinges on regulatory compliance infrastructure rather than molecule novelty, favoring targets with established notified body relationships and EU MDR technical documentation. Watch for PMDA accelerated review pathway designations as inflection signals for Asia-Pacific market access momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | FDA quality guidance alignment reduces batch release timelines for hydrocortisone tablets. |
| Extended-Release Formulation Development | Dual-layer coating patents differentiate circadian-matched products from immediate-release commoditization. |
| Diagnostic Platform Integration | ACTH stimulation testing convergence with EHR systems streamlines patient identification in Germany. |
| Pediatric Indication Expansion | Weight-based dosing solutions address unmet need in congenital adrenal hyperplasia management. |
| Emergency Kit Direct Distribution | Mail-order subscription models penetrate rural Australia and remote Canadian territories. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases anchors the qualitative findings. Bottom-up patient population modeling and top-down pharmaceutical market sizing triangulate volume estimates across the analysis window.
Calibration against historical hydrocortisone prescription volumes and extended-release capsule adoption curves in academic medical centers refines the analytical framework. Segmentation dimensions include therapy area severity, delivery mode technology tier, end-user setting, and regional regulatory cluster. CAGRs derive from patient identification rate projections, reimbursement pathway evolution, and formulation switching elasticity across the projection horizon. Forecast inputs incorporate EU MDR transition timelines and PMDA rare disease review pathway utilization.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates, statutory insurance reimbursement adjustments, or API trade friction would shift the trajectory. Quarterly review of FDA orphan drug designation grants, EMA real-world evidence guidance updates, and notified body capacity indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Immunology Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market