
 Diverticulitis Disease Market | 2026-2036
Diverticulitis Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Diverticulitis Disease Market Analysis
The divergence between premium biologic therapies and commodity generic antibiotics is hardening as hospital formularies tighten reimbursement tiers. Pfizer Inc. leverages its manufacturing scale to dominate oral antibiotic supply chains across North American health systems. Johnson & Johnson sustains premium positioning in surgical intervention devices through specialized mesh and stapling platforms. AbbVie Inc. differentiates via immunology R&D pipelines exploring novel anti-inflammatory mechanisms for complicated diverticulitis cases.
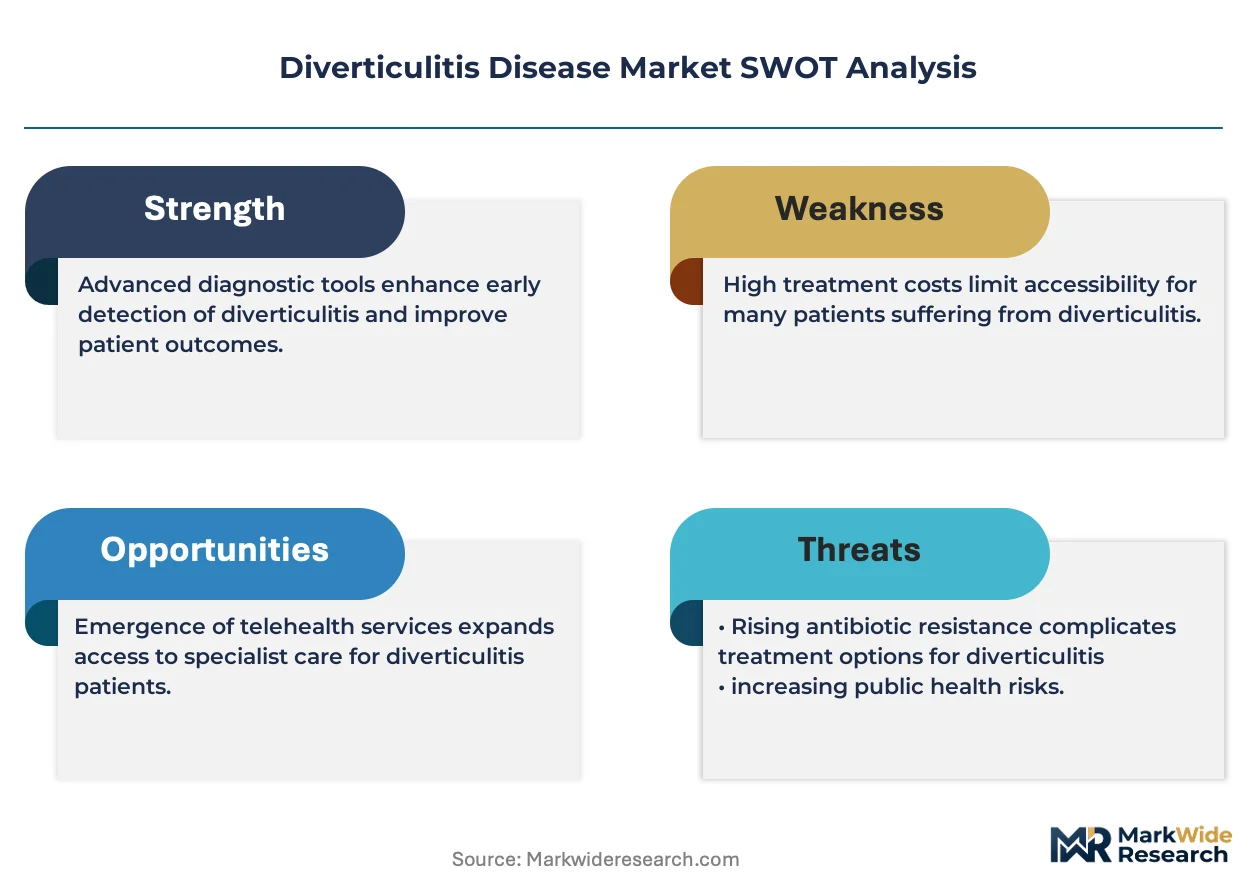
Diverticulitis denotes inflammation or infection of diverticula, pouch-like protrusions in the colonic wall typically arising from chronic low-fiber dietary patterns and elevated intraluminal pressure, with severity graded by Hinchey classification stages that guide intervention from bowel rest to emergent colectomy. The treatment type dimension shows antibiotics occupying the largest volume share while probiotic adjuvants represent the fastest-expanding margin pool as gastroenterology shifts toward microbiome-modulating protocols. Hospital end users anchor absolute spending, though homecare administration routes are gaining traction as oral antibiotic regimens and telehealth monitoring reduce inpatient length-of-stay requirements.
FDA antimicrobial stewardship mandates and EMA pharmacovigilance frameworks are reshaping prescription durations and first-line agent selection across outpatient and acute care settings. The EU MDR and updated ISO 13485 standards impose stricter clinical evidence requirements on surgical mesh and bowel resection devices, elevating compliance costs for device manufacturers. Stakeholders must monitor evolving microbiome-targeted therapy trial readouts and antimicrobial resistance surveillance data to calibrate portfolio allocation between conventional antibiotics and emerging biologic modalities.
Market Dynamics
FDA antimicrobial stewardship mandates are compressing prescription durations for first-line antibiotics while EMA pharmacovigilance frameworks tighten recurrent-case protocols, forcing hospital formularies to rebalance procurement tiers between premium biologics and commodity generics.
Growth Catalysts
- Aging demographics:Patient pools in the United States, Germany, and Japan are expanding as populations over 65 require more frequent intervention for complicated diverticulitis cases.
- EU MDR compliance:Stricter clinical evidence requirements for surgical mesh devices are elevating barriers for new entrants and consolidating share among established manufacturers with robust trial infrastructure.
- Microbiome-modulating protocols:Probiotic adjuvants are capturing gastroenterology practice mindshare as clinicians seek alternatives to extended antibiotic courses.
Market Restraints
- Antimicrobial resistance surveillance:CDC and ECDC tracking data are narrowing the effective therapeutic window for legacy fluoroquinolone regimens.
- Supply concentration in oral antibiotics:North American health system procurement depends on a limited manufacturing base for high-volume generic formulations.
- Technical limitation in non-invasive staging:Hinchey classification requires imaging confirmation that delays treatment initiation in resource-constrained settings.
Strategic Opportunities
- Homecare administration routes:Oral antibiotic regimens paired with telehealth monitoring are reducing inpatient length-of-stay and opening ambulatory revenue streams.
- Japan's geriatric care infrastructure:METI-supported digital health integration creates pathways for remote patient management in diverticulitis recurrence prevention.
- Immunology R&D convergence:Novel anti-inflammatory mechanisms targeting complicated cases represent unaddressed therapeutic white space beyond antibiotics and surgery.
Industry Challenges
- Specialized surgical training gaps:Laparoscopic colectomy proficiency requirements limit hospital capacity for emergent Hinchey stage III-IV interventions.
- ISO 13485 certification timelines:Updated quality management standards are extending device approval cycles for mesh and stapling platform innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diverticulitis Disease Market |
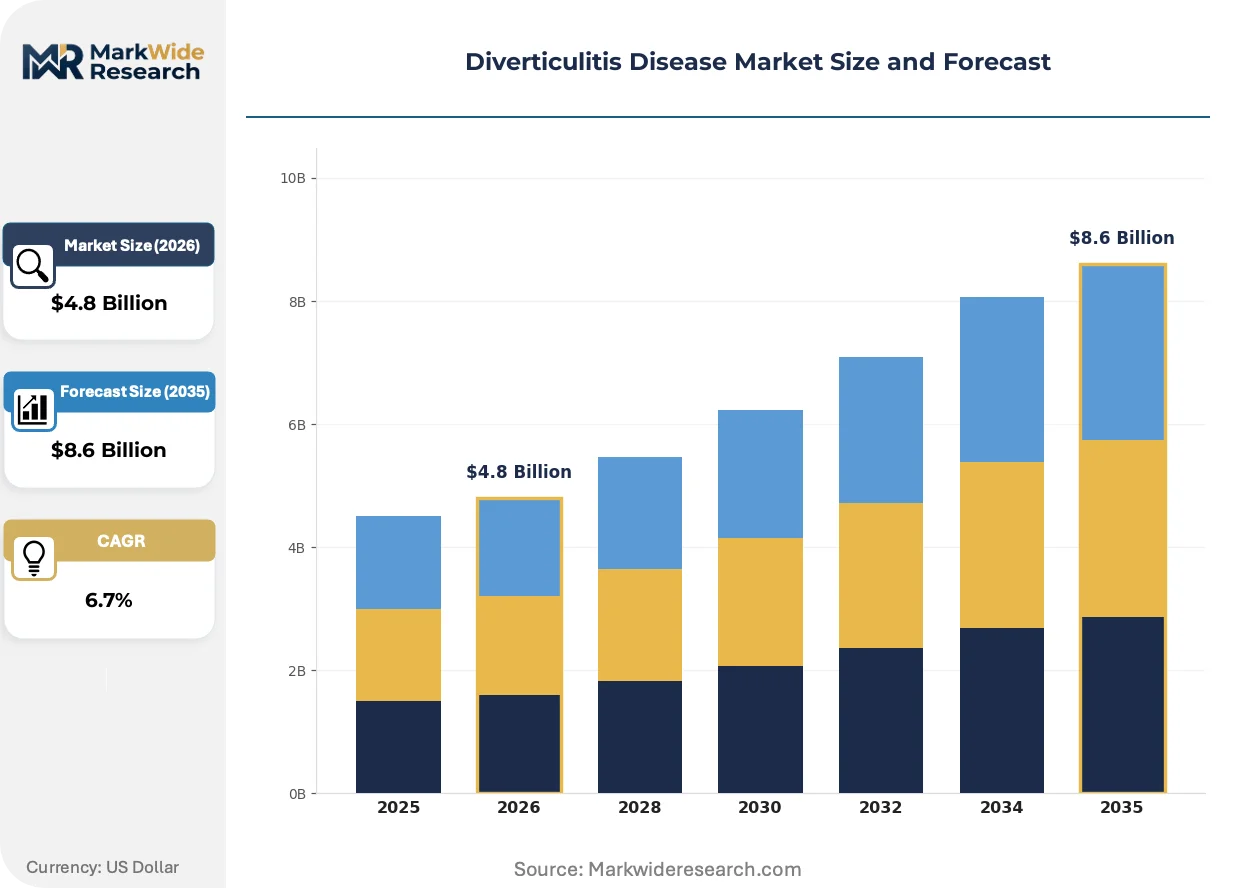
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Antibiotics, Dietary Fiber, Surgery, Probiotics End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Administration Route: Oral, Intravenous, Rectal, Topical Severity Level: Mild, Moderate, Severe, Complicated |
| Companies Covered | Pfizer Inc., Johnson & Johnson, F. Hoffmann-La Roche AG, Merck & Co. Inc., AbbVie Inc., Bayer AG, Novartis AG, Abbott Laboratories, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diverticulitis Disease Market Emerging Trajectories
Microbiome-targeted therapies and minimally invasive surgical platforms are reshaping clinical pathways, while procurement digitization and antimicrobial stewardship compliance are restructuring how hospitals allocate budgets across treatment modalities.
Next-generation probiotic formulations are consolidating position within gastroenterology treatment protocols. Academic medical centers in the United States and university hospitals in Germany are piloting adjuvant microbiome restoration alongside standard antibiotic courses. This convergence is compressing the addressable market for extended-spectrum antibiotics in uncomplicated cases.
EMA pharmacovigilance frameworks and FDA antimicrobial stewardship mandates are tightening prescription surveillance across outpatient settings. Hospital formularies must now document clinical justification for recurrent-case antibiotic selection. Surgical device manufacturers face elevated post-market surveillance obligations under EU MDR that extend trial commitments beyond traditional approval windows.
Hospital procurement teams are unbundling antibiotic sourcing from bundled infection-management contracts. Large integrated delivery networks in the United States are negotiating direct agreements with oral antibiotic suppliers, bypassing traditional group purchasing organizations. This disintermediation concentrates volume with manufacturers demonstrating manufacturing scale and supply chain redundancy.
Diverticulitis Disease Market Segmentation
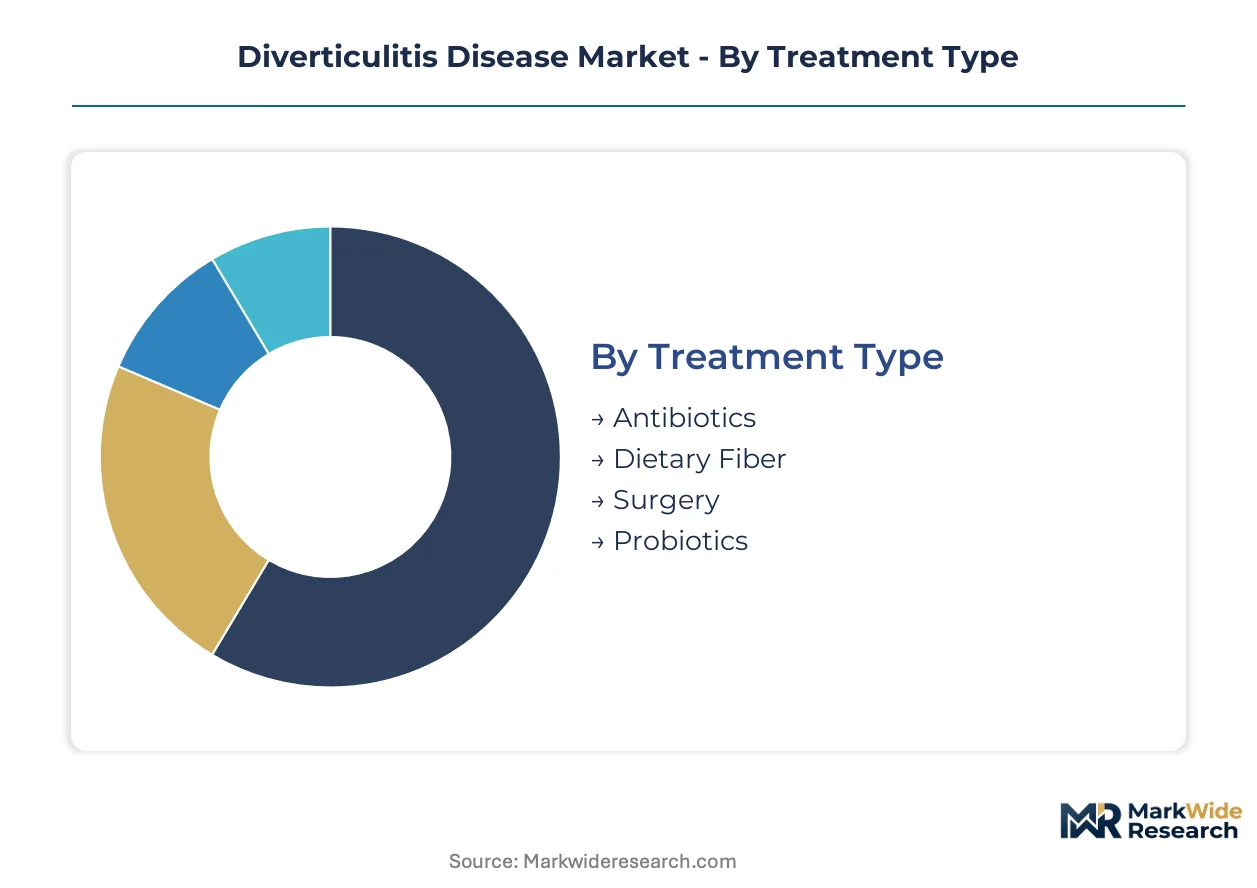
Segmentation in the diverticulitis market reveals how procurement power, clinical severity, and care setting interact to determine revenue allocation. Hospital formulary decisions and antimicrobial stewardship mandates create divergent growth trajectories across treatment modalities and administration routes.
Treatment Type:
Supply concentration in oral antibiotic manufacturing dominates procurement negotiations across North American health systems.
- Antibiotics:Fluoroquinolone and amoxicillin-clavulanate combinations constitute first-line therapy for uncomplicated cases. Hospital procurement in the United States concentrates volume with manufacturers demonstrating manufacturing scale and FDA-compliant active pharmaceutical ingredient sourcing.
- Surgery:Laparoscopic colectomy, Hartmann's procedure, and primary anastomosis address Hinchey stage III-IV complications. Academic medical centers in Germany and Japan are consolidating specialized training programs to expand emergent surgical capacity.
- Dietary Fiber:Psyllium husk and methylcellulose formulations support prevention protocols in outpatient gastroenterology practices.
- Probiotics:Lactobacillus and Bifidobacterium strains are gaining formulary inclusion as microbiome-modulating adjuvants in European university hospitals.
Today's leader: Antibiotics. Tomorrow's challenger: Probiotics.
End User:
Cost tier stratification separates capital-intensive inpatient facilities from ambulatory and home-based care models.
- Hospitals:Tertiary centers anchor absolute spending through emergency department admissions and surgical intervention capacity. Integrated delivery networks in the United States are unbundling antibiotic sourcing from bundled infection-management contracts.
- Homecare:Oral antibiotic regimens paired with telehealth monitoring are reducing inpatient length-of-stay. Japan's METI-supported digital health infrastructure creates pathways for remote patient management in recurrence prevention.
- Clinics:Outpatient gastroenterology practices in Germany manage uncomplicated cases through standardized antibiotic protocols.
- Long-term Care Facilities:Skilled nursing facilities in the United States handle post-acute recovery following surgical discharge.
Volume concentrates in hospitals. Margin expansion concentrates in homecare.
Administration Route:
Application requirements vary sharply between acute intervention and maintenance therapy settings.
- Oral:Ciprofloxacin-metronidazole combinations and amoxicillin-clavulanate tablets enable outpatient management of uncomplicated diverticulitis. North American health system procurement depends on a limited manufacturing base for high-volume generic formulations.
- Intravenous:Piperacillin-tazobactam and carbapenem antibiotics address severe or complicated cases requiring hospitalization. EMA pharmacovigilance frameworks tighten surveillance on extended-spectrum agent utilization.
- Rectal:Mesalamine enemas serve adjunctive roles in colonic inflammation management.
- Topical:Limited application in perioperative wound care following open surgical approaches.
Oral routes dominate prescription volume. Intravenous routes dominate acute care revenue.
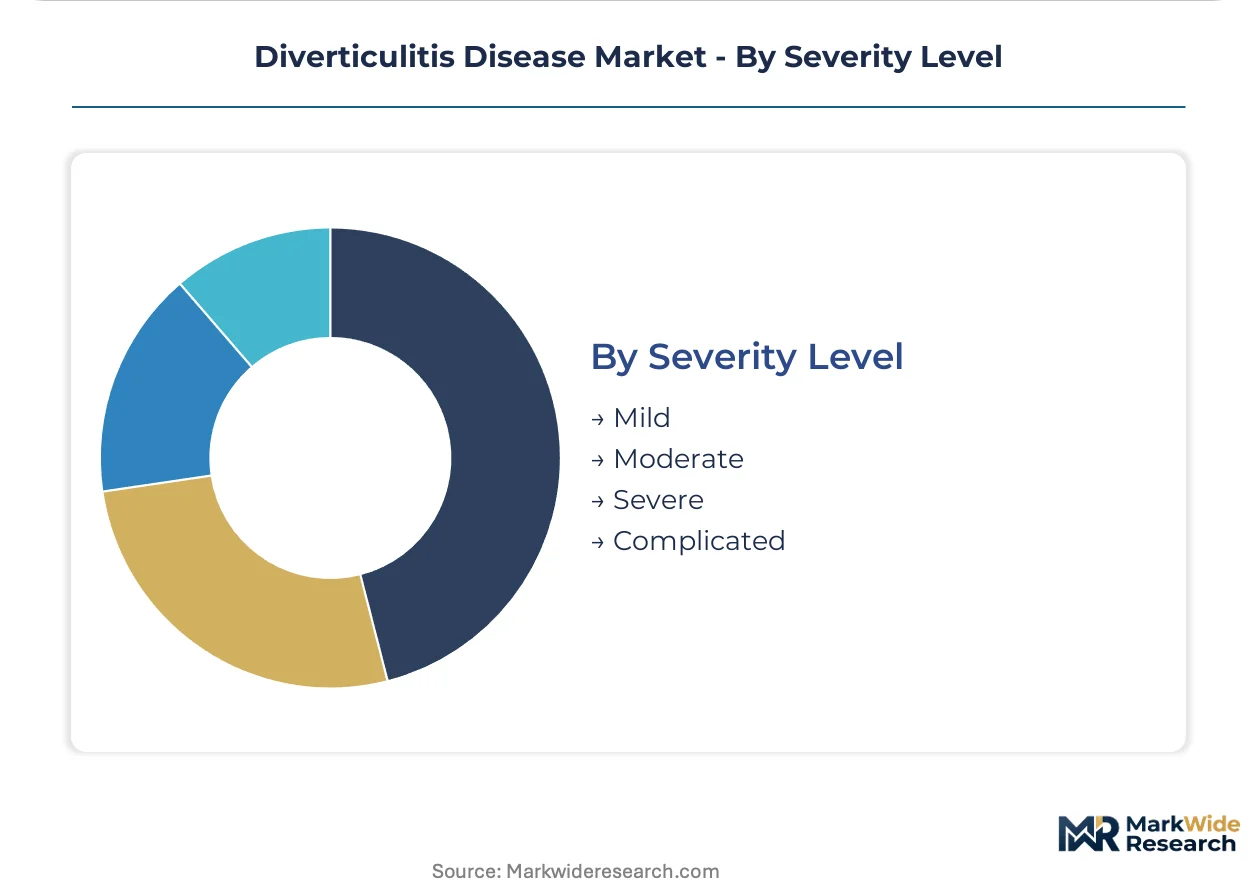
Severity Level:
Customer type segmentation aligns with Hinchey classification staging and corresponding intervention intensity.
- Mild:Outpatient bowel rest and oral antibiotics resolve inflammation without hospital admission. Primary care networks in the United States manage the majority of incident cases.
- Complicated:Abscess formation, perforation, or fistula requires interventional radiology drainage or surgical resection. Academic medical centers capture premium reimbursement for Hinchey stage III-IV interventions.
- Moderate:Short-stay hospitalization with intravenous antibiotics bridges outpatient and surgical management.
- Severe:Systemic inflammatory response or sepsis mandates intensive care unit admission and broad-spectrum antimicrobial coverage.
Mild cases generate volume. Complicated cases generate margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized gastroenterology training programs in the United States, Germany, and Japan anchor the geographic concentration of diverticulitis treatment capacity. Hospital procurement teams in these markets negotiate directly with antibiotic manufacturers and surgical device suppliers, bypassing traditional intermediaries. Regulatory frameworks in each jurisdiction reshape prescription protocols and reimbursement tiers.
United States
Aging demographics expand the addressable patient pool as populations over 65 require more frequent intervention for complicated cases. FDA antimicrobial stewardship mandates compress prescription durations for first-line antibiotics and tighten surveillance on recurrent-case selection. Academic medical centers in Boston and the Mayo Clinic system consolidate specialized training programs to expand laparoscopic colectomy capacity for Hinchey stage III-IV interventions.
Germany
University hospitals anchor absolute spending through emergency department admissions and surgical intervention capacity. EU MDR imposes stricter clinical evidence requirements on surgical mesh and bowel resection devices, elevating compliance costs for manufacturers. The Rhine-Ruhr and Bavarian hospital networks pilot adjuvant microbiome restoration protocols alongside standard antibiotic courses.
Japan
METI-supported digital health integration creates pathways for remote patient management in diverticulitis recurrence prevention. PMDA frameworks govern antimicrobial agent approval and post-market surveillance for extended-spectrum antibiotics. Tokyo and Osaka metropolitan hospital systems concentrate laparoscopic surgical expertise and telehealth monitoring infrastructure.
United Kingdom
NHS procurement digitization unbundles antibiotic sourcing from bundled infection-management contracts, concentrating volume with manufacturers demonstrating supply chain redundancy. NICE guidelines on antimicrobial stewardship reshape outpatient prescription protocols across primary care networks. London teaching hospitals and the Manchester academic health science center anchor specialized gastroenterology capacity.
France
ANSM pharmacovigilance frameworks tighten surveillance on fluoroquinolone utilization in outpatient settings. Hospital formularies in the Île-de-France region document clinical justification for recurrent-case antibiotic selection. Paris and Lyon university hospital clusters concentrate interventional radiology capacity for abscess drainage in complicated cases.
Diverticulitis Disease Market Vendor Landscape
Capital-heavy pharmaceutical manufacturers compete with asset-light biologic developers across the diverticulitis treatment spectrum. The market structure consolidates around three tiers: multinational antibiotic suppliers with manufacturing scale, diversified medical device conglomerates with surgical platform portfolios, and immunology specialists pursuing novel anti-inflammatory mechanisms. Strategic moves concentrate on unbundling procurement relationships, expanding telehealth-enabled homecare administration, and securing microbiome therapy pipeline assets.
Within the diversified pharmaceutical tier, Pfizer Inc. and Johnson & Johnson occupy positions defined by manufacturing infrastructure breadth and surgical device specialization respectively. AbbVie Inc. represents the immunology R&D vector, anchoring investment in novel mechanisms for complicated cases. F. Hoffmann-La Roche AG and Novartis AG exemplify European-headquartered conglomerates with cross-therapeutic presence, while Merck & Co. Inc. and Bayer AG sit within the legacy antibiotic and gastrointestinal portfolio segment. These seven entities collectively span the treatment modality spectrum from oral generics through biologic innovation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| F. Hoffmann-La Roche AG |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Bayer AG |
| Novartis AG |
| Abbott Laboratories |
| GlaxoSmithKline plc |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up antibiotic manufacturers anchor North American oral generic supply, concentrating procurement leverage with integrated delivery networks while compressing margin pools for non-scale producers across both pricing negotiations and manufacturing investment decisions.
Pricing Analysis
Bundled infection-management contracts are unbundling into discrete antibiotic sourcing agreements. Three-tier pricing structure across premium biologics, standard branded antibiotics, and economy generic formulations separates hospital formulary tiers. Price differentiation tracks FDA-compliant active pharmaceutical ingredient certification and manufacturing scale. Cost compression in oral generic antibiotics is intensifying because procurement teams negotiate direct agreements bypassing group purchasing organizations. Academic medical centers show least price sensitivity for Hinchey stage III-IV surgical interventions.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on Indian and Chinese specialty chemical producers, with finished dose manufacturing concentrated in the United States and Germany. Key inputs include fluoroquinolone precursors, amoxicillin-clavulanate intermediates, and probiotic culture strains. Single-source vulnerability in high-volume generic oral antibiotic production elevates risk for North American health system formularies. Distribution runs through integrated delivery network direct agreements and traditional wholesale channels serving outpatient clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where antimicrobial stewardship mandates and microbiome-modulating protocol adoption shift demand toward premium biologic and probiotic specifications.
For Market Incumbents: To counter microbiome-targeted therapy pipeline entrants, antibiotic manufacturers should deepen backward integration into FDA-compliant active pharmaceutical ingredient sourcing and expand manufacturing redundancy across multiple production sites. Surgical device incumbents must accelerate EU MDR clinical evidence generation for mesh and stapling platforms to defend hospital formulary positioning against emerging competitors.
For New Entrants and Emerging Players: Telehealth-enabled homecare administration routes offer the most penetrable white space for digital health platforms targeting Japan's METI-supported infrastructure and United States integrated delivery network remote monitoring programs. Probiotic adjuvant formulations for uncomplicated case prevention represent the fastest-expanding margin pool. A direct-to-clinic sampling program bypassing hospital procurement gatekeepers enables initial traction.
For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light biologic developers with immunology R&D pipelines targeting complicated diverticulitis anti-inflammatory mechanisms. Long-term viability centers on portfolio convergence between conventional antibiotics and microbiome-modulating modalities. The signal to watch is FDA antimicrobial stewardship mandate expansion into outpatient recurrent-case protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Microbiome restoration protocol readouts at German university hospitals validate probiotic adjuvant positioning. |
| Regulatory Approval Pathway | PMDA antimicrobial agent submissions in Japan open extended-spectrum antibiotic market access. |
| Manufacturing Scale-Up | FDA-compliant active pharmaceutical ingredient capacity expansion secures North American health system procurement volume. |
| Hospital System Partnership | Direct agreements with United States integrated delivery networks bypass group purchasing organization intermediaries. |
| Pipeline Diversification | Novel anti-inflammatory mechanisms for Hinchey stage III-IV cases address unmet therapeutic white space. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, formulary directors, gastroenterology clinicians, and surgical device regulatory affairs leads with secondary validation against FDA filings, EMA pharmacovigilance databases, ClinicalTrials.gov entries, and hospital procurement contract repositories. Bottom-up patient volume modeling and top-down pharmaceutical spending analysis provided triangulation across the analysis window.
Segment-weighting approaches modeled treatment type, severity level, administration route, and end-user facility tier across the projection horizon. CAGRs derived from historical procedure volume trajectories, antimicrobial prescription surveillance data, and surgical intervention reimbursement trend analysis. Forecast inputs incorporated aging demographic projections and regulatory mandate implementation timelines without specific year anchoring.
The model assumes a particular technology adoption path; alternative pathways for microbiome-targeted therapy clinical validation would alter the outlook. Forecasts reflect assumptions about antimicrobial stewardship compliance rates and probiotic formulary inclusion velocity. Supply concentration in oral generic manufacturing and evolving EMA pharmacovigilance frameworks warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Malignant Pleural Effusion Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Progressive Multifocal Leukoencephalopathy Treatment Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Scleritis Market