
 Pedestrian Detection System Market | 2026-2036
Pedestrian Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Pedestrian Detection System Market Analysis
A shortage of embedded-vision engineers is redrawing competitive boundaries in pedestrian detection hardware. Mobileye leverages its Jerusalem-based R&D hub to sustain algorithmic leadership in monocular camera solutions. Continental AG anchors European supply through its integrated radar-camera production in Germany. Robert Bosch GmbH competes across multiple sensor modalities with manufacturing scale that spans three continents.
Pedestrian detection systems fuse active sensors and machine-vision algorithms to identify human movement vectors and trigger braking or steering interventions within milliseconds. Camera systems dominate volume deployment due to cost curves and packaging flexibility, though lidar systems capture premium positioning in robotaxi and Level 4 autonomous vehicle programs. Advanced Driver Assistance Systems applications absorb the majority of unit shipments, while Smart Cities infrastructure represents a nascent but structurally distinct demand pool with longer procurement cycles.
NHTSA's Federal Motor Vehicle Safety Standards and Euro NCAP assessment protocols jointly determine minimum sensor configurations for new vehicle types in the United States and European Union. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces comparable pedestrian protection benchmarks that shape product development priorities for Denso Corporation and other Asian suppliers. Stakeholders must monitor divergence between camera-centric and multi-sensor regulatory test scenarios as this tension will determine which technology investments retain compliance value through the next product cycle.
Market Dynamics
Automotive OEM procurement of active safety suites is intensifying as Euro NCAP pedestrian safety protocols and NHTSA rulemaking tighten test requirements, compressing development cycles and forcing sensor architecture decisions years ahead of production.
Growth Catalysts
- Euro NCAP Assessment Protocols:Mandatory pedestrian protection scoring for new vehicle types in the European Union is forcing sensor suite upgrades across mass-market nameplates.
- Machine-vision algorithm maturation:Deep learning inference on embedded automotive processors now enables real-time pedestrian trajectory prediction at sub-$200 bill-of-materials cost points.
- German premium vehicle production:Concentrated OEM engineering resources in Stuttgart, Munich, and Wolfsburg are accelerating validation cycles for multi-sensor fusion architectures.
Market Restraints
- Embedded-vision engineer scarcity:Talent shortages in computer vision and sensor fusion are inflating R&D costs and extending hiring timelines for Tier 1 suppliers.
- Lidar component supply concentration:Critical solid-state emitter and SPAD detector production clusters in select East Asian manufacturing zones create single-source vulnerability for premium autonomous programs.
- NHTSA test scenario divergence:Proposed Federal Motor Vehicle Safety Standards for nighttime pedestrian detection impose technical requirements misaligned with current camera-centric Euro NCAP methodologies.
Strategic Opportunities
- Smart Cities infrastructure procurement:Municipal traffic management authorities in Japan and Germany are piloting roadside pedestrian detection for intersection conflict warning, opening hardware-as-a-service revenue models.
- Radar-camera sensor convergence:Integrated 4D imaging radar and high-resolution camera modules are collapsing system complexity and enabling single-supplier turnkey solutions.
- Japan's MLIT pedestrian protection benchmarks:Enforcement timelines for domestic-market vehicles are creating captive demand for Denso Corporation and other Asian suppliers with localized validation capabilities.
Industry Challenges
- Sensor fusion calibration complexity:Synchronizing radar, camera, and lidar data streams across temperature and vibration ranges demands specialized test facilities that few Tier 2 component suppliers possess.
- ISO 26262 functional safety certification:ASIL-D qualification for pedestrian detection algorithms requires 18-24 month validation cycles that delay platform launches and freeze architecture decisions early in vehicle programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pedestrian Detection System Market |
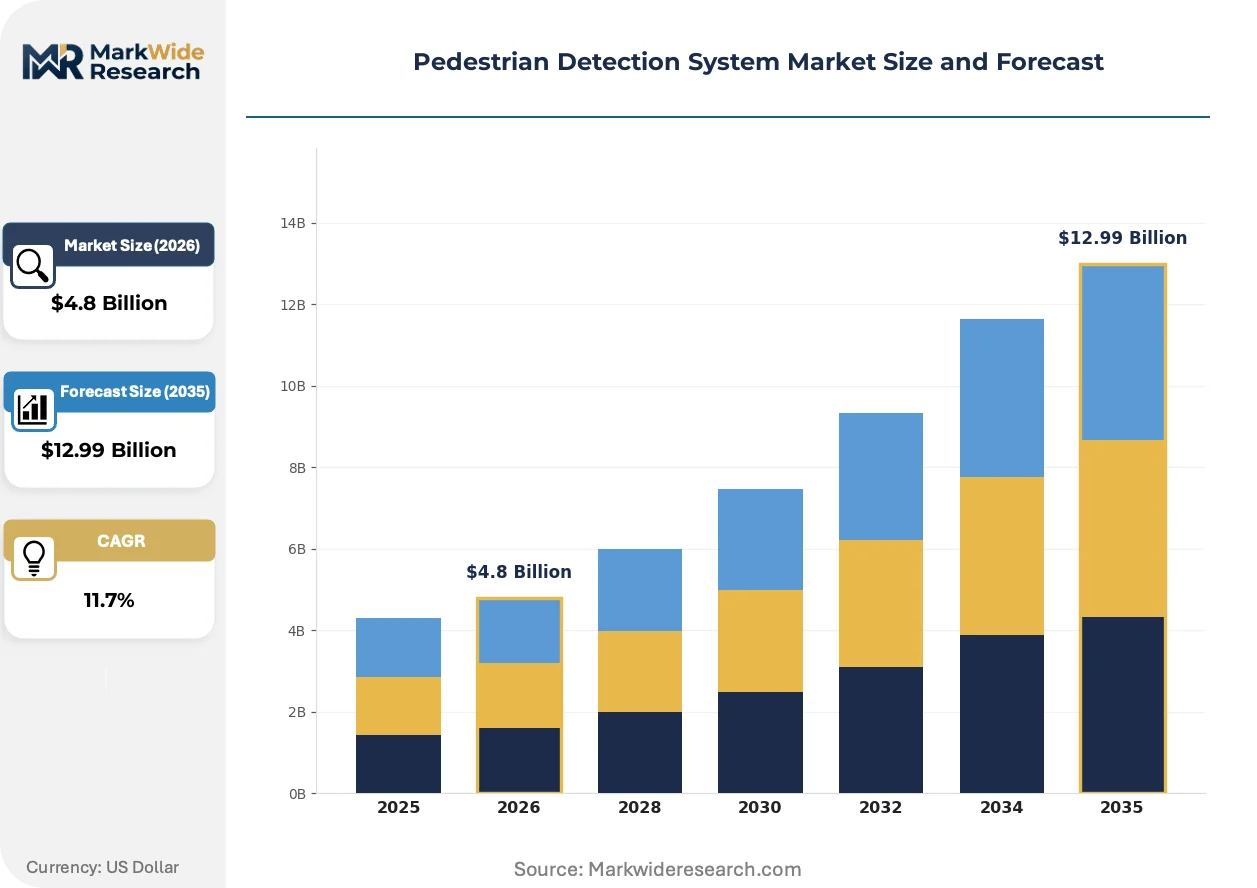
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Systems, Lidar Systems, Radar Systems, Ultrasonic Sensors End User: Automobile Manufacturers, Technology Providers, Fleet Operators, Public Transport Application: Smart Cities, Autonomous Vehicles, Bicycle Detection, Advanced Driver Assistance Systems Technology: Machine Learning, Computer Vision, Signal Processing, Artificial Intelligence |
| Companies Covered | Valeo, Mobileye, Robert Bosch GmbH, NVIDIA Corporation, Aptiv, Continental AG, ZF Friedrichshafen AG, Magna International, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pedestrian Detection System Market Emerging Trajectories
Algorithm-hardware co-design is compressing the traditional separation between perception software and sensor hardware, enabling tighter optimization for specific regulatory test scenarios and cost targets.
Monocular camera solutions with neural network-based depth estimation are fragmenting the historical radar-camera-lidar hierarchy in Level 2 ADAS applications. Mid-market OEMs in Germany and the United States are adopting these simplified architectures to meet Euro NCAP and NHTSA requirements without lidar cost premiums. The technology is fragmenting supplier relationships as software-centric vendors capture value previously held by sensor hardware specialists.
REACH substance restrictions on automotive electronics are forcing material substitutions in camera module housings and radar antenna substrates. European Tier 1 suppliers are redesigning thermal management components to eliminate restricted flame retardants ahead of 2026 enforcement deadlines. German production lines are most affected, with requalification costs concentrated in Stuttgart-area manufacturing clusters.
Fleet procurement of ADAS retrofit kits is displacing traditional aftermarket distribution through direct OEM service channel integration. Commercial vehicle operators in the United States are sourcing pedestrian detection upgrades through authorized dealer networks rather than independent installers. This pattern is most visible in California and Texas, where large logistics fleets negotiate enterprise service contracts bundling hardware, installation, and over-the-air calibration updates.
Pedestrian Detection System Market Segmentation
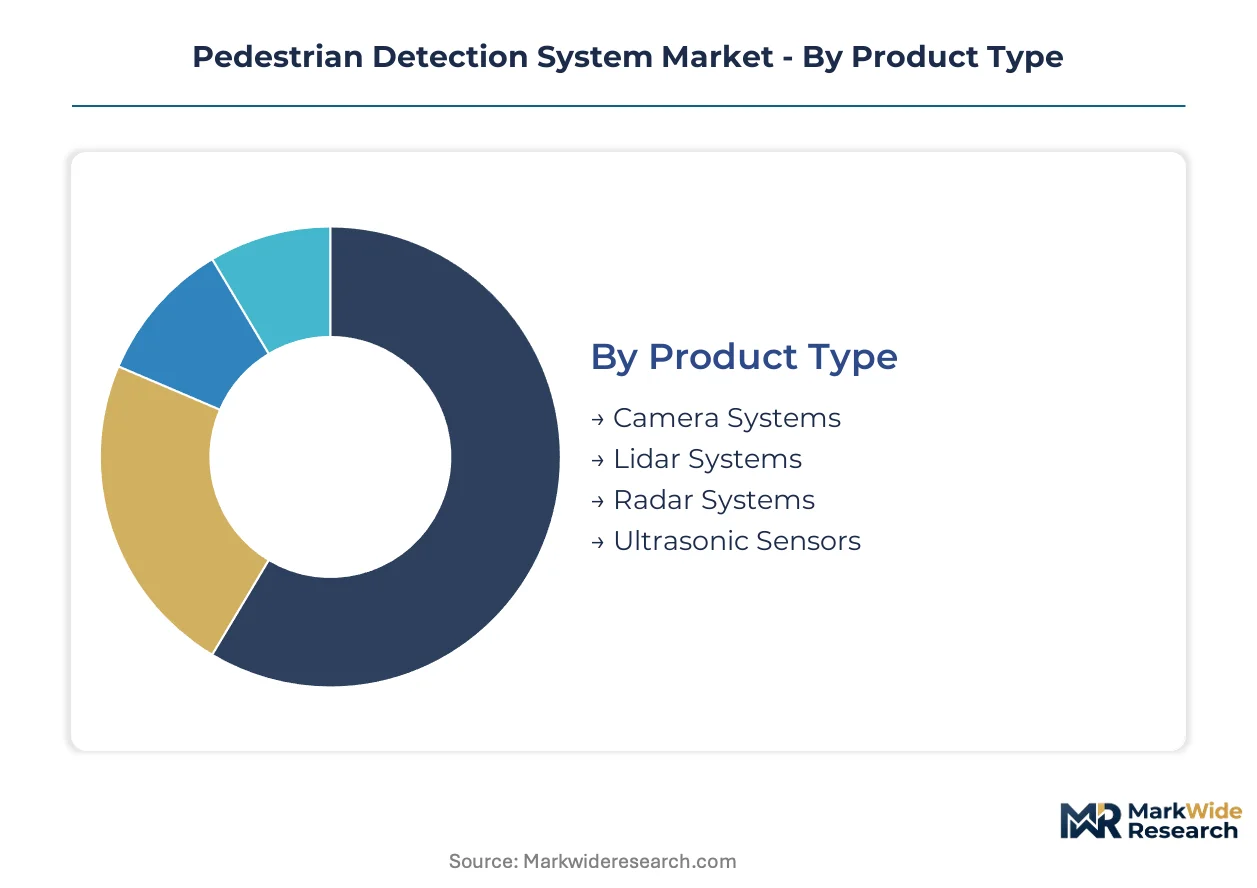
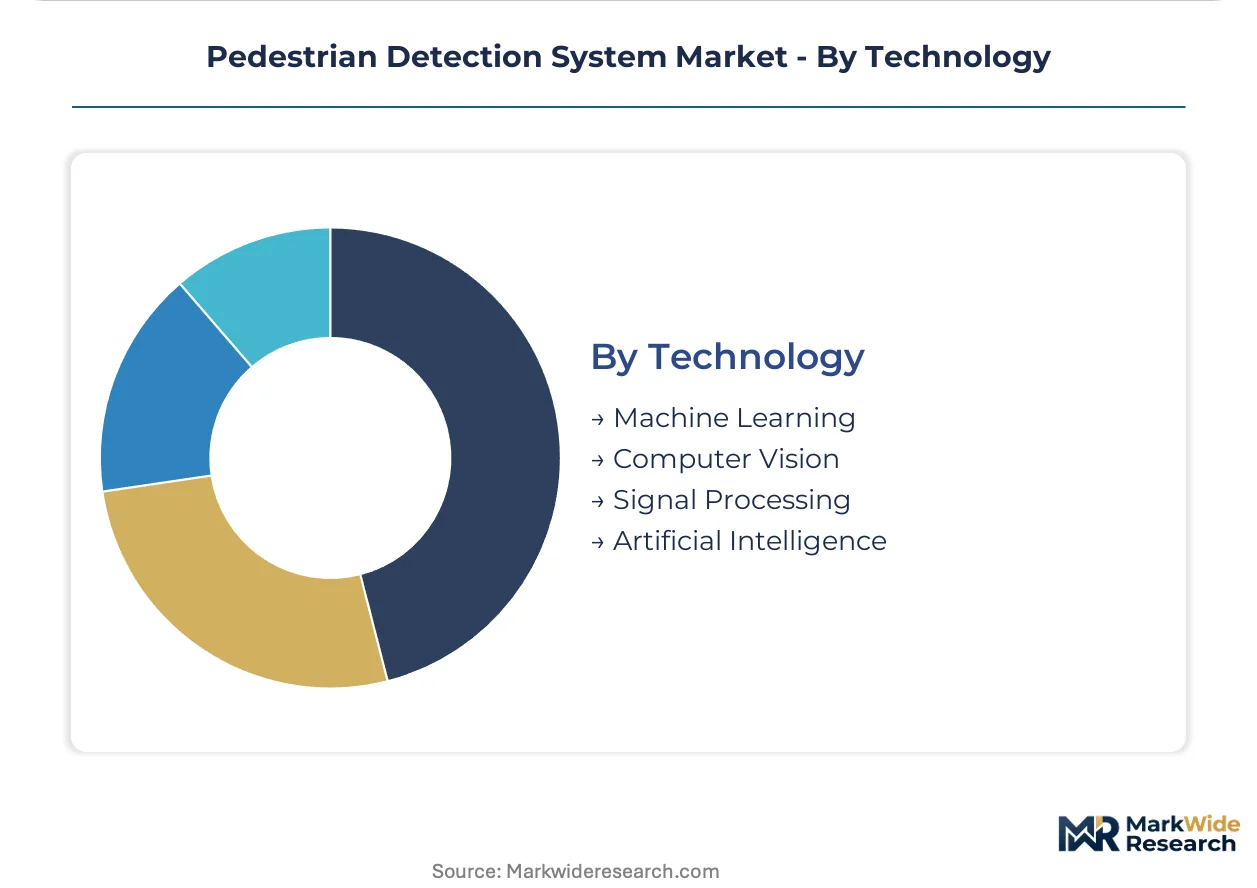
Pedestrian detection architectures fragment across sensor modalities and computational approaches, with regulatory test protocols determining which configurations achieve compliance certification in each jurisdiction. Tier 1 suppliers must maintain parallel product lines to address divergent Euro NCAP camera-centric standards and NHTSA multi-sensor requirements.
Product Type:
Euro NCAP and NHTSA protocols enforce distinct minimum sensor configurations, fragmenting procurement specifications across automotive OEMs serving different regulatory jurisdictions.
- Camera Systems:Monocular and stereo configurations leverage embedded neural networks for real-time depth estimation and trajectory prediction. German premium OEMs in Stuttgart and Munich validate these architectures for Euro NCAP pedestrian protection scoring, though NHTSA nighttime detection requirements are forcing supplementary sensor additions.
- Lidar Systems:Solid-state and mechanical scanning units generate dense point clouds for centimeter-precision positioning in urban environments. Robotaxi programs in California and Arizona absorb the majority of volume, with Waymo and Cruise procurement cycles driving emitter and SPAD detector demand.
- Radar Systems:4D imaging radar with elevation resolution enables all-weather operation independent of lighting conditions. Continental AG and Robert Bosch GmbH anchor European supply through integrated radar-camera production in Germany.
- Ultrasonic Sensors:Short-range proximity detection for low-speed maneuvering in parking and dense urban scenarios. Asian suppliers dominate component sourcing due to established piezoelectric transducer manufacturing clusters.
Camera systems handle the majority of throughput; lidar systems are gaining share fastest among premium autonomous vehicle programs.
End User:
Procurement authority concentrates with vehicle manufacturers, though fleet direct purchasing is restructuring traditional Tier 1 distribution channels.
- Automobile Manufacturers:Volkswagen Group, Toyota, and Ford Motor Company integrate pedestrian detection into active safety suites across nameplate ranges. Platform engineering decisions made years ahead of production freeze sensor architectures and supplier relationships.
- Fleet Operators:Logistics and commercial vehicle operators in Texas and California negotiate enterprise service contracts bundling hardware, installation, and over-the-air calibration. This procurement pattern is displacing traditional aftermarket distribution through direct OEM service channel integration.
- Technology Providers:Autonomous vehicle developers and mobility platforms source pre-integrated perception stacks rather than discrete sensors. Mobileye and Waymo maintain captive algorithm-hardware optimization teams.
- Public Transport:Municipal bus and tram operators in Japan and Germany pilot retrofit programs for vulnerable road user protection in dense urban corridors.
Automobile manufacturers command the largest procurement volumes; fleet operators are expanding most quickly as enterprise service contracts displace aftermarket channels.
Application:
ADAS penetration rates diverge sharply from autonomous vehicle and smart city deployment timelines, creating distinct revenue recognition patterns.
- Advanced Driver Assistance Systems:Emergency braking and collision avoidance functions represent the primary volume deployment channel. Euro NCAP mandatory scoring and NHTSA rulemaking are forcing sensor suite upgrades across mass-market nameplates.
- Autonomous Vehicles:Level 4 robotaxi programs require redundant multi-sensor configurations with functional safety certification to ASIL-D standards. Validation cycles extend 18-24 months and freeze architecture decisions early in vehicle programs.
- Smart Cities:Roadside intersection monitoring and traffic management infrastructure represents a nascent demand pool with municipal procurement cycles spanning multiple fiscal years. Pilot programs in Japan and Germany are testing hardware-as-a-service revenue models.
- Bicycle Detection:Vulnerable road user classification algorithms extend pedestrian detection models to two-wheeled vehicle trajectory prediction. Euro NCAP protocols are expanding test scenarios to include cyclist protection scoring.
Advanced Driver Assistance Systems processes the highest unit volumes; smart cities applications are climbing the fastest on long-term infrastructure investment commitments.
Technology:
Algorithm-hardware co-design is collapsing traditional boundaries between perception software and sensor hardware optimization teams.
- Computer Vision:Convolutional neural networks and transformer architectures process monocular and stereo camera streams for real-time object detection and tracking. Mobileye's Jerusalem-based R&D hub sustains algorithmic leadership in embedded automotive processors.
- Machine Learning:Deep learning inference on edge compute platforms enables trajectory prediction at sub-$200 bill-of-materials cost points. German premium vehicle production clusters in Stuttgart and Wolfsburg accelerate validation cycles for these architectures.
- Artificial Intelligence:End-to-end neural networks fuse multi-sensor inputs without explicit feature engineering. Regulatory approval frameworks for AI-driven safety-critical systems remain under development at NHTSA and Euro NCAP.
- Signal Processing:Radar and lidar point cloud preprocessing algorithms extract geometric features before downstream classification. Specialized digital signal processor architectures from Texas Instruments and NXP Semiconductors dominate automotive qualification.
Computer vision anchors current deployment volumes; artificial intelligence is expanding most quickly as end-to-end neural networks approach regulatory acceptance thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA rulemaking on nighttime pedestrian detection anchors United States market development. Euro NCAP protocols drive European procurement specifications. Japan's MLIT benchmarks shape Asian supplier priorities.
United States
NHTSA's proposed Federal Motor Vehicle Safety Standards for nighttime detection are forcing sensor architecture upgrades across Detroit-based OEM engineering centers. The rulemaking imposes technical requirements misaligned with camera-centric Euro NCAP methodologies. California and Texas logistics fleets negotiate enterprise service contracts bundling hardware, installation, and over-the-air calibration updates.
Germany
Euro NCAP mandatory pedestrian protection scoring compels sensor suite upgrades across Stuttgart, Munich, and Wolfsburg production clusters. REACH substance restrictions are forcing material substitutions in camera module housings ahead of 2026 enforcement deadlines. Continental AG and Robert Bosch GmbH anchor European supply through integrated radar-camera production.
Japan
MLIT pedestrian protection benchmarks create captive demand for domestic-market vehicle validation. Denso Corporation leverages localized engineering capabilities to serve Toyota and other Japanese OEMs. Kanto and Chubu manufacturing corridors concentrate Tier 1 supplier R&D facilities for multi-sensor fusion architectures.
China
GB standards and MIIT autonomous vehicle regulations are accelerating domestic lidar and camera module production scaling. Yangtze River Delta and Pearl River Delta manufacturing clusters host solid-state emitter and SPAD detector production. Local OEMs integrate pedestrian detection into active safety suites for both domestic consumption and export markets.
South Korea
Seoul Capital Area engineering centers validate pedestrian detection algorithms for Hyundai Motor Group and Kia platforms. MFDS-equivalent automotive safety frameworks align with Euro NCAP test protocols for export-bound vehicle programs. Busan-Ulsan manufacturing corridors concentrate camera module assembly for regional OEM supply.
Pedestrian Detection System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in pedestrian detection hardware supply. Tier 1 automotive suppliers with multi-sensor manufacturing footprints compete against software-centric algorithm developers with captive hardware optimization teams. Three archetypes dominate: integrated sensor-algorithm platforms, discrete component specialists, and autonomous vehicle stack providers. Competitive moves center on radar-camera sensor convergence and ISO 26262 functional safety certification acceleration.
Within the integrated sensor-algorithm tier, Mobileye and Continental AG exemplify divergent geographic and technical positioning. Mobileye anchors algorithmic development from its Jerusalem-based R&D hub, while Continental AG represents European manufacturing scale across radar-camera production lines. Robert Bosch GmbH occupies a position spanning multiple sensor modalities with three-continent manufacturing footprints.
| Leading Market Players |
|---|
| Valeo |
| Mobileye |
| Robert Bosch GmbH |
| NVIDIA Corporation |
| Aptiv |
| Continental AG |
| ZF Friedrichshafen AG |
| Magna International |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Scale economies in solid-state lidar emitter manufacturing concentrate production in Yangtze River Delta facilities, compressing unit costs for premium autonomous programs while establishing price floors for mid-market camera-radar fusion systems. This capacity concentration grants Tier 1 suppliers procurement leverage over OEMs in Stuttgart and Detroit, yet leaves them exposed to single-source vulnerability in SPAD detector supply.
Pricing Analysis
Geographic price spreads between German premium OEM contracts and mass-market Asian supply agreements exceed 40 percent on equivalent camera-radar fusion modules. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified architectures from Euro NCAP baseline configurations and aftermarket retrofit kits. Pricing pressure stems from embedded-vision engineer scarcity inflating R&D amortization across lower production volumes. Fleet operators in Texas and California exhibit highest price sensitivity due to enterprise service contract bundling, while robotaxi developers show lowest sensitivity given functional safety certification requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites critical semiconductor logistics for automotive image signal processors and neural network accelerators. Manufacturing concentration in China, South Korea, and Japan feeds camera module assembly, radar transceiver production, and lidar emitter fabrication. Raw material dependencies span silicon wafers, indium phosphide substrates, and specialized optical polymers. Single-source vulnerability in solid-state emitter supply creates structural risk for premium autonomous programs. Distribution runs through Tier 1 direct OEM supply agreements with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery anchored to NHTSA rulemaking timelines that will force sensor architecture refreshes across Detroit and Stuttgart engineering centers over the next product cycle.
For Market Incumbents: Secure algorithm-hardware co-design capabilities through captive embedded-vision engineering teams in Jerusalem or Munich talent clusters. Defend against software-centric entrants by accelerating ISO 26262 ASIL-D certification cycles for multi-sensor fusion architectures. Prioritize vertical integration into 4D imaging radar production to collapse system complexity for mid-market OEM procurement. For New Entrants and Emerging Players: Anchor in Smart Cities infrastructure procurement cycles in Japan and Germany where municipal traffic management authorities pilot roadside pedestrian detection with longer validation timelines. Target hardware-as-a-service revenue models for intersection conflict warning systems. Penetrate through direct municipal contracting rather than Tier 1 integration channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated sensor-algorithm platforms with multi-sensor manufacturing footprints spanning three continents. Long-term viability over a 5-10 year window rests on regulatory compliance value through divergent Euro NCAP and NHTSA test scenarios. Target acquisition archetypes include specialized computer vision teams with embedded automotive processor optimization expertise. Watch for inflection signals in NHTSA final rule publication timing and Euro NCAP protocol revision cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Radar-Camera Sensor Convergence | Integrated 4D imaging radar and high-resolution camera modules collapse system complexity for single-supplier turnkey solutions. |
| ISO 26262 ASIL-D Certification Acceleration | Shortened functional safety validation cycles freeze architecture decisions earlier in vehicle programs, locking in supplier relationships. |
| Smart Cities Hardware-as-a-Service Launch | Municipal traffic management pilots in Japan and Germany open recurring revenue streams distinct from automotive OEM procurement. |
| Embedded-Vision Engineering Talent Acquisition | Computer vision and sensor fusion specialists in Jerusalem and Munich clusters determine algorithmic leadership in monocular solutions. |
| REACH Compliance Material Redesign | Camera module housing substitutions ahead of 2026 enforcement deadlines concentrate requalification costs in Stuttgart-area manufacturing. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, embedded-vision algorithm developers, and municipal traffic management authorities and refined through secondary validation. Bottom-up demand modeling triangulated against top-down regulatory mandate analysis using vehicle production databases, IHS Markit registration data, Euro NCAP test protocol documentation, and NHTSA Federal Register filings.
Variance-decomposition across sensor modality, vehicle class, and regional regulatory cluster shaped the analytical framework. Segmentation dimensions modeled included product type, end user archetype, application tier, and technology approach across the projection horizon. CAGRs were derived from unit shipment trajectories and average selling price evolution. Industry-specific forecast inputs encompassed Euro NCAP scoring mandate timelines and NHTSA rulemaking progression.
Material uncertainties — regulatory test scenario divergence, embedded-vision engineer availability, and solid-state emitter supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about compliance pathway stability and technology maturation curves. Practitioners should keep alternative scenarios live as NHTSA final rule specifications and Euro NCAP protocol revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market