
 Betavoltaic Device Market | 2026-2036
Betavoltaic Device Market Size, Share, and Industry Trends Forecast 2026-2036
Betavoltaic Device Market Analysis
Multi-source sourcing for tritium and nickel-63 radioisotopes is consolidating as vendors secure long-term supply agreements with national isotope production facilities. Widetronix, Inc. leverages semiconductor fabrication partnerships to scale silicon carbide betavoltaic cell production. City Labs, Inc. sustains market presence through proprietary NanoTritium batteries designed for extreme-environment sensors. BetaBatt, Inc. specializes in volumetric energy density improvements for medical implant applications.
Betavoltaic devices convert beta particle emissions from radioisotopes into electrical current through semiconductor junctions, typically achieving power densities of 10–100 microwatts per cubic centimeter with operational lifespans exceeding twenty years. Radioisotope batteries dominate current revenue due to established aerospace procurement, while micro batteries represent the fastest-expanding category as healthcare miniaturization demands intensify. Semiconductor technology anchors the manufacturing base, though thermal conversion approaches are gaining traction for high-reliability underwater devices.
The US Nuclear Regulatory Commission governs radioisotope distribution and device licensing, while the FDA regulates betavoltaic-powered medical implants through premarket approval pathways. ISO 2919 standards for sealed radioactive sources shape international product certification requirements. Stakeholders must monitor isotope supply chain security and evolving radiation safety classifications as commercial deployment scales beyond defense and space applications.
Market Dynamics
Radioisotope supply concentration around national laboratory partnerships is compressing vendor qualification timelines and locking in procurement relationships before commercial scale-up. This supply-side consolidation shapes competitive positioning more than manufacturing scale.
Growth Catalysts
- Deep-space mission requirements:NASA's technology readiness level mandates for long-duration missions where solar charging fails are accelerating aerospace procurement of betavoltaic power systems.
- ISO 2919 certification pathways:International standards for sealed radioactive sources are streamlining cross-border device licensing and reducing regulatory friction for qualified vendors.
- Silicon carbide semiconductor fabrication:Partnerships with established foundries are enabling volume production of betavoltaic cells without dedicated capital expenditure.
Market Restraints
- Tritium supply concentration:Production of this critical radioisotope concentrates in national laboratory facilities, creating single-source dependency for device manufacturers.
- NRC licensing timelines:The US Nuclear Regulatory Commission's device approval processes extend commercialization cycles beyond typical venture capital horizons.
- Lithium-ion cost trajectories:Conventional battery economics in non-extreme applications limit betavoltaic penetration in price-sensitive sensor markets.
Strategic Opportunities
- Medical implant miniaturization:FDA premarket approval pathways for powered devices are opening as manufacturers demonstrate twenty-year operational lifespans without replacement surgery.
- Underwater sensor networks:Thermal conversion betavoltaic approaches are penetrating extreme-pressure monitoring applications where battery swap logistics prove prohibitive.
- Defense procurement channel expansion:Department of Energy radioisotope power systems program funding is broadening beyond space applications into remote terrestrial surveillance.
Industry Challenges
- Semiconductor physics specialization:The intersection of radiation damage modeling and wide-bandgap device engineering creates acute talent scarcity in hiring markets.
- Dual-use export control alignment:ITAR and EAR classification uncertainties complicate international sales of devices containing strategic radioisotopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Betavoltaic Device Market |
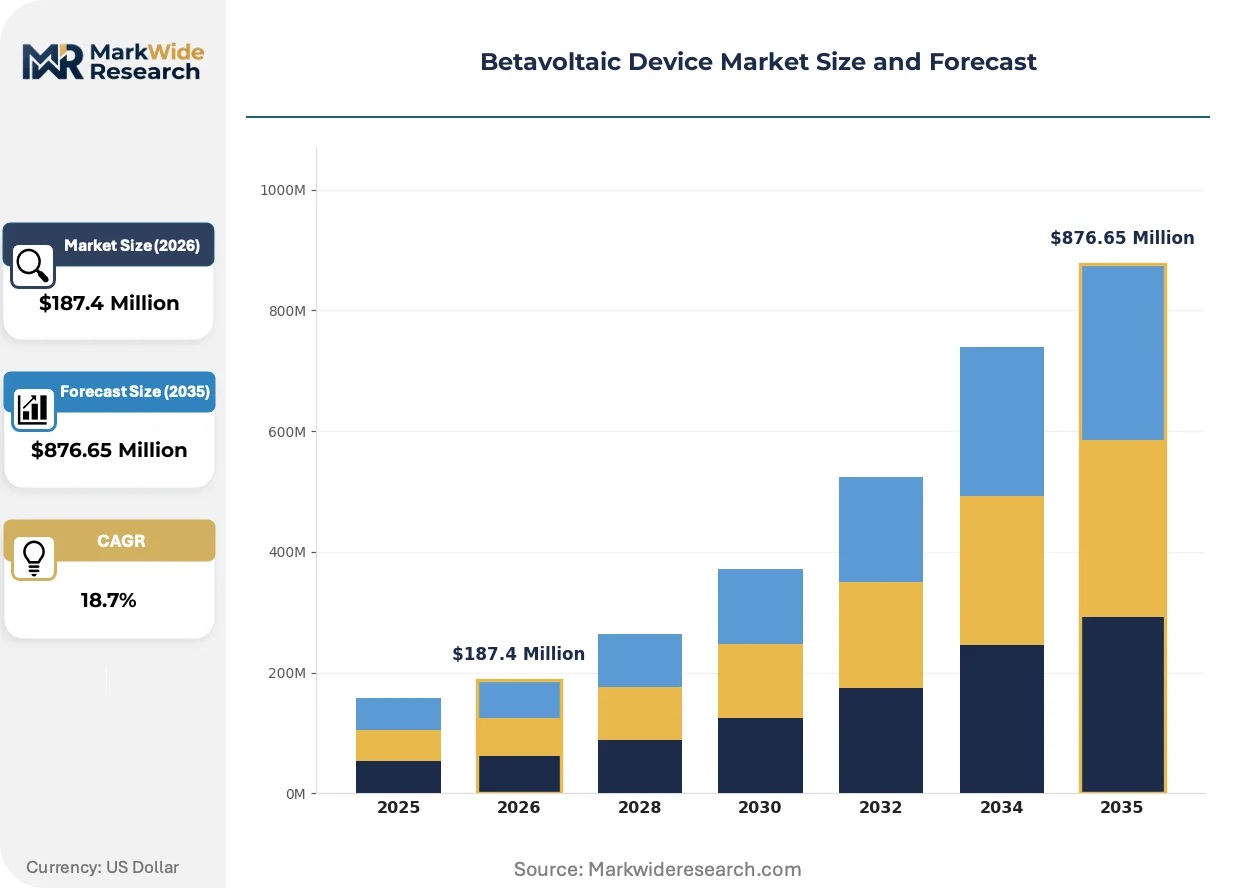
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radioisotope Batteries, Micro Batteries, Portable Power Sources, Energy Harvesting Units Application: Medical Implants, Aerospace Equipment, Remote Sensors, Underwater Devices End User: Healthcare Providers, Aerospace Manufacturers, Oil & Gas Companies, Research Institutions Technology: Semiconductor, Piezoelectric, Thermal, Electromagnetic |
| Companies Covered | Widetronix, Inc., NDB, Inc., City Labs, Inc., Elysium Space, Alpha Omega, BetaBatt, Inc., Qynergy Corporation, NUST MISIS, Direct Kinetic Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Betavoltaic Device Market Emerging Trajectories
Betavoltaic architecture is fragmenting into application-specific configurations rather than converging on universal platforms. This specialization is accelerating as end-users demand form factors matched to deployment constraints.
Silicon carbide betavoltaic junction design is modularizing around standardized die dimensions compatible with existing semiconductor packaging infrastructure. Aerospace prime contractors are adopting these modules for rapid mission-specific power system assembly. The approach is compressing custom engineering cycles from years to months for qualified vendors.
EU REACH substance restrictions on certain semiconductor processing chemicals are forcing reformulation of betavoltaic cell manufacturing protocols. The industrial consequence is qualification delays for European-sourced components. Medical device manufacturers are responding by diversifying supply chains toward US and Asian fabrication partners.
Sensor OEMs are unbundling power system procurement from device integration, creating dedicated betavoltaic specification roles within engineering teams. This organizational shift is displacing the previous model of battery vendor selection by purchasing departments. The pattern is most visible in United States defense contracting, where technical evaluation authority has migrated from logistics to systems engineering functions.
Betavoltaic Device Market Segmentation
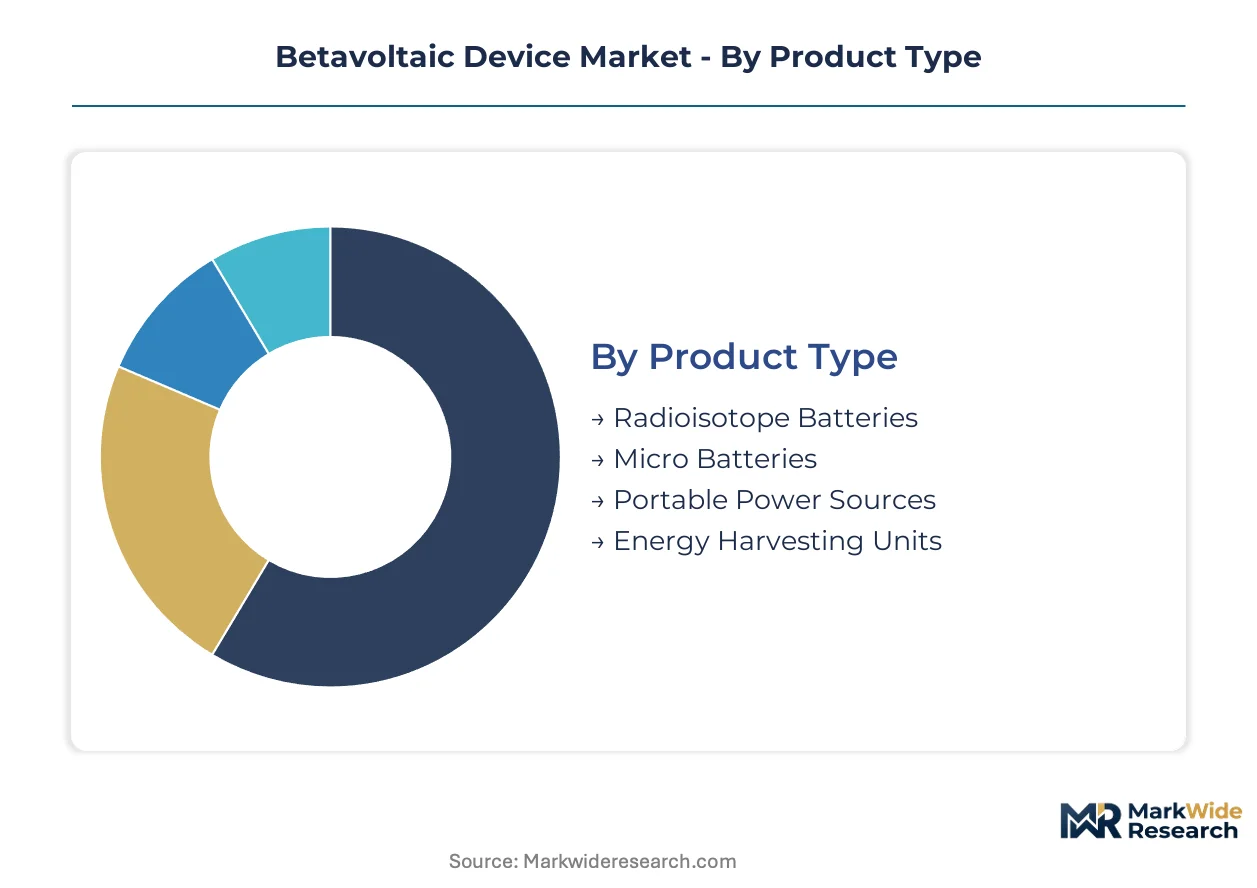
Betavoltaic device segmentation reveals how supply chain configuration and application requirements fragment manufacturing strategies. Radioisotope sourcing partnerships and semiconductor fabrication capabilities determine which product categories vendors can profitably serve.
Product Type:
Supply concentration around tritium and nickel-63 radioisotope production facilities locks device manufacturers into specific product architectures based on their procurement relationships.
- Radioisotope Batteries:These devices integrate sealed radioactive sources with wide-bandgap semiconductor junctions to deliver continuous microscale power across multi-decade operational lifespans. NASA's technology readiness level requirements and Department of Energy procurement channels concentrate demand in United States aerospace applications. Supply agreements with Oak Ridge National Laboratory and Savannah River National Laboratory determine competitive positioning.
- Micro Batteries:Miniaturized betavoltaic cells achieve sub-cubic-centimeter form factors through advanced semiconductor packaging techniques. FDA premarket approval pathways for twenty-year implantable devices are opening procurement channels at Mayo Clinic, Cleveland Clinic, and Johns Hopkins medical centers. Silicon carbide fabrication partnerships with foundries like X-FAB and GlobalFoundries enable volume scaling without captive manufacturing investment.
- Portable Power Sources:Larger-format betavoltaic systems serve defense remote surveillance applications where battery replacement logistics prove prohibitive.
- Energy Harvesting Units:Hybrid architectures combining betavoltaic base loads with supplemental energy harvesting target industrial IoT sensor networks.
Today's leader: Radioisotope Batteries. Tomorrow's challenger: Micro Batteries.
Application:
End-use environments dictate radiation shielding requirements, thermal management specifications, and regulatory approval pathways.
- Medical Implants:Cardiac pacemakers, neurostimulators, and drug delivery pumps leverage betavoltaic power to eliminate replacement surgeries. FDA Center for Devices and Radiological Health maintains active premarket review programs for long-life implantable power systems. ISO 14708 active implantable medical device standards shape electromagnetic compatibility testing protocols.
- Aerospace Equipment:Deep-space probes, lunar surface systems, and planetary landers deploy betavoltaic power where solar flux drops below operational thresholds. NASA Jet Propulsion Laboratory and Johns Hopkins Applied Physics Laboratory specify power system requirements for Discovery-class and New Frontiers missions. Technology readiness level 6+ mandates compress vendor qualification timelines.
- Remote Sensors:Arctic, desert, and mountain monitoring stations utilize betavoltaic power for seismic, meteorological, and environmental data collection.
- Underwater Devices:Extreme-pressure sensor networks for oil & gas subsea infrastructure and oceanographic research deploy thermal conversion betavoltaic architectures.
Medical Implants command premium pricing through regulatory moats. Aerospace Equipment offers volume scale through mission standardization.
End User:
Procurement sophistication varies dramatically across customer categories, with defense and space agencies driving technical specifications that commercial buyers later adopt.
- Healthcare Providers:Academic medical centers and integrated delivery networks evaluate betavoltaic power for implantable device portfolios. Cleveland Clinic's innovation programs and Mass General Brigham's procurement committees assess total cost of ownership across device lifecycles. Reimbursement coding from CMS shapes adoption economics.
- Aerospace Manufacturers:Lockheed Martin, Northrop Grumman, and Boeing satellite divisions specify betavoltaic power systems for classified and unclassified missions. NNSA and DOE radioisotope power systems program funding flows through prime contractor supply chains.
- Oil & Gas Companies:Chevron, ExxonMobil, and Shell deploy subsea sensors where wellhead intervention costs exceed betavoltaic power system premiums.
- Research Institutions:MIT Lincoln Laboratory, Sandia National Laboratories, and Lawrence Livermore National Laboratory pioneer advanced betavoltaic architectures.
Aerospace Manufacturers anchor current revenue. Healthcare Providers represent the steepest expansion trajectory as FDA pathways mature.
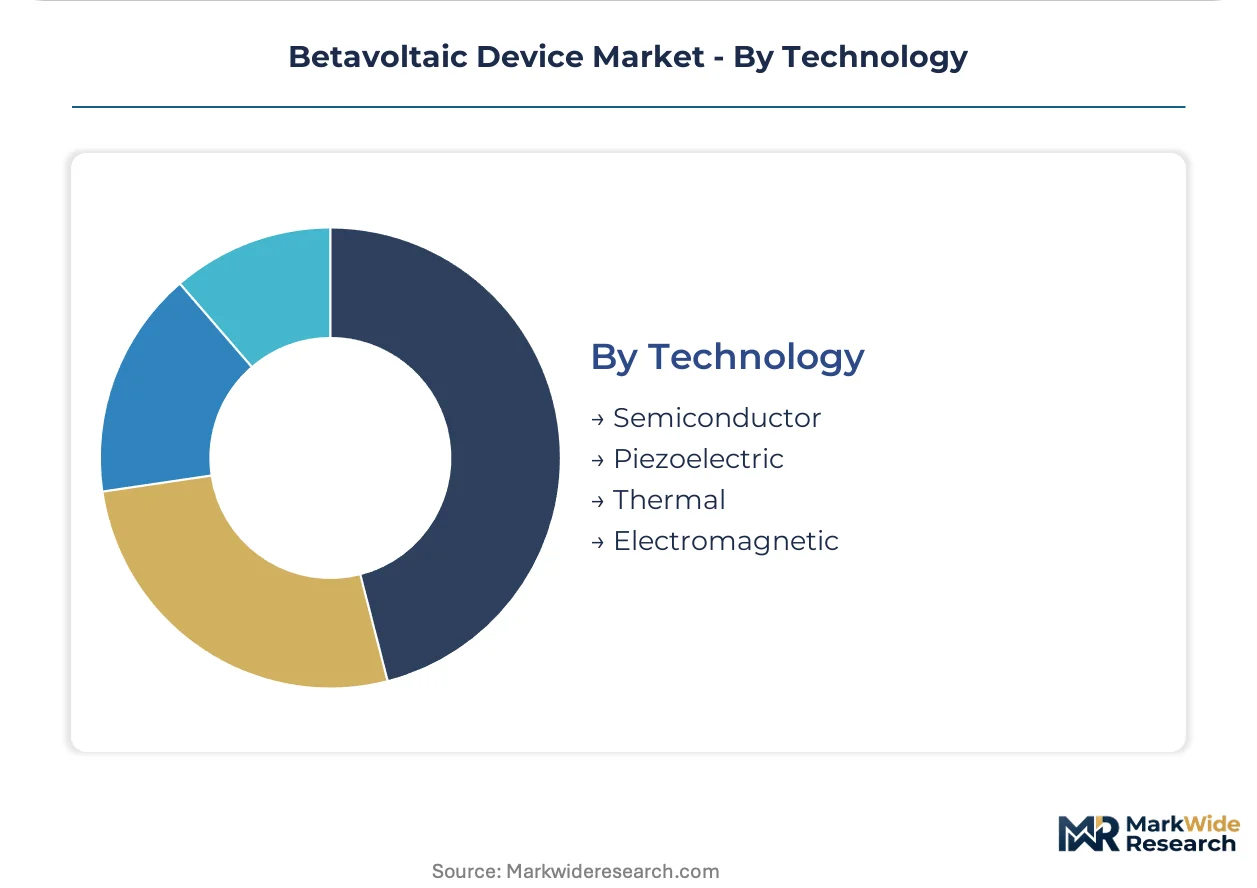
Technology:
Physics-based conversion mechanisms compete on efficiency, radiation hardness, and compatibility with existing semiconductor fabrication infrastructure.
- Semiconductor:Silicon carbide and gallium nitride p-n junctions convert beta particle kinetic energy directly to electrical current through electron-hole pair generation. Widetronix and City Labs have demonstrated 6-25% conversion efficiencies in commercial devices. Foundry partnerships with X-FAB, GlobalFoundries, and Tower Semiconductor enable process portability.
- Thermal:Radioisotope decay heat drives thermoelectric or thermophotovoltaic conversion for higher power output in volume-constrained applications. Underwater sensor networks at extreme depths leverage thermal approaches where pressure vessel design dominates form factor constraints.
- Piezoelectric:Beta particle impact on resonant mechanical structures generates electrical output through strain-induced polarization.
- Electromagnetic:Charged particle deceleration in tuned cavity structures produces RF energy for specialized communication applications.
Semiconductor dominates manufacturing scale. Thermal conversion gains share in extreme-environment deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oak Ridge National Laboratory anchors the world's densest concentration of betavoltaic R&D infrastructure. National isotope production facilities in the United States, Russia, and China control tritium and nickel-63 supply chains. Vendor qualification pathways concentrate in jurisdictions with established radioisotope handling protocols.
United States
Deep-space mission procurement from NASA Jet Propulsion Laboratory and Johns Hopkins Applied Physics Laboratory drives aerospace demand. The US Nuclear Regulatory Commission governs device licensing through 10 CFR Part 30 and 10 CFR Part 70 regulations. Oak Ridge National Laboratory and Savannah River National Laboratory supply tritium feedstock to qualified device manufacturers in the Tennessee-South Carolina corridor.
Russia
State atomic energy corporation Rosatom maintains vertical control over nickel-63 production for defense and space applications. Federal Service for Ecological, Technological and Nuclear Supervision (Rostekhnadzor) licenses sealed radioactive source devices under Federal Law No. 170-FZ. Moscow Institute of Physics and Technology and NUST MISIS anchor academic-commercial partnerships for semiconductor betavoltaic development.
China
China Academy of Engineering Physics directs radioisotope power systems research for lunar and deep-space missions. National Nuclear Safety Administration implements GB 18871-2002 standards for radiation protection and source security. Sichuan province hosts the primary tritium production complex feeding domestic betavoltaic device fabrication.
United Kingdom
UK Space Agency and European Space Agency co-funding supports radioisotope power system feasibility studies for future planetary missions. Office for Nuclear Regulation enforces Ionising Radiations Regulations 2017 for sealed source devices. Culham Centre for Fusion Energy and University of Bristol collaborate on tritium handling infrastructure for next-generation betavoltaic research.
Japan
Japan Aerospace Exploration Agency evaluates betavoltaic alternatives for small satellite and lunar surface power applications. Nuclear Regulation Authority administers the Law for the Regulation of Nuclear Source Material, Nuclear Fuel Material and Reactors. Tsukuba science city and Osaka University cluster semiconductor fabrication expertise for wide-bandgap betavoltaic junction development.
Betavoltaic Device Market Vendor Landscape
Global majors compete with regional champions across radioisotope sourcing agreements and national laboratory partnerships. The vendor base stratifies into three tiers: prime contractors with Department of Energy supply agreements, mid-scale specialists with single-isotope dependencies, and research-stage entrants with unproven fabrication partnerships. Dominant competitive moves include securing exclusive national laboratory isotope allocation contracts and forming foundry partnerships for silicon carbide semiconductor volume production.
Among US-based developers, Widetronix, Inc. and City Labs, Inc. occupy established positions anchored by proprietary semiconductor architectures and NanoTritium battery platforms respectively. BetaBatt, Inc. represents the medical implant specialization archetype. These three entities exemplify how early procurement relationships with Oak Ridge and Savannah River facilities create defensive moats against later entrants lacking comparable isotope supply security.
| Leading Market Players |
|---|
| Widetronix, Inc. |
| NDB, Inc. |
| City Labs, Inc. |
| Elysium Space |
| Alpha Omega |
| BetaBatt, Inc. |
| Qynergy Corporation |
| NUST MISIS |
| Direct Kinetic Solutions |
| Others |
Supply Flow & Price Mechanics
Captive isotope sourcing through Oak Ridge and Savannah River National Laboratory partnerships anchors both supply security and premium pricing power for qualified betavoltaic device manufacturers. This backward integration into tritium feedstock insulates incumbent vendors from spot-market volatility while locking out competitors lacking comparable procurement relationships.
Pricing Analysis
Radioisotope feedstock costs pass through directly to device pricing, with tritium procurement premiums compressing margins for non-integrated manufacturers. Three-tier pricing structure across aerospace-qualified, medical-certified, and industrial-grade levels separates NASA mission-specified systems from FDA-tracked implants and uncertified sensor applications. Pricing pressure stems from lithium-ion cost trajectories in non-extreme sensor markets where twenty-year operational lifespan carries insufficient value premium. Healthcare providers demonstrate lowest price sensitivity given total cost of ownership calculations across implant replacement cycles, while industrial IoT buyers exhibit acute sensitivity to per-unit premiums.
Supply Chain Analysis
Domestic-content mandates in US defense procurement are reshaping sourcing patterns toward Tennessee-South Carolina corridor fabrication facilities. Tritium supply concentrates in United States national laboratories, with secondary nickel-63 production anchored in Russian state atomic facilities and Chinese military-industrial complexes. Semiconductor junction fabrication draws from silicon carbide foundry partnerships with X-FAB and GlobalFoundries, creating single-source vulnerability in wide-bandgap substrate supply. Distribution runs through prime contractor supply chains for aerospace applications and direct hospital system procurement for medical implants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between US regulatory complexity and Russian state-controlled isotope pricing, with NRC licensing timelines extending commercialization cycles beyond venture capital horizons while Rosatom vertical integration enables cost-competitive defense exports.
For Market Incumbents: Deepen exclusive tritium allocation contracts with Oak Ridge and Savannah River facilities to defend against emerging entrants lacking comparable isotope security. Invest in silicon carbide foundry partnerships to scale semiconductor junction production without captive capital expenditure, countering margin pressure from lithium-ion alternatives in price-sensitive industrial segments.
For New Entrants and Emerging Players: Semiconductor foundry partnerships offer the most penetrable entry vector for betavoltaic cell fabrication, bypassing isotope sourcing barriers through tolling arrangements with established vendors. Target European Space Agency feasibility study participants seeking qualified alternative suppliers outside US prime contractor networks, leveraging CE marking pathways as regulatory differentiation.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale specialists with single-isotope dependencies because national laboratory procurement relationships create defensive moats that compound through scale. Monitor FDA premarket approval pathway maturation as inflection indicator for healthcare provider segment expansion, with Cleveland Clinic and Mayo Clinic procurement committee decisions signaling reimbursement viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Isotope Supply Agreement | Oak Ridge National Laboratory tritium allocation locks competitive positioning for aerospace procurement. |
| Silicon Carbide Foundry Partnership | X-FAB and GlobalFoundries collaborations enable volume scaling without dedicated capital investment. |
| FDA Premarket Approval Pathway | Center for Devices and Radiological Health clearance opens twenty-year implantable device procurement channels. |
| ISO 2919 Certification Investment | Sealed radioactive source standards streamline cross-border licensing for qualified vendors. |
| Defense Procurement Channel Expansion | Department of Energy radioisotope power systems program funding broadens beyond space applications. |
Methodological Framework
Multiple input streams — primary interviews with semiconductor fabrication engineers and aerospace procurement officers, secondary validation against NASA technology readiness level documentation and FDA premarket submission databases, and trade data from national isotope production facilities — were reconciled through bottom-up and top-down triangulation. Aerospace prime contractor supply chain managers, hospital biomedical engineering directors, and national laboratory technology transfer officers provided operational perspective. Secondary sources included US Nuclear Regulatory Commission licensing records, ISO certification registries, and Department of Energy procurement disclosures.
Historical deployment patterns across deep-space missions and medical implant approvals were cross-referenced against expert panel assessments of technology readiness progression. Segmentation modeling incorporated product architecture, application environment, end-user procurement sophistication, and conversion mechanism physics. CAGRs were derived from installed base growth projections and replacement cycle analysis. Forecast inputs included radioisotope production capacity expansion timelines and semiconductor foundry utilization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to national laboratory isotope allocation policy shifts and lithium-ion cost curve trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Audio Signaling Devices Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Automated Number Plate Recognition (ANPR) and Detection Sensors Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market
Detection and Regulation Devices
Flooded Member Detection Equipment Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market