
 Spark Detector Market | 2026-2036
Spark Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Spark Detector Market Analytics
Photoelectric sensing fused with thermal imaging is tilting spark detector architecture toward multi-modal platforms that catch incipient ignition across broader spectral bands. Firefly AB leverages its Nordic installed base to dominate wood processing verticals across Northern Europe. Fagus-GreCon Greten GmbH & Co. KG anchors German automotive paint shop deployments with application-specific calibration protocols. Hansentek Corporation competes on cost-optimized infrared arrays for mid-scale Chinese textile dust collection systems.
A spark detector is an active fire prevention instrument that senses incipient combustion particles—typically 0.1 to 5 microns in diameter—via infrared, ultraviolet, or optical beam transduction, then triggers suppression or process shutdown before flame propagation. The device primarily protects pneumatic conveying, dust collection, and material handling infrastructure in combustible dust environments where traditional smoke alarms respond too late. Infrared detectors lead product type revenue due to mature supply chains and broad spectral sensitivity across biomass and metal powder applications, while thermal imaging technology captures the fastest expansion as semiconductor cost curves enable affordable multi-point array deployment. Oil and gas applications concentrate margin pools because offshore platform specifications demand marine-certified housings and redundant sensor architectures that sustain premium pricing.
EU ATEX directives and the F-Gas Regulation shape detector design requirements across European process industries, while OSHA combustible dust emphasis programs and NFPA 654 drive US retrofit cycles in food and chemical processing plants. China's GB standards on dust explosion prevention, enforced by the Ministry of Emergency Management, mandate spark detection on new pneumatic conveying installations above specified throughput thresholds. Stakeholders must weigh sensor modality selection against evolving certification harmonization between EU ATEX and Chinese GB frameworks as export-oriented manufacturers seek single-platform compliance.
Market Dynamics
Multi-sensor fusion architectures are restructuring competitive advantage in spark detection, as vendors race to integrate photoelectric, thermal, and spectral analysis into unified platforms that reduce false positives while expanding detection range across combustible dust environments.
Growth Catalysts
- EU ATEX Directive 1999/92/EC:Mandatory explosion protection documentation for combustible dust operations drives systematic retrofit programs across German automotive paint shops and Scandinavian wood pellet facilities.
- Infrared array miniaturization:Semiconductor cost curves enable affordable deployment of multi-point detection networks in mid-scale Chinese textile dust collection systems previously served by single-sensor units.
- Biomass power expansion:Cement and biomass operators in Germany and China are retrofitting aging pneumatic conveying lines with redundant sensor architectures to satisfy insurer risk engineering requirements.
Market Restraints
- Indium gallium arsenide detector costs:Near-infrared sensing elements face supply concentration from limited epitaxial wafer foundries, creating input cost volatility for thermal imaging arrays.
- Marine certification bottlenecks:Offshore oil and gas platforms require DNV or ABS redundant housing specifications that extend product development cycles and limit supplier pool depth.
- Optical beam maintenance burden:Photoelectric systems suffer alignment drift in high-vibration pneumatic conveying environments, creating lifecycle cost penalties versus solid-state alternatives.
Strategic Opportunities
- India's dust explosion prevention gap:BIS standards adoption lags EU ATEX implementation, creating first-mover positioning for certified suppliers as enforcement tightens in pharmaceutical and food processing clusters.
- AI-driven spectral fingerprinting:Machine learning classification of combustion particle signatures enables predictive maintenance integration with plant SCADA systems, opening industrial IoT revenue streams.
- Service unbundling:Detector-as-a-subscription models separate hardware from calibration and suppression system maintenance, penetrating capital-constrained mid-market processors in Southeast Asia.
Industry Challenges
- ATEX-GB harmonization gaps:Divergent certification testing protocols between European notified bodies and China's MEE-authorized laboratories force dual-platform engineering for export-oriented manufacturers.
- Legacy pneumatic integration:Brownfield installations require custom mounting fabrication and signal conditioning to interface 1980s-era conveying controls with modern digital detection outputs.
- Suppressant chemical compatibility:Water mist, inert gas, and chemical powder suppression systems demand application-specific detector response calibration that stretches technical service bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spark Detector Market |
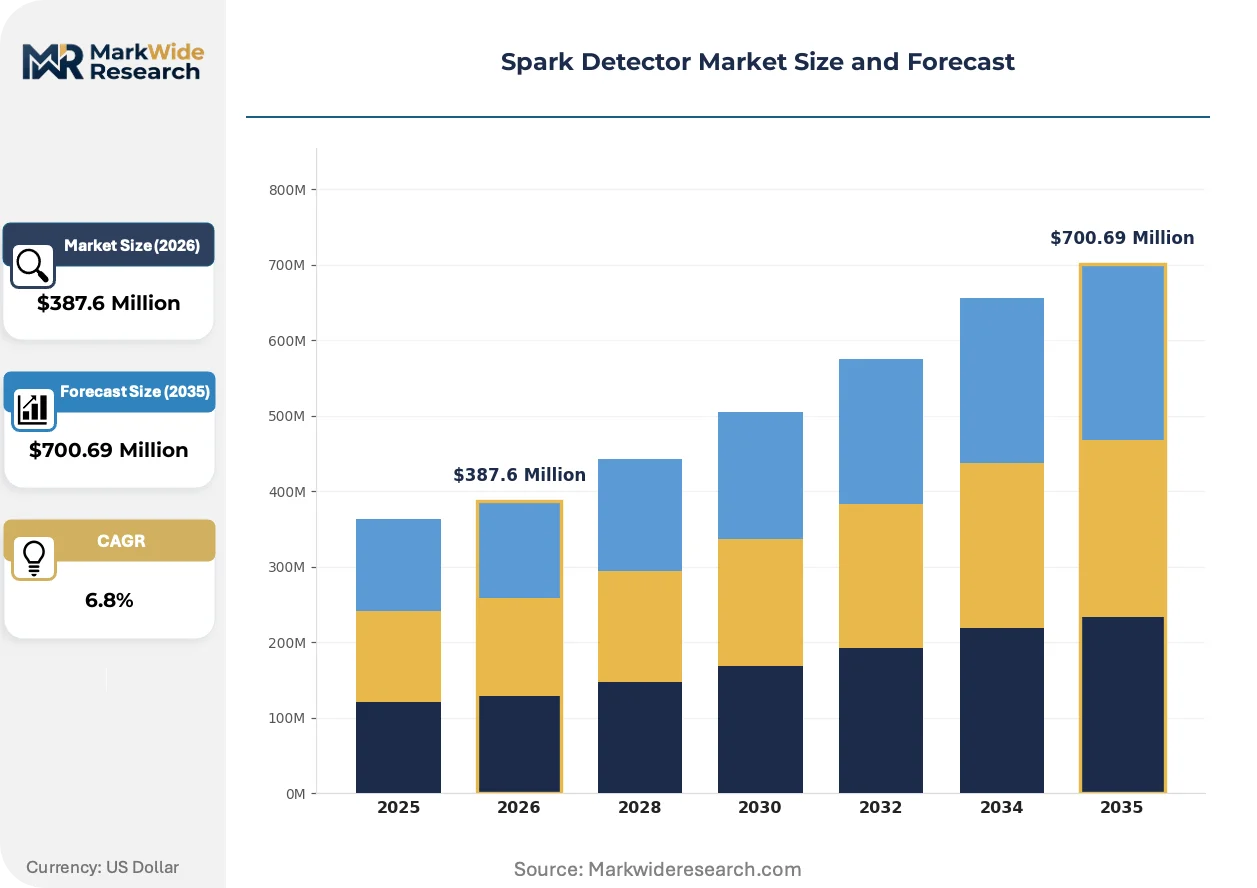
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Detectors, Smoke Detectors, Flame Detectors, Optical Beam Detectors Application: Industrial Manufacturing, Oil & Gas, Automotive, Power Generation End User: Manufacturers, Utilities, Transportation, Laboratories Technology: Laser-based, Ultrasonic, Photoelectric, Thermal Imaging |
| Companies Covered | Firefly AB, Flamex Inc., Fagus-GreCon Greten GmbH & Co. KG, Minimax GmbH, Argus Fire Control, BS&B Safety Systems LLC, Control Logic, IEP Technologies LLC, Hansentek Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spark Detector Market Evolving Landscape
Detection modality convergence is compressing product category boundaries, as single-technology vendors face displacement from integrated platform suppliers capable of spectral band fusion and unified suppression triggering.
Multi-spectral sensor fusion is collapsing the distinction between infrared point detectors and thermal imaging arrays. Wood processing facilities in Finland and Sweden now deploy unified platforms combining photoelectric spark sensing with thermal anomaly mapping, eliminating redundant wiring infrastructure while expanding coverage per installed unit. This convergence is collapsing price premiums historically commanded by standalone thermal imaging systems.
China's GB 15577-2018 dust explosion prevention standard, enforced by the Ministry of Emergency Management, mandates spark detection on new pneumatic conveying installations above specified throughput thresholds. Domestic cement and biomass power operators are accelerating procurement to avoid permitting delays, compressing supplier qualification timelines and favoring vendors with pre-certified GB-compliant product lines. The regulation is reshaping competitive positioning among European and Chinese detector manufacturers.
Buyers are unbundling hardware procurement from lifecycle service contracts, separating detector supply from suppression system maintenance and calibration scheduling. Large food and chemical processors in the United States now contract detection hardware through capital budgets while outsourcing ongoing service to specialized fire protection integrators. This bifurcation is most visible in OSHA-targeted facilities under combustible dust emphasis program scrutiny, where compliance documentation requirements favor third-party service specialization.
Spark Detector Market Segmentation
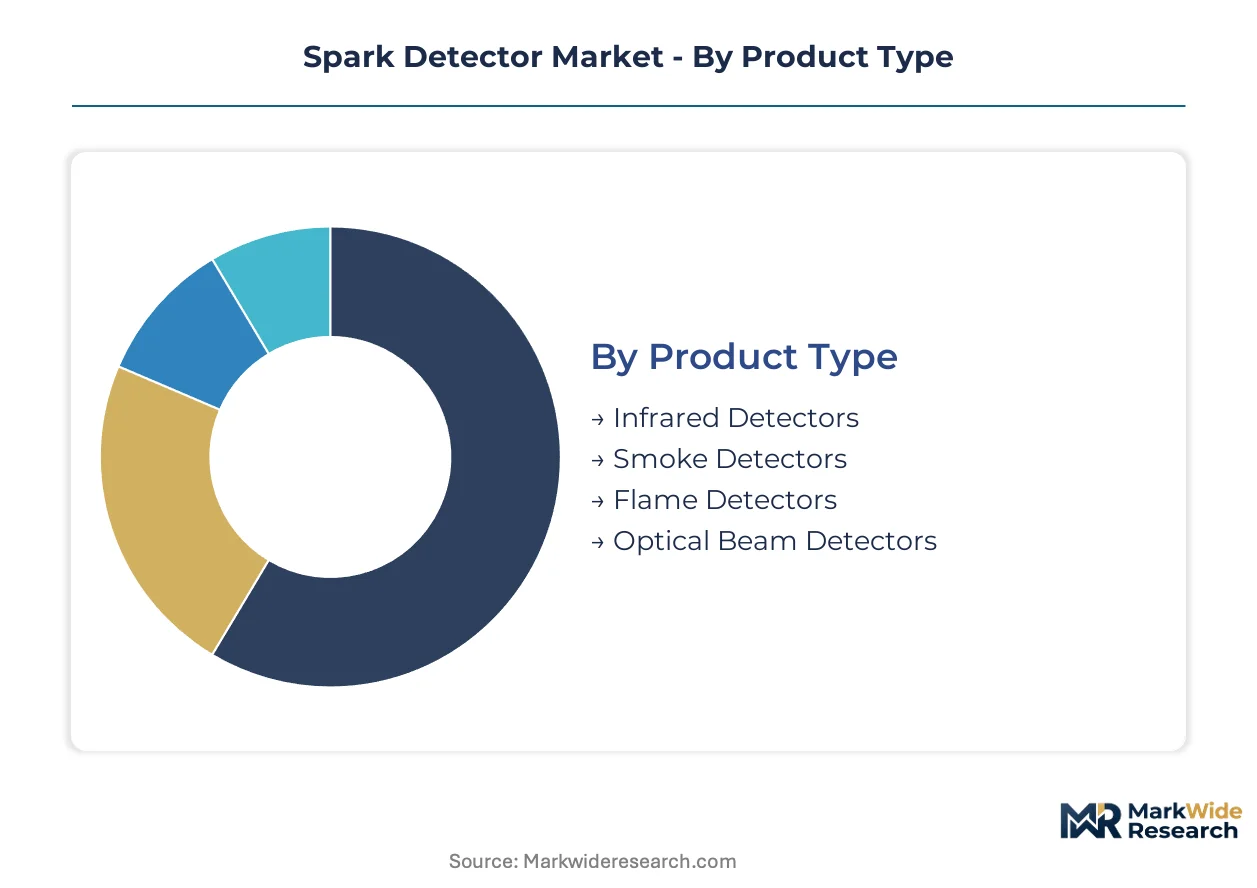
Segmentation in spark detection reveals divergent service intensity profiles across product architectures. Infrared arrays demand frequent recalibration in high-dust biomass environments, while thermal imaging platforms shift revenue toward predictive maintenance subscriptions.
Product Type:
After-sales service intensity varies sharply across detector modalities, with multi-sensor platforms requiring specialized technician networks that reshape vendor profitability models.
- Infrared Detectors:These devices sense incipient combustion particles via spectral absorption across 0.7 to 14 micron wavelengths, leveraging mature semiconductor supply chains. Scandinavian wood pellet processors specify these for EU ATEX compliance, though indium gallium arsenide detector costs create input volatility for manufacturers.
- Thermal Imaging:Semiconductor cost curves now enable affordable multi-point array deployment. German automotive paint shops and Chinese cement operators retrofit aging pneumatic conveying lines with these systems to satisfy insurer risk engineering requirements.
- Smoke Detectors:Traditional ionization and photoelectric units serve as secondary protection layers in dust collection facilities where primary spark detection triggers suppression.
- Flame Detectors:Ultraviolet and infrared flame sensors provide final-line defense in oil and gas processing where marine-certified redundant architectures sustain premium pricing tiers.
- Optical Beam Detectors:These systems suffer alignment drift in high-vibration pneumatic conveying environments, creating lifecycle cost penalties that favor solid-state alternatives in heavy industrial settings.
Infrared detectors hold the largest share; momentum sits with thermal imaging arrays as unit economics improve.
Application:
Application segmentation tracks combustible dust concentration and regulatory enforcement intensity across process industries.
- Industrial Manufacturing:Food and chemical processing plants under OSHA combustible dust emphasis programs drive US retrofit cycles. Third-party service specialization now dominates calibration and documentation compliance.
- Oil & Gas:Offshore platforms require DNV or ABS redundant housing specifications that extend product development cycles. Marine certification bottlenecks limit supplier pool depth despite concentrated margin pools.
- Automotive:German paint shop deployments anchor application-specific calibration protocols for solvent vapor and coating dust environments.
- Power Generation:Biomass power expansion in Germany and China accelerates procurement for pneumatic conveying protection, compressing supplier qualification timelines.
Industrial manufacturing generates the highest installed base; oil and gas commands the steepest expansion trajectory due to marine certification premiums.
End User:
End user segmentation reflects capital availability and in-house technical capacity for suppression system integration.
- Manufacturers:Large food and chemical processors unbundle hardware procurement from lifecycle service contracts, outsourcing ongoing service to specialized fire protection integrators.
- Utilities:Cement and biomass power operators in China face GB 15577-2018 mandates that accelerate procurement to avoid permitting delays.
- Transportation:Rail and maritime bulk handling facilities deploy spark detection for grain and coal dust protection in loading operations.
- Laboratories:Pharmaceutical and fine chemical R&D facilities require specialized detection for pyrophoric material handling with custom suppression response protocols.
Manufacturers dominate procurement volume; utilities are gaining share fastest as Chinese enforcement tightens.
Technology:
Technology segmentation tracks the convergence of detection modalities toward unified multi-sensor platforms.
- Laser-based:These systems project coherent light beams across conveying ducts, measuring particulate scattering to identify incipient ignition signatures with minimal false positives.
- Ultrasonic:Acoustic detection methods identify pressure wave anomalies from pre-combustion events, serving as complementary layers in high-value processing trains.
- Photoelectric:Light scattering detection remains cost-effective for standard dust collection systems, though alignment maintenance burdens favor solid-state alternatives in vibration-heavy environments.
- Thermal Imaging:Multi-point temperature mapping enables predictive maintenance integration with plant SCADA systems, opening industrial IoT revenue streams for detector vendors.
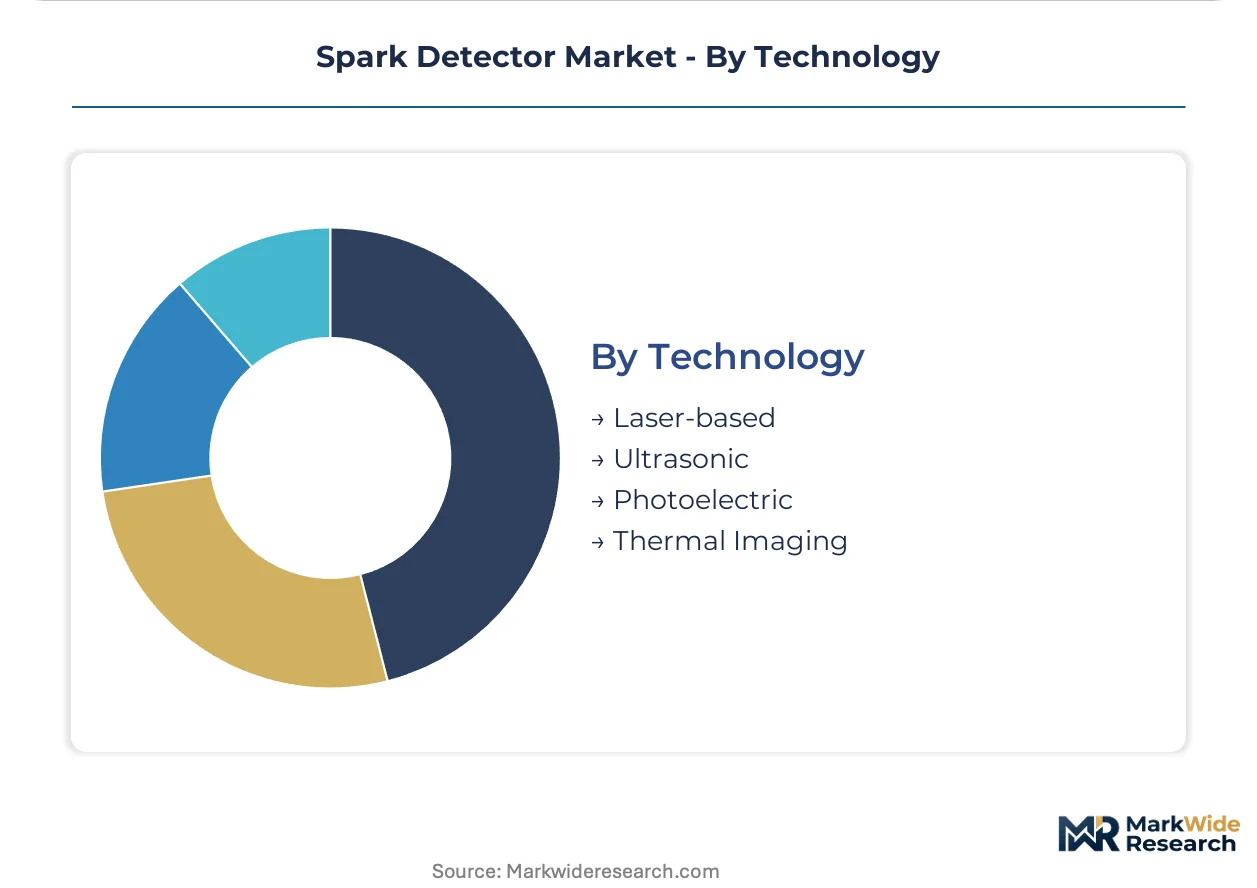
Photoelectric technology retains the broadest installed base; thermal imaging climbs the fastest as semiconductor costs enable affordable array deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers cluster around regulatory enforcement zones and high-concentration dust processing corridors. Cement, biomass, and wood pellet operators drive procurement intensity across distinct national enforcement calendars.
United States
OSHA combustible dust emphasis programs drive retrofit cycles in food and chemical processing corridors. Large processors now unbundle hardware procurement from third-party service contracts for compliance documentation. Gulf Coast petrochemical clusters and Midwest grain handling facilities anchor demand concentration.
Germany
Automotive paint shops and cement operators anchor EU ATEX-driven procurement intensity. The F-Gas Regulation shapes detector housing specifications for solvent vapor environments. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate retrofit activity on aging pneumatic conveying infrastructure.
China
GB 15577-2018 mandates from the Ministry of Emergency Management compress supplier qualification timelines for cement and biomass power operators. Yangtze River Delta and Shandong Peninsula industrial zones accelerate procurement to avoid permitting delays on new pneumatic conveying installations.
Sweden
Wood pellet processing facilities across Nordic forestry corridors expand infrared spark detection installations for EU ATEX compliance. Firefly AB leverages its regional installed base to dominate vertical-specific deployments. Västra Götaland and Norrland biomass clusters lead installation velocity.
India
BIS standards adoption lags EU implementation, creating positioning windows for certified suppliers as pharmaceutical and food processing enforcement tightens. Maharashtra and Gujarat industrial corridors show early procurement signals from dust explosion prevention upgrades in bulk handling operations.
Spark Detector Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented national enforcement windows. The vendor base separates into three strategic archetypes: Nordic wood-processing specialists, German automotive-industrial integrators, and Chinese cost-optimized fabricators. Dominant competitive moves include application-specific calibration protocol development and regional certification pre-positioning ahead of enforcement calendar shifts.
Within the Nordic specialist tier, Firefly AB exemplifies vertical-anchored positioning through concentrated wood processing deployments. German GmbH-structured entities including Fagus-GreCon Greten GmbH & Co. KG and Minimax GmbH occupy the industrial-automotive integration corridor with ATEX-compliant platform development. Hansentek Corporation represents the Asia-Pacific cost-optimization archetype serving mid-scale textile and cement dust collection retrofit cycles.
| Leading Market Players |
|---|
| Firefly AB |
| Flamex Inc. |
| Fagus-GreCon Greten GmbH & Co. KG |
| Minimax GmbH |
| Argus Fire Control |
| BS&B Safety Systems LLC |
| Control Logic |
| IEP Technologies LLC |
| Hansentek Corporation |
| Others |
Value Network & Pricing Analysis
Indium gallium arsenide epitaxial wafer foundries in Japan and the United States concentrate supply for near-infrared sensing elements, anchoring margin pools in thermal imaging arrays downstream while creating input cost volatility that propagates through detector manufacturer pricing strategies.
Pricing Analysis
Cost-plus contracts with indium gallium arsenide indexation dominate procurement between detector manufacturers and semiconductor foundries. Three-tier pricing structure across premium, standard, and economy levels separates marine-certified redundant architectures from single-sensor units, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in mid-scale textile and cement retrofit segments is intensifying because Hansentek Corporation and domestic Chinese fabricators compete on infrared array unit economics. Mid-scale biomass processors in Southeast Asia show highest price sensitivity, while offshore oil and gas operators demonstrate lowest sensitivity due to insurer-mandated specification compliance.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for detector manufacturers serving dual-certification markets. Component sourcing draws from Japan for indium gallium arsenide wafers, Germany for precision optical housings, and China for cost-optimized infrared emitter assemblies. Single-source vulnerability concentrates in epitaxial wafer foundries serving thermal imaging array production. Distribution runs through specialized fire protection integrators in developed markets and direct OEM relationships in capital-constrained regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as EU ATEX enforcement spreads beyond automotive and wood processing into pharmaceutical and food handling corridors, with penetration rates in pneumatic conveying retrofits still below saturation thresholds across multiple industrial clusters.
For Market Incumbents: Pre-empt displacement from multi-sensor fusion platforms by embedding photoelectric and thermal capabilities in unified architectures before pure-play thermal imaging vendors achieve scale. Backward integration into indium gallium arsenide supply relationships mitigates input cost volatility from Japanese wafer foundries. Certification investment in simultaneous GB and ATEX compliance preserves positioning for export-oriented Chinese manufacturing demand.
For New Entrants and Emerging Players: Pursue India's pharmaceutical and food processing clusters where BIS standards adoption lags EU implementation and enforcement timelines create first-mover windows. Application-specific calibration protocols for solvent vapor environments in automotive paint shops represent the most penetrable segment given incumbent concentration in standardized biomass and cement deployments. Channel partnership with fire protection integrators offers lower customer acquisition cost than direct OEM sales.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platform suppliers with captive semiconductor sourcing and pre-positioned dual-certification portfolios. Long-term viability over a multi-year horizon rests on convergence toward multi-modal detection architectures that collapse category boundaries. The signal to watch is GB 15577-2018 enforcement intensity in Yangtze River Delta permitting offices as a proxy for Chinese demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Platform Integration | Firefly AB and Fagus-GreCon consolidate photoelectric and thermal capabilities to displace single-technology vendors. |
| Dual-Certification Pre-Positioning | European manufacturers engineer simultaneous ATEX and GB compliance to capture Chinese cement and biomass procurement. |
| Indium Gallium Arsenide Supply Security | Detector fabricators negotiate long-term wafer offtake with Japanese foundries to hedge input cost volatility. |
| Detector-as-a-Subscription Launch | Vendors unbundle hardware from calibration service to penetrate capital-constrained Southeast Asian processors. |
| AI-Driven Spectral Fingerprinting | Machine learning classification enables predictive maintenance integration with plant SCADA systems. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at wood pellet and cement facilities, fire protection integrators, aftermarket service heads, and procurement leads at pneumatic conveying OEMs, and refined through secondary validation of EU ATEX directive implementation timelines, Chinese Ministry of Emergency Management enforcement bulletins, OSHA combustible dust emphasis program targeting patterns, and SEC filings from listed industrial safety equipment manufacturers. Bottom-up unit deployment estimates triangulated against top-down addressable infrastructure calculations.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by detector modality, application vertical, end-user capital availability tier, and regional regulatory enforcement intensity. CAGRs were derived from installed base growth rates and replacement cycle assumptions, incorporating biomass power expansion trajectories in Germany and China, marine certification bottlenecks limiting oil and gas supplier pool depth, and infrared array miniaturization cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese cost-optimized fabricators or rapid indium gallium arsenide supply disruption would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Hitoxic Gas Detector Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Infrared Detector Market