
 Underwater Signaling Devices Market | 2026-2036
Underwater Signaling Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Signaling Devices Market Analytics
Modular beacon-to-sonar bundling is restructuring procurement patterns for defense and commercial fleets alike. Kongsberg Maritime leverages its integrated subsea platform architecture to anchor long-term service contracts. L3Harris Technologies, Inc. competes through classified program relationships and signal-processing specialization. Teledyne Marine Technologies Incorporated extends its position across research and military channels with sensor-agnostic system designs.
Underwater signaling devices are electromechanical or pyrotechnic instruments engineered to transmit acoustic, optical, or electromagnetic signals through water columns, typically operating at depths exceeding 100 meters with pressure ratings up to 6,000 psi for full-ocean applications. These instruments serve critical functions in submarine communications, diver safety, asset tracking, and maritime domain awareness where radio frequencies attenuate rapidly. Acoustic beacons dominate installed base value owing to proven reliability in turbid conditions and deep-water pressure environments. Electronic devices incorporating sonar technology represent the fastest-expanding margin pool as digital signal processing enables multi-mode encoding and encryption. Visual signals and signal flares retain niche positions in shallow-water commercial diving and emergency protocols where simplicity overrides performance.
The International Maritime Organization's SOLAS conventions mandate carriage of approved signaling equipment, while NATO STANAG standards govern interoperability for military acoustic systems. The U.S. Navy's Undersea Warfare Directorate shapes procurement specifications through its Technical Authority process, effectively filtering market access for non-compliant suppliers. Stakeholders must monitor evolving encryption requirements and dual-use export control classifications as geopolitical competition intensifies in contested littoral zones.
Market Dynamics
Encrypted acoustic signaling systems are restructuring defense procurement as NATO interoperability mandates force fleet-wide equipment upgrades, compressing supplier qualification timelines and tilting contract awards toward integrated platform providers with established security clearances.
Growth Catalysts
- NATO STANAG Standardization:Military acoustic interoperability requirements across member states are mandating encrypted multi-mode systems, forcing replacement cycles for legacy unencrypted equipment.
- Offshore Energy Expansion:Deepwater oil and gas development in the Gulf of Mexico and North Sea is driving demand for asset tracking beacons rated to 6,000 psi operating pressures.
- SOLAS Convention Compliance:The International Maritime Organization's updated carriage requirements for emergency signaling equipment are compelling commercial fleet operators to modernize bridge-mounted pyrotechnic inventories.
Market Restraints
- Pressure-Tolerant Component Costs:Titanium alloy housings and sapphire acoustic windows constitute 40% of bill-of-materials costs, exposing margins to commodity price volatility.
- Dual-Use Export Controls:U.S. International Traffic in Arms Regulations and EU dual-use classifications create licensing friction for acoustic modems with encryption capabilities.
- Radio Frequency Substitution Limits:Underwater optical communication systems remain confined to clear-water deployments, preventing displacement of acoustic signaling in turbid littoral zones.
Strategic Opportunities
- Unmanned Underwater Vehicle Integration:Swarming autonomous platforms require mesh-network acoustic modems, opening design wins for low-power, high-data-rate signaling modules.
- Research Vessel Modernization:Academic and governmental oceanographic fleets in Norway, Japan, and Australia are retrofitting with sensor-agnostic beacon systems supporting multi-institutional data sharing.
- Green Shipping Incentives:EU Emissions Trading System compliance pathways reward fleets with digitalized safety equipment enabling route optimization and reduced standby times.
Industry Challenges
- Hydroacoustic Engineering Talent Scarcity:Specialized signal processing expertise for multipath propagation environments concentrates within defense contractors and national laboratories, constraining supplier scaling.
- Legacy System Integration Complexity:Analog beacon architectures aboard aging submarine fleets resist digital retrofit without hull-penetrating cable pulls, extending procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Signaling Devices Market |
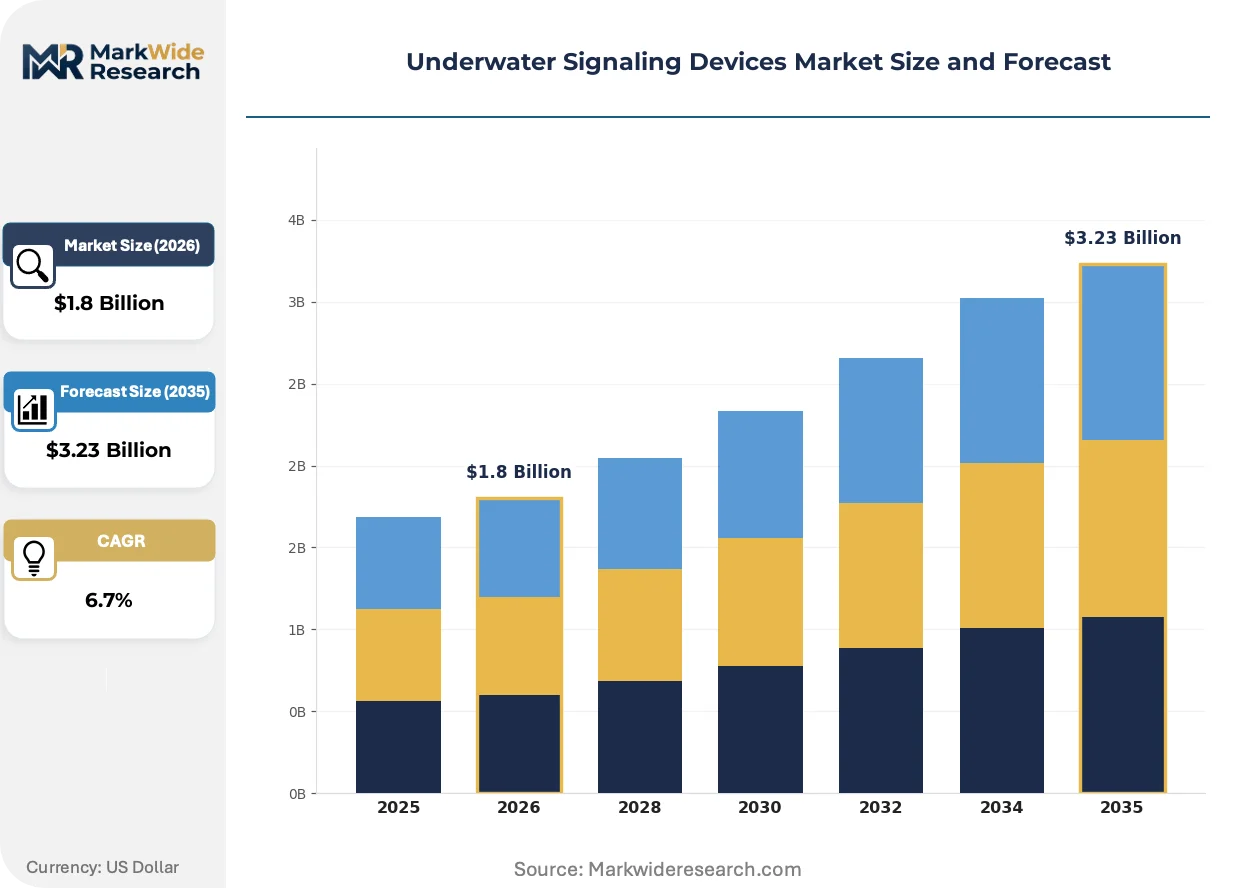
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Beacons, Visual Signals, Electronic Devices, Signal Flares End User: Marine Research, Military Applications, Commercial Diving, Search & Rescue Technology: Sonar Technology, Signal Transmission, LED Lighting, Radio Communication Application: Underwater Navigation, Emergency Signaling, Fishery Management, Aquaculture |
| Companies Covered | Kongsberg Maritime, L3Harris Technologies, Inc., Thales, Saab AB, Teledyne Marine Technologies Incorporated, Ultra Electronics, Sonardyne, EvoLogics GmbH, DSPComm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Signaling Devices Market Evolving Landscape
Digital signal processing architectures are compressing the functional boundary between navigation beacons and tactical sonar systems, enabling procurement consolidation and reshaping long-term service contracting structures.
Software-defined acoustic modems is unifying transmission, reception, and encryption functions on reprogrammable FPGA platforms. Naval procurement offices in the United States and United Kingdom are specifying these architectures for next-generation submarine communications programs. This convergence is unifying previously separate beacon and sonar supplier categories into single-source platform contracts.
REACH substance restrictions on lead-based piezoelectric materials are compelling ceramic formulation changes across European-manufactured transducers. Industrial consequences include accelerated qualification timelines for barium titanate alternatives and supply chain requalification costs passed through to defense primes. Hydrophone arrays for research applications face the most acute reformulation pressure given their high channel counts.
Fleet operators are unbundling hardware procurement from lifecycle maintenance, separating capital expenditure approvals from technical refresh obligations. Channel partners with regional depot capabilities are displacing direct OEM relationships in the commercial diving segment. This pattern is most pronounced in Southeast Asian markets where local content requirements favor joint-venture service entities.
Underwater Signaling Devices Market Segmentation
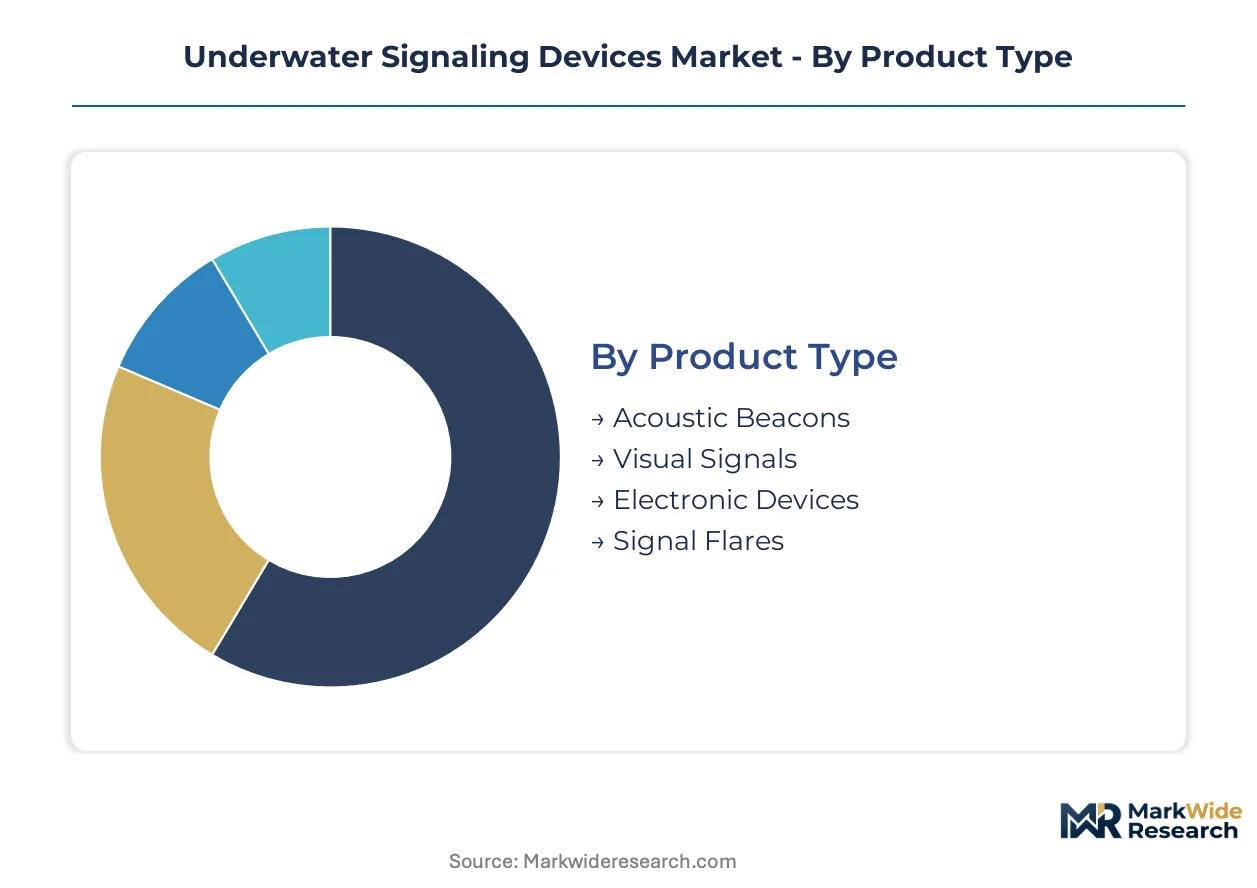
Segmentation in underwater signaling devices reveals divergent capital requirements and procurement cycles across defense, commercial, and scientific channels. Equipment specifications vary dramatically by operating depth, encryption standards, and platform integration complexity.
Product Type:
Capital intensity clusters heavily around pressure-rated electronic systems, while pyrotechnic and visual alternatives require minimal upfront tooling investment.
- Acoustic Beacons:Titanium-housed transducers with sapphire acoustic windows dominate installed base value. NATO fleet modernization programs in Norway and the United Kingdom are mandating encrypted multi-mode replacements for legacy unencrypted units.
- Electronic Devices:FPGA-based software-defined modems unify transmission, reception, and encryption on reprogrammable platforms. The U.S. Navy's Technical Authority process filters market access toward suppliers with established security clearances and integrated platform capabilities.
- Visual Signals:Strobe and chemical light systems serve shallow-water commercial diving operations where simplicity overrides performance requirements.
- Signal Flares:Pyrotechnic bridge-mounted inventories face SOLAS-mandated replacement cycles across commercial fleets operating in the Gulf of Mexico and North Sea.
Acoustic beacons absorb the bulk of installed capacity; electronic devices are expanding most quickly.
End User:
Procurement authority concentrates within defense acquisition offices, while commercial segments fragment across fleet operators and diving contractors.
- Military Applications:Classified program relationships and signal-processing specialization determine contract awards. Encrypted acoustic interoperability requirements across NATO member states compress supplier qualification timelines.
- Commercial Diving:Regional depot capabilities in Southeast Asia are displacing direct OEM relationships as fleet operators unbundle hardware procurement from lifecycle maintenance.
- Marine Research:Academic and governmental oceanographic fleets in Japan and Australia retrofit with sensor-agnostic beacon systems supporting multi-institutional data sharing.
- Search & Rescue:Coast guard organizations prioritize equipment standardization for interoperability during multinational emergency response operations.
Military applications command the largest contract values; commercial diving generates the highest transaction frequency.
Technology:
Digital architectures are compressing the functional boundary between discrete signaling and full sonar systems, reshaping supplier categories.
- Sonar Technology:Digital signal processing enables multi-mode encoding and encryption for submarine communications. REACH substance restrictions on lead-based piezoelectric materials compel ceramic formulation changes across European-manufactured transducers.
- Signal Transmission:Mesh-network acoustic modems for swarming autonomous platforms require low-power, high-data-rate engineering.
- LED Lighting:Solid-state optical systems remain confined to clear-water deployments, preventing displacement of acoustic methods in turbid littoral zones.
- Radio Communication:Surface-only applications supplement underwater systems where electromagnetic propagation fails.
Sonar technology anchors defense procurement budgets; signal transmission modules for unmanned platforms are climbing the fastest.
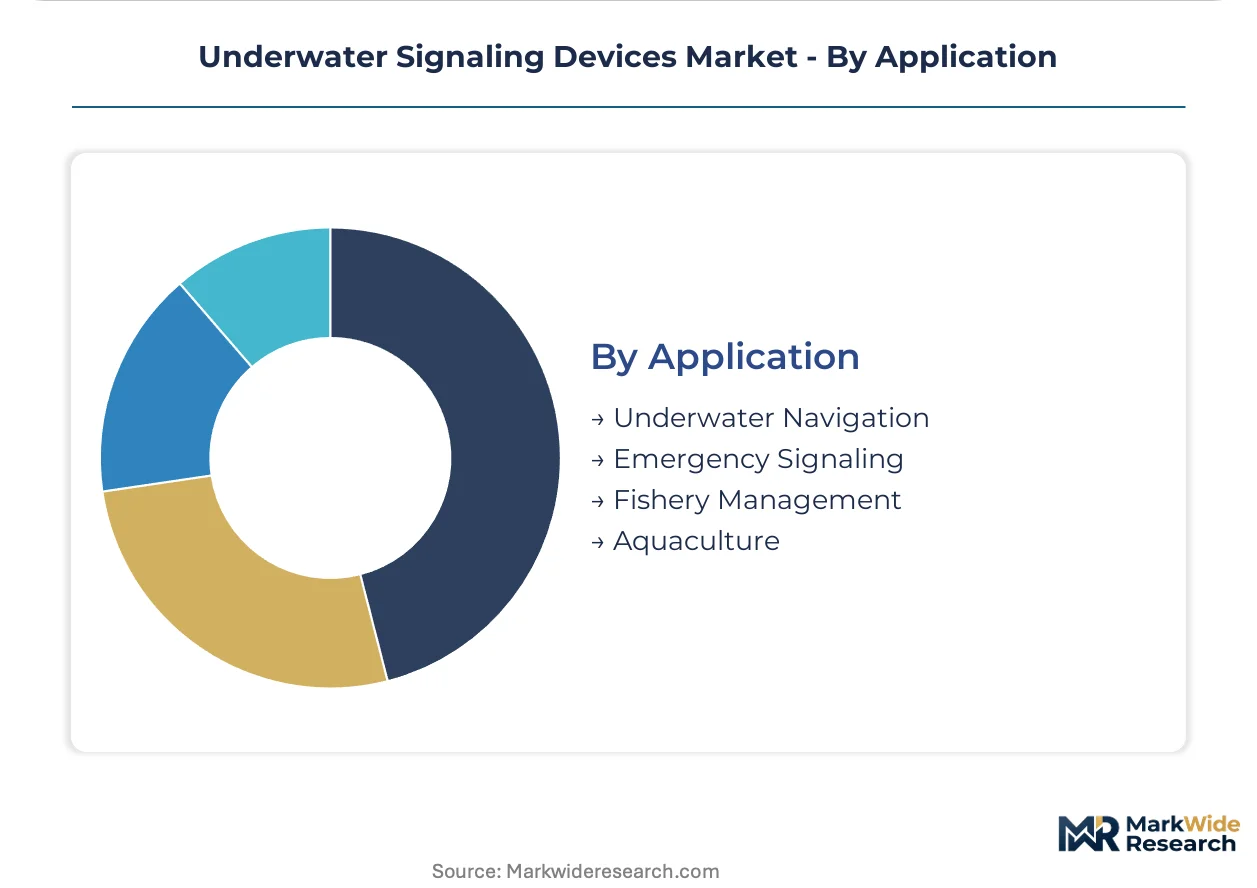
Application:
Regulatory mandates drive replacement cycles in emergency and navigation segments, while fishery and aquaculture applications follow commercial investment patterns.
- Underwater Navigation:Asset tracking beacons rated to 6,000 psi support deepwater oil and gas development. Offshore operators in the Gulf of Mexico specify pressure-tolerant components exposed to commodity price volatility.
- Emergency Signaling:SOLAS convention carriage requirements compel commercial fleet operators to modernize bridge-mounted equipment inventories.
- Fishery Management:Acoustic telemetry tracks stock migration patterns for regulatory compliance and quota enforcement.
- Aquaculture:Subsea monitoring systems in Norwegian fjords optimize feeding schedules and predator detection for salmon farming operations.
Underwater navigation captures the deepest operating pressures; emergency signaling faces the most rigid regulatory replacement schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of pressure-rated transducers clusters in Norway and the United Kingdom, while procurement volumes concentrate in the United States and Gulf of Mexico offshore operators. Consumption patterns diverge sharply between NATO defense modernization programs and commercial fleet safety mandates.
United States
Naval modernization programs through the Undersea Warfare Directorate drive encrypted acoustic system procurement. The Department of Defense filters market access via security clearance requirements and Technical Authority specifications. Defense contractors in Virginia and California anchor submarine communications integration programs.
Norway
Deepwater oil and gas development in the North Sea generates demand for asset tracking beacons rated to extreme operating pressures. REACH substance restrictions on lead-based piezoelectric materials compel ceramic reformulation across transducer manufacturers. Kongsberg-based suppliers leverage integrated subsea platform architectures for long-term service contracts.
United Kingdom
NATO STANAG interoperability mandates force fleet-wide equipment upgrades across Royal Navy surface and submarine fleets. The Ministry of Defence compresses supplier qualification timelines toward established security-cleared contractors. Southampton and Plymouth harbor defense industrial clusters specializing in sonar signal processing.
Japan
Academic and governmental oceanographic fleets retrofit with sensor-agnostic beacon systems supporting multi-institutional research data sharing. METI standards govern domestic equipment certification for deep-sea research vessels. Yokohama and Kobe maritime technology clusters concentrate hydrophone array manufacturing for scientific applications.
Australia
Coast guard organizations prioritize equipment standardization for multinational emergency response interoperability in the Indo-Pacific. The Australian Maritime Safety Authority enforces SOLAS convention carriage requirements for commercial fleet operators. Perth and Sydney defense technology corridors host acoustic modem integration facilities for autonomous underwater vehicle programs.
Underwater Signaling Devices Market Competitive Landscape
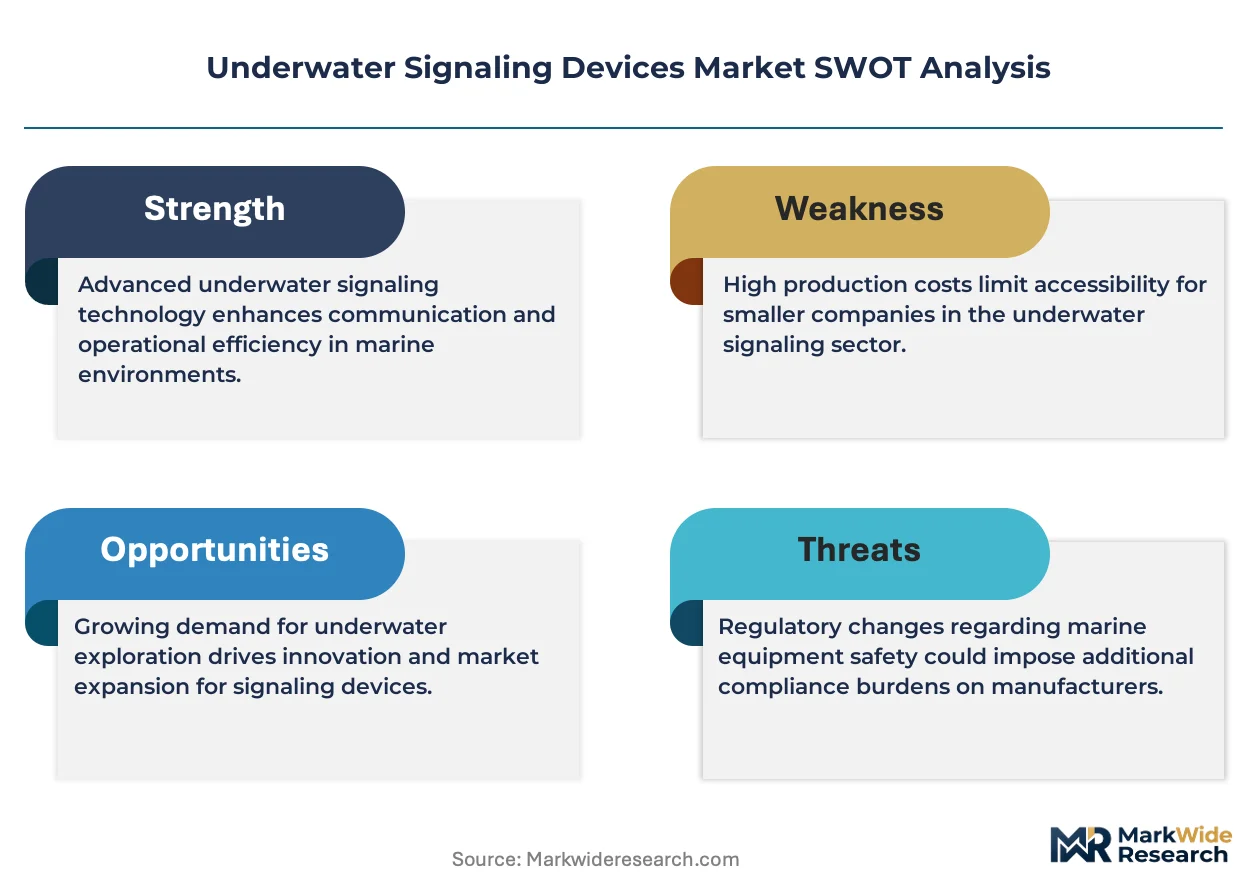
The competitive structure tilts toward integrated platform providers with established defense security clearances. Supplier categories that previously separated beacon manufacturers from sonar specialists are compressing under software-defined architecture procurement. Two archetypes dominate: full-stack subsea platform builders and signal-processing specialists with classified program relationships. Consolidation pressures favor M&A toward integrated capabilities and strategic partnerships for regional service depot networks.
Among Norwegian and UK-based integrated platform providers, Kongsberg Maritime and Sonardyne occupy positions exemplifying the full-stack archetype through bundled beacon-to-sonar offerings. L3Harris Technologies, Inc. represents the specialization vector, anchoring the signal-processing tier through defense program relationships. Teledyne Marine Technologies Incorporated sits within the sensor-agnostic design category, extending across research and military procurement channels.
| Leading Market Players |
|---|
| Kongsberg Maritime |
| L3Harris Technologies, Inc. |
| Thales |
| Saab AB |
| Teledyne Marine Technologies Incorporated |
| Ultra Electronics |
| Sonardyne |
| EvoLogics GmbH |
| DSPComm |
| Others |
Value Network & Pricing Analysis
Titanium alloy ingots and sapphire boules flow from specialized metallurgical suppliers through three distinct pricing tiers before reaching defense primes and commercial fleet operators. REACH substance restrictions on lead-based piezoelectric ceramics in Europe compound input cost volatility, forcing ceramic reformulation expenses that transmit downstream as tiered equipment premiums.
Pricing Analysis
Margin tightening in commercial diving equipment traces to unbundled hardware procurement patterns that separate capital expenditure from lifecycle maintenance obligations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with NATO STANAG-compliant encrypted systems commanding the highest tier. Cost-down pressure on sensor-agnostic research equipment accelerates because academic fleets prioritize interoperability over performance specifications. Commercial diving contractors in Southeast Asia exhibit the greatest price sensitivity, while classified military programs demonstrate the least.
Supply Chain Analysis
Direct-to-OEM channels handle defense procurement volumes, while regional depot partnerships serve commercial fleet maintenance demand. Manufacturing of pressure-rated transducers concentrates in Norway, the United Kingdom, and Japan, with titanium alloy housings and sapphire acoustic windows drawing from aerospace and optical component suppliers. Single-source vulnerability in piezoelectric ceramic formulation creates exposure to REACH regulatory revisions. Distribution runs through integrated platform providers with established security clearances for military segments, and through joint-venture service entities for commercial markets with local content requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform providers as software-defined architectures compress supplier categories and compress qualification timelines for non-compliant vendors.
For Market Incumbents: Deepen backward integration into titanium alloy machining and sapphire window fabrication to insulate margins from commodity volatility. Expand regional depot networks in Southeast Asia to capture unbundled commercial maintenance contracts before channel partners solidify positions. Signal-processing specialization and classified program relationships remain the primary defensive moat against sensor-agnostic entrants. For New Entrants and Emerging Players: Digital-channel routes through academic research consortia offer the most penetrable entry path, as sensor-agnostic beacon systems face lower security clearance barriers than defense programs. Target fishery management and aquaculture monitoring applications in Norwegian fjords and North Sea operations, where regulatory compliance requirements are less stringent than NATO STANAG mandates. Pursue software-defined modem design wins for unmanned underwater vehicle mesh networks as the primary go-to-market angle. For Investors and Strategic Acquirers: NATO member state procurement announcements for encrypted acoustic interoperability upgrades are the leading indicator that consolidation momentum is accelerating. The five-to-ten year viability window favors acquisition targets with established Technical Authority relationships and FPGA-based platform architectures. Watch for Ministry of Defence compressed qualification timelines as the specific signal that integrated platform providers are pulling ahead of specialized component suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies beacon and sonar procurement under single-source contracts with NATO fleets. |
| Regional Depot Expansion | Captures unbundled lifecycle maintenance from Southeast Asian commercial diving operators. |
| Software-Defined Modem Development | Enables reprogrammable encryption for U.S. Navy submarine communications programs. |
| Backward Integration into Titanium Alloys | Reduces exposure to aerospace commodity price volatility for pressure housings. |
| Joint Venture for Local Content Compliance | Satisfies ASEAN fleet operator requirements for regional service presence. |
Research Methodology
Multi-period observation of NATO procurement announcements, SOLAS compliance deadlines, and REACH regulatory revisions anchored the trend analysis, supplemented by interviews with defense acquisition officers, commercial fleet operations managers, hydroacoustic engineering directors, and regional channel partners. Secondary validation drew from U.S. Navy Technical Authority specifications, International Maritime Organization convention updates, customs trade data for titanium alloy imports, and SEC filings from listed defense contractors. Bottom-up equipment shipment estimates triangulated against top-down defense budget allocations and offshore energy capital expenditure projections.
Segment-weighting across product type, end user, technology, and application dimensions shaped the analytical framework across the projection horizon. CAGRs derived from equipment replacement cycle analysis, fleet modernization schedules, and regulatory mandate compliance timelines. Industry-specific forecast inputs included NATO STANAG adoption curves and deepwater oil and gas development project pipelines in the Gulf of Mexico and North Sea.
The model holds under stable geopolitical conditions and sustained defense budget commitments; deviation in export control classifications or dual-use licensing friction would shift supplier competitive positioning. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Temperature Detection Screen Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Moisture Detection Stickers Market
Detection and Regulation Devices
Gas Detectors Market
Detection and Regulation Devices
Hitoxic Gas Detector Market
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Global Label-Free Detection Market