
 Arc Fault Detection Devices Market | 2026-2036
Arc Fault Detection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Arc Fault Detection Devices Market Outlook
The EU Green Deal is expanding the cost-of-entry calculus for arc fault detection devices across European electrical infrastructure. Siemens leverages its industrial automation heritage to dominate digital AFDD integration with building management systems. Schneider Electric anchors its position through deep channel control in residential distribution across France and Benelux markets. Eaton competes aggressively in North American commercial retrofit segments with specialized UL-certified product lines.
Arc fault detection devices are protective electrical components engineered to identify dangerous arcing conditions in circuits through current waveform analysis, typically rated for 16-63A residential and commercial loads. These devices interrupt power when parallel or series arc signatures exceed calibrated thresholds, preventing fire ignition in wiring systems. Indoor product types command the largest installed base but digital technology variants represent the fastest-growing margin pool as electromechanical architectures face obsolescence in smart-building specifications. New construction applications sustain premium pricing while retrofit installation types expand volume through mandatory replacement cycles in aging European housing stock.
Germany's KBA and France's national electrical safety regulator enforce AFDD mandates through building code amendments tied to the EU Green Deal framework. The CE marking and MDR compliance pathways shape product certification timelines and cross-border market access for manufacturers. Stakeholders must monitor whether hybrid technology architectures can bridge the cost-performance gap between legacy electromechanical units and fully digital platforms without triggering wholesale distribution channel disruption.
Market Dynamics
The EU Green Deal's building electrification mandates are restructuring arc fault detection device deployment across European residential construction, forcing wholesale replacement cycles in aging housing stock while accelerating digital platform adoption.
Growth Catalysts
- EU Green Deal building codes:France's national electrical safety regulator and Germany's KBA enforce mandatory AFDD installation in new residential construction and major renovations, creating legal demand floors.
- Smart building integration:Digital AFDD architectures with waveform analytics and remote monitoring capabilities are capturing specification share in commercial retrofit projects across North American building management systems.
- Aging European housing stock:Mandatory replacement cycles in Germany, France, and Benelux markets are sustaining volume growth even as new construction fluctuates.
Market Restraints
- Semiconductor input volatility:Digital AFDD production depends on specialized analog-to-digital converters and microcontrollers subject to foundry allocation constraints and price swings.
- Electromechanical legacy lock-in:Established distribution channels in Southern Europe remain anchored to lower-cost electromechanical units, slowing digital platform penetration.
- CE marking complexity:MDR compliance pathways and harmonized standard revisions create certification timeline uncertainty for manufacturers targeting cross-border European access.
Strategic Opportunities
- North American retrofit channels:UL-certified digital variants are gaining traction in commercial building upgrades as insurers mandate enhanced electrical fire protection.
- Hybrid technology architectures:Bridge products combining electromechanical cost structures with digital sensing capabilities could unlock price-sensitive segments without channel disruption.
- Service unbundling models:Predictive maintenance contracts tied to AFDD waveform data analytics represent recurring revenue streams in facility management procurement.
Industry Challenges
- Firmware engineering talent scarcity:Digital AFDD development requires specialized expertise in arc signature algorithms and embedded systems that outpaces supply in European labor markets.
- Legacy panel compatibility:Retrofit installation types face integration friction with existing residential distribution boards designed for narrower electromechanical form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arc Fault Detection Devices Market |
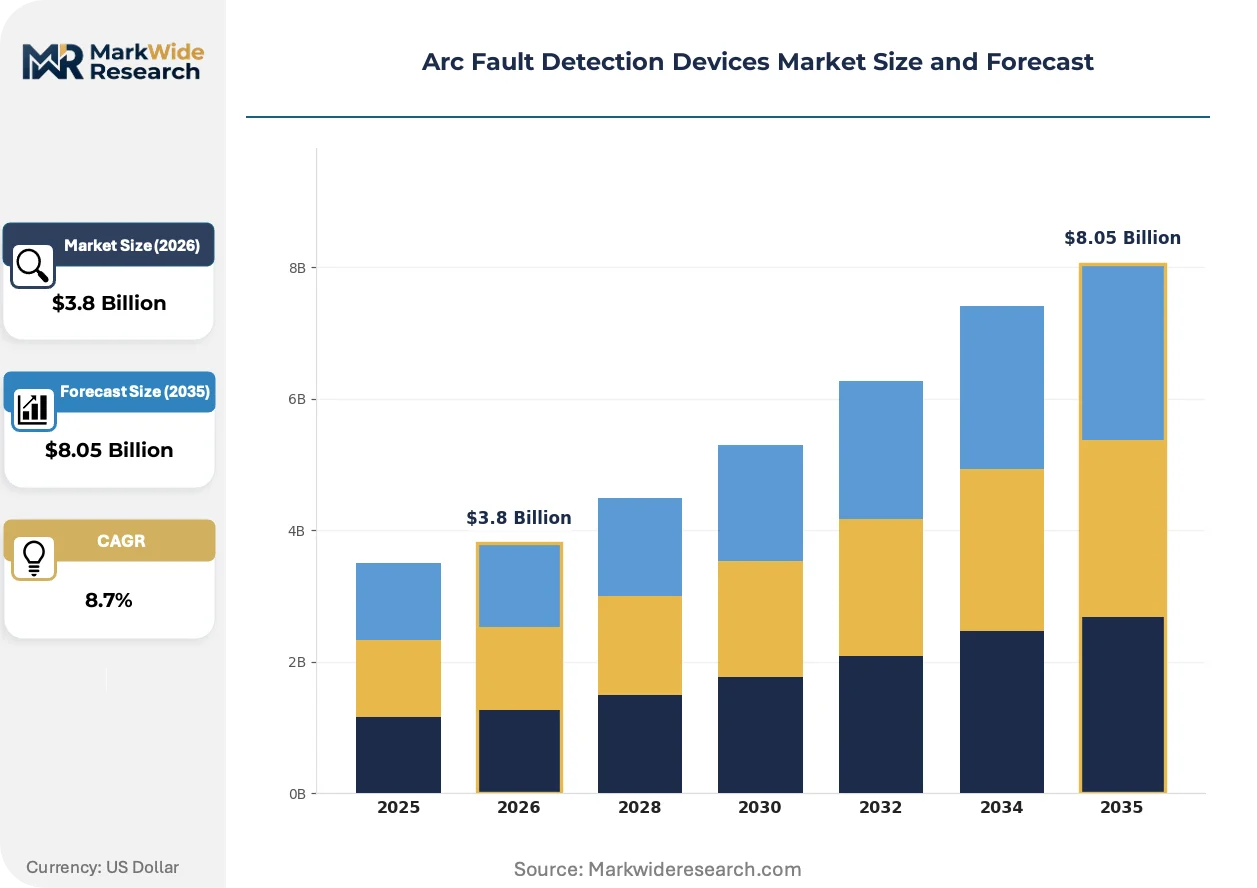
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor, Outdoor, Portable, Fixed Installation Type: Retrofit, New Construction, Panel Mount, Surface Mount Application: Residential, Commercial, Industrial, Institutional Technology: Electromechanical, Digital, Hybrid, Analog |
| Companies Covered | Siemens, Schrack Technik, Schneider Electric, NHP, Doepke, ABB, Hager Group, OEZ s.r.o., Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arc Fault Detection Devices Market Strategic Shifts
Waveform analytics and embedded connectivity are transforming arc fault detection from passive safety components into active building intelligence nodes, compressing replacement cycles and reshaping procurement criteria.
Digital signal processing platforms with machine-learned arc signature libraries are expanding into residential and light commercial specifications previously dominated by electromechanical trip mechanisms. Multi-family developers in Germany and France specify these units for centralized monitoring capabilities. This expansion is compressing electromechanical margin pools and forcing incumbent suppliers to reconfigure product roadmaps.
France's national electrical safety regulator has tightened AFDD mandate enforcement through amended building codes tied to the EU Green Deal's 2030 energy efficiency targets. The policy accelerates replacement timelines in renovation projects exceeding specific electrical load thresholds. Residential contractors in Paris and Lyon metropolitan areas report specification shifts toward digital platforms to satisfy inspection protocols.
Facility managers increasingly bundle AFDD procurement with predictive maintenance service contracts rather than transactional hardware purchases. Industrial and commercial end-users in the US Northeast favor outcome-based arrangements covering waveform monitoring and remote diagnostics. This pattern is most visible in healthcare and data center verticals where downtime costs dominate total cost of ownership calculations.
Arc Fault Detection Devices Market Segmentation
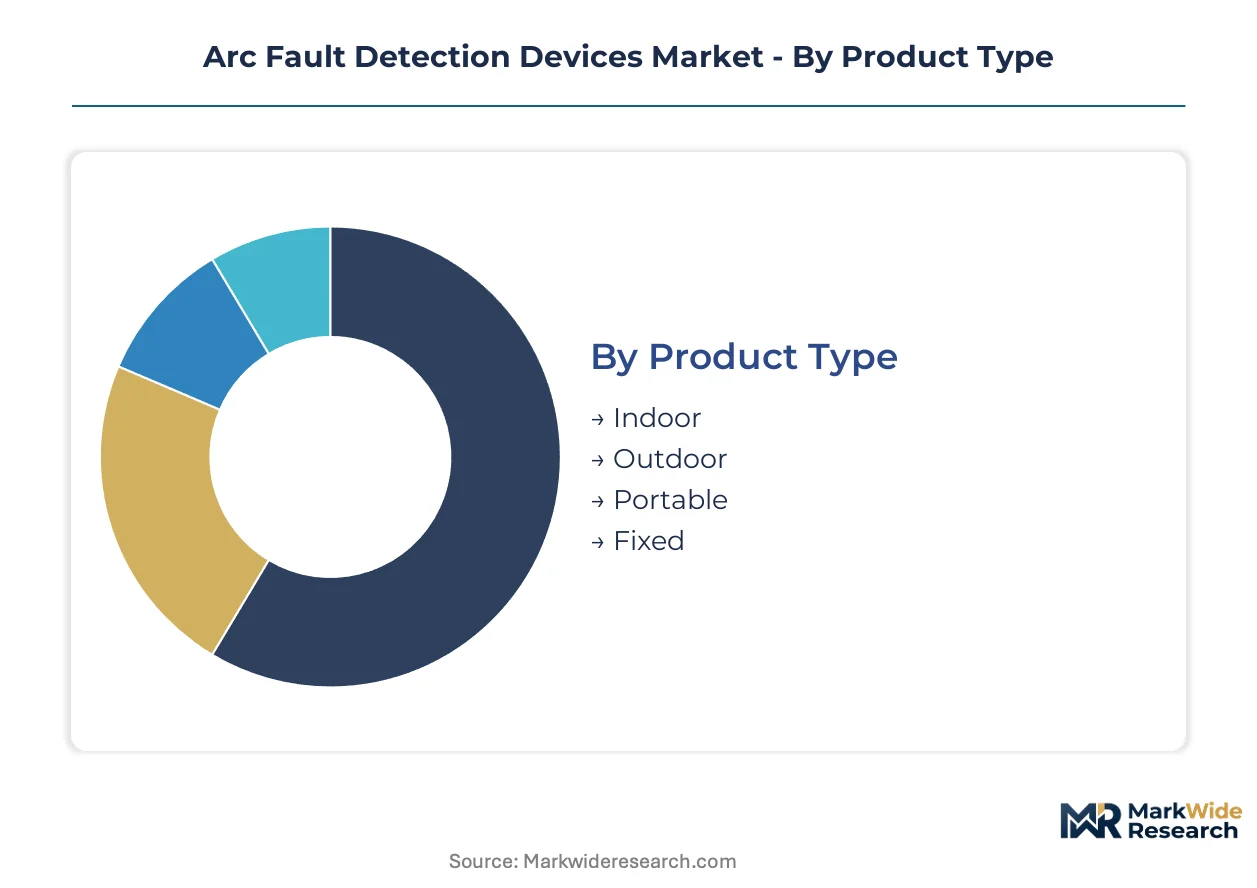
Arc fault detection devices fragment across four critical dimensions that shape procurement patterns and margin structures. Buyers prioritize installation compatibility, environmental exposure, and integration complexity when specifying protective equipment for electrical distribution systems.
Product Type:
Purchase decisions hinge on environmental exposure ratings and enclosure durability requirements.
- Indoor:Enclosed units rated for dry, controlled environments dominate residential and light commercial panel boards. Germany's KBA mandates these for new housing stock under EU Green Deal building codes, sustaining volume concentration despite margin compression from electromechanical legacy products.
- Outdoor:Weather-resistant housings with IP65+ ratings serve utility infrastructure and exposed distribution points. French grid operators specify these for rural electrification projects where enclosure integrity determines service life.
- Portable:Temporary power protection units deploy on construction sites and maintenance operations. German rental equipment channels stock these for contractor compliance with site electrical safety protocols.
- Fixed:Permanent-mount devices integrate into dedicated distribution architecture. Benelux commercial specifications favor these for centralized monitoring in multi-tenant buildings.
Volume sits with Indoor; growth tilts toward Outdoor as distributed generation expands exposed infrastructure.
Installation Type:
Project phase and labor economics determine specification between integrated and surface-mounted solutions.
- Retrofit:Replacement installations in aging European housing stock require form-factor compatibility with legacy panels. France's national electrical safety regulator mandates these in renovation projects exceeding defined electrical load thresholds, compressing replacement timelines.
- New Construction:Greenfield specifications embed AFDDs into initial electrical design. German residential developers specify digital platforms here to satisfy centralized monitoring requirements under tightened building codes.
- Panel Mount:DIN-rail integration suits standardized distribution boards. Southern European contractors favor these for cost-efficient electromechanical deployments in price-sensitive segments.
- Surface Mount:External enclosure installations accommodate non-standard panel configurations. US Northeast commercial retrofits specify these where legacy board dimensions preclude rail mounting.
Retrofit commands current volume; New Construction offers the steepest expansion trajectory as EU Green Deal mandates deepen.
Application:
End-use verticals differentiate by fire risk tolerance, downtime costs, and inspection stringency.
- Residential:Single-family and multi-family housing units represent the foundational demand base. German and French building codes mandate AFDD installation in all new residential construction, establishing legal demand floors.
- Commercial:Office, retail, and hospitality specifications prioritize remote monitoring capabilities. US insurers increasingly mandate enhanced electrical fire protection in commercial property policies.
- Industrial:Manufacturing and processing facilities demand ruggedized units with high fault-current tolerance. Arc signature discrimination algorithms face stringent validation for industrial motor load environments.
- Institutional:Healthcare, education, and government buildings specify predictive maintenance integration. Data center operators in the US Northeast bundle AFDD procurement with waveform analytics service contracts.
Residential anchors volume concentration; Institutional climbs fastest as downtime cost sensitivity reshapes procurement criteria.
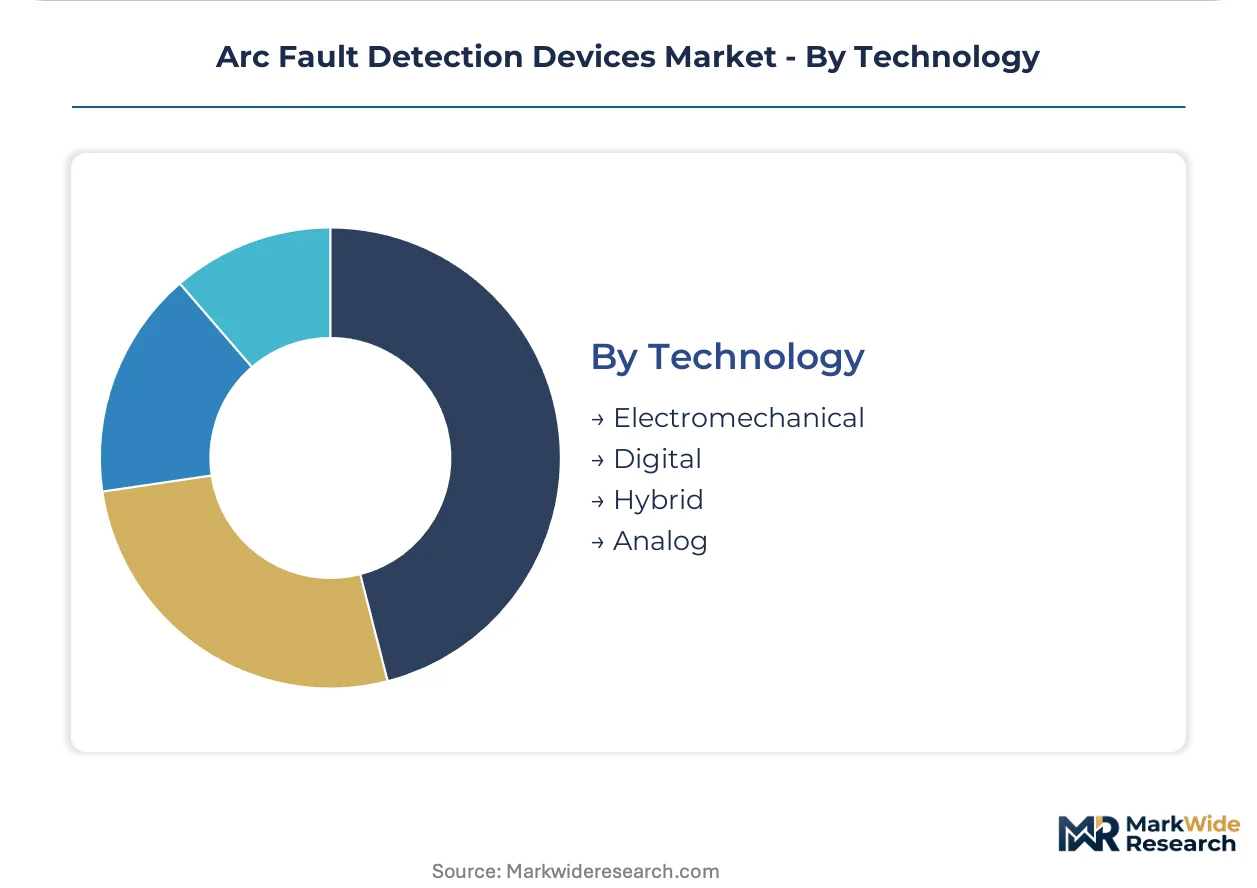
Technology:
Architecture selection balances upfront cost against functionality, connectivity, and algorithmic sophistication.
- Electromechanical:Thermal-magnetic trip mechanisms with basic arc detection circuits dominate legacy installed base. Established Southern European distribution channels anchor volume here despite obsolescence pressure from smart-building specifications.
- Digital:Microcontroller-based waveform analysis platforms with machine-learned signature libraries capture specification share in commercial retrofit projects. Facility managers specify these for building management system integration and remote diagnostics.
- Hybrid:Bridge architectures combining electromechanical cost structures with digital sensing capabilities target price-sensitive segments. These unlock mid-market penetration without forcing wholesale channel disruption.
- Analog:Discrete component signal processing persists in cost-optimized residential specifications. Limited functionality constrains these to basic protection roles without connectivity or analytics.
Electromechanical retains volume leadership; Digital gains share fastest as smart-building procurement criteria displace legacy specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for arc fault detection devices concentrates in European markets where regulatory mandates drive replacement cycles, with Germany and France establishing the most stringent installation requirements under EU Green Deal frameworks.
Germany
Germany's KBA enforces mandatory AFDD installation in new residential construction and major electrical renovations, creating legal demand floors for device manufacturers. The EU Green Deal's building electrification targets accelerate digital platform adoption in multi-family housing developments. Industrial clusters in Bavaria and North Rhine-Westphalia drive specification shifts toward building management system integration.
France
France's national electrical safety regulator mandates AFDD installation in renovation projects exceeding defined electrical load thresholds, compressing replacement timelines in aging urban housing stock. The amended building codes tie enforcement to the EU Green Deal's 2030 energy efficiency commitments. Residential contractors in Paris and Lyon metropolitan areas report specification migration toward digital platforms to satisfy tightened inspection protocols.
United States
US commercial property insurers increasingly mandate enhanced electrical fire protection in building policies, driving specification share for UL-certified digital AFDD variants. The Northeast corridor exhibits strongest retrofit activity as facility managers bundle procurement with predictive maintenance contracts. Data center operators in Virginia and New Jersey prioritize waveform analytics integration to minimize downtime cost exposure.
United Kingdom
UK building regulations incorporate AFDD requirements through amendments to electrical safety standards in residential construction. CE marking transitions post-Brexit create certification pathway complexity for cross-border suppliers. London and Southeast England concentrate specification activity for smart-building integration in commercial retrofit channels.
Italy
Italian electrical safety frameworks adopt EU Green Deal mandates through regional building code harmonization, though enforcement varies across municipal jurisdictions. Southern European distribution channels remain anchored to lower-cost electromechanical units, slowing digital platform penetration. Industrial districts in Lombardy and Emilia-Romagna exhibit emerging specification interest for hybrid technology architectures.
Arc Fault Detection Devices Market Competitive Environment
European producers anchor the premium-tier supply base; North American specialists hold retrofit-focused positions. Market structure exhibits moderate consolidation around industrial automation heritage players with building management system integration capabilities. Three archetypes dominate: diversified electrical equipment conglomerates with channel control, specialized safety component manufacturers with regulatory expertise, and emerging digital platform developers with firmware analytics capabilities. Capacity expansion and strategic technology licensing represent the dominant competitive moves across the forecast window.
Within the diversified conglomerate tier, Siemens and Schneider Electric occupy positions shaped by industrial automation heritage and distribution channel depth. Schrack Technik represents the specialized European safety component archetype with regulatory compliance focus. Eaton anchors the North American retrofit specialization vector through UL-certified product positioning.
| Leading Market Players |
|---|
| Siemens |
| Schrack Technik |
| Schneider Electric |
| NHP |
| Doepke |
| ABB |
| Hager Group |
| OEZ s.r.o. |
| Eaton |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between UL-certified digital platforms and CE-marked electromechanical units manifests in divergent margin pools and sourcing configurations across North American and European supply networks. Premium-tier manufacturers anchor production in Germany and France to satisfy KBA and ANSM inspection protocols, while commodity electromechanical sourcing concentrates in Southern European contract facilities serving price-sensitive retrofit channels.
Pricing Analysis
Volume concentrates in electromechanical units while margin accretion tilts toward digital architectures with waveform analytics and remote diagnostics. Price differentiation rests on UL versus CE certification tiers, with German and French regulatory mandates sustaining premium realization in new construction specifications. Cost compression in electromechanical segments is intensifying because Southern European distributors prioritize lowest-unit-cost procurement for aging housing stock replacement cycles. Residential retrofit contractors exhibit highest price sensitivity; data center operators and healthcare facility managers demonstrate lowest sensitivity due to downtime cost exposure.
Supply Chain Analysis
CE marking and UL certification gating restricts qualified supplier bases to established industrial automation conglomerates with in-house testing facilities. Manufacturing concentrates in Germany, France, and the Czech Republic for European market access, with Mexico and US Southeast facilities serving North American demand. Specialized analog-to-digital converters and arc signature algorithm microcontrollers draw from Taiwan and South Korean foundry networks. Single-source vulnerability in semiconductor inputs poses structural risk to digital AFDD production schedules. Distribution runs through electrical wholesale channels with contractor specification influence determining final placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arc fault detection device sector sits in a technology-transition phase as digital waveform analytics platforms displace electromechanical trip mechanisms across commercial and institutional specifications.
For Market Incumbents: Cement channel control in French and German distribution networks before hybrid technology architectures unlock mid-market penetration. Deepen firmware engineering capabilities through specialized embedded systems hiring in Bavaria and North Rhine-Westphalia industrial clusters. Defend against emerging digital platform developers by accelerating building management system integration roadmaps. For New Entrants and Emerging Players: The price-point gap between premium Siemens/Schneider digital units and economy electromechanical imports creates white-space opportunity for hybrid bridge products. Target Italian regional markets where municipal enforcement of EU Green Deal mandates remains uneven and electromechanical legacy lock-in persists. Pursue OEM private-label partnerships with Southern European electrical distributors seeking certified alternatives to established supplier relationships. For Investors and Strategic Acquirers: Re-rating potential sits with specialized firmware analytics developers given insurer mandate expansion across US commercial property policies. Long-term viability favors acquisition targets with captive arc signature algorithm libraries and embedded connectivity stacks. Monitor CE marking timeline announcements from France's national electrical safety regulator as inflection indicator for European replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Technology Platform Launch | Bridge architectures unlock Italian and Spanish retrofit channels without forcing distributor requalification. |
| Building Management System Integration | Siemens leverages industrial automation heritage to capture specification share in German multi-family developments. |
| Predictive Maintenance Service Unbundling | Waveform data analytics contracts create recurring revenue streams with US Northeast healthcare facility managers. |
| Semiconductor Supply Agreement | Long-term foundry allocations mitigate analog-to-digital converter volatility for digital AFDD production. |
| UL Certification Pathway Investment | Eaton anchors North American retrofit positioning through specialized commercial property insurer mandates. |
Study Parameters
Multi-period observation of AFDD installation mandates, semiconductor input pricing, and distributor inventory cycles anchored the trend analysis, supplemented by interviews with electrical contractors, facility managers, and regulatory compliance officers. Primary fieldwork engaged specification engineers at multi-family developers in Paris and Lyon, procurement leads at German housing associations, and aftermarket service heads at US data center operators. Secondary validation drew from KBA enforcement bulletins, ANSM building code amendments, UL certification databases, and EU Green Deal implementation trackers. Bottom-up unit shipment modeling triangulated against top-down construction spending allocations.
Input-output matrix framework linked residential and commercial construction permit flows to AFDD specification rates across electromechanical, digital, and hybrid technology tiers. Segmentation dimensions spanned installation type, environmental exposure rating, end-use vertical, and regional regulatory cluster. CAGRs were derived from trend extrapolation of mandate enforcement intensity and technology substitution curves. Forecast inputs incorporated foundry capacity allocation signals for specialized microcontrollers and insurer policy wording evolution in US commercial property markets.
Inputs from KBA, ANSM, and UL certification registries were available through the study window; gaps in real-time distributor pricing data introduce uncertainty bands around electromechanical segment margin estimates. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and semiconductor supply normalization. Model refresh is warranted upon material change in French building code amendment timelines or US commercial property insurer mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Transient Voltage Suppressor (TVS) Diode Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market
Detection and Regulation Devices
IR Detector Market
Detection and Regulation Devices
Neutron Detector Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Moisture Detection Stickers Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market