
 Middle East and Africa Trace Detection Market | 2026-2036
Middle East and Africa Trace Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Trace Detection Market Insights
South Africa's defense industrial corridor is fragmenting as trace detection procurement spreads across multiple domestic security agencies and cross-border initiatives. Smiths Detection Group Ltd leverages its established airport security footprint across sub-Saharan hubs to sustain service revenue streams. Teledyne Flir LLC anchors its regional position through thermal-chemical fusion systems tailored for desert climate operations. Bruker Corporation differentiates via portable mass spectrometry units designed for field-deployable military applications.
Trace detection encompasses analytical instrumentation that identifies microscopic quantities of explosives, narcotics, chemical warfare agents, or toxic materials through ion mobility separation, chromatographic analysis, or spectroscopic fingerprinting at parts-per-billion sensitivity thresholds. The technology serves critical screening functions at transportation nodes, military checkpoints, and forensic laboratories where human safety depends on rapid substance identification without physical sample destruction. Ion mobility spectrometry occupies the dominant installed base across airport security deployments due to its sub-ten-second analysis speed and minimal operator training requirements. Mass spectrometry segments command premium pricing in military and border control settings where false-positive intolerance justifies higher capital expenditure. Laser-induced breakdown spectroscopy represents the fastest-growing product category for environmental monitoring applications across mining-intensive African economies.
South Africa's National Regulator for Compulsory Specifications enforces equipment certification standards that shape import eligibility for trace detection systems deployed at critical infrastructure. The UAE's Civil Aviation Authority and Saudi Arabia's General Authority of Civil Aviation impose parallel aviation security equipment mandates that accelerate replacement cycles at major hub airports. Stakeholders must monitor evolving alignment between Gulf state regulatory frameworks and European CE marking requirements to anticipate future market access conditions.
Market Dynamics
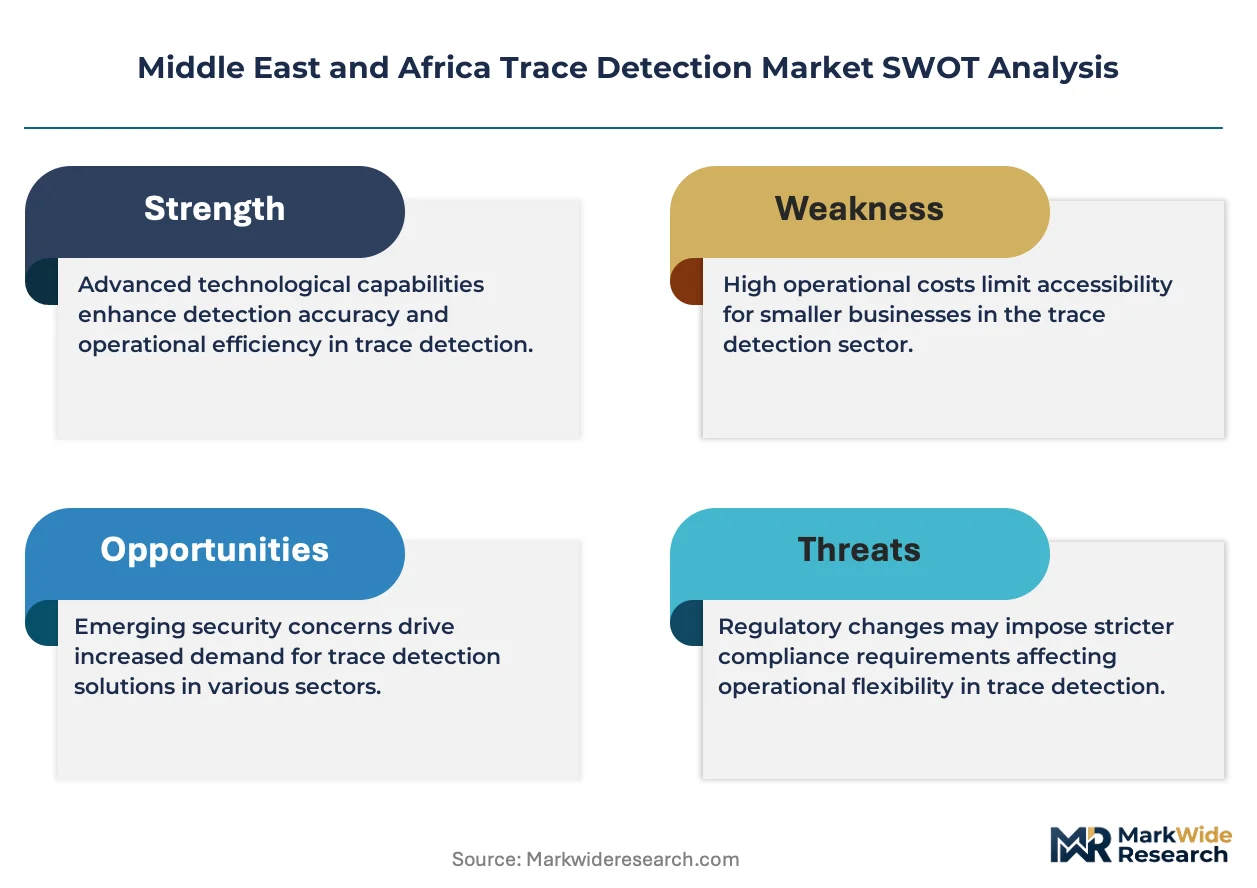
Aviation security mandates across Gulf Cooperation Council states are forcing accelerated replacement cycles at major hub airports, compressing procurement timelines from five-year capital plans to emergency budget allocations.
Growth Catalysts
- UAE Civil Aviation Authority screening mandates:Dubai International and Abu Dhabi Zayed International airports are expanding explosive trace detector deployment to meet tightened hold baggage inspection protocols.
- Ion mobility spectrometry speed advantages:Sub-ten-second analysis cycles enable high-throughput passenger processing at congested African border crossings without secondary screening bottlenecks.
- Saudi Arabia's General Authority of Civil Aviation:The regulator's equipment certification requirements are standardizing procurement specifications across King Abdulaziz International and King Khalid International terminals.
Market Restraints
- Helium-3 supply constraints:Neutron-based detection systems face input scarcity as nuclear non-proliferation agreements restrict isotope availability for portal monitors.
- South African rand volatility:Import-dependent procurement for the National Regulator for Compulsory Specifications-certified equipment exposes domestic agencies to exchange rate-driven cost spikes.
- Laser-induced breakdown spectroscopy sensitivity thresholds:Environmental dust interference in Saharan operating conditions limits field reliability for mining security applications.
Strategic Opportunities
- Kenya's Mombasa Port modernization:Container screening infrastructure gaps create first-mover advantage for integrated chemical-radiological detection platforms at East Africa's primary trade gateway.
- Thermal-chemical sensor fusion:Combined infrared and ion mobility architectures address false-positive reduction in desert climate operations where temperature swings degrade single-modality accuracy.
- Egypt's Suez Canal Economic Zone:Industrial security requirements for petrochemical facilities are opening demand for portable mass spectrometry units with military-grade ruggedization.
Industry Challenges
- Spectroscopy technician scarcity:Field maintenance of mass spectrometry systems requires specialized training unavailable through standard vocational programs in sub-Saharan Africa.
- CE marking alignment delays:South Africa's National Regulator for Compulsory Specifications certification timeline extends eighteen months for European manufacturers seeking equipment import approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Trace Detection Market |
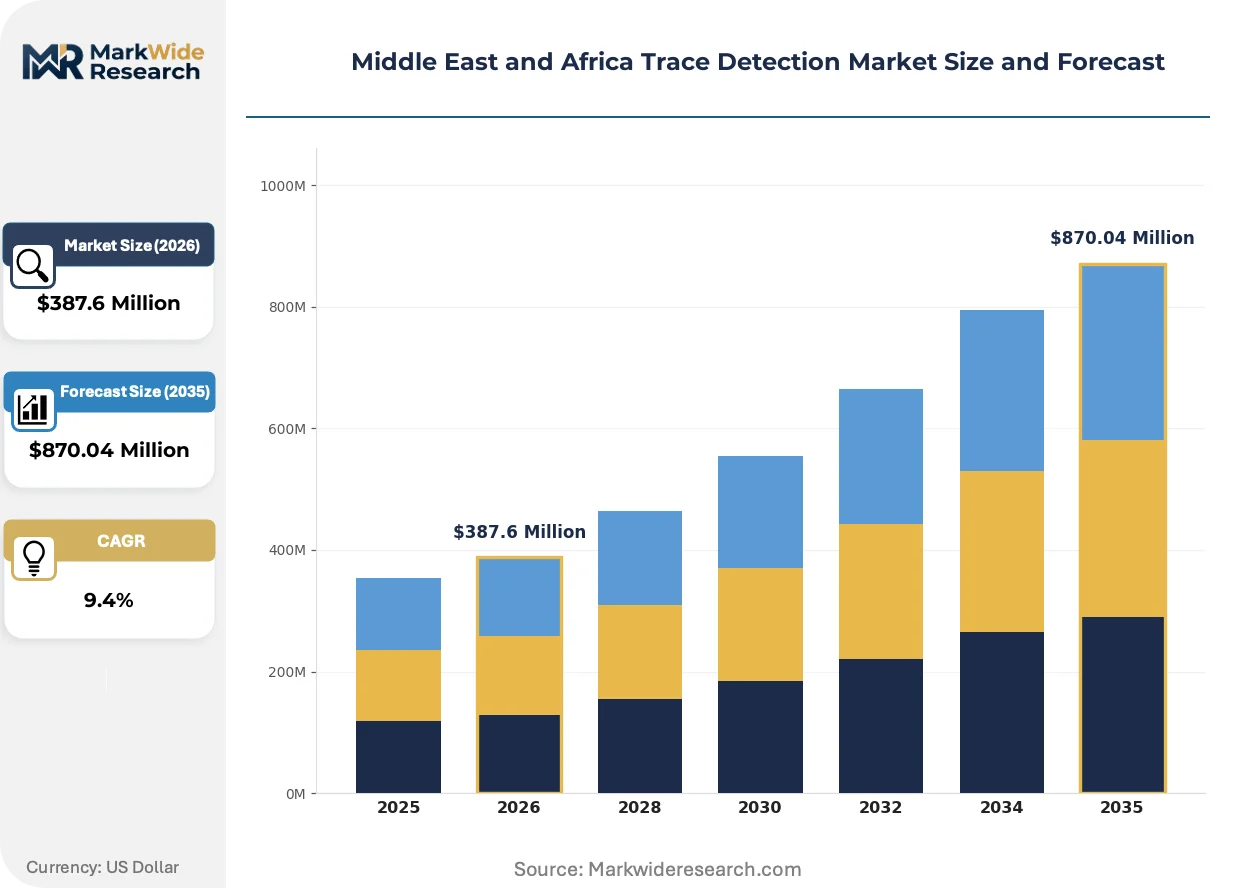
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ion Mobility Spectrometry, Gas Chromatography, Mass Spectrometry, Laser-Induced Breakdown Spectroscopy End User: Airport Security, Border Control, Military, Law Enforcement Application: Explosive Detection, Drug Testing, Environmental Monitoring, Food Safety Technology: Optical Sensors, Chemical Sensors, Acoustic Sensors, Electromechanical Systems |
| Companies Covered | Smiths Detection Group Ltd, Teledyne Flir LLC, Bruker Corporation, Leidos Holdings Inc, Autoclear LLC, DetectaChem, Nuctech, High Tech Detection Systems, OSI Systems Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Trace Detection Market Trends and Innovations
Detection architectures are converging around multi-modal sensor fusion as single-technology systems prove inadequate for complex threat matrices. Equipment vendors are repositioning around software-defined analysis platforms that decouple hardware refresh cycles from capability upgrades.
Artificial intelligence inference engines are virtualizing threat identification workflows by embedding neural network classifiers directly at the sensor edge. Military checkpoint operators in the UAE and Saudi Arabia are deploying these systems to reduce false-positive rates below two percent without human adjudication. The technology is virtualizing traditional tier-one support structures by enabling remote diagnostic access and predictive maintenance scheduling.
South Africa's National Regulator for Compulsory Specifications is harmonizing equipment certification standards with European CE marking requirements to accelerate cross-border equipment mobility. This regulatory convergence reduces duplicate testing costs for manufacturers serving both domestic and export markets. Portable mass spectrometry segments are responding fastest, with vendors pre-certifying units to dual-standard specifications.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance contracts into discrete software subscription and hardware assurance components. Airport authorities in Dubai and Johannesburg are negotiating per-screen pricing models that transfer operational risk to equipment vendors. This shift concentrates buyer leverage among large hub operators with sufficient transaction volume to justify outcome-based arrangements.
Middle East and Africa Trace Detection Market Segmentation
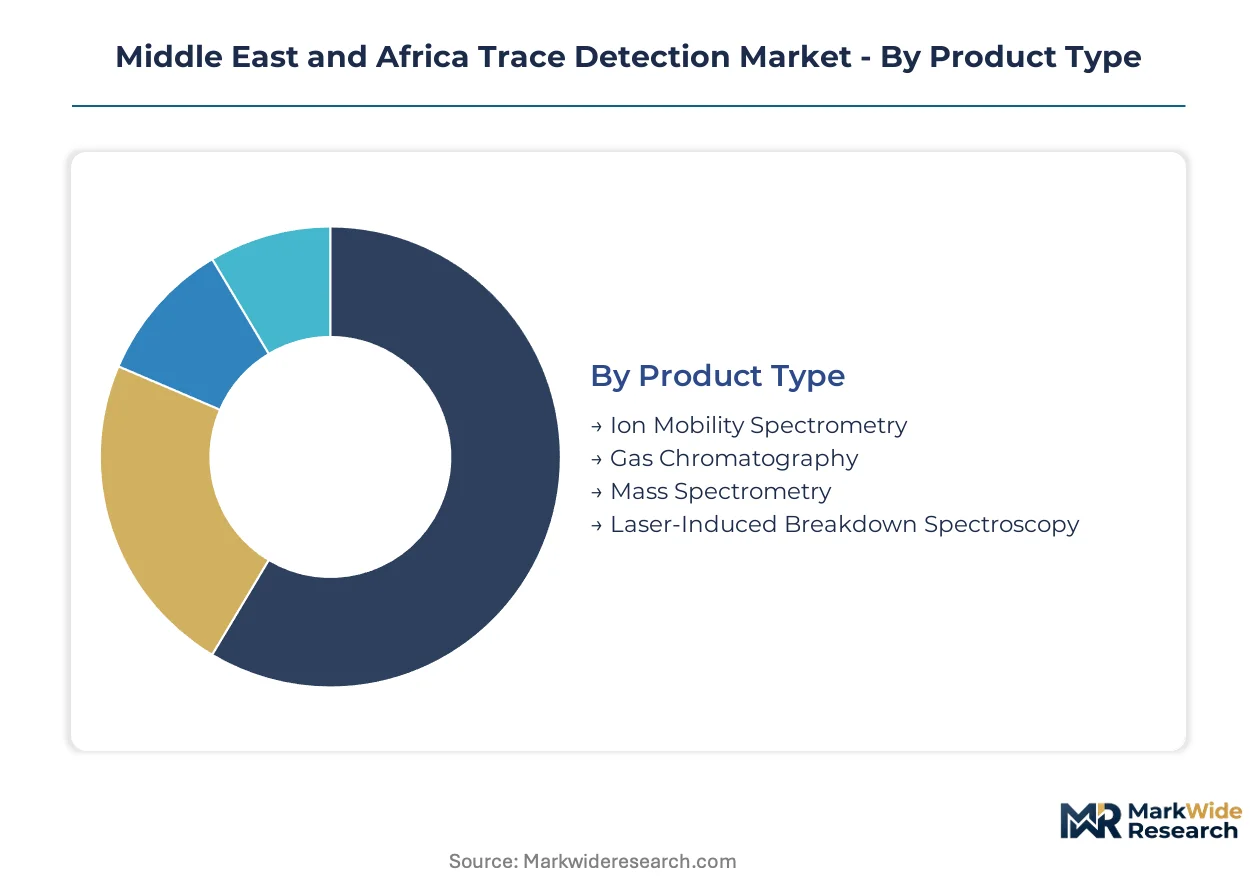
Trace detection procurement patterns diverge sharply across deployment contexts, with airport security operators prioritizing throughput speed while military buyers emphasize false-positive immunity. Understanding these segment-specific performance trade-offs clarifies vendor positioning and service contract structures across the Middle East and Africa.
Product Type:
After-sales service intensity varies dramatically by detection modality, with mass spectrometry systems demanding specialized technician deployment while ion mobility units rely on remote diagnostics.
- Ion Mobility Spectrometry:Sub-ten-second analysis cycles exploit electric field drift-time separation of ionized molecules at ambient pressure. Dubai International Airport and Abu Dhabi Zayed International have standardized on these systems for passenger checkpoint throughput, accepting higher false-positive rates in exchange for processing volume.
- Mass Spectrometry:Magnetic sector and quadrupole configurations deliver parts-per-billion sensitivity through precise mass-to-charge ratio measurement. Saudi military procurement channels favor these units for CBRN checkpoint applications where false-negative consequences outweigh capital expenditure premiums.
- Gas Chromatography:Separates volatile compounds through differential column retention prior to detection. South African forensic laboratories deploy hybrid GC-IMS architectures for drug evidence confirmation.
- Laser-Induced Breakdown Spectroscopy:Ablative laser pulses generate plasma emissions for elemental fingerprinting. Mining security operators across Botswana and Zambia pilot these units for environmental compliance monitoring despite Saharan dust interference challenges.
By volume, ion mobility spectrometry leads. By growth pace, laser-induced breakdown spectroscopy is expanding most quickly.
End User:
Procurement authority fragmentation shapes contract negotiation leverage, with consolidated airport authorities commanding outcome-based pricing that dispersed military units cannot replicate.
- Airport Security:Gulf Cooperation Council aviation regulators mandate explosive trace detector deployment at hold baggage and passenger screening nodes. Dubai Airports and Saudi Ground Services negotiate per-screen service contracts that transfer operational risk to equipment vendors.
- Military:Field-deployable requirements drive demand for ruggedized portable units with extended battery autonomy. UAE Armed Forces and Saudi Arabian National Guard procurement channels prioritize mass spectrometry segments for CBRN reconnaissance missions.
- Border Control:South African Revenue Service and Kenya Revenue Authority modernization programs concentrate demand at land and maritime entry points. Ion mobility systems dominate due to minimal operator training requirements.
- Law Enforcement:Forensic laboratory and tactical team procurement spreads across multiple domestic agencies. South African Police Service drug analysis units favor chromatographic confirmation systems.
Airport security commands the largest installed base. Military end-use exhibits the steepest expansion trajectory as regional defense budgets prioritize CBRN preparedness.
Application:
Regulatory mandate intensity varies by threat category, with explosive detection facing mandatory certification while environmental monitoring follows voluntary adoption curves.
- Explosive Detection:Aviation security protocols require certified explosive trace detectors at every passenger screening lane. UAE Civil Aviation Authority and Saudi General Authority of Civil Aviation specifications standardize procurement across King Abdulaziz International and King Khalid International terminals.
- Drug Testing:Forensic confirmation and interdiction applications concentrate demand in South Africa and Nigeria. Border control agencies deploy portable ion mobility units for precursor chemical identification.
- Environmental Monitoring:Mining sector compliance drives LIBS adoption for heavy metal soil analysis across Zambian copper belt operations.
- Food Safety:Pesticide residue screening applications remain nascent, with South African Department of Agriculture piloting mass spectrometry for export certification.
Explosive detection dominates current revenue. Environmental monitoring is gaining share fastest as African mining economies tighten tailings regulation.
Technology:
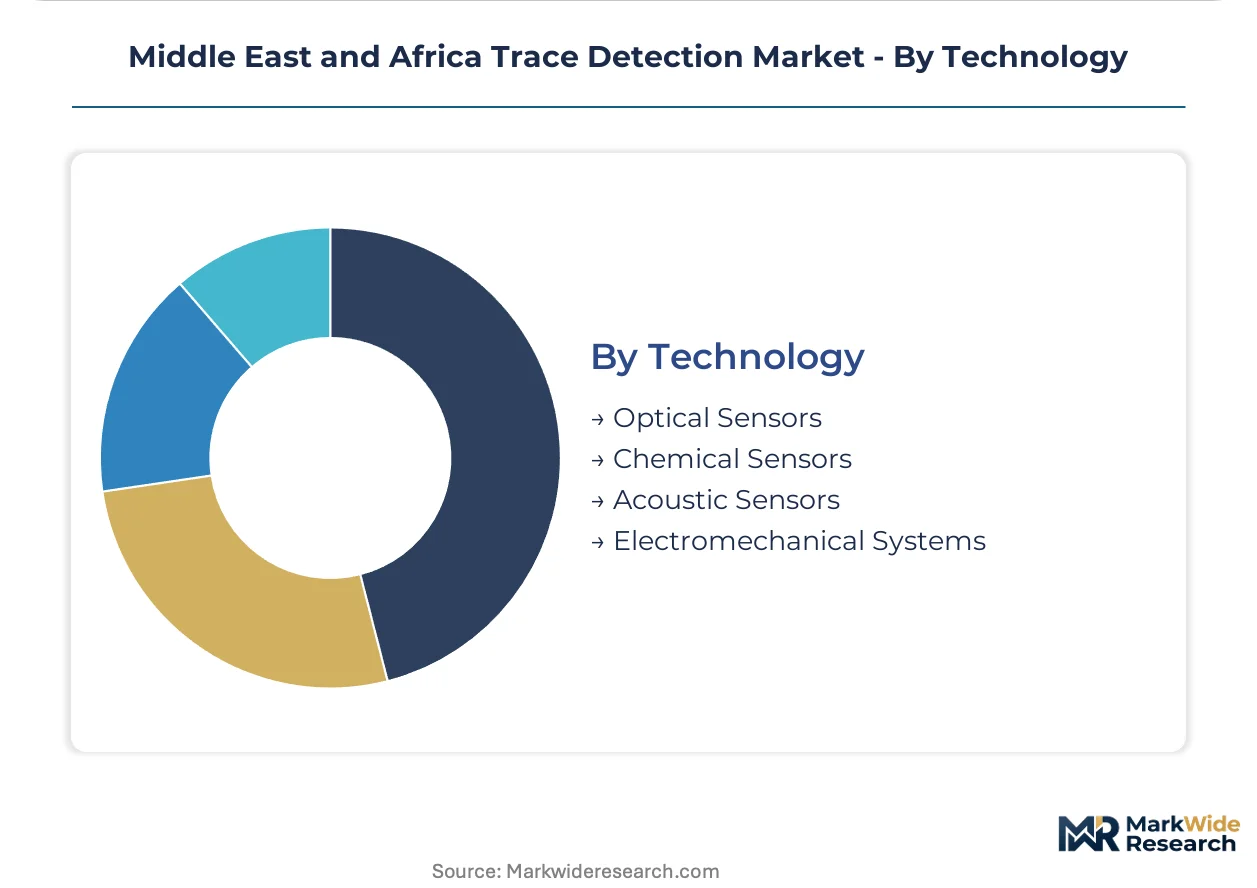
Sensor modality selection determines maintenance infrastructure requirements, with optical systems enabling remote calibration while electromechanical platforms demand field technician presence.
- Chemical Sensors:Ion mobility and chromatographic detection cores constitute the dominant installed base. These systems integrate directly into Smiths Detection and Teledyne FLIR product architectures deployed across sub-Saharan airport hubs.
- Optical Sensors:Infrared and laser-based spectroscopic methods enable standoff detection capabilities. Thermal-chemical fusion systems address false-positive reduction in UAE and Saudi desert climate operations.
- Electromechanical Systems:MEMS-based preconcentrator and sampling subsystems extend detection sensitivity. These components require periodic replacement cycles that sustain vendor service revenue streams.
- Acoustic Sensors:Surface acoustic wave and quartz crystal microbalance configurations serve niche environmental monitoring applications with limited current deployment.
Chemical sensors lead by installed base. Optical sensors are climbing the fastest as multi-modal fusion architectures displace single-technology systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor service infrastructure concentrates in the UAE and South Africa, with secondary technical support nodes emerging in Saudi Arabia. Equipment certification requirements diverge across national regulators, fragmenting procurement standardization. Each jurisdiction imposes distinct operational constraints on deployment timelines and maintenance protocols.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International airports drive explosive trace detector procurement under Civil Aviation Authority screening mandates. The regulator's hold baggage inspection protocols compress replacement cycles to emergency budget allocations. Abu Dhabi hosts the Gulf's densest concentration of ion mobility spectrometry service technicians.
Saudi Arabia
The General Authority of Civil Aviation standardizes equipment specifications across King Abdulaziz International and King Khalid International terminals. Military procurement channels through the Saudi Arabian National Guard prioritize mass spectrometry units for CBRN reconnaissance missions. Riyadh anchors the kingdom's defense industrial corridor for trace detection maintenance infrastructure.
South Africa
The National Regulator for Compulsory Specifications enforces eighteen-month certification timelines for European manufacturers seeking import approval. The South African Revenue Service and South African Police Service fragment procurement across border control and forensic laboratory applications. Johannesburg concentrates technical training capacity for chromatographic confirmation systems.
Egypt
The Suez Canal Economic Zone generates demand for portable mass spectrometry units with military-grade ruggedization at petrochemical facilities. The country's national aviation regulator aligns equipment mandates with Gulf Cooperation Council standards to facilitate cross-border mobility. Cairo serves as the primary distribution node for North African military procurement channels.
Kenya
The Kenya Revenue Authority's Mombasa Port modernization program creates infrastructure gaps for integrated chemical-radiological detection platforms. Land border crossings with Tanzania and Uganda deploy ion mobility systems requiring minimal operator training. Nairobi hosts East Africa's limited pool of spectroscopy maintenance technicians.
Middle East and Africa Trace Detection Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying electromechanical subsystems and preconcentrator modules. The vendor base splits between consolidated airport security incumbents with established service footprints and emerging specialists in thermal-chemical fusion architectures. Three archetypes dominate: throughput-optimized integrators serving aviation authorities, ruggedization-focused suppliers for military channels, and software-defined platform vendors decoupling hardware from capability upgrades. Competitive intensity centers on outcome-based pricing negotiations and predictive maintenance service unbundling.
Within the platform integrator tier, Smiths Detection Group Ltd and Teledyne Flir LLC exemplify divergent geographic anchoring strategies. Smiths Detection leverages its sub-Saharan airport hub presence to sustain recurring service revenue. Teledyne Flir occupies a position emphasizing thermal-chemical sensor fusion for desert climate operations. Bruker Corporation represents the portable mass spectrometry archetype targeting military-grade field deployment requirements. Each firm situates within distinct procurement channel relationships shaped by national regulator certification timelines and end-user technical capacity constraints.
| Leading Market Players |
|---|
| Smiths Detection Group Ltd |
| Teledyne Flir LLC |
| Bruker Corporation |
| Leidos Holdings Inc |
| Autoclear LLC |
| DetectaChem |
| Nuctech |
| High Tech Detection Systems |
| OSI Systems Inc |
| Others |
Pricing and Supply Chain Analysis
Abu Dhabi's ion mobility spectrometry service technician cluster concentrates regional maintenance capacity, translating into vendor pricing leverage over airport authorities in secondary hubs lacking comparable technical infrastructure. Gulf Cooperation Council aviation regulators compress replacement cycles through emergency budget allocations, amplifying cost pass-through power for established service providers.
Pricing Analysis
The UAE Civil Aviation Authority dictates the pricing tier structure across explosive trace detector procurement, with three-tier pricing separating certified premium units from standard airport-grade systems and economy-tier refurbished equipment. Price differentiation rests on certification grade alignment with Saudi General Authority of Civil Aviation specifications and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because South African rand volatility exposes import-dependent agencies to exchange rate-driven spikes. Military procurement channels show least price sensitivity due to false-negative intolerance, while forensic laboratories face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for electromechanical subsystems and preconcentrator modules concentrates among German, Japanese, and South Korean precision component specialists. Helium-3 isotope sourcing draws from restricted nuclear non-proliferation supply channels, while MEMS-based sampling subsystems and infrared sensor arrays feed from East Asian semiconductor fabrication nodes. Single-source vulnerability in neutron detection isotope supply creates procurement risk for portal monitor deployments. Distribution runs through Dubai and Johannesburg as primary regional hubs, with secondary nodes emerging in Riyadh and Cairo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated Gulf airport authorities capable of negotiating per-screen outcome-based contracts, fragmenting leverage for dispersed military and law enforcement procurement units.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance software into existing ion mobility deployments at Dubai International and Abu Dhabi Zayed International. Deepen backward integration into electromechanical subsystem production to offset MEMS component cost volatility. Certification investment in dual-standard pre-certification for South Africa's National Regulator for Compulsory Specifications and European CE marking accelerates cross-border equipment mobility. For New Entrants and Emerging Players: Build out thermal-chemical sensor fusion capabilities targeting false-positive reduction in Saudi and UAE desert climate operations where temperature swings degrade single-modality accuracy. Kenya's Mombasa Port modernization presents the most penetrable white-space for integrated chemical-radiological detection platforms. A software-defined analysis platform go-to-market angle decouples hardware refresh cycles from capability upgrades, appealing to budget-constrained African border control agencies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined platform vendors with predictive maintenance capabilities over pure hardware manufacturers. Long-term viability over the projection horizon rests on service contract recurrence and regulatory certification moats rather than unit sales velocity. Acquisition targets should display established dual-standard certification pipelines and installed bases in aviation security channels. The signal to watch is alignment velocity between Gulf state regulatory frameworks and European CE marking requirements as a proxy for market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Standard Certification Investment | Pre-certification to South African NRCS and CE marking specifications reduces eighteen-month approval timelines for European manufacturers. |
| Predictive Maintenance Platform Launch | Software subscription unbundling transfers operational risk to vendors while securing recurring revenue from Dubai Airports. |
| Thermal-Chemical Sensor Fusion Development | Combined infrared and ion mobility architectures address false-positive reduction in UAE and Saudi desert climate checkpoints. |
| East African Service Infrastructure Expansion | Nairobi technical training capacity addresses spectroscopy technician scarcity constraining mass spectrometry field maintenance. |
| Helium-3 Alternative Technology Pivot | Neutron-independent detection platforms mitigate isotope supply restriction risks from nuclear non-proliferation agreements. |
Research Methodology
A standing panel of airport security procurement directors, military CBRN program officers, border control agency technical leads, and forensic laboratory managers provided ongoing calibration across the study period. Primary interviews with equipment vendors, aftermarket service providers, and national regulator certification specialists combined with secondary validation through customs import records, aviation authority equipment mandate filings, and defense budget appropriation documents. Bottom-up installed base enumeration triangulated against top-down market sizing derived from procurement contract disclosures.
Scenario bracketing across conservative, baseline, and expansion cases anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include detection modality, end-user category, application threat type, and regional regulatory cluster. CAGRs were derived from weighted average growth trajectories across these segments, with inputs from equipment replacement cycle compression rates and certification timeline evolution patterns specific to Middle East and Africa trace detection procurement channels.
Stress conditions across helium-3 supply restriction severity, South African rand volatility bands, and Gulf aviation security mandate acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory alignment velocity and service technician training pipeline expansion. Quarterly review of national regulator certification timeline announcements and defense budget appropriation trajectories is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Electronic Article Surveillance Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market
Detection and Regulation Devices
Volatile Organic Compound (VOC) Detector Market
Detection and Regulation Devices
Superconducting Detector Market