
 Portable Radar Detectors Market | 2026-2036
Portable Radar Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Radar Detectors Market Analytics
Subscription-based firmware update services is realigning revenue models away from one-time hardware sales toward recurring annual plans. Escort Inc. leverages its Defender database to sustain customer retention through real-time threat mapping. Uniden Corporation anchors its position with long-range detection hardware that competes on raw sensitivity specifications. Valentine Research Inc. specializes in enthusiast-grade units that dominate the premium segment through direct-to-consumer channel control.
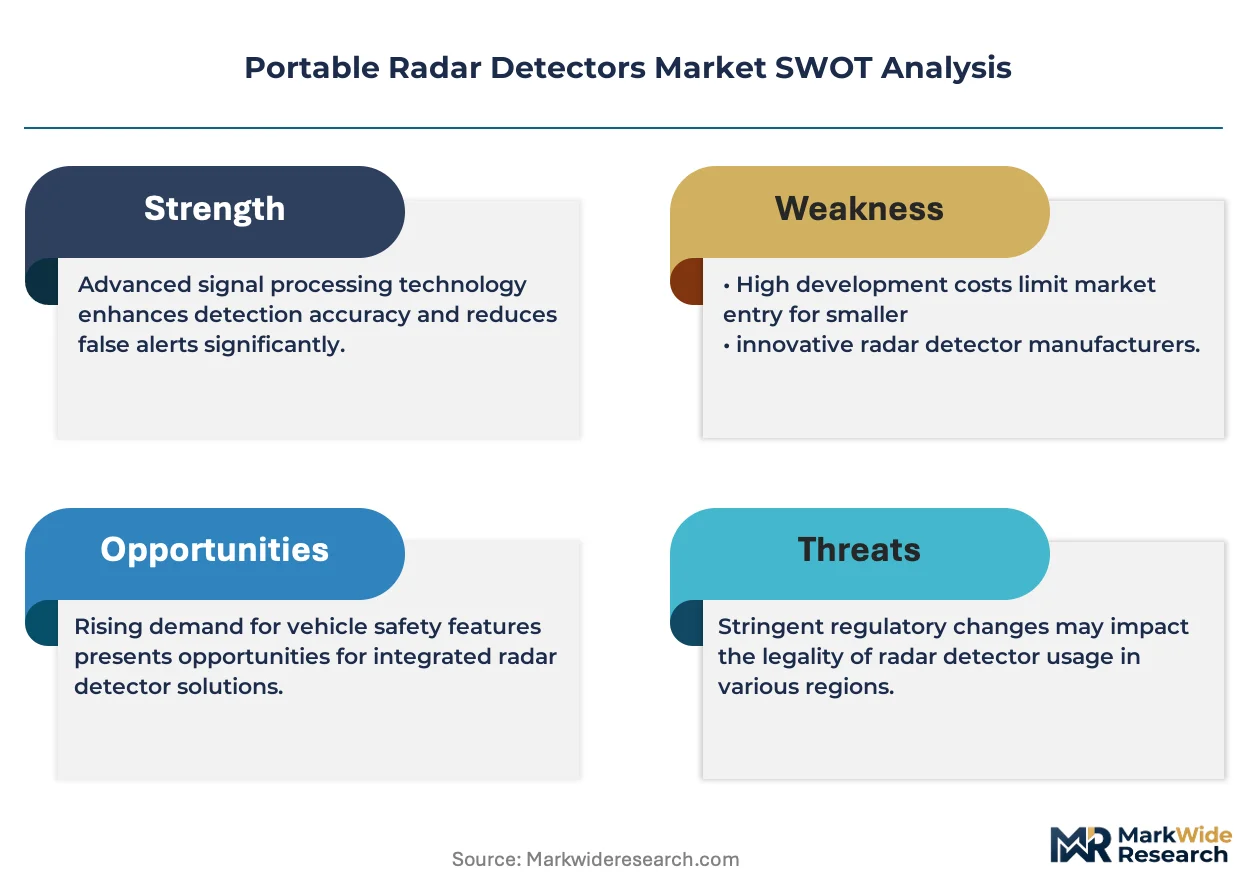
Portable radar detectors are electronic devices that sense radio waves emitted by police speed measurement systems, typically operating across Ka, K, and X frequency bands with sensitivity thresholds measured in decibels. Their primary commercial purpose is alerting drivers to active enforcement zones, thereby reducing citation incidence and insurance penalty exposure. GPS-enabled units represent the fastest-growing product configuration as geofenced alert databases reduce false positives from automated door openers. Multispectrum technology captures margin concentration because single-band hardware faces obsolescence as law enforcement agencies upgrade to variable-pulse lidar systems. The fleet management end-user category exhibits structural expansion potential tied to corporate liability reduction programs.
The FCC governs electromagnetic emission standards for radar detectors sold in the United States, while NHTSA safety guidelines influence mounting location restrictions that shape product form factors. State-level prohibitions in Virginia and Washington D.C. create geographic demand fragmentation that manufacturers navigate through region-locked distribution. Stakeholders must monitor municipal adoption of frequency-hopping lidar protocols that threaten to outpace hardware detection capabilities.
Market Dynamics
Frequency-hopping lidar protocols deployed by state highway patrols are forcing detector manufacturers to compress hardware refresh cycles while defending sensitivity specifications against obsolescence.
Growth Catalysts
- Fleet telematics integration:Corporate liability programs in long-haul trucking are embedding driver safety alerts directly into dispatch platforms, creating bundled procurement pull-through.
- GPS geofencing databases:Real-time threat mapping reduces false positives from automated retail door sensors, improving user retention in suburban commuter corridors.
- Ka-band sensitivity upgrades:FCC emission standard enforcement is pushing hardware makers toward higher decibel thresholds to capture variable-pulse radar signals.
Market Restraints
- State-level prohibitions:Virginia and Washington D.C. maintain outright bans that fragment distribution networks and require region-locked firmware.
- Gallium arsenide component costs:High-frequency receiver chips face input price volatility tied to semiconductor foundry capacity allocation.
- Smartphone app substitution:Crowdsourced speed trap alerts via Waze and similar platforms erode entry-level hardware demand among casual users.
Strategic Opportunities
- Subscription firmware services:Recurring revenue models replace one-time hardware sales through threat database access and over-the-air sensitivity tuning.
- Insurance partnership channels:Usage-based auto insurers in Texas and Florida are piloting detector rebates as loss-prevention incentives for policyholders.
- Lidar-to-Radar convergence:Multispectrum detection modules that capture both photonic and radio frequency signals open premium positioning against single-band obsolescence.
Industry Challenges
- RF engineering talent scarcity:Microwave circuit design expertise concentrates among legacy defense contractors, constraining product development velocity.
- NHTSA mounting compliance:Windshield placement restrictions require industrial design revalidation for each vehicle platform, extending certification timelines.
- Intellectual property fragmentation:Patent thickets around digital signal processing algorithms complicate licensing for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Radar Detectors Market |
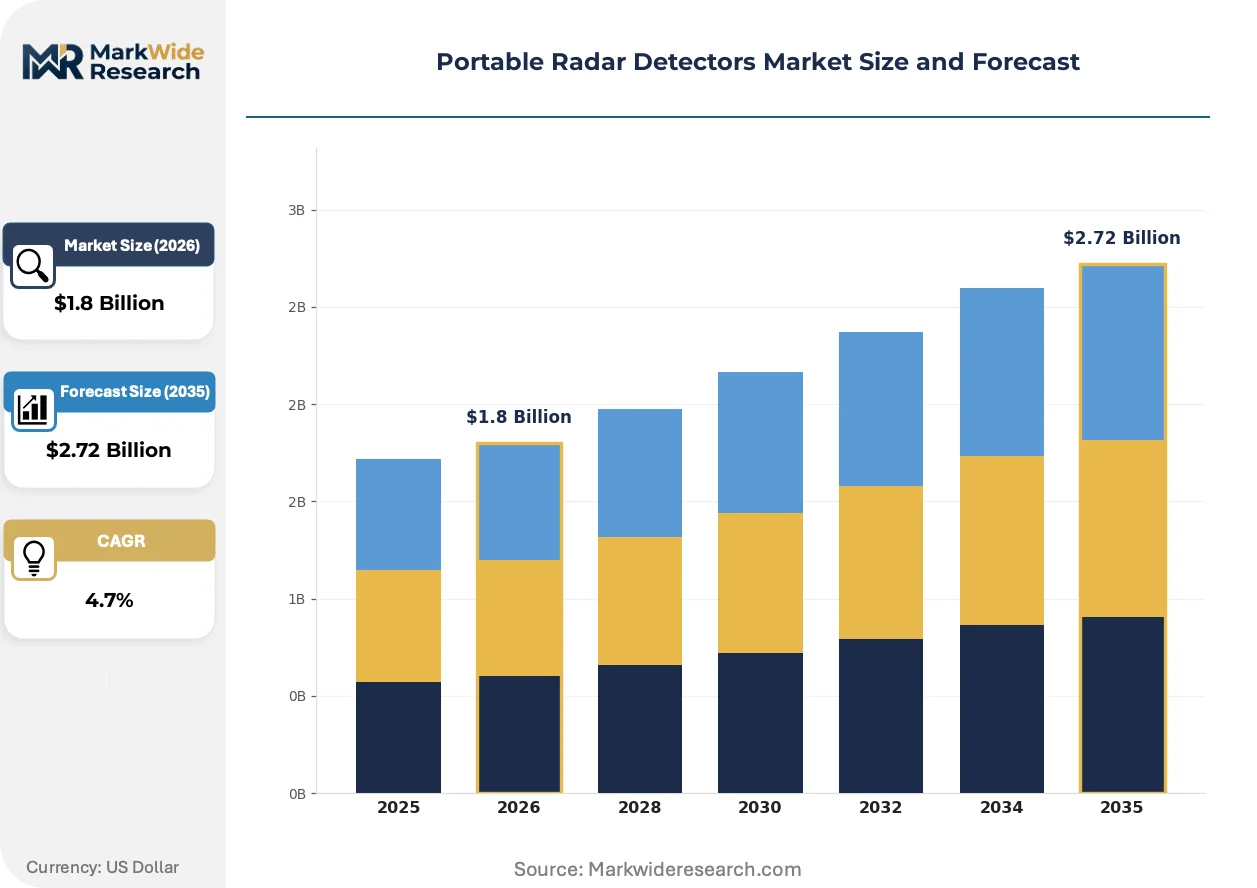
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DSP Detectors, GPS Detectors, Laser Detectors, Wireless Detectors Technology: Ka Band, K Band, X Band, Multispectrum End User: Personal Use, Law Enforcement, Fleet Management, Commercial Users Distribution Channel: Online Retail, Specialty Stores, General Retailers, Direct Sales |
| Companies Covered | Escort Inc., Uniden Corporation, Cobra Electronics Corporation, Valentine Research Inc., Beltronics, Radenso, K40 Electronics, Whistler Group, Rocky Mountain Radar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Radar Detectors Market Evolving Landscape
Detection hardware is pivoting from passive radio reception toward active threat intelligence platforms, with software-defined sensitivity and cloud-connected alert networks displacing standalone analog architectures.
Multispectrum detection modules are expanding into fleet management installations as operators demand unified coverage against Ka-band radar, variable-pulse lidar, and laser-based speed measurement. Logistics coordinators at regional trucking firms are specifying these units in telematics RFPs to consolidate driver safety spend. The technology is expanding into premium consumer segments as enthusiasts seek future-proofing against enforcement protocol upgrades.
NHTSA safety guidelines on windshield mounting locations are compressing form factor flexibility, forcing industrial designers toward rearview mirror clip-ons and dashboard-integrated housings. The restriction most acutely affects compact vehicle owners where cabin geometry limits placement options. Manufacturers are responding with magnetic quick-release systems that satisfy visibility compliance while preserving user portability.
Aftermarket buyers are unbundling hardware purchase from ongoing service contracts, treating threat database subscriptions as discretionary renewals rather than bundled necessities. Direct-to-consumer channels are capturing this shift through annual plan trials that decouple upfront detector cost from recurring alert access. This pattern concentrates among suburban commuters in enforcement-dense corridors where citation risk justifies sustained subscription outlays.
Portable Radar Detectors Market Segmentation
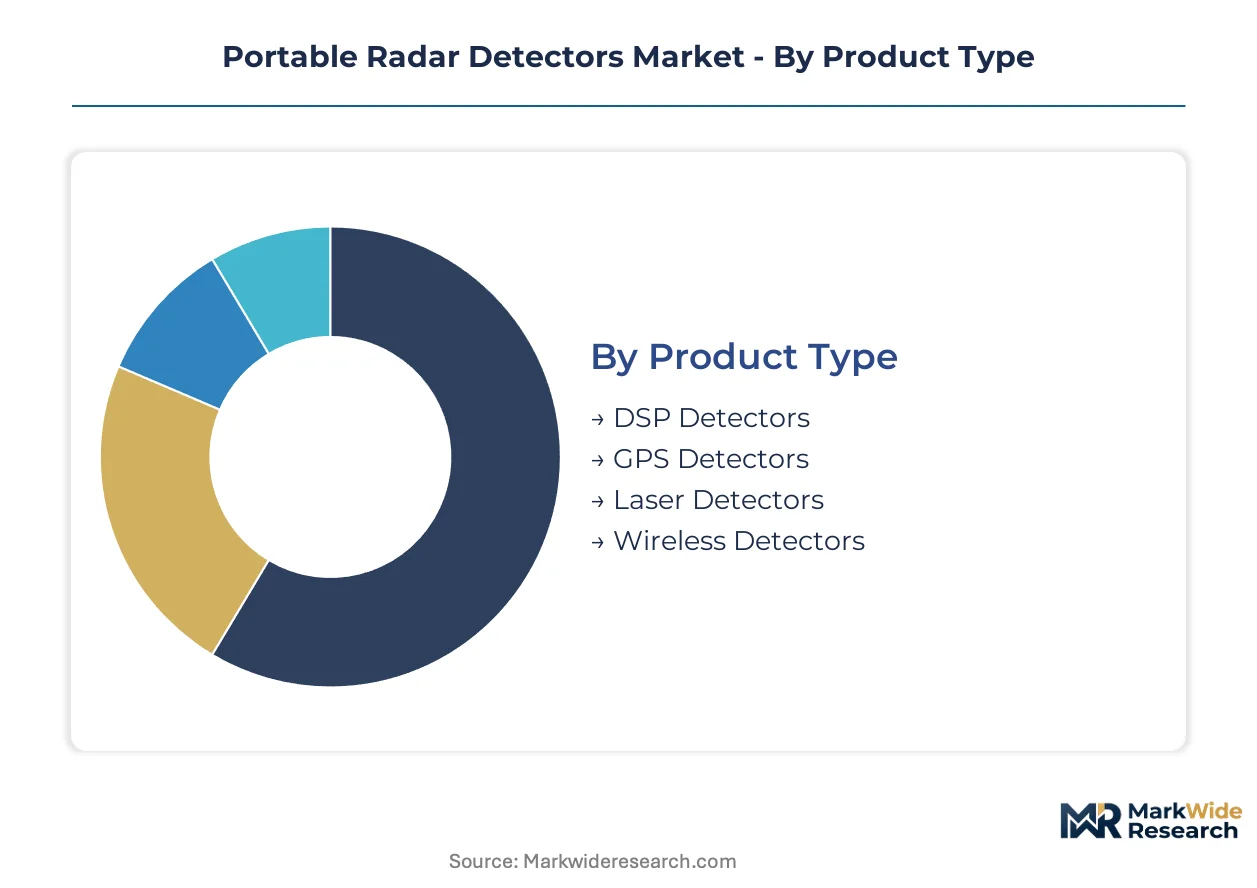
Portable radar detector manufacturers configure product portfolios across four intersecting dimensions that determine sensitivity specifications, pricing architecture, and channel strategy. Each segmentation layer reveals distinct margin profiles and obsolescence risks tied to enforcement technology evolution.
Product Type:
Standardization dominates entry-level hardware while premium tiers embed customizable firmware and modular sensitivity upgrades.
- DSP Detectors:Digital signal processing architectures filter noise through algorithmic pattern recognition, enabling variable-pulse radar detection without hardware swaps. Demand concentrates among long-haul trucking fleets along Interstate corridors where Ka-band enforcement density justifies the processing overhead.
- GPS Detectors:Geofenced alert databases store fixed camera locations and historical enforcement patterns, reducing false positives from retail door sensors. Suburban commuter belts in enforcement-dense counties drive procurement as citation risk elevates subscription willingness.
- Laser Detectors:Photodiode arrays sense 904nm lidar pulses with nanosecond response windows.
- Wireless Detectors:Bluetooth tethering to smartphone displays enables dashboard-agnostic mounting compliant with NHTSA visibility rules.
Leading the category by volume: GPS Detectors. Expanding most quickly: DSP Detectors.
Technology:
Receiver sensitivity specifications stratify by frequency band allocation and pulse modulation complexity, with higher bands commanding component cost premiums.
- Ka Band:Superheterodyne receivers tuned to 33.4-36.0 GHz capture variable-pulse radar deployed by state highway patrols. FCC emission standard enforcement pushes hardware makers toward gallium arsenide low-noise amplifiers that maintain detection range against attenuated signals.
- Multispectrum:Unified detection modules spanning radio frequency and photonic domains consolidate driver safety spend for fleet operators. Logistics coordinators specify these units in telematics RFPs to future-proof against enforcement protocol upgrades.
- K Band:24.05-24.25 GHz reception targets older stationary radar installations still active in municipal jurisdictions.
- X Band:10.525 GHz hardware faces obsolescence as law enforcement agencies retire aging speed measurement systems.
Capturing the largest installed base: Ka Band. Climbing the fastest: Multispectrum.
End User:
Procurement authority and liability exposure create divergent specification requirements across consumer and institutional buyers.
- Fleet Management:Corporate liability programs embed driver safety alerts directly into dispatch platforms, creating bundled procurement pull-through. Long-haul trucking operators specify multispectrum hardware with telematics integration to reduce insurance penalty exposure.
- Personal Use:Enthusiast-grade units dominate premium positioning through direct-to-consumer channel control. Direct sales bypass retail margin extraction while sustaining firmware subscription attach rates.
- Law Enforcement:Counter-detection and calibration equipment serves agency technical services divisions.
- Commercial Users:Ride-share and delivery contractors in citation-risk corridors drive entry-level GPS detector demand.
Dominating revenue concentration: Fleet Management. Gaining share fastest: Personal Use.
Distribution Channel:
Channel selection determines subscription attach rates and warranty service obligations, with direct relationships sustaining recurring revenue models.
- Direct Sales:Manufacturer-controlled channels decouple hardware purchase from ongoing service contracts, enabling annual plan trials that improve retention. Valentine Research leverages this structure to dominate enthusiast-grade positioning without retail margin dilution.
- Online Retail:E-commerce platforms aggregate comparison shopping for specification-sensitive buyers, concentrating demand for sensitivity threshold documentation. Amazon and specialty automotive sites capture suburban commuter procurement patterns.
- Specialty Stores:Installation services and hands-on demonstration sustain premium tier throughput in enforcement-dense metropolitan areas.
- General Retailers:Big-box automotive sections move entry-level units with minimal sales assistance.
Highest volume throughput: Online Retail. Steepest expansion trajectory: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portable radar detector manufacturing concentrates among defense-electronics contractors in the United States, while consumption patterns diverge sharply between enforcement-dense jurisdictions and prohibition zones. The FCC's spectrum governance shapes component sourcing decisions across North American assembly facilities.
United States
Long-haul trucking corridors through Texas and Florida drive fleet procurement of multispectrum hardware with telematics integration. The FCC enforces electromagnetic emission standards under Part 15 rules that constrain receiver sensitivity thresholds. Suburban commuter belts around Atlanta and Dallas-Fort Worth concentrate GPS-enabled detector demand among insurance-conscious professionals.
Canada
Cross-border logistics operators along the Windsor-Quebec City corridor purchase hardware compliant with both FCC and Industry Canada emission specifications. Health Canada coordinates spectrum allocation with Transport Canada vehicle safety guidelines. The Greater Toronto Area anchors retail distribution through specialty automotive chains serving Ontario's enforcement-monitored highways.
Germany
Aftermarket accessory distributors in Bavaria and Baden-Württemberg supply detector hardware to international travelers despite domestic Autobahn speed enforcement relying on camera systems rather than radar. The KBA enforces strict electromagnetic compatibility certification for automotive electronics. Stuttgart's automotive engineering cluster influences industrial design standards for European-market form factors.
United Kingdom
Enthusiast import channels in London and the Southeast source premium detectors for track-day and continental driving applications. The Driver and Vehicle Licensing Agency maintains distinct enforcement protocols that limit domestic radar deployment. Specialist retailers in Birmingham and Manchester service the remaining demand from motorists crossing into jurisdictions with active speed measurement.
Australia
State highway patrols in Victoria and New South Wales deploy Ka-band and lidar systems that drive sensitivity requirements for imported hardware. The Australian Communications and Media Authority regulates 33.4-36.0 GHz receiver compliance through radiocommunications licensing. Sydney's eastern suburbs and Melbourne's outer commuter rings concentrate demand among drivers facing demerit point accumulation.
Portable Radar Detectors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the portable radar detector sector, with vertically integrated RF specialists maintaining captive gallium arsenide foundry relationships while fabless competitors outsource microwave component fabrication. The vendor structure fragments across three tiers: multinational electronics conglomerates with broad automotive portfolios, dedicated detector specialists controlling direct-to-consumer channels, and regional assemblers serving price-sensitive fleet accounts. Two dominant competitive moves define current positioning: subscription firmware services that convert hardware sales into recurring revenue streams, and multispectrum module development that future-proofs against lidar protocol upgrades.
Among North American specialists, Escort Inc. and Valentine Research Inc. occupy positions at opposite ends of the channel strategy spectrum, with the former exemplifying database-driven subscription retention and the latter representing enthusiast-grade direct sales without retail margin dilution. Uniden Corporation anchors the mid-tier volume position through consumer electronics distribution scale. These three entities collectively illustrate how sensitivity specification competition, firmware service attach rates, and mounting compliance industrial design constitute the primary vectors of differentiation in this hardware category.
| Leading Market Players |
|---|
| Escort Inc. |
| Uniden Corporation |
| Cobra Electronics Corporation |
| Valentine Research Inc. |
| Beltronics |
| Radenso |
| K40 Electronics |
| Whistler Group |
| Rocky Mountain Radar |
| Others |
Value Network & Pricing Analysis
Multispectrum module adoption is compressing component economics while concentrating procurement leverage among gallium arsenide foundry operators in the United States and Taiwan. This technological transition simultaneously elevates receiver sensitivity thresholds and fragments sourcing options for high-frequency semiconductor inputs.
Pricing Analysis
Cost-down pressure on entry-tier hardware accelerates because smartphone app substitution erodes casual user willingness to pay upfront premiums. Pricing stratifies across enthusiast-grade direct sales, mid-tier consumer electronics channels, and fleet procurement bundles. Sensitivity specifications and firmware subscription attach rates drive differentiation, with corporate buyers exhibiting lowest price sensitivity due to liability reduction mandates.
Supply Chain Analysis
FCC Part 15 certification gates access to United States distribution, constraining qualified suppliers to domestic and Taiwanese RF specialists with proven electromagnetic compliance records. Gallium arsenide low-noise amplifiers, photodiode arrays, and DSP chipsets anchor bill-of-materials exposure. Single-source vulnerability concentrates in semiconductor foundry capacity allocation. Distribution runs through direct manufacturer channels, specialty automotive retailers, and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frequency-hopping lidar deployment by state highway patrols is forcing hardware refresh cycles that weaker capitalized players cannot sustain, creating consolidation pressure across the vendor base.
For Market Incumbents: Deploy subscription firmware services to convert transactional hardware revenue into recurring annual plans. Escalate multispectrum R&D investment to maintain sensitivity leadership against variable-pulse lidar protocols. Consolidate gallium arsenide foundry relationships through long-term supply agreements that lock in receiver chip allocation ahead of capacity constraints. For New Entrants and Emerging Players: Begin with insurance partnership channels in Texas and Florida where usage-based auto insurers pilot detector rebates as loss-prevention incentives. Target fleet management telematics integrators seeking bundled driver safety procurement. Pursue white-label manufacturing for established automotive aftermarket brands lacking in-house RF engineering capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by consumer electronics conglomerates seeking automotive aftermarket diversification. Long-term viability hinges on subscription attach rate sustainability and multispectrum technology transition timing. Monitor municipal lidar protocol adoption rates as the critical inflection signal for hardware obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Firmware Service Launch | Transforms Escort Inc.'s Defender database into recurring revenue retention engine. |
| Multispectrum Module Development | Future-proofs Uniden Corporation against Ka-band radar and variable-pulse lidar upgrades. |
| Direct-to-Consumer Channel Expansion | Preserves Valentine Research Inc.'s enthusiast-grade margins without retail dilution. |
| Fleet Telematics Integration Partnership | Embeds driver safety alerts into dispatch platforms for long-haul trucking procurement. |
| Gallium Arsenide Foundry Supply Agreement | Secures low-noise amplifier allocation against semiconductor capacity constraints. |
Research Methodology
Document review covered FCC spectrum allocation rulings, NHTSA safety guideline filings, and state-level enforcement protocol disclosures, complemented by interviews with RF engineering directors at detector manufacturers, fleet telematics procurement coordinators, and specialty automotive retail buyers. Secondary sources included SEC 10-K filings from consumer electronics conglomerates, customs import records for gallium arsenide components, and telecommunications regulatory databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Historical volume patterns were cross-referenced against expert panel inputs regarding lidar protocol adoption timelines. The analytical framework modeled demand across product type, technology band, end-user category, and distribution channel dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate distributions weighted by enforcement technology deployment density and fleet telematics integration penetration.
State-level prohibition expansion, FCC emission standard tightening, and gallium arsenide foundry capacity constraints are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding enforcement technology upgrade cadence and subscription service attach rate sustainability. A model refresh is warranted upon material change in municipal lidar protocol adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Electronic Article Surveillance Market
Detection and Regulation Devices
Digital Attenuators Market