
 Hydrogen Detection Transmitters Market | 2026-2036
Hydrogen Detection Transmitters Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Detection Transmitters Market Insights
Aftermarket service revenue is reshaping margin pools in the hydrogen detection transmitters landscape, pulling value from hardware sales toward calibration contracts and sensor replacement programs. Honeywell International leverages its distributed service network to capture recurring revenue from installed base maintenance. Teledyne Technologies anchors its position through R&D intensity in optical sensing architectures. Drägerwerk AG & Co. KGaA dominates European safety certification channels with specialized industrial gas detection expertise.
Hydrogen detection transmitters are electromechanical instruments that convert hydrogen gas concentration into standardized output signals, typically operating across detection ranges from parts-per-million to percentage lower explosive limit thresholds for continuous area monitoring and process safety shutdown systems. Fixed transmitters constitute the mature revenue base in petrochemical complexes and hydrogen fueling stations, while wireless transmitters represent the fastest-growing configuration as plants retrofit cable-constrained zones and embrace Industrial Internet of Things architectures. Electrochemical sensors retain cost advantages for general-purpose leak detection, though optical sensors are displacing legacy technologies in applications demanding immunity to poisoning and cross-sensitivity interference.
FDA oversight applies where transmitters interface with pharmaceutical hydrogenation processes, while OSHA process safety management standards mandate continuous monitoring in facilities exceeding hydrogen threshold quantities. The EU AI Act introduces conformity requirements for smart transmitters incorporating machine-learning-based alarm prioritization, complicating market access for non-compliant architectures. Stakeholders must monitor evolving interoperability standards between detection systems and plant distributed control networks as hydrogen infrastructure scales beyond pilot demonstrations.
Market Dynamics
Retrofit mandates across Germany's Ruhr industrial cluster and the Netherlands' Rotterdam port complex are forcing simultaneous upgrades of legacy safety systems, compressing installation timelines and reshaping vendor qualification criteria.
Growth Catalysts
- EU Green Deal hydrogen infrastructure mandates:National hydrogen strategies in France, Germany, and the Netherlands require continuous leak detection at all production and storage facilities, creating baseline demand for fixed transmitter installations.
- Industrial Internet of Things architectures:Petrochemical complexes are retrofitting cable-constrained zones with wireless transmitter configurations to enable real-time data integration into plant distributed control networks.
- Ruhr industrial cluster expansion:Refineries and chemical plants in this concentrated geography are systematically replacing electrochemical sensors with optical architectures immune to poisoning.
Market Restraints
- Platinum catalyst cost volatility:Electrochemical sensor production depends on platinum-group metal inputs subject to supply disruption from South African mining concentration.
- Optical sensor technical limitation:Tunable diode laser absorption spectroscopy remains unable to detect hydrogen at sub-ppm concentrations required for semiconductor cleanroom applications.
- EU AI Act conformity friction:Smart transmitters incorporating machine-learning-based alarm prioritization face extended certification timelines and documentation burdens.
Strategic Opportunities
- Underpenetrated pharmaceutical hydrogenation:FDA-regulated facilities in Ireland and Switzerland lack standardized detection protocols, creating first-mover advantage for certified system integrators.
- Green hydrogen export hubs:Port of Rotterdam and Wilhelmshaven terminal projects require marine-grade transmitters with salt-corrosion resistance specifications.
- CE marking convergence with IECEx:Dual certification streamlining reduces vendor qualification costs for equipment suppliers serving both EU and Asia-Pacific markets.
Industry Challenges
- Optical sensing talent scarcity:Tunable diode laser spectroscopy expertise concentrates in German and Swiss research institutes, constraining production scaling.
- Legacy system integration complexity:4-20 mA analog output transmitters must interface with digital safety instrumented systems through signal converters, adding failure points.
- Sensor calibration skill gap:Electrochemical cell replacement and zero-span adjustment require certified technicians absent in smaller hydrogen fueling station operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Detection Transmitters Market |
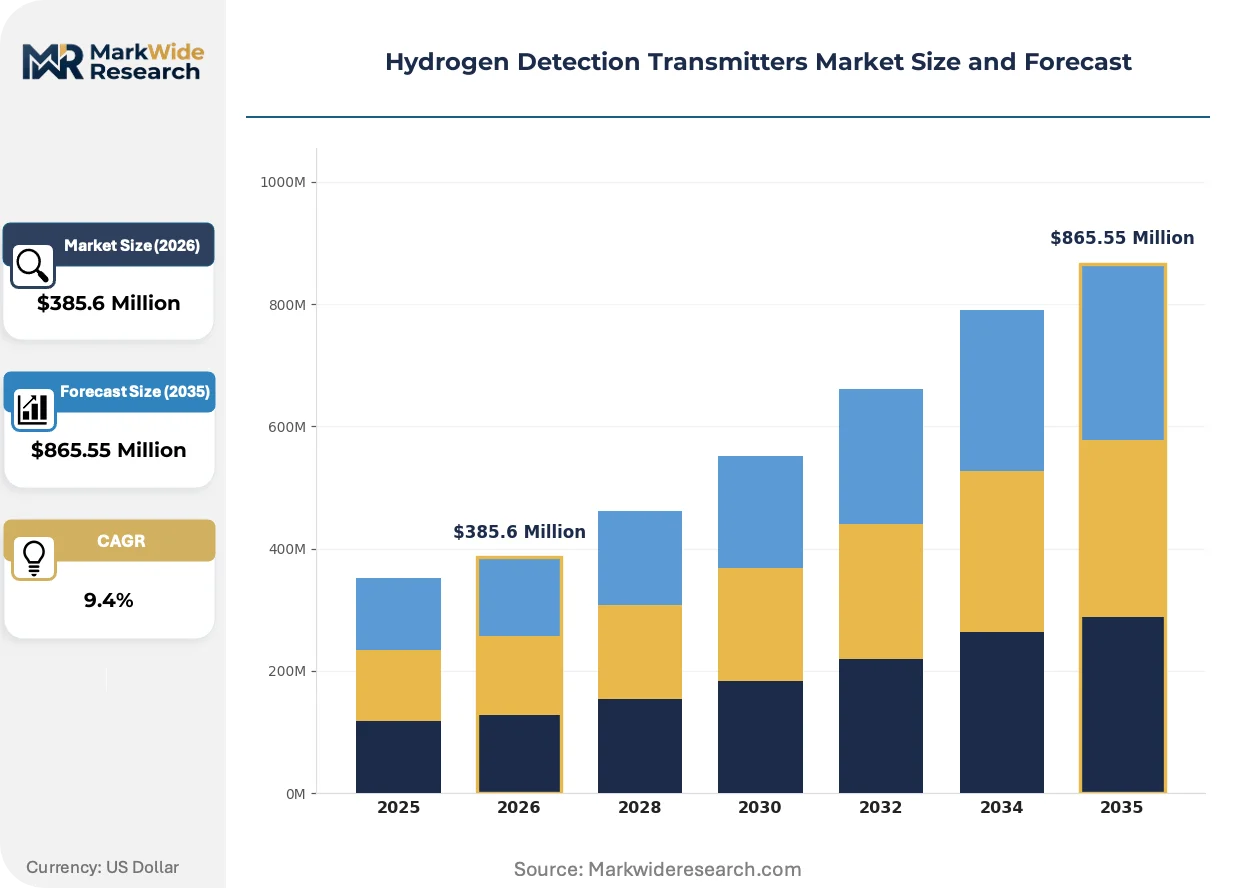
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $865.55 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Transmitters, Portable Transmitters, Wireless Transmitters, High-Temperature Transmitters Technology: Catalytic Sensors, Metal Oxide Sensors, Electrochemical Sensors, Optical Sensors End User: Oil & Gas, Chemical Manufacturing, Automotive, Aerospace Application: Leak Detection, Safety Monitoring, Process Control, Industrial Safety |
| Companies Covered | Honeywell International, Teledyne Technologies, Drägerwerk AG & Co. KGaA, MSA Safety Incorporated, H2Scan Corporation, Figaro Engineering, NevadaNano, Emerson Electric Co., RKI Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Detection Transmitters Market Trends and Innovations
Detection architectures are converging around predictive maintenance capabilities and edge-computing integration, compressing the traditional separation between sensing hardware and plant control systems.
Photonic sensing platforms based on fiber-optic hydrogen sensors are virtualizing the physical detection layer, enabling intrinsic safety in explosive atmospheres without electrical components. Offshore wind-to-hydrogen pilot projects in the North Sea are adopting these architectures for subsea pipeline monitoring. The technology is virtualizing maintenance schedules by eliminating sensor poisoning and drift calibration requirements.
REACH authorization processes for lead-based sensor components are accelerating substitution toward lead-free electrochemical architectures. German chemical manufacturers face supply chain audits documenting compliance with restricted substance thresholds. The regulation most affects portable transmitter configurations where miniaturized lead-acid battery integration has been standard practice.
Buyer concentration among integrated energy majors is compressing vendor qualification cycles and unbundling after-sales service from equipment procurement. EPC contractors at Rotterdam and Hamburg hydrogen terminals now specify separate calibration contract terms. This pattern is most visible in Netherlands-Germany border industrial zones where Shell, Uniper, and RWE coordinate safety standard harmonization.
Hydrogen Detection Transmitters Market Segmentation
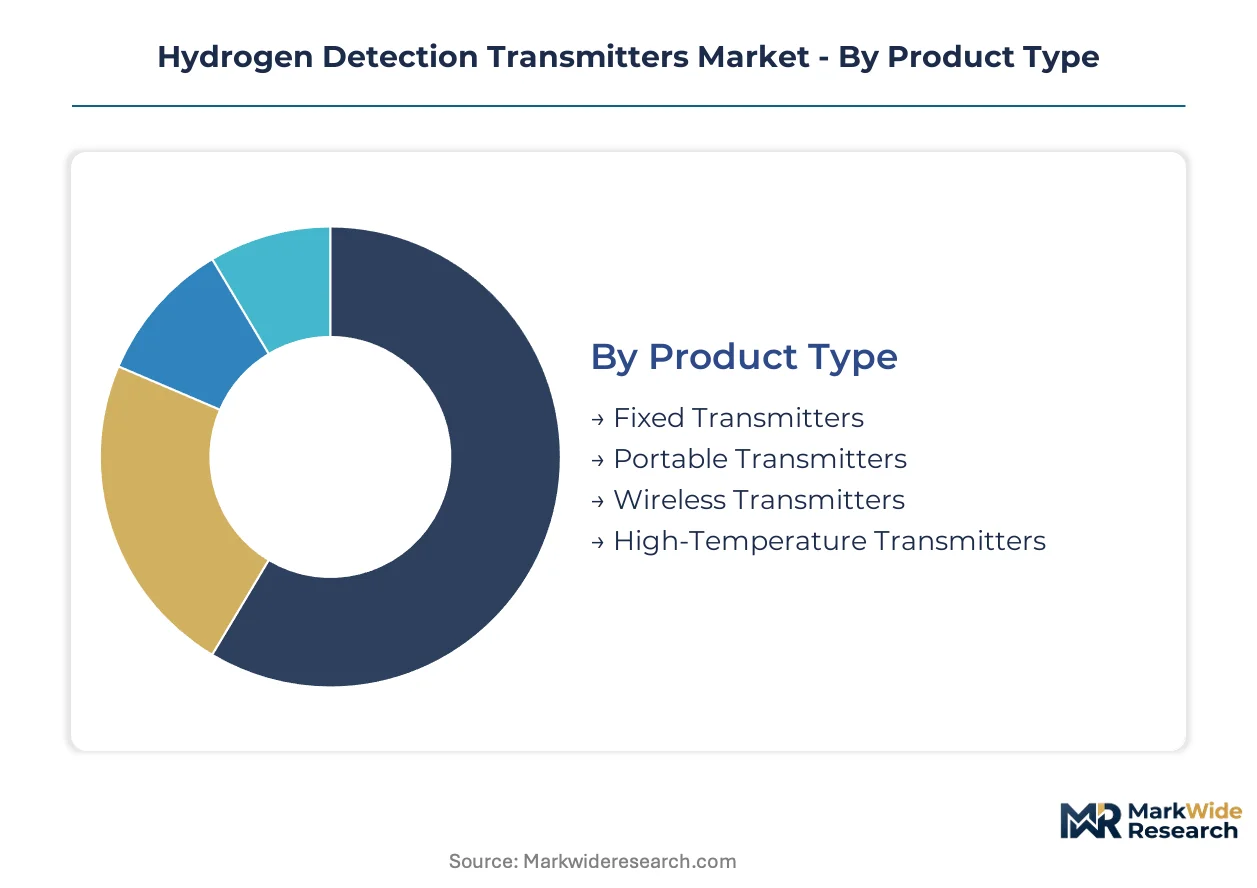
Segmentation in hydrogen detection transmitters reveals divergent replacement cycles that reshape vendor revenue stability. Product configuration and sensing technology determine whether installations generate recurring calibration income or one-time hardware sales.
Product Type:
Fixed transmitters operate on decade-long replacement cycles while portable units turn over every three to five years due to battery degradation and physical wear.
- Fixed Transmitters:Permanently mounted electromechanical instruments with 4-20 mA or digital output integration into plant distributed control systems. Demand concentrates in Germany's Ruhr refineries and Rotterdam hydrogen terminals where EU Green Deal mandates require continuous area monitoring infrastructure.
- Portable Transmitters:Handheld battery-powered units with electrochemical or catalytic sensing heads for spot-checking and confined space entry protocols. Chemical manufacturing facilities in France and the Netherlands deploy these for maintenance turnarounds where fixed coverage gaps exist.
- Wireless Transmitters:Battery-operated mesh-network devices eliminating cable runs in retrofit-constrained zones.
- High-Temperature Transmitters:Specialized units rated for catalytic reformer and steam methane reformer environments exceeding standard operating ranges.
Fixed transmitters anchor the volume base while wireless configurations gain share at the steepest rate.
Technology:
Cost tiers separate legacy electrochemical architectures from premium optical platforms, with platinum catalyst volatility widening the gap.
- Catalytic Sensors:Pellistor-based detection measuring hydrogen combustion on heated platinum catalyst surfaces. Oil & gas operators in Germany favor these for general-purpose leak detection despite susceptibility to silicone poisoning.
- Metal Oxide Sensors:Semiconductor films responding to hydrogen concentration through conductivity changes. Automotive fuel cell testing facilities use these for cost-sensitive bulk monitoring applications.
- Electrochemical Sensors:Amperometric cells with liquid electrolyte and gas-permeable membrane barriers. Chemical plants across the Netherlands and Belgium rely on these for sub-ppm detection thresholds in process safety systems.
- Optical Sensors:Tunable diode laser absorption spectroscopy eliminating cross-sensitivity and calibration drift. Aerospace cleanrooms and semiconductor hydrogenation processes specify these where poisoning immunity justifies premium positioning.
Electrochemical sensors dominate installed unit volumes while optical platforms expand most quickly in certified safety applications.
End User:
Application maturity varies sharply across verticals, with aerospace qualification cycles stretching years while chemical plant procurement compresses to months.
- Oil & Gas:Refineries and underground storage facilities requiring continuous monitoring at hydrogen threshold quantities under OSHA process safety management standards. Rotterdam and Wilhelmshaven terminal projects specify marine-grade configurations with salt-corrosion resistance.
- Chemical Manufacturing:Hydrogenation reactors, ammonia synthesis loops, and methanol production trains demanding SIL-rated safety instrumented systems. German Ruhr cluster facilities are systematically replacing legacy electrochemical units with optical architectures.
- Automotive:Fuel cell vehicle production lines and hydrogen fueling station compliance monitoring.
- Aerospace:Launch vehicle ground support equipment and aircraft fuel cell auxiliary power unit testing.
Chemical manufacturing anchors the volume base while automotive installations climb the fastest as hydrogen fueling infrastructure scales.
Application:
Functional requirements determine sensor specification stringency, with process control demanding precision that leak detection can relax.
- Leak Detection:Area monitoring for fugitive emissions and pipeline rupture identification. Fixed transmitter networks in Netherlands-Germany border industrial zones serve this function under coordinated Shell-Uniper-RWE safety standards.
- Safety Monitoring:Personnel protection through alarm-activated ventilation and evacuation triggers. Pharmaceutical hydrogenation facilities in Ireland and Switzerland lack standardized protocols, creating specification variability.
- Process Control:Closed-loop feedback for hydrogen partial pressure optimization in chemical reactors.
- Industrial Safety:Integrated fire and gas detection systems with SIL 2 or SIL 3 reliability ratings.
Leak detection anchors the volume base while process control applications gain share at the steepest rate as green hydrogen production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's Ruhr cluster show the lowest price elasticity as EU Green Deal mandates compress procurement timelines, while smaller hydrogen fueling station operators in France and the Netherlands exhibit acute sensitivity to upfront hardware costs.
Germany
The Ruhr industrial cluster drives concentrated demand as refineries and chemical plants retrofit legacy electrochemical sensors with optical architectures. EU Green Deal hydrogen infrastructure mandates require continuous leak detection at all production facilities. BASF and ThyssenKrupp operations in Ludwigshafen and Duisburg are systematically upgrading safety instrumented systems ahead of 2026 certification deadlines.
Netherlands
Port of Rotterdam green hydrogen export terminals require marine-grade transmitters with salt-corrosion resistance specifications. The Dutch national hydrogen strategy mandates stricter leak detection protocols at all storage and distribution facilities. Shell and Uniper coordination in the Rotterdam-Hamburg corridor is harmonizing safety standards across border industrial zones.
France
Pharmaceutical hydrogenation facilities in the Île-de-France region lack standardized detection protocols, creating specification variability for FDA-regulated processes. The French national hydrogen strategy aligns with EU AI Act conformity requirements for smart transmitters. Air Liquide's hydrogen production assets in the Paris Basin are piloting machine-learning-based alarm prioritization systems.
United States
OSHA process safety management standards mandate continuous monitoring at hydrogen threshold quantities in Gulf Coast petrochemical complexes. The Inflation Reduction Act hydrogen production tax credits are accelerating electrolyzer deployments requiring integrated detection infrastructure. Texas and Louisiana refineries are expanding fixed transmitter networks to cover new hydrogen fueling corridors.
Japan
METI's hydrogen roadmap targets commercial-scale imports from Australian and Middle Eastern suppliers, driving demand for marine loading and unloading detection systems. JIS standards for gas detection equipment are converging with IECEx certification to streamline vendor qualification. Kobe and Yokohama port authorities are specifying dual-certified transmitters for hydrogen carrier vessel operations.
Hydrogen Detection Transmitters Market Competitive Landscape
Capability concentration sits with specialized optical sensing developers; scale advantage sits with diversified industrial safety conglomerates. The market exhibits a tiered structure where premium optical architectures command margins above commodity electrochemical units. Three archetypes dominate: integrated safety technology conglomerates with distributed service networks, specialized gas detection firms with deep certification expertise, and component-focused sensor developers supplying upstream integrators. Competitive moves center on backward integration into platinum-group metal supply chains and geographic expansion through dual CE marking-IECEx certification strategies.
Within the integrated safety technology tier, Honeywell International and Emerson Electric Co. occupy positions anchored by plant distributed control system integration capabilities. Teledyne Technologies exemplifies the R&D-intensive optical sensing specialist archetype. Drägerwerk AG & Co. KGaA sits within the European safety certification channel specialist tier, leveraging German industrial gas detection heritage. MSA Safety Incorporated represents the North American industrial safety conglomerate model with broad personal protective equipment cross-selling potential.
| Leading Market Players |
|---|
| Honeywell International |
| Teledyne Technologies |
| Drägerwerk AG & Co. KGaA |
| MSA Safety Incorporated |
| H2Scan Corporation |
| Figaro Engineering |
| NevadaNano |
| Emerson Electric Co. |
| RKI Instruments |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Hamburg freight corridors carry platinum-group metals and optical sensor subassemblies from German research institutes to Dutch hydrogen terminals, with logistics cost volatility amplifying margin pressure on electrochemical sensor producers while rewarding vendors with captive calibration service networks.
Pricing Analysis
After-sales calibration contracts and sensor replacement programs now capture the majority of lifetime value in hydrogen detection transmitter deployments. Three-tier pricing structure across premium optical, standard electrochemical, and economy catalytic configurations separates vendors by certification grade and poisoning immunity specifications. Cost compression in economy tiers is intensifying because platinum catalyst volatility squeezes electrochemical margins. Integrated energy majors at Rotterdam and Wilhelmshaven terminals show the lowest price sensitivity, while independent hydrogen fueling station operators in France exhibit acute upfront hardware cost consciousness.
Supply Chain Analysis
Platinum-group metal feedstock draws from South African mining concentration and Russian refining capacity, creating single-source vulnerability for electrochemical sensor production. German and Swiss research institutes anchor optical sensing component supply, while Chinese manufacturers dominate metal oxide semiconductor substrates. Tariff exposure runs through EU carbon border adjustment mechanisms on imported catalyst materials. Distribution runs through EPC contractor procurement channels at major hydrogen terminal projects, with aftermarket service increasingly unbundled from initial equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen detection transmitters market is accelerating through a regulatory inflection as EU AI Act conformity requirements and EU Green Deal infrastructure mandates compress vendor qualification timelines and reshape competitive positioning.
For Market Incumbents: Harden installed base lock-in through predictive maintenance platform integration and captive platinum-group metal supply arrangements. Optical sensing specialists face margin pressure from electrochemical cost compression, requiring certification investment in dual CE marking-IECEx pathways to defend channel position. Backward integration into sensor membrane manufacturing reduces exposure to South African supply disruption. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical hydrogenation facilities across Ireland and Switzerland where FDA-regulated processes lack standardized detection protocols. Wireless transmitter configurations for cable-constrained retrofit zones offer the most penetrable entry point. Partner with regional system integrators holding SIL-rated safety instrumented system certification to bypass direct vendor qualification barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized optical sensing developers with tunable diode laser spectroscopy expertise concentrated in German and Swiss research corridors. Long-term viability hinges on regulatory compliance automation capabilities rather than hardware scale. Monitor EU AI Act implementation timelines as the critical inflection signal for smart transmitter certification backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Platinum-Group Metal Supply | Captive catalyst sourcing insulates electrochemical production from South African mining concentration risk. |
| Dual CE Marking-IECEx Certification Expansion | Streamlined vendor qualification reduces friction for equipment suppliers serving EU and Asia-Pacific markets simultaneously. |
| Predictive Maintenance Platform Development | Machine-learning-based calibration scheduling captures recurring revenue from installed base maintenance contracts. |
| Pharmaceutical Hydrogenation System Integration | FDA-regulated facility partnerships in Ireland and Switzerland address underpenetrated safety protocol standardization gaps. |
| Wireless Mesh Network Architecture Deployment | Battery-operated retrofit configurations eliminate cable installation constraints in legacy plant distributed control system upgrades. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant safety engineers at Ruhr cluster refineries, EPC procurement leads at Rotterdam hydrogen terminals, pharmaceutical facility managers in Ireland and Switzerland, and aftermarket service technicians at German chemical manufacturers. Secondary validation drew from EU Green Deal implementation documents, OSHA process safety management guidance, SEC filings of listed industrial safety conglomerates, and customs data on platinum-group metal import flows. Bottom-up unit economics and top-down market sizing were triangulated to constrain variance.
Calibration against historical electrochemical sensor replacement cycles and optical platform adoption curves anchored volume projections across the analysis window. Segmentation modeling incorporated product configuration, sensing technology, end-use vertical, and application function dimensions. CAGRs were derived from fitted growth curves adjusted for regulatory mandate implementation timelines and platinum price scenario inputs.
Sensitivities concentrate around EU AI Act certification timeline delays, platinum-group metal supply disruption from South African mining concentration, and optical sensing talent scarcity constraining production scaling. Cross-checking against IECEx certification database growth rates and hydrogen terminal project announcement pipelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Frequency Counter Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
IR Detector Market
Detection and Regulation Devices
EMEA Frequency Control and Timing Devices Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Arc Fault Detection Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Automated Number Plate Recognition (ANPR) and Detection Sensors Market