
 Singapore Data Center Processor Market | 2026-2036
Singapore Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Data Center Processor Market Insights
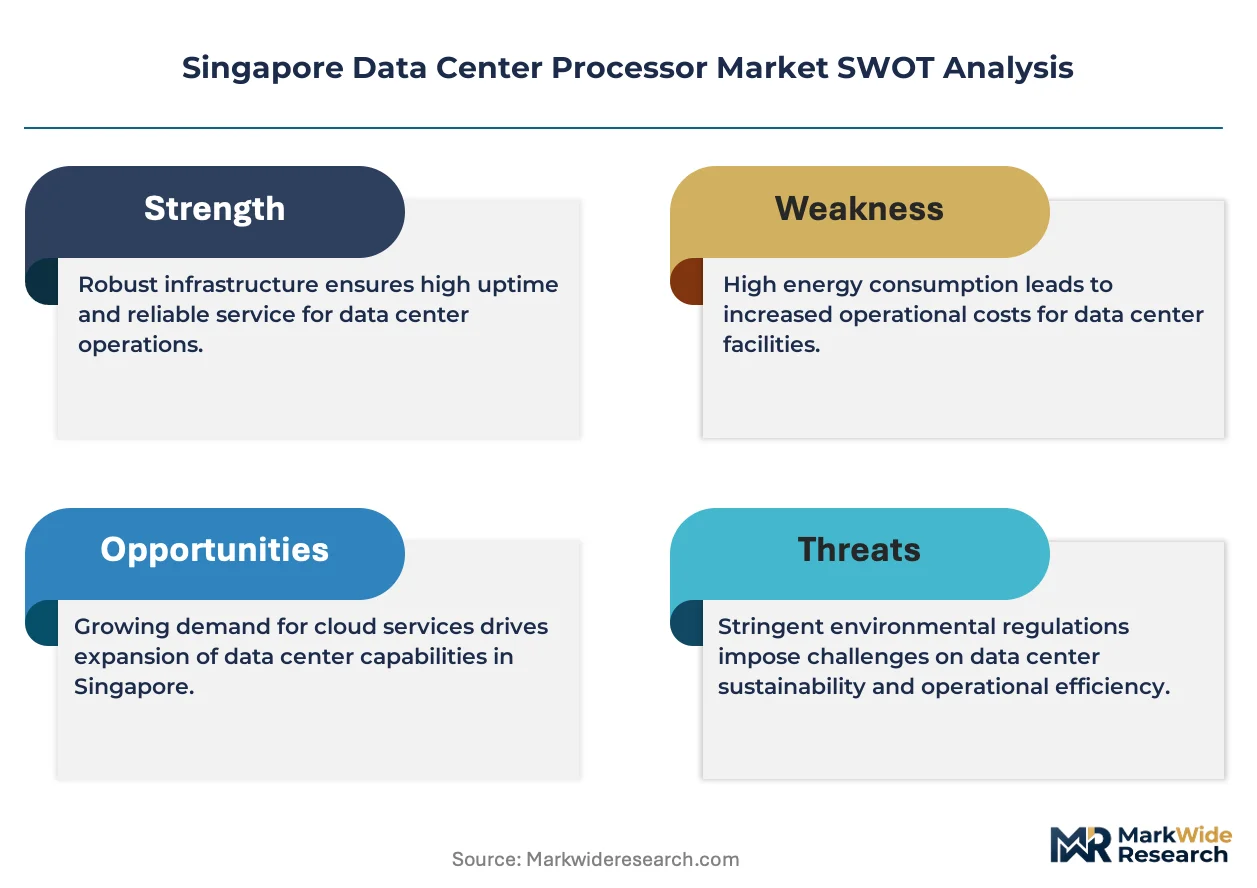
Platform licensing revenue is tilting toward AI-optimized accelerator ecosystems as cloud operators seek tighter hardware-software coupling. NVIDIA Corporation dominates training-class GPU supply through its CUDA software moat. Intel Corporation competes via its foundry partnerships and x86 server CPU refresh cycles. AMD sustains pressure in high-core-count server processors with its EPYC architecture.
A data center processor is a semiconductor device engineered for parallel computation, thermal resilience above 80°C junction temperatures, and 24/7 reliability in rack-dense environments, purpose-built to execute virtualization, database, and machine learning workloads at datacenter scale. CPU configurations still anchor mainstream enterprise deployments, yet GPU segments are capturing the fastest expansion as generative AI training clusters multiply across Singapore's colocation facilities. Rack-mounted form factors lead volume shipments, though modular designs are gaining traction among operators pursuing phased capacity expansion.
Singapore's Infocomm Media Development Authority (IMDA) imposes sustainability benchmarks on new data center approvals, while the Building and Construction Authority enforces Green Mark standards that elevate cooling efficiency requirements for processor-intensive facilities. The central bank's risk management guidelines for technology infrastructure further shape procurement rigor among financial services end users. Stakeholders must weigh sovereign AI ambitions against land and power constraints when calibrating processor mix and facility location decisions.
Market Dynamics
Generative AI training clusters are compressing processor refresh cycles and concentrating procurement authority within hyperscale cloud operators, fundamentally restructuring vendor relationships and facility design priorities across Singapore's data center corridor.
Growth Catalysts
- IMDA Sustainability Benchmarks:Singapore's Infocomm Media Development Authority mandates energy efficiency thresholds for new data center approvals, accelerating adoption of liquid-cooled processor architectures and high-density rack configurations.
- AI Inference Workload Surge:Financial services and enterprise SaaS operators are deploying GPU-accelerated inference nodes at scale, driving demand for heterogeneous compute fabrics in Jurong and Tuas facilities.
- Green Mark Certification Premium:The Building and Construction Authority's Green Mark standards reward facilities achieving superior power usage effectiveness, incentivizing processor selections optimized for thermal resilience above 80°C junction temperatures.
Market Restraints
- Advanced Packaging Bottleneck:CoWoS and HBM supply concentration in Taiwan constrains GPU and AI accelerator availability, extending lead times for Singapore-based deployments.
- Land and Power Scarcity:Singapore's moratorium on new data center capacity between 2019 and 2022 created persistent queue congestion, limiting greenfield processor deployment opportunities.
- Carbon Border Adjustments:Anticipated EU carbon border mechanisms threaten to increase effective costs for processor imports sourced from carbon-intensive manufacturing regions.
Strategic Opportunities
- Subsea Cable Interconnection:Singapore's position as a cable landing hub creates arbitrage opportunities for processor-heavy workloads serving ASEAN markets from low-latency facilities.
- Sovereign AI Infrastructure:Government-led AI development initiatives are opening dedicated procurement channels for domestic cloud operators, bypassing hyperscale concentration.
- Modular Data Center Formats:Phased deployment models allow operators to match processor procurement to actual workload ramp, reducing stranded capacity risk in power-constrained environments.
Industry Challenges
- Specialized Thermal Engineering Talent:Liquid cooling and immersion system design expertise remains scarce in Singapore's labor pool, constraining deployment velocity for high-TDP processor generations.
- Multi-Vendor Integration Complexity:Heterogeneous compute environments combining x86 CPUs with GPU accelerators from different suppliers introduce firmware and orchestration compatibility burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Data Center Processor Market |
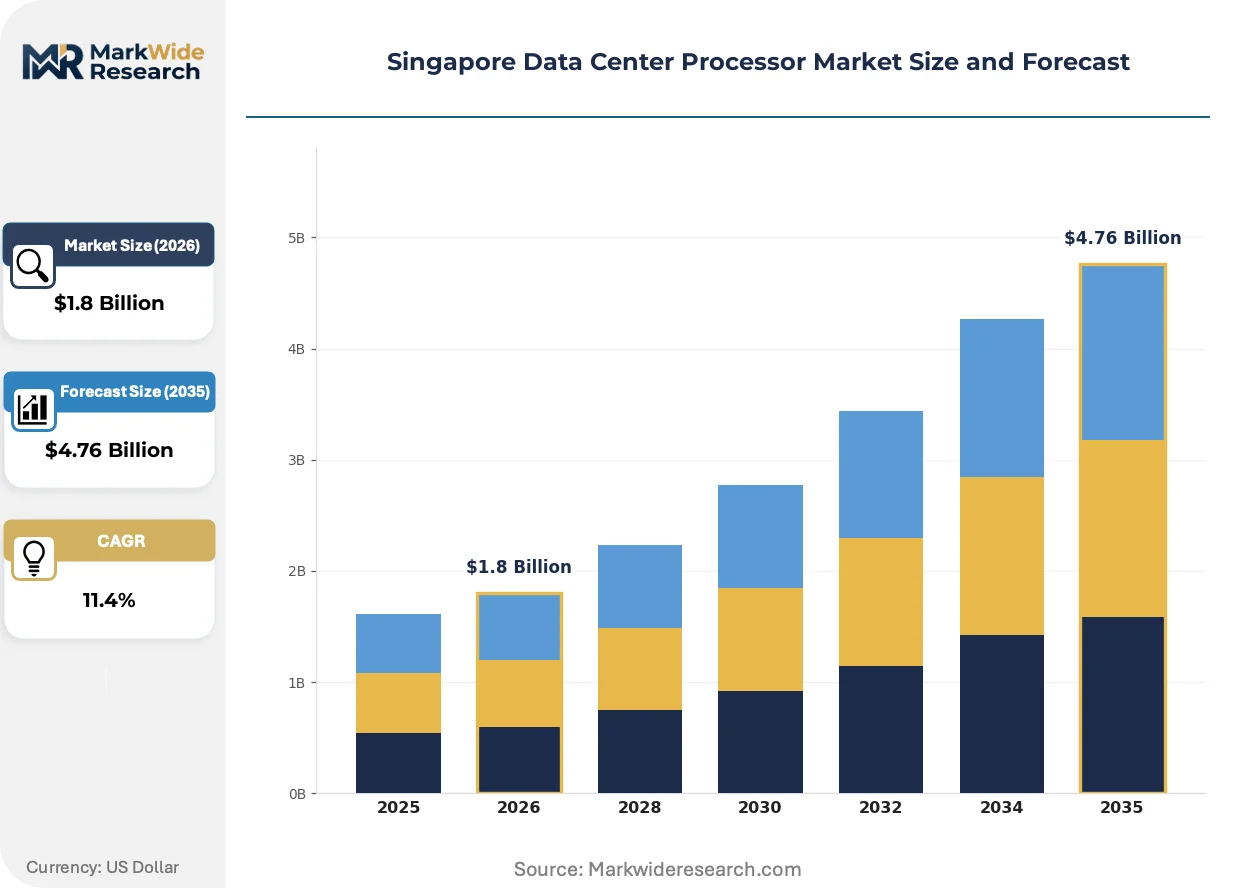
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: CPU, GPU, FPGA, ASIC End User: Cloud Service Providers, Colocation Providers, Enterprises, Government Form Factor: Rack Mounted, Blade, Modular, Tower Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Intel Corporation, GlobalFoundries U.S. Inc., NVIDIA Corporation, Qualcomm Incorporated, Advanced Micro Devices Inc., Micron Technology, Arm Holdings, Broadcom Inc., Marvell Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Data Center Processor Market Trends and Innovations
Processor architecture decisions are increasingly decoupled from traditional server refresh cycles, with procurement timelines now synchronized to AI model training roadmaps and sovereign cloud deployment schedules rather than enterprise IT budgets.
Chiplet-based designs are migrating from niche high-performance computing applications into mainstream data center deployments. Hyperscale operators in Singapore's Tuas corridor are qualifying multi-die processor packages for production inference workloads. This migration from monolithic silicon is enabling tighter customization of compute-memory ratios and compressing time-to-market for workload-optimized silicon.
Singapore's IMDA data center standards are tightening carbon intensity disclosure requirements for new facility approvals. Operators must now document embodied carbon in processor supply chains and demonstrate circular economy commitments for end-of-life hardware. Financial services end users, governed by the Monetary Authority of Singapore's technology risk management guidelines, are prioritizing vendors with transparent Scope 3 emissions reporting.
Cloud repatriation signals are emerging among regulated enterprises dissatisfied with hyperscale pricing volatility and data sovereignty constraints. Singapore-based colocation providers are capturing this demand through bare-metal processor leasing models that preserve operational control. This pattern is most visible in healthcare and government verticals, where procurement committees favor contractual structures that decouple hardware ownership from infrastructure management.
Singapore Data Center Processor Market Segmentation
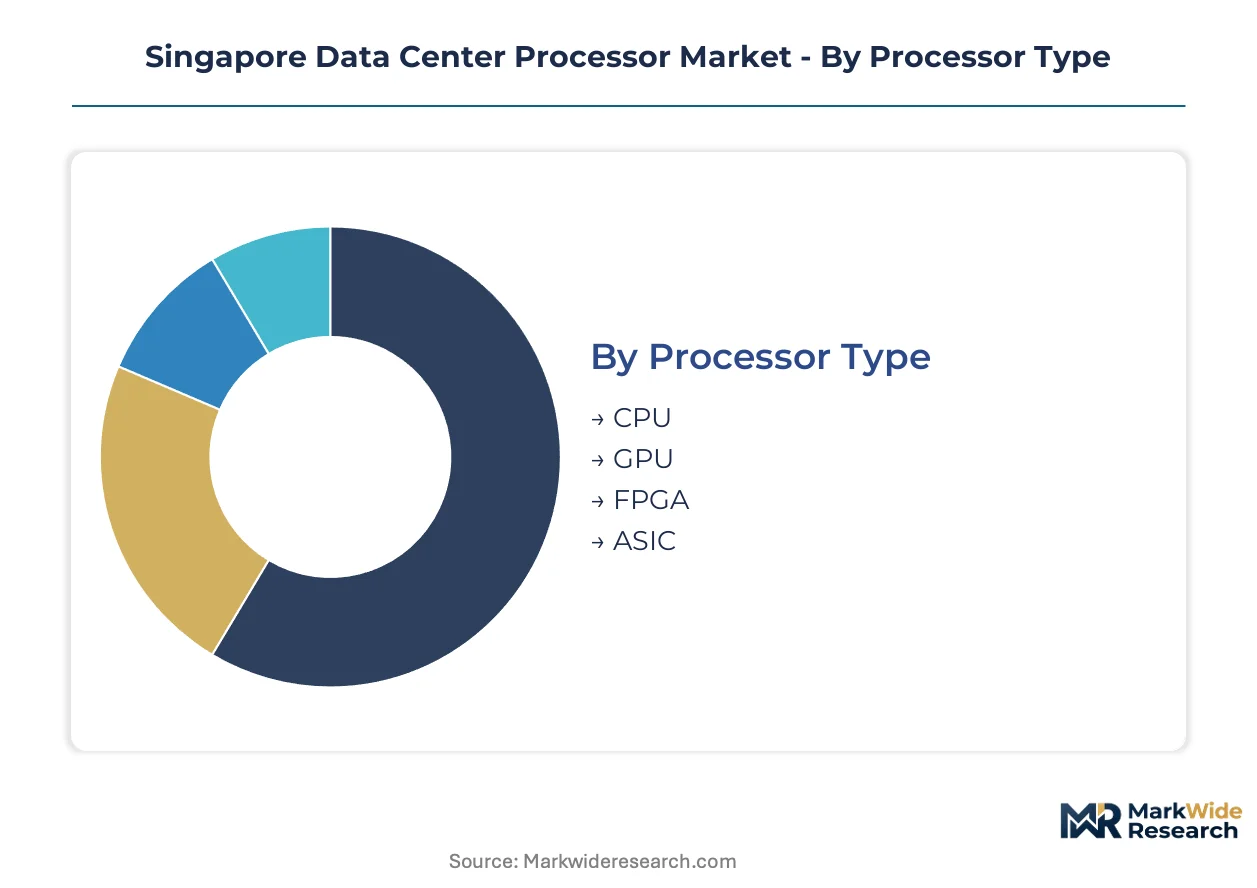
Processor segmentation in Singapore reflects the tension between established x86 architectures and emerging AI-optimized silicon. Procurement committees weigh thermal constraints against workload parallelism when mapping specifications to facility capabilities across Jurong and Tuas clusters.
Processor Type:
Mature general-purpose designs coexist with emerging domain-specific accelerators, each occupying distinct positions in the workload hierarchy.
- CPU:x86 architectures anchor enterprise virtualization and database workloads with proven reliability metrics. Financial services operators in Singapore's central business district favor these configurations for transactional systems requiring deterministic latency. Colocation facilities report steady refresh cycles aligned with Intel and AMD server platform roadmaps.
- GPU:Parallel tensor cores enable training and inference for generative AI models at datacenter scale. Cloud service providers in Tuas are deploying NVIDIA H100 and AMD MI300 clusters under IMDA sustainability benchmarks that reward liquid-cooled deployments. Supply constraints from CoWoS packaging bottlenecks extend procurement lead times.
- FPGA:Reconfigurable logic suits low-latency financial trading and network function virtualization. Singapore Exchange participants deploy these for tick-to-trade optimization.
- ASIC:Custom silicon from Google TPU and Amazon Trainium delivers inference efficiency at hyperscale. Sovereign AI initiatives are evaluating domestic design partnerships.
CPU handles the majority of throughput; GPU is the fastest mover on share.
End User:
Customer type determines procurement volume, contract structure, and technical specification rigor.
- Cloud Service Providers:Hyperscale operators negotiate direct silicon supply agreements with foundries and fabless designers. AWS, Microsoft Azure, and Google Cloud dominate rack space in Singapore's purpose-built facilities, driving demand for high-TDP accelerators and custom cooling infrastructure.
- Colocation Providers:Equinix, ST Telemedia Global Data Centres, and Keppel Data Centres offer bare-metal leasing that preserves tenant processor selection flexibility. These operators are capturing cloud repatriation demand from regulated enterprises seeking operational control without capital ownership.
- Enterprises:Banking and healthcare verticals prioritize vendors with transparent Scope 3 emissions reporting under MAS technology risk guidelines.
- Government:Smart Nation infrastructure and defense applications specify sovereign supply chain requirements and local support presence.
Cloud service providers command the largest procurement volumes; government is expanding fastest as sovereign AI programs accelerate.
Form Factor:
Physical packaging choices reflect facility power density and phased deployment strategies.
- Rack Mounted:Standard 19-inch enclosures dominate hyperscale deployments with predictable thermal and power distribution. Jurong facilities have standardized on 52U and 58U configurations to maximize floor plate efficiency.
- Modular:Prefabricated units enable rapid scaling in power-constrained environments. Tuas operators deploy these for GPU-heavy inference clusters where workload ramp timing remains uncertain.
- Blade:High-density shared infrastructure suits enterprise consolidation projects with mixed workload profiles.
- Tower:Edge and small-scale deployments persist in research and development environments.
Rack mounted maintains the installed base; modular is climbing the fastest as operators manage stranded capacity risk.
Power Rating:
Thermal design power thresholds segment processor selection by cooling infrastructure investment and energy cost exposure.
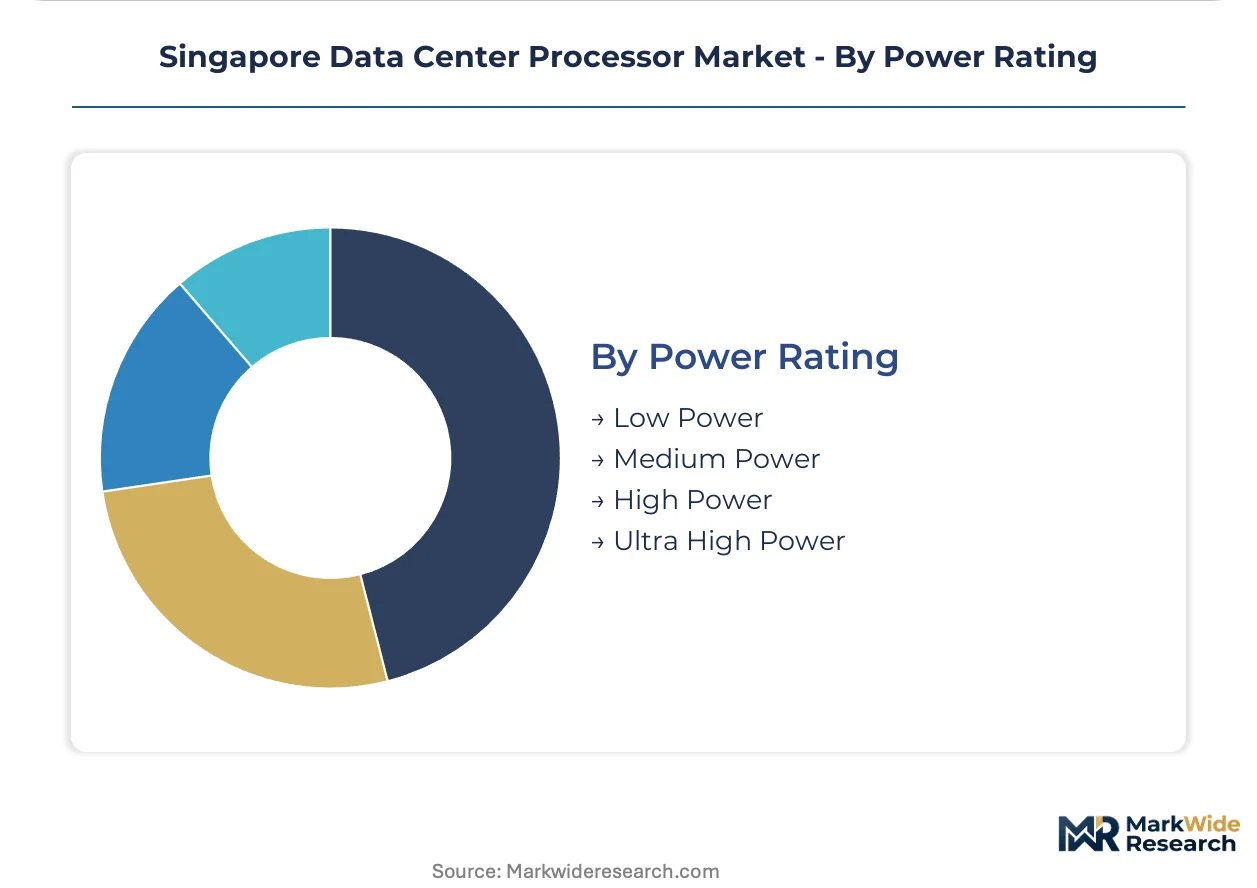
- High Power:Processors exceeding 350W TDP require liquid cooling or immersion systems. Singapore's Green Mark certification rewards facilities achieving superior power usage effectiveness through these deployments.
- Ultra High Power:Next-generation AI accelerators surpass 700W, demanding specialized thermal engineering talent scarce in Singapore's labor pool.
- Medium Power:150-350W range balances performance with air-cooled infrastructure compatibility.
- Low Power:Under 150W designs serve edge inference and legacy enterprise workloads.
High power absorbs the dominant share of capital expenditure; ultra high power shows the steepest expansion trajectory as training clusters scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's data center processor consumption diverges from regional peers through its hyperscale concentration and sovereign AI procurement channels, whereas neighboring markets spread demand across enterprise colocation and edge deployments. Malaysia and Indonesia absorb spillover capacity from Singapore's land constraints, while Vietnam and Thailand attract manufacturing-linked investments.
Malaysia
Johor's Iskandar region hosts GPU clusters serving Singapore-overflow demand from cloud operators seeking lower land costs. Malaysia's national investment authority offers tax incentives for data center developments exceeding 500MW capacity. Cyberjaya and Kulai house expanding facilities where operators deploy air-cooled processors for enterprise workloads.
Indonesia
Batam's free trade zone captures transshipment-sensitive compute workloads requiring proximity to Singapore's cable landing stations. Indonesia's Ministry of Communication and Informatics regulates data localization requirements for financial services data. Jakarta's Cikarang industrial corridor attracts modular data center deployments with medium-power processor configurations.
Vietnam
Ho Chi Minh City and Hanoi drive demand for cloud infrastructure serving manufacturing digitization and e-commerce platforms. Vietnam's cybersecurity law mandates domestic data storage for select industries, stimulating local facility construction. Bac Ninh and Thai Nguyen provinces host processor-intensive facilities supporting electronics supply chain analytics.
Thailand
Eastern Economic Corridor provinces Chonburi and Rayong attract data center investments linked to automotive and petrochemical industry digitalization. Thailand's Board of Investment grants eight-year tax holidays for certified digital infrastructure projects. Bangkok's Ratchada-Ladprao district concentrates enterprise colocation with CPU-heavy virtualization workloads.
Philippines
Metro Manila's Makati and Taguig financial districts generate demand for low-latency trading infrastructure using FPGA accelerators. The Philippines' central bank imposes technology risk management guidelines on financial institutions handling customer data. Clark Freeport Zone in Pampanga hosts emerging facilities targeting business process outsourcing compute requirements.
Singapore Data Center Processor Market Competitive Landscape
Capability concentration sits with fabless designers commanding software ecosystems; scale advantage sits with foundry operators and integrated device manufacturers controlling wafer supply. The Singapore data center processor market structures around three archetypes: CUDA-anchored GPU suppliers, x86 incumbents with foundry partnerships, and custom silicon specialists serving hyperscale self-design programs. Competitive moves center on advanced packaging capacity reservations and sovereign AI qualification pathways.
Within the fabless designer tier, NVIDIA Corporation and Advanced Micro Devices Inc. occupy positions shaped by AI workload acceleration requirements. Intel Corporation anchors the integrated manufacturing archetype with foundry transition efforts. Arm Holdings represents the licensable architecture model enabling custom processor development among cloud operators.
| Leading Market Players |
|---|
| Intel Corporation |
| GlobalFoundries U.S. Inc. |
| NVIDIA Corporation |
| Qualcomm Incorporated |
| Advanced Micro Devices Inc. |
| Micron Technology |
| Arm Holdings |
| Broadcom Inc. |
| Marvell Technology |
| Others |
Pricing and Supply Chain Analysis
Taiwan's Hsinchu Science Park anchors advanced packaging capacity for CoWoS and HBM supply, concentrating pricing power among foundry operators serving Singapore's AI accelerator deployments. This geographic chokepoint compresses margins for downstream system integrators while amplifying cost pass-through to cloud service providers.
Pricing Analysis
Long-term offtake agreements dominate procurement for high-volume GPU clusters, insulating hyperscale operators from spot-market volatility while locking in capacity allocation. Price differentiation rests on thermal design power thresholds and liquid-cooling compatibility under Singapore's Green Mark certification tiers. Cost compression in air-cooled CPU segments is intensifying because enterprise refresh cycles are elongating. Colocation providers exhibit the highest price sensitivity due to stranded capacity risk, whereas sovereign AI programs demonstrate the lowest sensitivity given mission-critical procurement mandates.
Supply Chain Analysis
TSMC and Samsung Foundry hold captive capacity for advanced node production, with ASE Group and Amkor Technology concentrating chiplet packaging services. Raw material dependencies span silicon wafers from Japan, photoresists from South Korea, and specialty gases from the United States. Single-source vulnerability in CoWoS intermediates threatens deployment timelines for Singapore-based training clusters. Distribution runs through direct foundry relationships for hyperscalers and tier-one distributors for enterprise and colocation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's data center processor market fragments across sovereign AI mandates, cloud repatriation demand, and modular deployment formats, creating distinct competitive niches for specialized players.
For Market Incumbents: Harden software ecosystem moats through tighter CUDA-equivalent tooling for heterogeneous compute environments. Secure advanced packaging capacity reservations with TSMC and ASE Group to defend against supply rationing. Invest in liquid-cooling certification pathways under IMDA sustainability benchmarks to maintain premium positioning as thermal thresholds escalate. For New Entrants and Emerging Players: Bare-metal processor leasing for regulated healthcare and government verticals represents the most penetrable entry point, bypassing hyperscale procurement concentration. FPGA-based low-latency trading infrastructure for Singapore Exchange participants offers a second white-space target with defensible technical requirements. A channel partnership model with established colocation providers accelerates customer acquisition without direct facility investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors custom silicon design houses with sovereign AI qualification pathways and transparent Scope 3 emissions reporting. Long-term viability rests on backward integration into advanced packaging or forward integration into liquid-cooled system integration. Watch for IMDA approval queue velocity as the inflection signal indicating capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Reservation | TSMC CoWoS allocation secures GPU supply for Singapore training clusters. |
| Liquid Cooling Certification Investment | Green Mark compliance unlocks premium pricing for high-TDP deployments. |
| Sovereign AI Partnership Structuring | Domestic cloud operator alliances bypass hyperscale procurement concentration. |
| Heterogeneous Compute Software Development | CUDA-competitive tooling reduces NVIDIA dependency for inference workloads. |
| Modular Data Center Integration | Phased deployment formats match processor procurement to actual workload ramp. |
Research Methodology
A standing panel of data center facility planners, semiconductor procurement directors, thermal engineering specialists, and IMDA regulatory officers provided ongoing calibration throughout the study. Primary interviews with cloud service provider infrastructure teams, colocation operator executives, and financial services technology risk officers combined with secondary validation from hyperscaler capex disclosures, foundry utilization reports, and Singapore government data center approval registers. Bottom-up processor shipment estimates triangulated against top-down facility power capacity projections.
Scenario-bracketing framed volume and value outputs across the projection horizon, with optimistic and conservative cases bound by CoWoS supply expansion assumptions and Singapore land-use policy trajectories. Segmentation dimensions modeled include processor type, end-user archetype, form factor, and power rating tier. CAGRs derived from fitted growth curves applied to facility pipeline data and workload migration patterns. Industry-specific forecast inputs encompassed AI training cluster deployment schedules and sovereign cloud procurement timelines.
Practitioners should monitor foundry capacity allocation announcements, IMDA sustainability benchmark revisions, and EU carbon border mechanism implementation for early signals of forecast deviation. Quarterly review of hyperscaler capex guidance and Singapore data center approval queue length is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Automotive Smart Chip Market
Chipset and Processors
Auto Chip Market
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Global Heterogeneous Mobile Processing and Computing Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Accelerated Processing Unit (APU) Market