
 Semiconductor Leak Detectors Market | 2026-2036
Semiconductor Leak Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Leak Detectors Market Insights
ISO 20485 qualification for helium leak detection in semiconductor vacuum systems is collapsing the vendor landscape to certified equipment builders. Inficon leverages its mass spectrometer heritage to dominate high-resolution trace gas analysis for EUV tool chambers. Agilent Technologies sustains R&D intensity across optical sensing platforms for sub-atmospheric process monitoring. MKS Instruments anchors its position through backward integration into vacuum hardware and gas analysis subsystems.
Semiconductor leak detectors are precision instruments engineered to identify and quantify gas escape in ultra-high vacuum environments, typically achieving sensitivity thresholds below 10^-9 mbar·l/s for helium tracer methods. These systems employ mass spectrometry, thermal conductivity, or optical sensor architectures to safeguard wafer yield by preventing contamination during deposition, etch, and lithography operations. Fixed detector installations command the largest revenue share across semiconductor plants where continuous process control is non-negotiable, while portable units represent the fastest-expanding category as maintenance services adopt mobile diagnostics for fleet-wide equipment audits. Mass spectrometry technology leads on performance margins due to its selectivity for tracer gases in complex vacuum matrices, though ultrasonic detection is gaining traction in compressed gas distribution networks outside cleanroom cores.
The U.S. EPA enforces fluorinated greenhouse gas reporting under Subpart I that mandates leak monitoring across semiconductor manufacturing, while the EU F-Gas Regulation phases down hydrofluorocarbon use and tightens containment verification protocols. China's MEE implements dual carbon targets that pressure domestic fabs to upgrade legacy detection infrastructure. Japan's METI coordinates JIS standards for vacuum equipment integrity that shape procurement specifications for Tokyo Electron and Shin-Etsu supply chains. Stakeholders must calibrate investment between fixed infrastructure and portable service fleets as regional regulatory enforcement diverges on calibration frequency and detection sensitivity thresholds.
Market Dynamics
EUV lithography node compression below 3nm is forcing fabs to requalify entire vacuum system architectures, collapsing supplier ecosystems to ISO 20485-certified equipment builders who can guarantee helium tracer sensitivity below 10^-9 mbar·l/s.
Growth Catalysts
- Taiwan fabrication corridor expansion:TSMC and UMC are commissioning new EUV bays that require redundant leak detection arrays per chamber, doubling installed detector density at leading-edge nodes.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon containment verification mandates are compelling retrofits of fluorinated gas monitoring across legacy etch and CVD equipment fleets.
- Advanced packaging scale-up:Hybrid bonding and chiplet integration processes are extending leak detection requirements from lithography into post-fab assembly operations.
Market Restraints
- Helium supply volatility:Qatar and Algeria concentrate global helium extraction, creating input cost instability for tracer gas-dependent detection protocols.
- Mass spectrometer component bottlenecks:Electron multiplier and ion source manufacturing concentrates among specialized vacuum technology suppliers in Germany and Japan.
- Substitution threat from ultrasonic methods:Compressed gas distribution networks outside cleanroom cores are adopting acoustic detection that bypasses vacuum infrastructure entirely.
Strategic Opportunities
- India semiconductor manufacturing incentives:PLI scheme subsidies for domestic fabs create first-mover positioning for portable detector service fleets covering greenfield installations.
- Optical sensing convergence:Integration of laser absorption spectroscopy with existing vacuum gauges enables multi-gas detection without mass spectrometer hardware.
- Service contract unbundling:Equipment OEMs are separating leak detection calibration from maintenance agreements, opening direct procurement channels for third-party specialists.
Industry Challenges
- ISO 20485 certification timelines:Qualification protocols for new detector architectures extend 18-24 months, delaying product launches for emerging vacuum chamber designs.
- Legacy system integration friction:200mm and 300mm fabs running mature nodes cannot retrofit digital leak detection interfaces without custom analog bridge development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Leak Detectors Market |
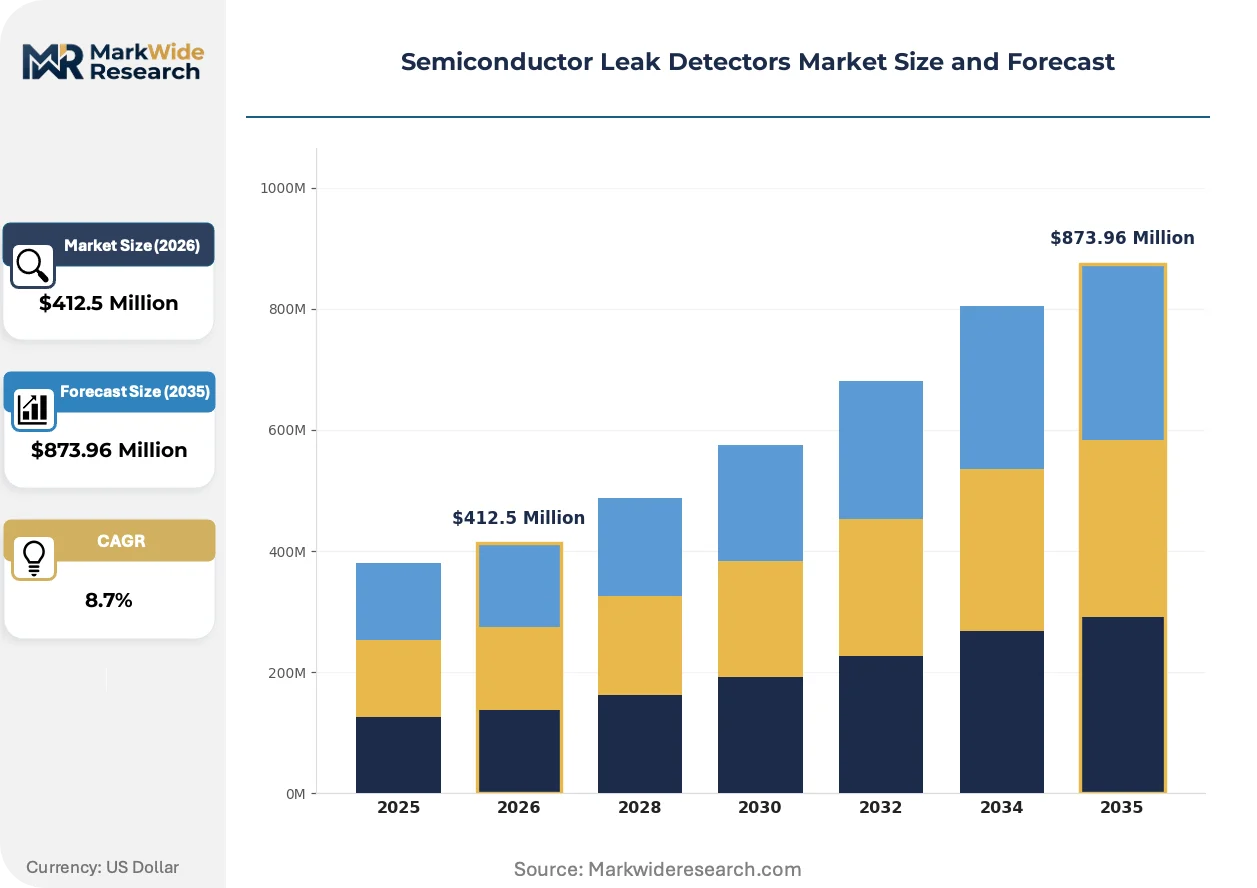
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Handheld Detectors, Automated Detectors Technology: Optical Sensors, Mass Spectrometry, Ultrasonic Detection, Thermal Conductivity End User: Manufacturing Facilities, Research Laboratories, Semiconductor Plants, Maintenance Services Application: Process Control, Quality Assurance, Equipment Maintenance, Safety Compliance |
| Companies Covered | Parker Hannifin, Inficon, Agilent Technologies, Emerson Electric Co., Honeywell International Inc., MKS Instruments, Ametek, Thermo Fisher Scientific, Yokogawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Leak Detectors Market Trends and Innovations
Detection modalities are diverging between high-resolution mass spectrometry for EUV vacuum chambers and lower-cost alternatives for peripheral gas distribution, fragmenting what was once a unified equipment category.
Quadrupole mass spectrometry is fragmenting the high-performance segment as EUV tool OEMs demand dedicated helium channels with sub-ppb resolution for pellicle integrity verification. ASML and Nikon lithography divisions now specify independent mass spec units per vacuum zone rather than centralized sampling manifolds. This specification shift is compressing supplier margins on multi-port systems while expanding unit volume for single-channel architectures.
The EU F-Gas Regulation's 2024 tightening of hydrofluorocarbon containment verification is mandating continuous leak monitoring across semiconductor etch equipment using alternative tracer protocols. Equipment builders in Germany and France must now certify fluorinated gas detection sensitivity at 1 gram per year equivalent, a threshold that optical infrared methods barely achieve. This regulatory compression is accelerating R&D investment into photoacoustic spectroscopy platforms by European detector specialists.
Maintenance procurement patterns are fragmenting as foundries unbundle leak detection calibration from OEM service contracts and award multi-year agreements to independent metrology service providers. Samsung and SK Hynix memory fabs in South Korea now operate mobile detector fleets that rotate between sites rather than fixed per-fab instrumentation. This service model shift is most visible in East Asian manufacturing corridors where equipment utilization rates justify dedicated diagnostic teams.
Semiconductor Leak Detectors Market Segmentation
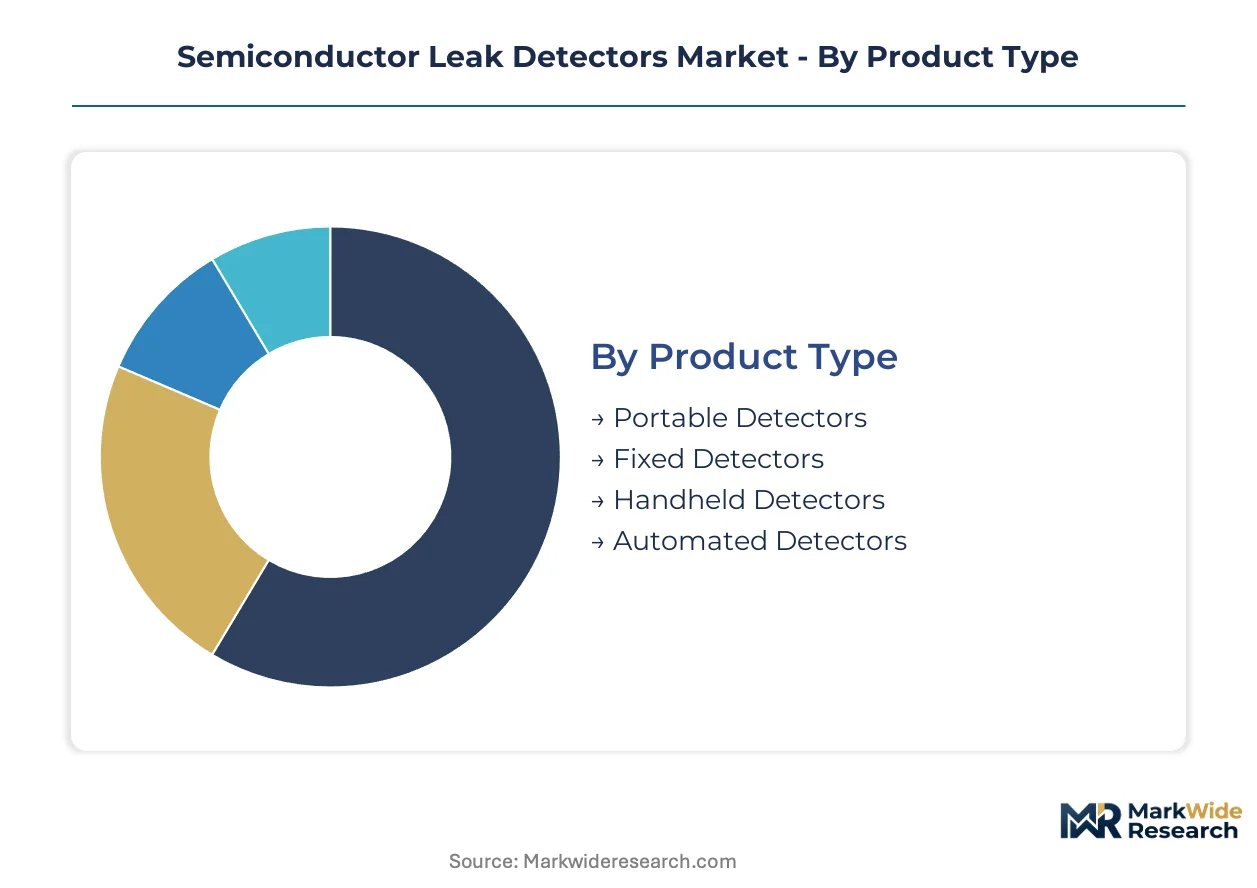
Semiconductor leak detector segmentation reflects diverging technical requirements between high-resolution vacuum chamber monitoring and cost-sensitive peripheral gas distribution networks. Equipment specifications vary sharply across EUV lithography nodes, legacy process tools, and post-fab packaging operations where contamination sensitivity thresholds differ by orders of magnitude.
Product Type:
Portable and handheld formats face intensifying substitution pressure from ultrasonic methods in compressed gas distribution networks, while fixed installations defend their position through ISO 20485 certification requirements for continuous process control.
- Fixed Detectors:Permanent installations integrate directly with vacuum chamber architectures, achieving helium tracer sensitivity below 10^-9 mbar·l/s through mass spectrometer modules. TSMC and Samsung fabs in Taiwan and South Korea specify redundant fixed arrays per EUV bay, doubling detector density at sub-3nm nodes where pellicle integrity verification is non-negotiable.
- Portable Detectors:Mobile units enable fleet-wide equipment audits across multiple fabrication sites, with South Korean memory manufacturers operating rotating detector pools between Hynix and Samsung facilities. Unbundling of calibration services from OEM maintenance agreements is accelerating procurement of third-party portable fleets.
- Handheld Detectors:Compact form factors target quick diagnostic checks in gas distribution manifolds outside cleanroom cores.
- Automated Detectors:Self-calibrating systems reduce manual intervention for high-throughput manufacturing environments.
Fixed detectors anchor the volume base while portable units gain share at the steepest rate.
Technology:
Cost tier stratification separates high-investment mass spectrometry platforms from emerging optical alternatives, with price-performance trade-offs determining adoption across different vacuum system complexity levels.
- Mass Spectrometry:Quadrupole architectures dominate EUV lithography specifications through sub-ppb helium resolution and tracer gas selectivity in complex vacuum matrices. ASML and Nikon now mandate independent single-channel units per vacuum zone rather than centralized manifolds, fragmenting supplier margins while expanding unit volumes.
- Optical Sensors:Laser absorption spectroscopy enables multi-gas detection without vacuum hardware, with European specialists accelerating photoacoustic R&D to meet EU F-Gas Regulation thresholds of 1 gram per year equivalent for fluorinated gas monitoring.
- Ultrasonic Detection:Acoustic methods bypass vacuum infrastructure entirely in compressed gas networks.
- Thermal Conductivity:Established platforms serve baseline leak screening in mature process nodes.
Mass spectrometry commands the premium tier while optical sensing climbs fastest as a cost-optimized alternative.
End User:
Customer type segmentation tracks the shift from capital equipment procurement by fabrication owners toward service-based models where independent metrology providers capture recurring calibration revenue.
- Semiconductor Plants:Foundry and memory manufacturers drive specifications for ISO 20485-certified equipment, with procurement concentrated among Taiwan fabrication corridors and South Korean memory complexes where EUV deployment is most advanced.
- Maintenance Services:Independent providers now operate mobile detector fleets under multi-year agreements, particularly visible in East Asian manufacturing corridors where equipment utilization rates justify dedicated diagnostic teams.
- Manufacturing Facilities:Broader industrial users adopt leak detection for general vacuum system integrity.
- Research Laboratories:R&D installations prioritize flexibility over throughput in detector specifications.
Semiconductor plants anchor current demand while maintenance services represent the steepest expansion trajectory.
Application:
Application segmentation aligns with regulatory enforcement intensity, where safety compliance and process control face mandatory verification protocols while quality assurance remains more discretionary.
- Process Control:Continuous monitoring safeguards wafer yield during deposition, etch, and lithography operations, with EUV node compression below 3nm forcing requalification of entire vacuum system architectures to maintain contamination-free environments.
- Safety Compliance:EPA Subpart I reporting and EU F-Gas Regulation phase-down mandates drive retrofit demand across legacy etch and CVD equipment fleets, with China's MEE dual carbon targets adding pressure for domestic fab infrastructure upgrades.
- Quality Assurance:Post-process verification supports yield optimization in advanced packaging.
- Equipment Maintenance:Preventive diagnostics reduce unplanned downtime in high-utilization facilities.
Process control anchors the revenue base while safety compliance gains share fastest under tightening regulatory timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme subsidies for domestic semiconductor fabs are accelerating first-mover positioning for portable detector service fleets covering greenfield installations. Taiwan and South Korea fabrication corridors dominate advanced node demand where EUV lithography below 3nm requires redundant helium detection arrays. China's dual carbon targets and the EU F-Gas Regulation are tightening fluorinated gas monitoring mandates across legacy equipment retrofits.
United States
EPA Subpart I mandates fluorinated greenhouse gas reporting across semiconductor manufacturing, compelling fabs in Arizona and Texas to upgrade leak detection infrastructure. The CHIPS and Science Act directs federal investment toward domestic fabrication capacity in the Southwest and Midwest. Intel's expanding presence in Greater Phoenix and Ohio anchors detector procurement for new EUV bays requiring ISO 20485-certified continuous monitoring systems.
Taiwan
TSMC and UMC are commissioning redundant leak detection arrays per EUV chamber, doubling installed detector density at sub-3nm nodes. The National Science and Technology Council coordinates industrial policy supporting advanced packaging scale-up in Hsinchu Science Park. Tainan and Taichung fabrication corridors concentrate demand for mass spectrometry platforms with helium tracer sensitivity below 10^-9 mbar·l/s.
South Korea
Samsung and SK Hynix memory fabs operate mobile detector fleets that rotate between sites rather than fixed per-fab instrumentation. METI-aligned procurement specifications shape vacuum equipment integrity standards for domestic supply chains. The Yongin and Pyeongtaek semiconductor clusters drive specifications for independent single-channel mass spec units per vacuum zone.
China
MEE implements dual carbon targets pressuring domestic fabs to upgrade legacy detection infrastructure across mature node facilities. GB standards for vacuum equipment integrity are tightening calibration frequency requirements for etch and CVD tools. The Yangtze River Delta and Pearl River Delta manufacturing corridors concentrate retrofit demand for fluorinated gas monitoring systems.
Germany
EU F-Gas Regulation phase-down mandates are compelling equipment builders to certify fluorinated gas detection sensitivity at 1 gram per year equivalent. ECHA enforcement of containment verification protocols accelerates R&D investment into photoacoustic spectroscopy platforms. Dresden and Bavaria semiconductor clusters anchor demand for optical infrared methods serving etch equipment retrofits.
Semiconductor Leak Detectors Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with vacuum technology heritage alongside specialized mass spectrometry pure-plays. Consolidation pressure intensifies as ISO 20485 certification requirements collapse supplier ecosystems to qualified equipment builders. Three archetypes dominate: mass spectrometer heritage specialists, diversified industrial technology conglomerates, and vacuum hardware-integrated subsystem providers. Competitive moves center on backward integration into ion source manufacturing and strategic partnerships with EUV lithography OEMs for chamber-integrated designs.
Within the mass spectrometry heritage tier, Inficon and Agilent Technologies exemplify positioning built on trace gas analysis platforms for ultra-high vacuum environments. MKS Instruments occupies a position among vacuum hardware-integrated providers through captive supply of gas analysis subsystems. These three anchors represent divergent strategic vectors: spectral resolution specialization, optical sensing diversification, and subsystem backward integration.
| Leading Market Players |
|---|
| Parker Hannifin |
| Inficon |
| Agilent Technologies |
| Emerson Electric Co. |
| Honeywell International Inc. |
| MKS Instruments |
| Ametek |
| Thermo Fisher Scientific |
| Yokogawa Electric |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month ISO 20485 certification timelines concentrate pricing power among established mass spectrometer builders while compressing margins for aspirant entrants lacking vacuum technology heritage. Taiwan and South Korea fabrication corridors absorb premium pricing for sub-ppb helium resolution as EUV node compression eliminates second-source qualification.
Pricing Analysis
Certification level creates the primary spread between ISO 20485-qualified fixed installations and uncertified portable alternatives. Three-tier pricing structure across premium mass spectrometry, mid-grade optical sensing, and economy ultrasonic methods reflects performance-grade differentiation. Cost compression in the optical tier is intensifying because European specialists accelerate photoacoustic R&D to meet EU F-Gas Regulation thresholds. Maintenance service providers exhibit highest price sensitivity due to unbundled procurement models, while EUV tool OEMs accept premium positioning for chamber-integrated designs.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand while Germany and Japan concentrate electron multiplier and ion source manufacturing for mass spectrometer subsystems. Helium tracer gas supply draws from Qatar and Algeria extraction concentration, creating input cost instability for detection protocol-dependent fabs. Single-source vulnerability in specialized vacuum component supply threatens equipment delivery schedules. Distribution runs through lithography OEM channel partnerships and direct procurement by foundry maintenance divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor capital equipment cycles are recovering from trough conditions as EUV lithography node compression below 3nm forces vacuum system requalification across Taiwan and South Korea fabrication corridors.
For Market Incumbents: Fortify backward integration into ion source manufacturing to neutralize German and Japanese component bottlenecks. Deepen captive supply of gas analysis subsystems to defend against optical sensing substitution in fluorinated gas monitoring applications. Accelerate ISO 20485 pre-qualification for emerging EUV chamber architectures to compress entrant certification timelines. For New Entrants and Emerging Players: Portable service fleet gaps in India's PLI-subsidized greenfield fabs offer immediate white-space access. Target rotating detector pool contracts where Samsung and SK Hynix memory complexes have unbundled calibration from OEM maintenance agreements. Lead with mobile diagnostic capabilities and multi-site service coverage rather than fixed installation competition. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EPA Subpart I, EU F-Gas Regulation, and China's MEE dual carbon targets mandate continuous retrofit investment regardless of semiconductor demand cycles. Target mass spectrometry pure-plays with established vacuum technology heritage and existing EUV OEM relationships. Watch helium supply volatility indices as inflection indicators for tracer gas protocol substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ion Source Manufacturing | MKS Instruments and Inficon reduce German and Japanese supplier dependency for electron multiplier components. |
| Photoacoustic Spectroscopy Platform Development | European specialists target EU F-Gas Regulation 1 gram per year equivalent certification thresholds for etch equipment retrofits. |
| Mobile Detector Fleet Expansion | Samsung and SK Hynix rotating pool models in South Korea demonstrate service unbundling traction. |
| ISO 20485 Pre-Qualification Investment | ASML and Nikon lithography divisions now specify independent single-channel units per vacuum zone. |
| India PLI Scheme Market Entry | Greenfield fab subsidies create first-mover positioning for portable calibration service providers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with vacuum equipment engineers, fab maintenance directors, lithography OEM procurement teams, and regulatory compliance officers; and secondary validation through SEC filings, customs trade data, EPA Subpart I enforcement records, and EU ECHA regulatory filings. Bottom-up equipment unit estimates and top-down market sizing triangulated against foundry capex disclosures and EUV tool shipment patterns.
Across the analysis window, forecasts model detector unit demand by product type, technology platform, end-user category, and application segment. CAGRs derive from regression analysis of historical foundry equipment procurement cycles and regulatory compliance retrofit timelines. Helium supply volatility indices and EU F-Gas Regulation enforcement intensity serve as scenario-weighting inputs.
Material uncertainties — helium supply disruption, mass spectrometer component export restrictions, and EUV lithography node transition delays — sit outside the modeled envelope. Forecasts reflect assumptions about continued regulatory tightening across EPA, EU, and Chinese jurisdictions. Recalibration cycles align with material shifts in semiconductor fabrication capacity expansion and fluorinated gas monitoring mandate enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Neutron Detector Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Frequency Counter Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Gas Detectors Market
Detection and Regulation Devices
Volatile Organic Compound (VOC) Detector Market