
 Europe Gas Detectors Market | 2026-2036
Europe Gas Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gas Detectors Market Foresight
A shift from single-source to multi-source procurement is pivoting how European industrial buyers evaluate gas detection vendors. Drägerwerk AG & Co. KGaA leverages its vertically integrated manufacturing in Germany to control component quality across infrared and electrochemical sensor lines. Siemens AG anchors large-scale fixed installations through its automation channel dominance in chemical and power generation facilities. MSA Safety competes aggressively in portable multi-gas units for confined-space entry across offshore energy platforms.
Europe gas detectors are instruments that sense and quantify airborne concentrations of combustible, toxic, or oxygen-deficient gases through electrochemical, catalytic bead, or infrared absorption principles, typically calibrated to trigger alarms at parts-per-million or percentage lower explosive limit thresholds to prevent occupational fatalities and process explosions. Fixed detector deployments dominate value generation due to capital-intensive integration with distributed control systems in refineries and chemical plants, while portable multi-gas detectors represent the fastest-expanding category as contractors face heightened temporary-worksite scrutiny. Photoionization detector technology leads growth in volatile organic compound monitoring for environmental compliance, whereas infrared sensors command premium positioning through their immunity to sensor poisoning and reduced calibration frequency.
The EU ATEX Directive and IECEx certification schemes mandate intrinsic safety standards for equipment deployed in potentially explosive atmospheres, forcing non-compliant manufacturers toward costly redesigns or market exit. Germany's Federal Institute for Occupational Safety and Health (BAuA) and France's ANSM both influence national adoption timelines through workplace exposure limit enforcement and medical gas handling protocols. Buyers must weigh sensor interoperability against vendor lock-in as the EU AI Act begins classifying predictive maintenance algorithms in connected detection systems.
Market Dynamics
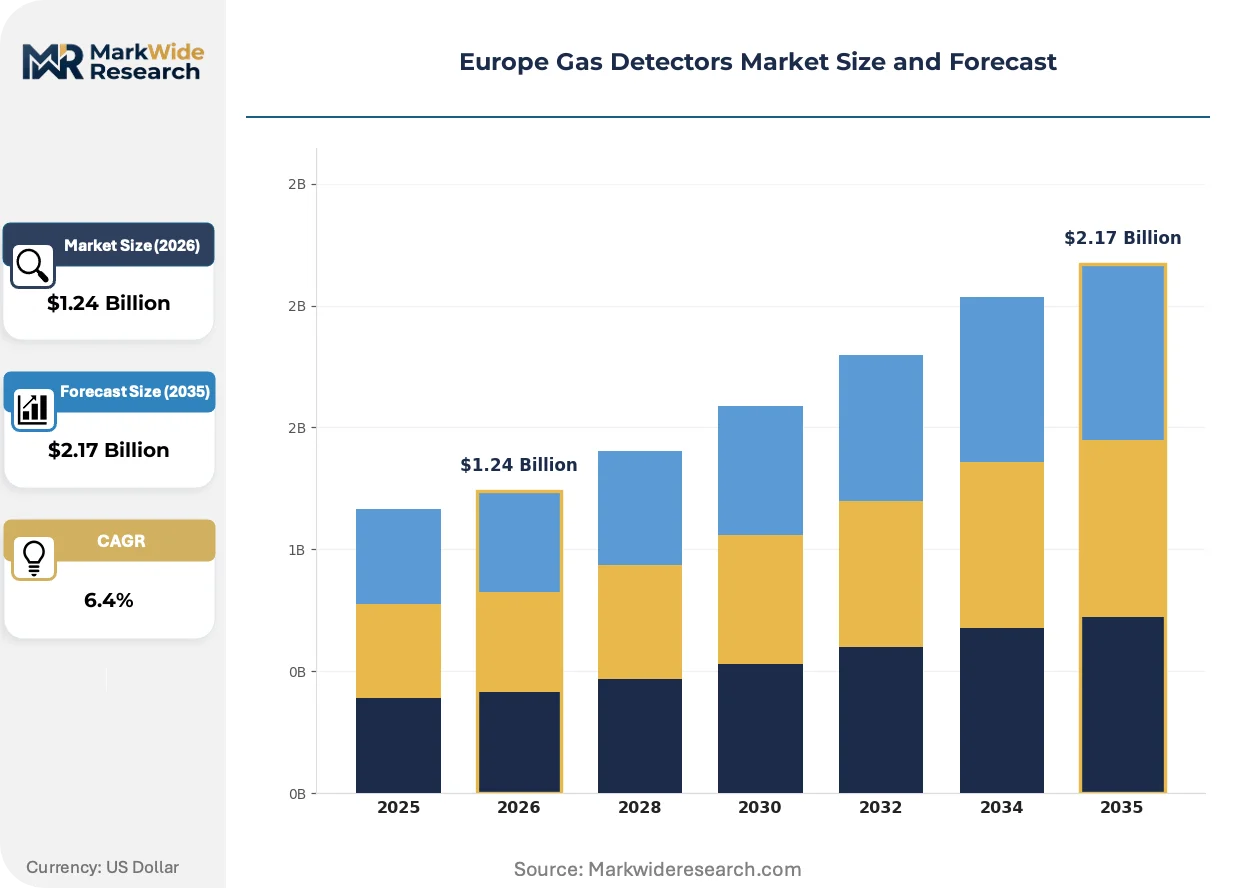
The EU Green Deal's methane reduction mandates are compressing replacement cycles for aging sensing infrastructure across European energy and chemical facilities, forcing capital reallocation toward connected detection systems.
Growth Catalysts
- REACH chemical exposure protocols:Stricter workplace exposure limits under ECHA frameworks mandate continuous ambient monitoring in German and French chemical manufacturing clusters.
- Offshore platform electrification:North Sea energy operators deploy fixed detector networks to manage hydrogen sulfide risks during extended platform maintenance windows.
- Photoionization detector miniaturization:Shrinking PID sensor footprints enable wearable VOC monitoring for environmental compliance teams in industrial cleanup operations.
Market Restraints
- Palladium and platinum input volatility:Catalytic bead sensors depend on precious metal coatings, exposing manufacturers to London Metal Exchange price swings.
- ATEX certification timelines:IECEx laboratory bottlenecks in Germany and UK extend product launch cycles by 8-14 months for non-EU component suppliers.
- Optical gas imaging substitution:Thermal camera-based leak detection displaces point-source detectors in upstream methane monitoring applications.
Strategic Opportunities
- Poland's coal-to-gas transition:District heating network modernization creates demand for distributed natural gas detection in municipal pipeline retrofits.
- Predictive maintenance algorithms:Machine learning integration with electrochemical sensor arrays enables drift prediction before calibration failure.
- EU AI Act compliance services:Classification of connected detection systems as high-risk AI creates advisory revenue streams for certification consultancies.
Industry Challenges
- Electrochemical sensor calibration workforce:Specialized technicians capable of ppm-level reference gas handling remain concentrated in Germany and the Netherlands.
- Legacy DCS integration complexity:4-20mA analog outputs from new detectors must interface with 1990s-era distributed control systems in aging French refineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gas Detectors Market |
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Multi-Gas Detectors, Single-Gas Detectors Technology: Chemical Sensors, Infrared Sensors, Ultrasound Sensors, Photoionization Detectors End User: Industrial, Commercial, Residential, Government Installation: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Crowcon Detection Instruments, Emerson Electric, Drägerwerk AG & Co. KGaA, Teledyne Technologies, Industrial Scientific, Honeywell International, GfG Instrumentation, Siemens AG, MSA Safety, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gas Detectors Market Shifts & Advancements
Sensor fusion architectures and wireless mesh protocols are collapsing the cost and installation barriers that historically separated fixed and portable detection categories.
Infrared absorption sensing is electrifying refinery perimeter monitoring by eliminating sensor poisoning from silicone contaminants. Dutch chemical operators along the Rotterdam-Antwerp corridor deploy dual-wavelength IR detectors for continuous benzene surveillance. The technology compresses maintenance intervals from quarterly to annual cycles.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is redirecting detector R&D toward ammonia and carbon dioxide leak detection in commercial cold chain facilities. Industrial refrigeration OEMs in Italy and Spain now specify electrochemical ammonia sensors for compliance. Equipment retrofit demand concentrates in southern European food processing clusters.
Multi-source procurement contracts are fragmenting historical vendor relationships in offshore energy. Norwegian platform operators unbundle sensor hardware from calibration service agreements, selecting infrared detectors from German specialists while sourcing electrochemical units through Nordic distributors. This pattern is most pronounced in North Sea decommissioning projects where temporary monitoring needs dominate capital planning.
Europe Gas Detectors Market Segmentation
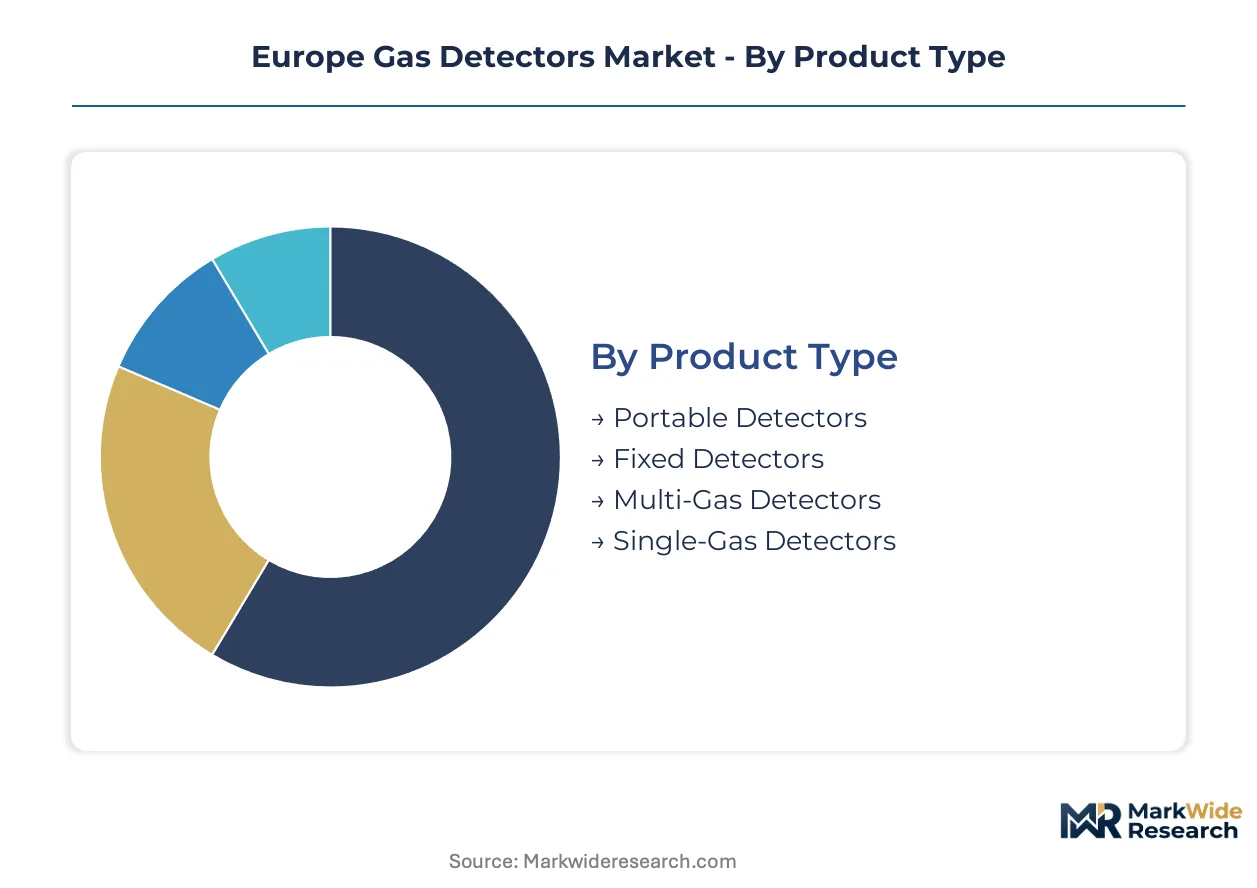
Gas detector procurement patterns diverge sharply across product architectures, sensing technologies, and deployment environments. Capital allocation decisions in European industrial facilities hinge on whether monitoring needs are permanent infrastructure or temporary compliance-driven deployments.
Product Type:
Fixed detector networks demand the heaviest upfront investment due to distributed control system integration and hardwired power infrastructure.
- Portable Detectors:Battery-powered handheld units with electrochemical or catalytic bead sensors provide mobility for confined-space entry and maintenance turnarounds. Norwegian offshore contractors deploy these across decommissioning projects where temporary workforce protection overrides permanent infrastructure spend.
- Fixed Detectors:Hardwired installations with 4-20mA outputs integrate directly into refinery distributed control systems for continuous perimeter surveillance. German chemical clusters along the Rhine corridor concentrate replacement demand as REACH exposure protocols tighten.
- Multi-Gas Detectors:Simultaneous monitoring of combustible, toxic, and oxygen-deficient atmospheres through sensor fusion architectures.
- Single-Gas Detectors:Dedicated hydrogen sulfide or carbon monoxide units for specialized hazard environments.
Most installed capacity flows through Fixed Detectors. Expansion is steepest in Portable Detectors.
Technology:
Sensor selection pivots on calibration frequency tolerance and immunity to poisoning contaminants in specific industrial atmospheres.
- Chemical Sensors:Electrochemical cells and catalytic beads dominate cost-sensitive applications despite quarterly calibration requirements. French refineries favor these for legacy DCS compatibility where analog signal integration trumps maintenance burden.
- Infrared Sensors:Non-dispersive infrared absorption eliminates sensor poisoning from silicone vapors and extends calibration cycles to annual intervals. Dutch operators in the Rotterdam-Antwerp corridor specify dual-wavelength variants for benzene surveillance.
- Ultrasound Sensors:Acoustic leak detection for pressurized gas systems without direct gas contact.
- Photoionization Detectors:Miniaturized PID sensors enable wearable volatile organic compound monitoring for environmental compliance teams.
Chemical Sensors retain the largest installed base. Infrared Sensors are climbing the fastest as poisoning immunity commands premium positioning.
End User:
Procurement sophistication and contract scale separate industrial buyers from fragmented residential and commercial segments.
- Industrial:Oil refineries, chemical plants, and offshore platforms drive specification standards through multi-year framework agreements. German automotive paint shops and Italian food refrigeration facilities anchor regional demand clusters.
- Commercial:Retail refrigeration and hospitality applications concentrate in southern European cold chain modernization.
- Residential:Standalone carbon monoxide alarms for single-family housing.
- Government:Municipal district heating networks and emergency response equipment.
Industrial buyers command the deepest specification influence. Commercial retrofit demand is gaining share fastest as F-Gas Regulation compliance spreads.
Installation:
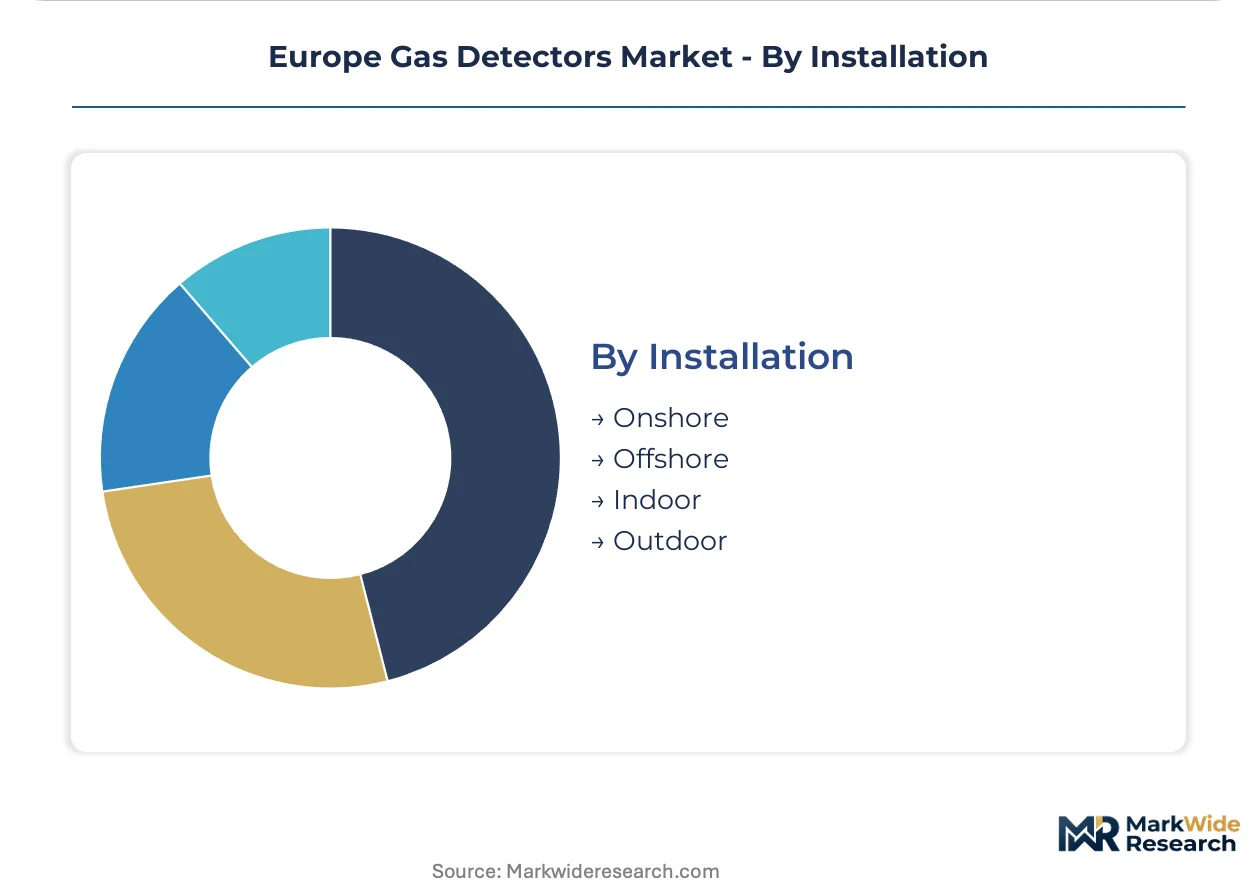
Environmental exposure severity and accessibility constraints dictate housing specifications and wireless versus hardwired architecture choices.
- Onshore:Refinery perimeter and chemical plant process unit deployments dominate capital deployment. Polish district heating retrofits and German hydrogen pipeline pilots concentrate emerging demand.
- Offshore:North Sea platforms require ATEX-certified housings and saline-resistant coatings for extended maintenance windows.
- Indoor:Confined-space monitoring in manufacturing facilities and laboratories.
- Outdoor:Perimeter fence-line monitoring and wastewater treatment facilities.
Onshore infrastructure holds the majority of active installations. Offshore replacement cycles are compressing fastest as platform electrification extends operational life.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr chemical corridor anchors European gas detector procurement through its dense concentration of petrochemical crackers and specialty chemical manufacturing. REACH enforcement by ECHA tightens workplace exposure limits across German and French facilities. Polish district heating conversions and North Sea platform electrification extend demand geography northward and eastward.
Germany
Chemical manufacturing clusters along the Rhine corridor and offshore North Sea operations drive continuous monitoring upgrades. BAuA workplace exposure limit enforcement accelerates replacement cycles for aging electrochemical sensors. The BASF Ludwigshafen complex and Bayer Leverkusen facilities anchor fixed detector network expansions tied to process automation investments.
United Kingdom
North Sea decommissioning projects and hydrogen pipeline pilots concentrate portable and temporary fixed detector demand. IECEx laboratory bottlenecks extend certification timelines for non-EU component suppliers. Aberdeen's energy service sector and Teesside hydrogen hub anchor procurement for ATEX-certified offshore equipment.
Netherlands
Rotterdam-Antwerp corridor refineries deploy dual-wavelength infrared detectors for benzene surveillance and poisoning immunity. The Port of Rotterdam's industrial complex mandates perimeter monitoring for VOC emissions compliance. Dutch chemical operators compress maintenance intervals from quarterly to annual cycles through IR technology adoption.
France
ANSM medical gas handling protocols and legacy refinery DCS integration requirements shape procurement specifications. French refineries favor electrochemical sensors for analog signal compatibility with 1990s-era control systems. The Normandy petrochemical cluster and Lyon pharmaceutical manufacturing belt anchor regional demand concentration.
Poland
Coal-to-gas district heating network modernization creates distributed natural gas detection demand in municipal pipeline retrofits. EU Green Deal methane reduction targets accelerate sensing infrastructure investment across energy transition projects. Warsaw and Krakow heating utilities anchor emerging procurement for fixed detector networks in urban gas distribution.
Europe Gas Detectors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connected detection and predictive maintenance algorithm development. The vendor base separates into three functional tiers: vertically integrated German manufacturers controlling sensor component quality, automation conglomerates anchoring large-scale fixed installations, and portable equipment specialists serving offshore contractors. Consolidation pressure concentrates among mid-scale electrochemical sensor suppliers facing precious metal input volatility. Dominant competitive moves include backward integration into infrared sensor fabrication and unbundling of hardware from calibration service agreements.
Among Germany-based fabricators, Drägerwerk AG & Co. KGaA exemplifies vertical integration control over component manufacturing. Siemens AG occupies a position anchoring automation-channel dominance in chemical and power generation facilities. MSA Safety represents the portable equipment archetype competing across confined-space entry applications. These three entities illustrate how geographic concentration in German industrial clusters shapes competitive positioning through proximity to Rhine corridor chemical demand and regulatory influence from BAuA and ECHA frameworks.
| Leading Market Players |
|---|
| Crowcon Detection Instruments |
| Emerson Electric |
| Drägerwerk AG & Co. KGaA |
| Teledyne Technologies |
| Industrial Scientific |
| Honeywell International |
| GfG Instrumentation |
| Siemens AG |
| MSA Safety |
| Others |
Supply & Pricing Matrix
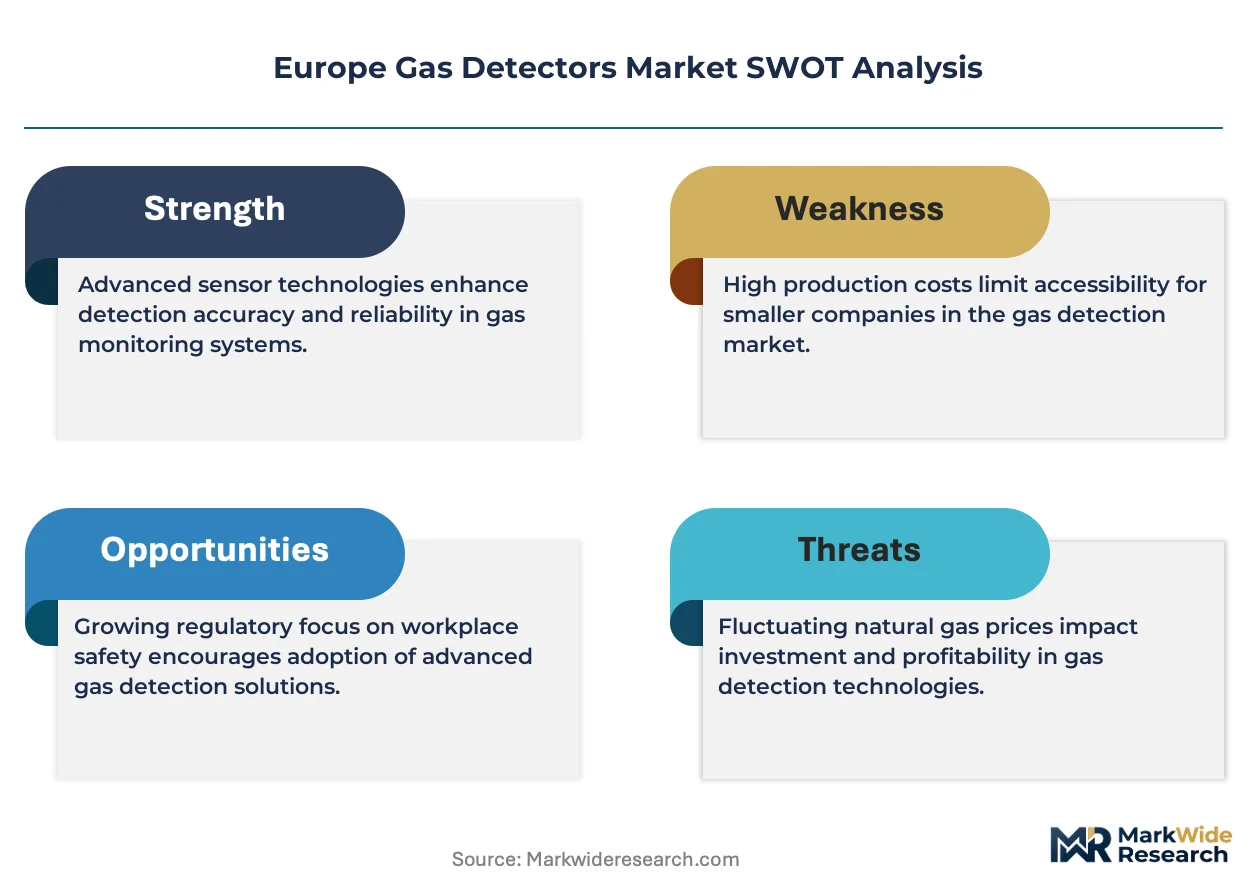
Rhine corridor chemical plant operators concentrate procurement authority through multi-year framework agreements, anchoring a contract-based pricing model where volume scale and certification tier separate premium infrared systems from standard electrochemical units. This buyer concentration creates asymmetric negotiating power that compresses margins for non-integrated sensor suppliers while rewarding vendors with captive component manufacturing.
Pricing Analysis
Palladium and platinum cost pass-through from London Metal Exchange volatility directly pressures catalytic bead sensor pricing, forcing electrochemical manufacturers to absorb margin erosion or risk volume loss to infrared alternatives. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade, with ATEX/IECEx dual-certified units commanding substantial premiums over single-certification equipment. Pricing pressure stems from optical gas imaging substitution in upstream methane monitoring, displacing point-source detectors in Norwegian and UK North Sea operations. Commercial refrigeration retrofit buyers exhibit highest price sensitivity due to F-Gas Regulation compliance mandates squeezing capital budgets, while offshore platform operators prioritize poisoning immunity over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German infrared sensor fabricators and Dutch electrochemical cell specialists, concentrating critical component supply in the Rhine-Ruhr corridor and Rotterdam-Antwerp corridor. Raw material dependencies include palladium coatings for catalytic beads, rare earth elements for infrared optical paths, and specialized polymer membranes for electrochemical cells. Supply chain risk centers on IECEx laboratory bottlenecks extending certification timelines for non-EU component suppliers. Distribution runs through automation channel partners for fixed detector networks and industrial safety distributors for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's coal-to-gas district heating transition offers geographic-arbitrage returns against Western European saturation, as Warsaw and Krakow utilities face EU Green Deal methane mandates without established vendor relationships. Regulatory enforcement gaps between German BAuA protocols and Polish adoption timelines create temporary pricing power for early entrants.
For Market Incumbents: Anticipate optical gas imaging displacement in upstream methane monitoring by accelerating predictive maintenance algorithm development for connected detection systems. Backward integration into infrared sensor fabrication defends margin position against precious metal input volatility. Prioritize unbundling hardware from calibration service agreements to match Norwegian offshore contractor procurement patterns. For New Entrants and Emerging Players: Wireless mesh sensor fusion architectures offer the most penetrable wedge against legacy fixed-portable category boundaries. Target Polish district heating network retrofits where incumbent relationships remain unformed and EU funding accelerates capital deployment. Lead with predictive maintenance SaaS tiering to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Industrial automation conglomerates represent the most active acquirer in this space, seeking sensor fusion capabilities to complement distributed control system portfolios. Mid-scale electrochemical specialists facing palladium price volatility present consolidation targets over a five-to-ten year viability window. Monitor IECEx laboratory capacity expansion as the critical signal for non-EU supplier market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Infrared Sensor Fabrication | Drägerwerk's captive optical path production insulates margins from rare earth supply shocks. |
| Predictive Maintenance Algorithm Development | Machine learning integration with electrochemical arrays enables drift prediction before calibration failure. |
| Multi-Source Procurement Contract Unbundling | Norwegian platform operators now separate hardware from calibration service agreements. |
| Wireless Mesh Protocol Deployment | Sensor fusion architectures collapse installation barriers between fixed and portable detection categories. |
| Poland District Heating Network Entry | Warsaw and Krakow utilities accelerate sensing infrastructure investment under EU Green Deal targets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and ECHA regulatory affairs specialists with secondary validation against customs data, BAuA exposure limit filings, SEC 10-K industrial safety disclosures, and EU Green Deal implementation progress reports. Bottom-up sensor shipment modeling and top-down chemical facility capital expenditure triangulation anchored volume estimates.
Segment-weighting approaches distributed value across fixed versus portable architectures, infrared versus electrochemical versus photoionization technologies, and industrial versus commercial end-use categories. CAGRs derived from replacement cycle compression under REACH protocols and platform electrification extending North Sea operational life. Forecast inputs incorporated F-Gas Regulation refrigerant phasedown timelines and EU AI Act high-risk system classification for connected detection algorithms.
The model holds under steady EU regulatory enforcement and palladium price bands; deviation in IECEx laboratory capacity or optical gas imaging cost curves would shift replacement demand timing. Forecasts reflect documented assumptions about methane reduction mandate implementation pace and ATEX certification backlog resolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Automated Number Plate Recognition (ANPR) and Detection Sensors Market
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Arc Fault Detection Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Gas Detectors Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market