
 OLED Blue Emitter Market | 2026-2036
OLED Blue Emitter Market Size, Share, and Industry Trends Forecast 2026-2036
OLED Blue Emitter Market Insights
The EU Green Deal is consolidating demand around mercury-free and reduced-cadmium emitter formulations across European display supply chains. Universal Display Corporation leverages its phosphorescent blue IP portfolio to sustain royalty streams from licensed manufacturers. Merck KGaA anchors European material supply through its Frankfurt-area production campus, while Idemitsu Kosan dominates Japanese blue host material shipments to Korean panel makers.
OLED blue emitters are organic electroluminescent compounds—typically iridium or platinum complexes for phosphorescent variants, or thermally activated delayed fluorescence (TADF) molecules—that generate blue light through exciton recombination within an emissive layer, with peak wavelengths near 450-470 nm and external quantum efficiency targets exceeding 25%. Small molecule phosphorescent emitters lead premium smartphone panel supply due to their superior efficiency and color purity, while quantum dot approaches represent the fastest-growing alternative as manufacturers seek to bypass heavy-metal content restrictions. Polymer-based systems occupy niche wearable applications where solution-processed deposition reduces capital intensity.
REACH regulates organometallic precursor substances across European manufacturing zones, while Korea's Ministry of Trade, Industry and Energy enforces domestic content requirements under its national strategic material program. The EPA's Toxic Substances Control Act governs importation of novel emitter chemistries into U.S. fabrication facilities. Stakeholders must monitor regulatory divergence between jurisdictions to avoid qualification bottlenecks that fragment material sourcing strategies.
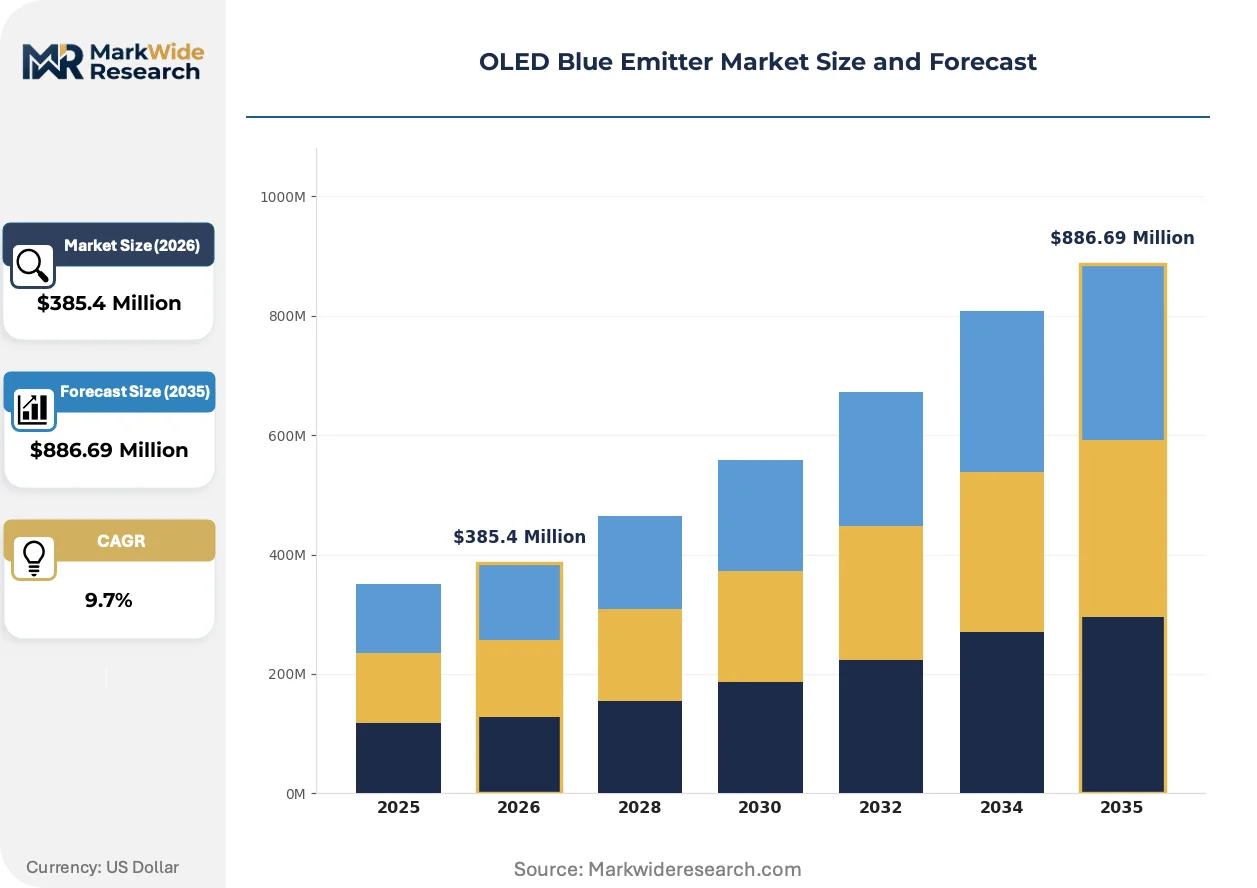
Market Dynamics
Phosphorescent blue emitter architectures are consolidating their position as the dominant efficiency platform, while thermally activated delayed fluorescence (TADF) chemistries accelerate toward commercial viability under heavy-metal restriction pressures from the EU Green Deal.
Growth Catalysts
- EU Green Deal phased restrictions:Mercury-free and reduced-cadmium formulations are gaining mandatory preference across European display supply chains, forcing rapid qualification of compliant emitter portfolios.
- Smart manufacturers:Samsung Display and LG Display are expanding integrated OLED fabrication complexes in South Korea, concentrating demand for high-efficiency blue host materials.
- TADF molecule platforms:These heavy-metal-free alternatives are achieving external quantum efficiency thresholds that approach phosphorescent benchmarks, opening new formulation pathways.
Market Restraints
- Iridium complex supply concentration:Organometallic precursor refining capacity clusters in East Asian chemical processing zones, creating single-source vulnerability for phosphorescent emitter production.
- Technical limitation in deep-blue emission:TADF systems struggle to simultaneously achieve narrow emission bandwidth below 470 nm peak wavelength with operational stability exceeding 10,000 hours.
- REACH registration timelines:ECHA's phased substance evaluation protocols for novel organometallic emitters extend qualification cycles by 18-24 months versus legacy materials.
Strategic Opportunities
- Automotive display integration:Tier-1 panel suppliers are qualifying blue emitters for curved instrument clusters and pillar-to-pillar screens, with reliability requirements exceeding consumer electronics standards.
- India PLI scheme for display manufacturing:Domestic panel fabrication incentives are attracting emitter material suppliers to establish local formulation and dispensing operations.
- Solution-processed polymer systems:Wearable device manufacturers are adopting inkjet-deposited blue emitters to reduce capital intensity in sub-6-inch panel production.
Industry Challenges
- Organometallic synthetic chemist scarcity:The specialized expertise required for iridium and platinum complex design remains concentrated in Japanese and Korean research institutes, constraining formulation team expansion.
- Cleanroom deposition equipment lead times:Vacuum thermal evaporation systems for small-molecule emitter stacking face 14-18 month delivery backlogs from German and Japanese toolmakers.
- Cross-jurisdictional IP licensing complexity:Phosphorescent emitter patent thickets span US, Korean, and Japanese filings, complicating freedom-to-operate analysis for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OLED Blue Emitter Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecule, Polymer, Quantum Dot, Phosphorescent Application: Televisions, Smartphones, Tablets, Wearables End User: Consumer Electronics, Automotive, Commercial Displays, Signage Technology: OLED, MicroLED, AMOLED, Flexible Displays |
| Companies Covered | Universal Display Corporation, Merck KGaA, Idemitsu Kosan, LG Chem, DuPont, Sumitomo Chemical, Samsung Display, LG Display, Novaled GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OLED Blue Emitter Market Trends and Innovations
Emitter technology trajectories are diverging between efficiency-maximizing phosphorescent platforms and sustainability-aligned heavy-metal-free alternatives, with regulatory compliance emerging as the primary selection criterion alongside performance metrics.
TADF molecular architectures are overtaking early-generation fluorescent systems in mid-tier smartphone panel supply. Chinese display manufacturers are adopting these platforms at accelerated qualification paces to preempt EU material restriction enforcement. The structural consequence is compressing royalty-dependent phosphorescent licensing models while expanding captive TADF formulation capabilities among integrated panel makers.
REACH authorization requirements for organometallic precursors are tightening submission standards for new emitter chemistries entering European manufacturing zones. Industrial consequence includes mandatory substitution planning for legacy iridium complexes in high-volume applications. Korean panel suppliers operating EU-bound export lines are responding with dual-track qualification of compliant TADF alternatives alongside phosphorescent efficiency improvements.
Display manufacturers are consolidating emitter procurement around vertically integrated material subsidiaries with captive intellectual property positions. Long-term supply agreements with fixed volume commitments are displacing spot-market purchasing for blue host and dopant materials. This concentration is most visible in South Korea, where Samsung Display and LG Display have internalized formulation development through dedicated material science divisions.
OLED Blue Emitter Market Segmentation
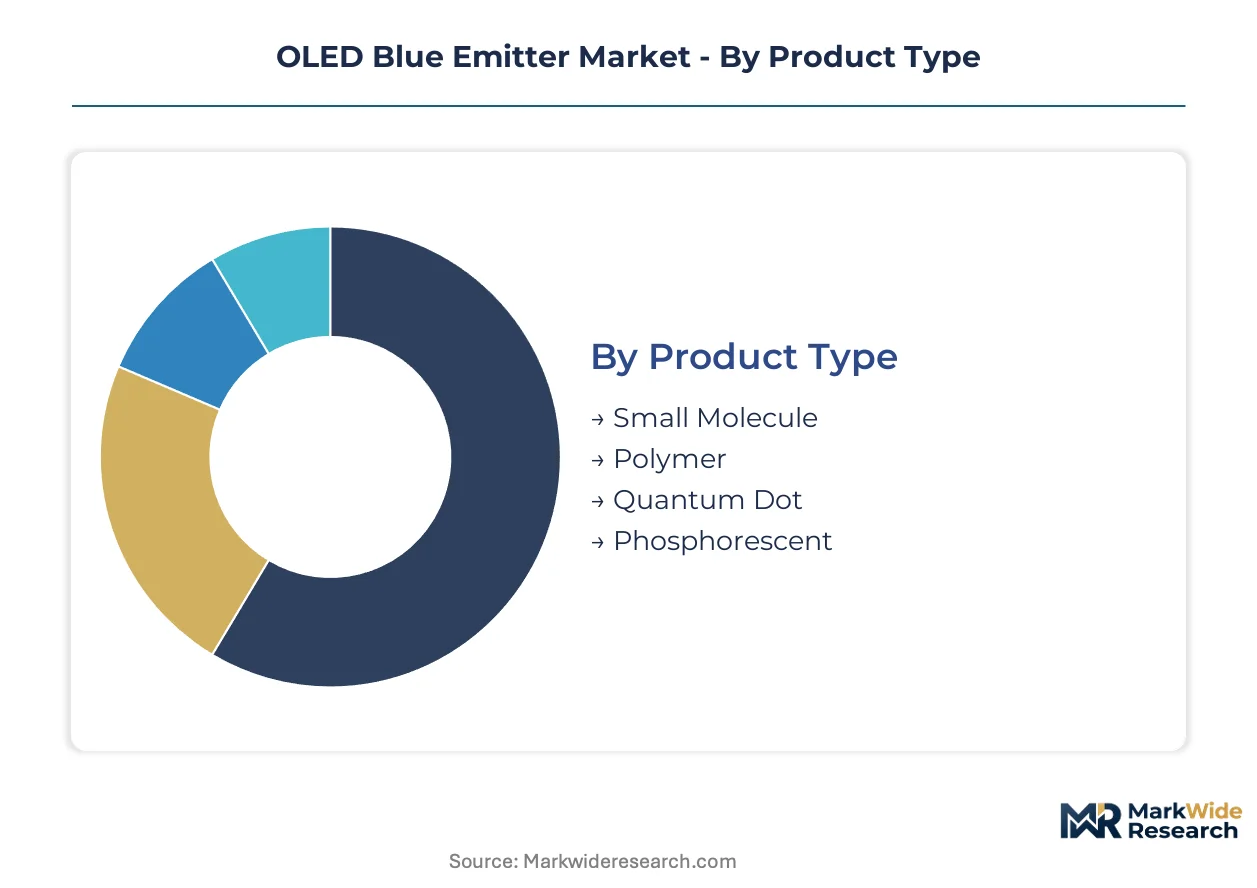
OLED blue emitter procurement patterns diverge sharply across material chemistries and deposition requirements. Panel manufacturers align sourcing strategies with specific display formats, creating distinct supply channels for each segment combination.
Product Type:
Supply concentration clusters around vapor-deposition-compatible small-molecule platforms, with polymer and quantum-dot alternatives occupying specialized fabrication niches.
- Small Molecule:Vacuum-thermal-evaporation systems deposit these iridium and platinum complexes in precisely controlled emissive layers. Samsung Display and LG Display anchor procurement volume through captive material science divisions in South Korea, driven by smartphone panel efficiency requirements.
- Phosphorescent:These heavy-metal-based emitters achieve external quantum efficiency exceeding 25% through triplet harvesting architectures. Universal Display Corporation's licensing portfolio governs commercial deployment, with royalty structures concentrating adoption among capital-rich integrated panel makers.
- Polymer:Solution-processed deposition suits inkjet printing for sub-6-inch wearable panels.
- Quantum Dot:Cadmium-free formulations address EU Green Deal heavy-metal restrictions for premium television supply.
Today's leader: Phosphorescent. Tomorrow's challenger: Quantum Dot.
Application:
Volume distribution follows display size economics, with smaller formats commanding premium emitter specifications per square centimeter.
- Smartphones:High pixel density demands sub-micrometer emissive layer precision. Korean and Chinese panel suppliers consume the majority of phosphorescent blue host material shipments, constrained by iridium complex refining capacity concentration in East Asian chemical processing zones.
- Televisions:Large-area deposition requires uniform emitter distribution across 65-inch and larger substrates. Quantum-dot alternatives are gaining share fastest here as manufacturers seek exemption from EU material restriction enforcement.
- Tablets:Mid-size formats balance efficiency targets with cost constraints.
- Wearables:Polymer systems reduce capital intensity for curved and flexible panel geometries.
Smartphones generate the highest unit economics. Televisions drive the steepest volume expansion trajectory.
End User:
Customer procurement sophistication varies across electronics, automotive, and commercial segments, with qualification timelines stretching longest for safety-critical applications.
- Consumer Electronics:Annual product cycles compress emitter qualification windows to 12-18 months. Samsung Electronics and Apple anchor demand through direct supply agreements with material formulators.
- Automotive:Tier-1 panel suppliers enforce reliability standards exceeding consumer electronics benchmarks by an order of magnitude. Curved instrument clusters and pillar-to-pillar screens require thermal cycling stability above 10,000 hours.
- Commercial Displays:24/7 operation requirements favor conservative emitter selection.
- Signage:Outdoor brightness specifications drive high-efficiency phosphorescent adoption.
Consumer Electronics sets the pace on volume. Automotive sets the bar on specification rigor.
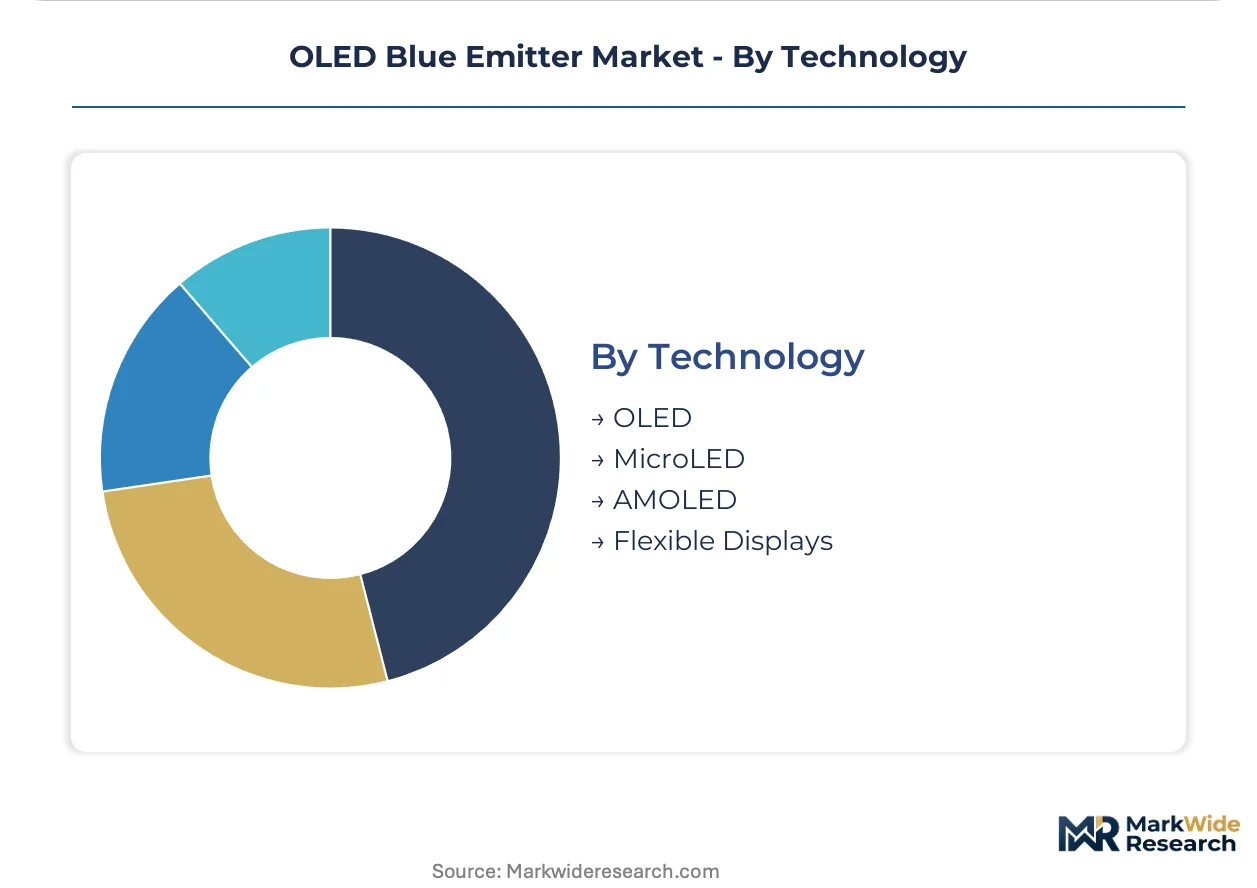
Technology:
Fabrication architecture determines emitter deposition method and layer stack complexity, with flexible substrates imposing additional barrier requirements.
- AMOLED:Active-matrix backplanes enable precise pixel-level brightness control in premium smartphone panels. Korean fabrication complexes concentrate global production capacity, sourcing blue host materials through long-term supply agreements with fixed volume commitments.
- Flexible Displays:Polyimide substrate compatibility requires modified thermal processing windows. Wearable device manufacturers adopt these formats to differentiate form factors, with solution-processed polymer emitters reducing equipment capital requirements.
- OLED:Rigid glass substrates maintain cost efficiency for television production.
- MicroLED:Emitter-free architecture eliminates organic material procurement entirely.
AMOLED commands current investment. Flexible Displays capture emerging format premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized organometallic synthetic chemists cluster in Japanese and Korean research institutes, anchoring formulation capabilities near major panel fabrication sites. This talent concentration shapes regional supply patterns and qualification timelines.
South Korea
Samsung Display and LG Display operate integrated OLED fabrication complexes in the Seoul Capital Area and Busan-Ulsan corridor, consuming the majority of phosphorescent blue host material shipments. The Ministry of Trade, Industry and Energy enforces domestic content requirements under its national strategic material program. Korean panel suppliers maintain captive material science divisions that internalize emitter formulation development.
Japan
Idemitsu Kosan dominates blue host material shipments to Korean panel makers through its Tokyo-based chemical operations. METI oversees export licensing for advanced display materials under strategic technology controls. Chubu region chemical processors maintain iridium complex refining capacity that feeds East Asian phosphorescent emitter supply chains.
Germany
Merck KGaA anchors European material supply through its Frankfurt-area production campus, serving EU-bound display manufacturers. ECHA REACH authorization requirements tighten submission standards for organometallic precursors entering European manufacturing zones. Bavarian chemical clusters specialize in mercury-free emitter alternatives aligned with EU Green Deal phased restrictions.
United States
Universal Display Corporation leverages its phosphorescent blue IP portfolio to sustain royalty streams from licensed manufacturers worldwide. The EPA's Toxic Substances Control Act governs importation of novel emitter chemistries into U.S. fabrication facilities. Princeton-New Jersey research corridors host specialized synthetic chemistry teams supporting phosphorescent complex design.
China
Chinese display manufacturers accelerate TADF platform qualification to preempt EU material restriction enforcement on export-bound panels. MIIT coordinates domestic OLED supply chain development under national industrial policy directives. Yangtze River Delta chemical processors are expanding organometallic precursor capacity to reduce import dependency.
OLED Blue Emitter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the OLED blue emitter value chain. The market structure consolidates around vertically integrated material subsidiaries with captive intellectual property positions. Three archetypes dominate: phosphorescent IP licensors, TADF formulation specialists, and integrated panel-maker material divisions. Capacity expansion and strategic patent licensing constitute the primary competitive moves, with long-term supply agreements displacing spot-market purchasing.
Within the phosphorescent IP tier, Universal Display Corporation occupies a position exemplifying royalty-dependent licensing models. Among European chemical conglomerates, Merck KGaA represents the integrated material supply archetype through its Frankfurt-area production campus. Japanese specialists including Idemitsu Kosan anchor the blue host material segment serving Korean panel fabrication demand.
| Leading Market Players |
|---|
| Universal Display Corporation |
| Merck KGaA |
| Idemitsu Kosan |
| LG Chem |
| DuPont |
| Sumitomo Chemical |
| Samsung Display |
| LG Display |
| Novaled GmbH |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal mercury-free mandates are forcing rapid reformulation of blue emitter portfolios, compelling suppliers to absorb R&D transition costs while panel makers lock in long-term offtake agreements to secure compliant material flows.
Pricing Analysis
Unbundled phosphorescent licensing from Universal Display Corporation operates alongside bundled TADF formulation packages from integrated Korean material divisions. Price differentiation rests on heavy-metal content certification tiers and volume scale commitments. Pricing pressure intensifies in mid-tier smartphone panels as Chinese manufacturers accelerate TADF adoption to bypass royalty structures. Consumer electronics OEMs exhibit highest price sensitivity, while automotive Tier-1 suppliers accept premium positioning for reliability guarantees.
Supply Chain Analysis
Reverse-logistics flows for spent iridium complex precursors remain underdeveloped, constraining circular economy claims despite EU sustainability disclosure requirements. Raw material refining concentrates in South Korea, Japan, and Germany, with organometallic precursor synthesis drawing from East Asian chemical processing zones. Iridium ore supply hinges on South African and Russian mining concentration. Single-source vulnerability pervades phosphorescent emitter production. Distribution runs through captive material science divisions at Samsung Display and LG Display.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as display panel efficiency requirements tighten across consumer electronics refresh cycles, embedding emitter material demand in structural technology transitions.
For Market Incumbents: Anchor royalty-dependent licensing models through accelerated deep-blue phosphorescent efficiency improvements before TADF stability thresholds mature. Defend against Chinese integrated panel makers by securing REACH pre-registration for novel organometallic precursors. Prioritize backward integration into iridium complex refining to offset East Asian supply concentration. For New Entrants and Emerging Players: The premium-economy price-point gap in automotive display qualification presents immediate white-space opportunity. Target curved instrument cluster and pillar-to-pillar screen applications where reliability requirements exceed incumbent specification libraries. Pursue inkjet-deposited polymer emitter platforms for wearable sub-6-inch panels to reduce capital barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with TADF formulation specialists holding captive IP positions outside phosphorescent patent thickets. Long-term viability favors material science divisions with demonstrated dual-track qualification capabilities across heavy-metal and heavy-metal-free platforms. Monitor EU REACH authorization timelines for iridium complex substitution mandates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Korean panel makers secure iridium complex supply independence from Japanese chemical processors. |
| TADF Platform Commercialization | Chinese manufacturers bypass Universal Display royalty structures for EU-bound export panels. |
| Automotive Reliability Qualification | Tier-1 suppliers enforce thermal cycling standards exceeding consumer electronics benchmarks. |
| REACH Pre-Registration Acceleration | Merck KGaA secures first-mover advantage for mercury-free emitter authorization pathways. |
| Solution-Processed Polymer Scale-Up | Wearable device OEMs reduce vacuum evaporation capital intensity through inkjet deposition. |
Research Methodology
Direct dialogue with OLED material formulators, panel maker procurement directors, and deposition equipment engineers grounded qualitative findings in operational reality. Secondary validation drew from ECHA REACH substance databases, Korean Ministry of Trade strategic material program filings, and SEC disclosures from phosphorescent IP licensors. Bottom-up emitter shipment estimates triangulated against top-down panel production forecasts across the analysis window.
Segmented outputs trace phosphorescent versus TADF chemistry splits, application tiers from smartphones to automotive displays, and regional regulatory compliance clusters. CAGRs derive from installed base replacement modeling and technology transition elasticity parameters. Forecast inputs incorporate EU Green Deal enforcement phasing and iridium complex refining capacity expansion announcements.
Caveats apply where REACH authorization delays or TADF stability breakthroughs could materially shift the outlook. Practitioners should monitor ECHA substance evaluation timelines and Korean domestic content requirement adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
North America Micro-LED Display Market
LED
Mini LED Market
LED
US LED Downlight Market
LED
China Outdoor LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
Indonesia LED Market
LED
LED Panel Light Drivers Market
LED
Saudi Arabia LED Lights Market
LED
Germany LED Lighting Market
LED
Infrared (IR) LED Market
LED
Biometrics Infrared LED Market
LED
UV-C LED Market
LED
Led Video Walls Market
LED
Architectural LED Products Market
LED
Germany Outdoor LED Lighting Market
LED
Asia Pacific Indoor LED Lighting Market